
 Asia-Pacific Baby Care Products Market | 2026-2036
Asia-Pacific Baby Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
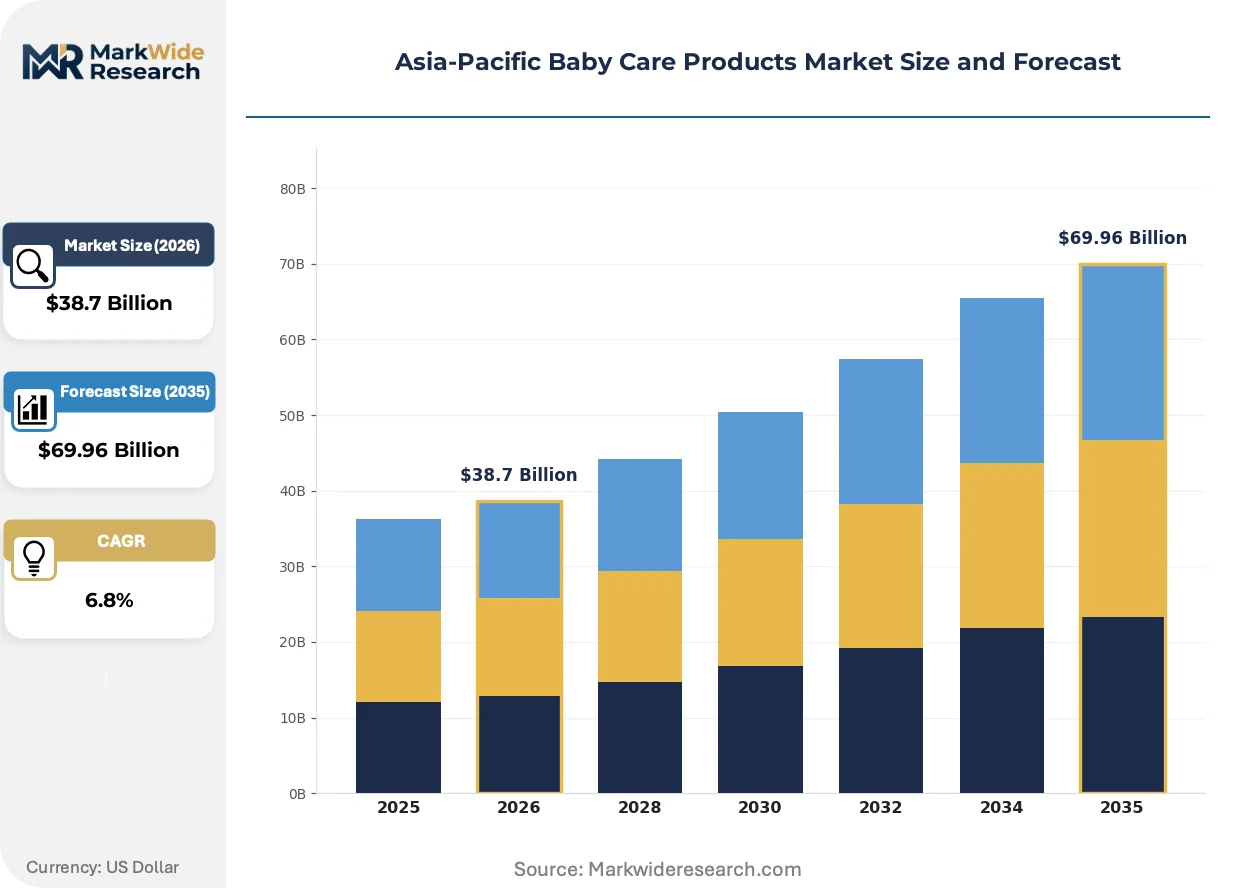
Asia-Pacific Baby Care Products Market Analytics
GB 31701-2015, China's national textile safety standard for infant products, is unwinding the competitive landscape by forcing smaller domestic manufacturers toward costly lab upgrades. Procter & Gamble leverages its established compliance infrastructure to maintain shelf presence in Chinese hypermarkets. Unicharm anchors its position through captive absorbent-material R&D in Japan. Kimberly-Clark competes aggressively on diaper SKU breadth across Southeast Asian pharmacy chains.
Asia-Pacific baby care products span formulated skincare, absorbent hygiene articles, and nutritional supplements engineered for epidermal pH below 5.5 and tear-free surfactant thresholds. Diapers command the largest revenue pool due to daily-consumption frequency and premium-tier elastic-film innovations, though baby wipes represent the fastest-expanding category as travel-size formats penetrate India's online channel. Distribution through specialty stores captures the highest margin per unit because trained staff convert first-time parents to bundled regimens, while supermarket volume anchors economies of scale for economy-tier producers.
Japan's PMDA, China's SAMR, and India's CDSCO collectively tighten ingredient traceability and advertising claims for infant-directed formulations, raising compliance costs but also clearing shelf space for verified brands. The EU Green Deal's indirect influence through Asian export-oriented suppliers accelerates biodegradable wipe substrate adoption. Stakeholders must monitor regulatory divergence between Japan's preservative ban lists and China's evolving GB cosmetic standards when configuring regional product portfolios.
Market Dynamics
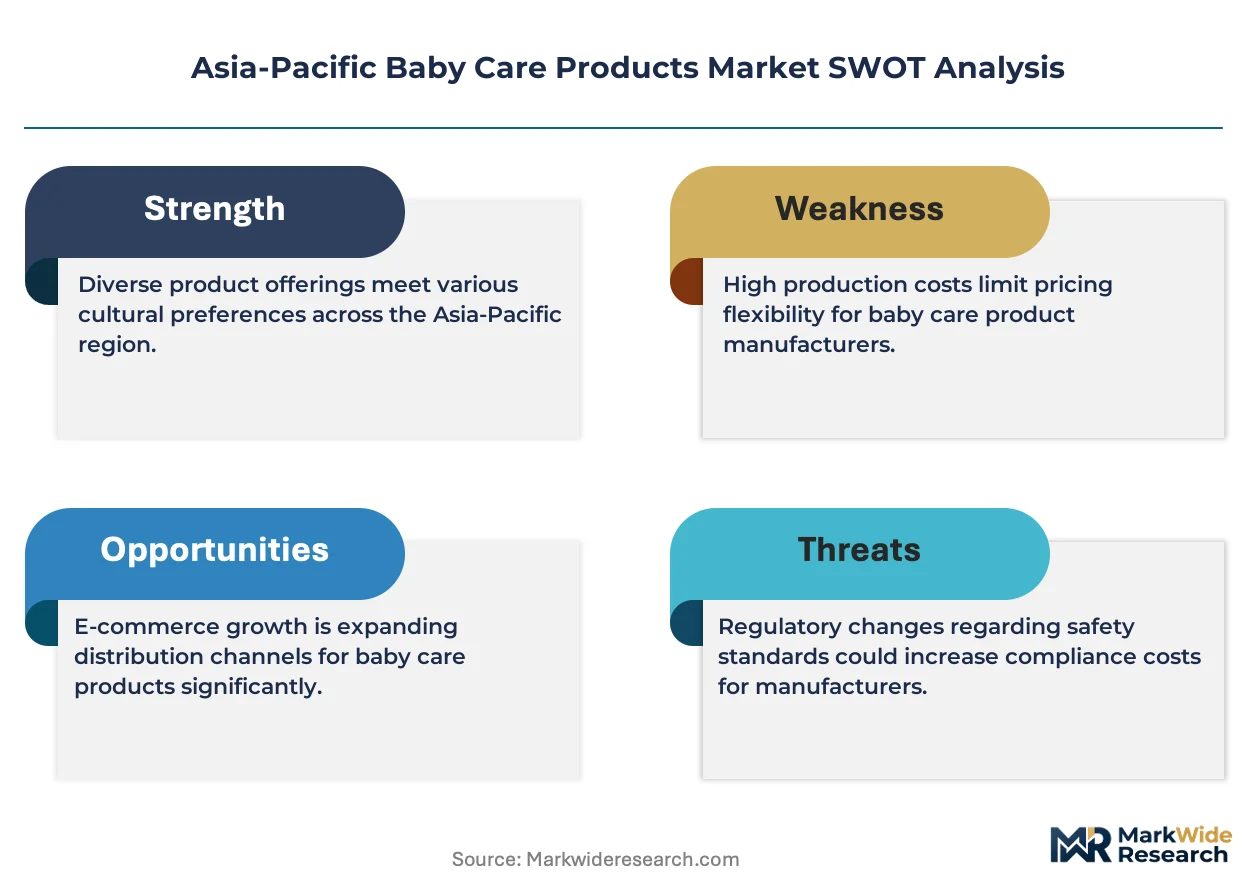
Urban millennial parents across China's tier-one cities and India's National Capital Region are compressing purchase cycles for organic-certified infant skincare, forcing manufacturers to accelerate formulation pipelines while absorbing escalating compliance costs from divergent national safety standards.
Growth Catalysts
- Japan's PMDA disclosure mandates:Tightened ingredient traceability rules for infant cosmetics are clearing shelf space for verified brands with established lab infrastructure.
- Biodegradable substrate innovation:EU Green Deal pressure on Asian export suppliers is accelerating plant-based wipe material adoption across premium product lines.
- Online channel penetration:Travel-size baby wipe formats are capturing first-time buyers through India's e-commerce platforms, expanding addressable households beyond traditional retail catchments.
Market Restraints
- GB 31701-2015 compliance costs:China's national textile safety standard for infant products is forcing smaller domestic manufacturers toward capital-intensive lab upgrades or market exit.
- Absorbent material supply concentration:Captive R&D and polymer production capabilities in Japan create import dependency for Southeast Asian diaper assemblers.
- Preservative formulation bans:Divergent prohibited substance lists between Japan's PMDA and China's evolving GB cosmetic standards fragment regional product portfolios and raise inventory complexity.
Strategic Opportunities
- Tier-two China expansion:Organic-certified skincare lines remain underpenetrated in Chengdu, Hangzhou, and Wuhan relative to saturation in Beijing and Shanghai.
- Specialty store channel development:Trained staff conversion of first-time parents to bundled regimens captures margin premiums unavailable through supermarket volume channels.
- SAMR advertising claim clarity:China's evolving regulatory framework for infant-directed formulations creates first-mover advantage for brands with pre-validated clinical documentation.
Industry Challenges
- Formulation chemist scarcity:Epidermal pH below 5.5 and tear-free surfactant thresholds require specialized expertise concentrated in Japan and South Korea.
- Dual certification timelines:Parallel CDSCO and SAMR approval tracks for nutritional supplements extend product launch windows by 8-14 months.
- Legacy absorbent hygiene retooling:Elastic-film innovation cycles demand capital redeployment away from commodity diaper lines toward premium SKU development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Baby Care Products Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Wipes, Baby Oil, Lotions Customer Type: Parents, Guardians, Pediatricians, Retailers Distribution Channel: Online, Supermarkets, Specialty Stores, Pharmacies Price Tier: Premium, Economy, Mid-Range, Bulk |
| Companies Covered | Procter & Gamble, Kimberly-Clark, Unicharm, Johnson & Johnson, Nestle, Unilever, Abbott Laboratories, Pigeon Corporation, The Himalaya Drug Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Baby Care Products Market Evolving Landscape
Formulation science and channel architecture are diverging simultaneously across the Asia-Pacific baby care landscape, with premium organic lines and economy-tier volume plays accumulating distinct competitive moats.
Plant-derived emollient systems are bifurcating the infant skincare segment. Metro Chinese parents are adopting ceramide-alternative formulations at triple the pace of conventional mineral-oil bases. This technology compression is enabling niche organic brands to capture shelf space previously held by mass-market incumbents with legacy petroleum-derived portfolios.
SAMR's evolving GB cosmetic standards for infant-directed products are tightening advertising claim substantiation. Manufacturers must now submit clinical documentation prior to market authorization. Premium skincare and nutritional supplement categories face the steepest compliance ramps, with several multinational portfolios undergoing accelerated reformulation to maintain Chinese market access.
First-time parent buying patterns are rotating toward subscription-bundle procurement through specialty retail channels. Trained staff at curated baby boutiques in Tokyo, Seoul, and Mumbai are displacing supermarket impulse purchases with regimen-based selling. This channel shift is most visible in India's National Capital Region, where online-offline integration allows hyperlocal delivery of personalized product cycles.
Asia-Pacific Baby Care Products Market Segmentation
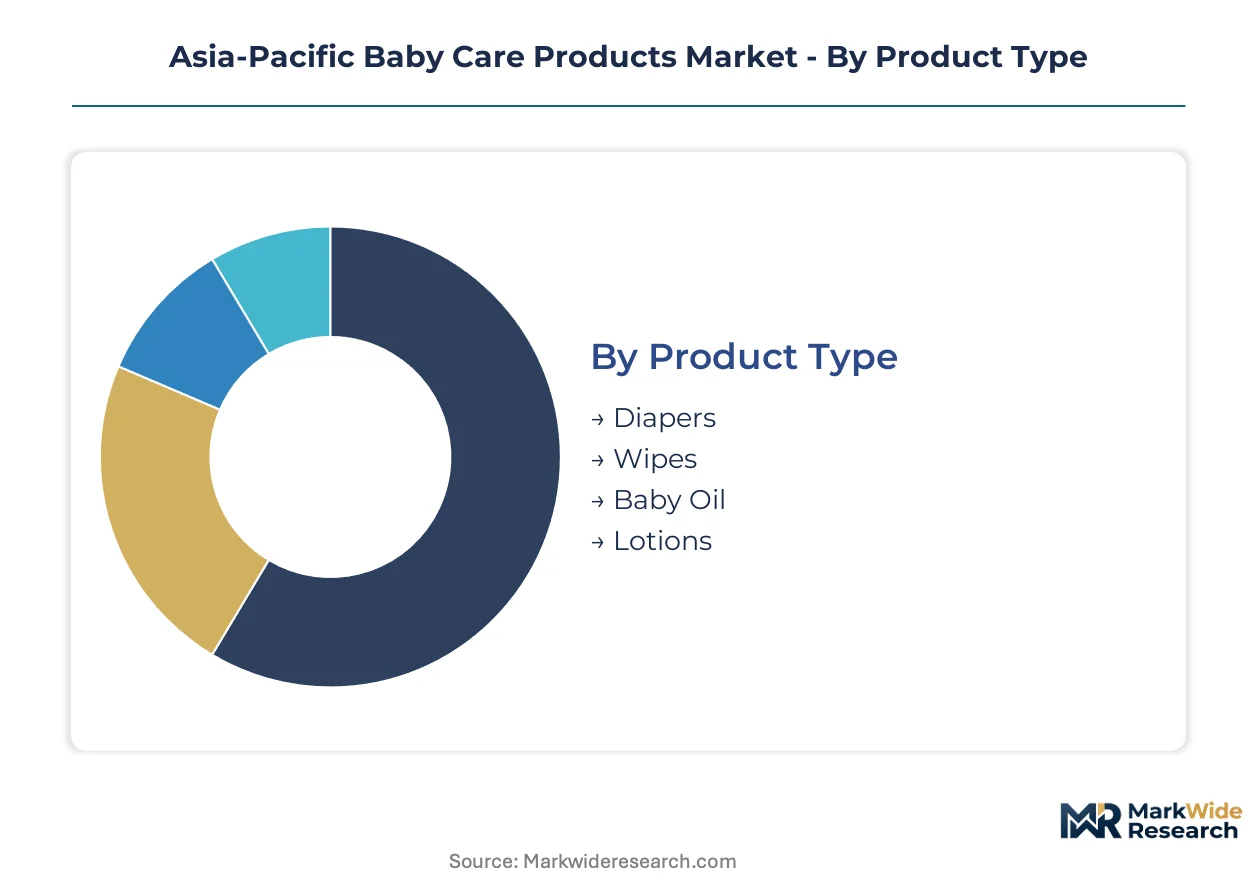
Segmentation in Asia-Pacific baby care products reveals distinct substitution dynamics. Premium organic skincare lines displace conventional petroleum-based formulations, while specialty retail channels capture margin premiums unavailable through supermarket volume plays.
Product Type:
Diapers face the strongest substitution pressure from reusable cloth alternatives and subscription-based delivery models, forcing manufacturers to differentiate through elastic-film innovation and skin-sensitive coatings.
- Diapers:Absorbent hygiene articles engineered with SAP cores and breathable elastic films command the largest revenue pool due to daily-consumption frequency. Demand concentrates in China's tier-one cities and India's National Capital Region, where urban millennial parents prioritize premium-tier leakage protection and dermatological certification.
- Wipes:Non-woven substrate sheets formulated with pH-balanced cleansers and plant-derived emollients represent the fastest-expanding category. Travel-size formats penetrate India's online channel, expanding addressable households beyond traditional retail catchments in Mumbai and Delhi.
- Baby Oil:Mineral-oil and plant-derived emollient systems for infant massage and moisture barrier protection.
- Lotions:Ceramide-alternative and petroleum-free moisturizing formulations targeting epidermal pH below 5.5.
Diapers anchor the volume base while wipes gain share at the steepest rate.
Customer Type:
Purchase authority concentrates with first-time parents in metropolitan clusters, though pediatrician endorsement carries disproportionate weight in Japan's clinical-channel skincare sales.
- Parents:Urban millennial decision-makers in Beijing, Shanghai, and Tokyo compress purchase cycles for organic-certified infant skincare, accelerating manufacturer formulation pipelines.
- Guardians:Grandparents and extended-family caregivers in multi-generational Indian households.
- Pediatricians:Medical professionals influencing brand selection through clinical recommendation in Japan's pharmacy-linked distribution.
- Retailers:Specialty store buyers and supermarket category managers negotiating SKU breadth and promotional support.
Parents drive absolute volume while pediatrician-channel conversion delivers the highest per-unit margin.
Distribution Channel:
Channel cost structures diverge sharply, with specialty stores absorbing trained-staff overhead to capture bundled-regimen premiums against supermarket economies of scale.
- Online:E-commerce platforms and direct-to-consumer portals enable hyperlocal delivery of personalized product cycles, particularly in India's National Capital Region where online-offline integration accelerates.
- Supermarkets:Mass-market volume anchors for economy-tier diaper and wipe producers competing on shelf presence and promotional pricing.
- Specialty Stores:Curated baby boutiques with trained staff converting first-time parents to bundled regimens.
- Pharmacies:Clinical-channel distribution for dermatologically tested skincare and nutritional supplements.
Supermarkets anchor the volume base while specialty stores expand most quickly in revenue-per-unit terms.
Price Tier:
Pricing stratification separates certified-organic premium lines from commodity diaper production, with mid-range SKUs facing compression from both directions.
- Premium:Organic-certified skincare and elastic-film diaper innovations targeting epidermal pH thresholds and tear-free surfactant compliance.
- Economy:Volume-focused diaper and wipe production for price-sensitive households in Southeast Asian markets.
- Mid-Range:Standard-formulation products without organic certification or advanced material specifications.
- Bulk:Subscription and wholesale procurement formats reducing per-unit cost for high-frequency consumption items.
Economy tiers anchor the volume base while premium lines climb the fastest in revenue contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR advertising claim mandates and Japan's PMDA disclosure rules are compressing product launch timelines across the region. India's CDSCO nutritional supplement approvals and Australia's TGA cosmetic standards add parallel compliance tracks. Southeast Asian diaper assemblers face raw material import dependencies from Japanese polymer producers.
China
Urban millennial parents in Beijing and Shanghai compress purchase cycles for organic-certified infant skincare. SAMR's evolving GB cosmetic standards now require clinical documentation prior to market authorization for infant-directed formulations. Chengdu and Hangzhou represent underpenetrated expansion corridors where premium organic lines remain available relative to tier-one saturation.
Japan
Pediatrician-endorsed clinical-channel sales concentrate purchasing authority among medical professionals in Tokyo and Osaka. PMDA tightened ingredient traceability rules for infant cosmetics, clearing shelf space for verified brands with established lab infrastructure. Kanto region specialty boutiques displace supermarket impulse purchases through regimen-based selling to first-time parents.
India
Grandparents and extended-family caregivers in multi-generational Delhi-NCR households influence brand selection alongside millennial parents. CDSCO parallel approval tracks for nutritional supplements extend product launch windows by 8-14 months relative to single-market filings. Mumbai's online-offline integration enables hyperlocal delivery of personalized product cycles through specialty retail channels.
Australia
TGA cosmetic standards and EU Green Deal pressure through export-oriented suppliers accelerate biodegradable wipe substrate adoption. Sydney and Melbourne specialty stores capture margin premiums through trained staff conversion of first-time parents to bundled regimens. The country's stringent preservative formulation requirements fragment regional product portfolios for multinational brands.
South Korea
Formulation chemist scarcity for epidermal pH below 5.5 and tear-free surfactant thresholds concentrates specialized expertise in Seoul and Busan. MFDS regulatory alignment with evolving international standards creates compliance complexity for imported infant skincare lines. Domestic manufacturers leverage captive R&D capabilities to supply Southeast Asian diaper assemblers with advanced elastic-film innovations.
Asia-Pacific Baby Care Products Market Competitive Landscape
Listed leaders compete with private specialists across compliance infrastructure and channel architecture. The market structures around three tiers: multinational conglomerates with established regulatory affairs departments, regional specialists with captive material R&D, and emerging organic-certified challengers. Strategic archetypes include compliance-heavy incumbents defending shelf presence, innovation-focused regional anchors, and niche organic formulators capturing premium positioning. Dominant competitive moves center on M&A for regional distribution access and portfolio diversification into adjacent nutritional supplement categories.
Among Japan-based specialists, Pigeon Corporation exemplifies the clinical-channel anchor archetype with pharmacy-linked distribution expertise. Within the multinational tier, Procter & Gamble and Kimberly-Clark occupy positions representing divergent strategic emphases—established compliance infrastructure versus aggressive SKU breadth expansion. Unicharm sits within the captive R&D archetype, demonstrating how absorbent-material innovation capabilities create supply-side differentiation. These three names illustrate how geographic origin and corporate structure correlate with competitive positioning across the region's divergent regulatory environments.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark |
| Unicharm |
| Johnson & Johnson |
| Nestle |
| Unilever |
| Abbott Laboratories |
| Pigeon Corporation |
| The Himalaya Drug Company |
| Others |
Value Network & Pricing Analysis
GB 31701-2015 compliance gates both supplier qualification and price differentiation simultaneously, forcing smaller Chinese textile manufacturers toward capital-intensive lab upgrades while certified incumbents capture premium shelf positioning in hypermarkets. Certification investment separates organic-certified skincare lines from commodity diaper production, with SAMR and PMDA disclosure mandates adding parallel compliance cost layers that concentrate pricing power among established brands.
Pricing Analysis
Certification level creates the primary spread across the Asia-Pacific baby care landscape, with organic-certified formulations commanding substantial premiums over petroleum-derived alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects divergent compliance investment and raw material sourcing. Cost compression in economy-tier diapers intensifies as Chinese domestic manufacturers absorb GB standard upgrade expenses. First-time parents in tier-one cities exhibit lowest price sensitivity, while Southeast Asian pharmacy chains drive aggressive promotional pricing for volume SKUs.
Supply Chain Analysis
Polymer supply from Japanese captive R&D facilities underwrites absorbent hygiene production across Southeast Asian diaper assemblers. Raw material dependencies center on superabsorbent polymers from Japan, non-woven substrates from South Korea, and plant-derived emollients from Australian suppliers. Single-source vulnerability concentrates in Japan's elastic-film innovation pipeline, where Unicharm's integrated production creates import dependency for regional competitors. Distribution runs through specialty store channels for premium skincare margins and supermarket volume plays for economy-tier scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story, where PMDA and SAMR compliance infrastructure creates switching costs that defend incumbent positions against organic challengers. Network effects concentrate in specialty store channel relationships and pediatrician endorsement pathways.
For Market Incumbents: Secure CDSCO and SAMR pre-validation for nutritional supplement claims to compress launch timelines against emerging organic competitors. Deepen captive R&D in biodegradable wipe substrates ahead of EU Green Deal acceleration through Asian export suppliers. Channel control through trained specialty store staff conversion rates defends margin premiums unavailable to supermarket-dependent entrants.
For New Entrants and Emerging Players: Anchor in Chengdu and Hangzhou organic skincare white space, where premium certified lines remain underpenetrated relative to Beijing and Shanghai saturation. Target India's National Capital Region online-offline integration for hyperlocal delivery of subscription-bundle formats. Pediatrician endorsement pathways in Japan's clinical channel offer highest per-unit margin entry with differentiated positioning.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerates seeking to divest non-core baby care portfolios amid regional regulatory fragmentation. Long-term viability favors brands with established compliance infrastructure across PMDA, SAMR, and CDSCO tracks. Monitor biodegradable substrate adoption rates as inflection indicator for premium line margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Validation Investment | CDSCO and SAMR clinical documentation submission accelerates market authorization timelines for infant-directed formulations. |
| Biodegradable Substrate Transition | Plant-based wipe material adoption responds to EU Green Deal pressure on Asian export-oriented suppliers. |
| Specialty Store Channel Expansion | Trained staff conversion of first-time parents to bundled regimens captures margin premiums in Tokyo and Mumbai. |
| Captive Absorbent Material R&D | In-house polymer production capabilities reduce import dependency for Southeast Asian diaper assemblers. |
| Tier-Two China Geographic Push | Chengdu and Wuhan penetration extends organic-certified skincare lines beyond saturated Beijing and Shanghai markets. |
Research Methodology
A spread of perspectives from brand managers at multinational incumbents, category buyers at Chinese hypermarkets, formulation chemists in Seoul and Busan, and CDSCO regulatory consultants converged on the working assumptions. Secondary validation drew from SAMR GB standard filings, PMDA ingredient disclosure databases, India customs import records for absorbent polymers, and Nielsen retail audit data across Asia-Pacific pharmacy chains. Bottom-up SKU-level volume estimates triangulated against top-down category spending projections.
Segmentation dimensions modeled include product type, customer purchase authority, distribution channel architecture, and price tier stratification across the projection horizon. CAGRs were derived from category growth rate reconciliation with macroeconomic consumption indicators and regulatory timeline impacts. Forecast inputs incorporated diaper daily-consumption frequency elasticity, organic certification adoption curves in tier-one versus tier-two Chinese cities, and specialty store channel share expansion in India's National Capital Region.
Material uncertainties — divergent preservative ban lists between Japan's PMDA and China's evolving GB cosmetic standards, CDSCO approval timeline variability, and biodegradable substrate cost parity achievement — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and parent demographic shift rates. Practitioners should keep alternative scenarios live as SAMR advertising claim substantiation requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Global Baby Play Mats Market
Baby Products
Smart Pacifier Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Breast Milk Storage Products Market
Baby Products
Baby Personal Care Products Market
Baby Products
India Baby Care Products Market
Baby Products
North America Baby Bottle Market
Baby Products
Baby Feeding Bottles Market
Baby Products
Baby Pacifier Market
Baby Products
Electric Baby Nail Trimmer Market
Baby Products
Baby Bouncers Market
Baby Products
Global Pregnancy Pillow Market
Baby Products
Pregnancy Products Market
Baby Products
France Baby Care Products Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Luxury Baby Stroller Market