
 Baby Bottle Warmers Market | 2026-2036
Baby Bottle Warmers Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Bottle Warmers Market Outlook
China is rewriting competitive dynamics in baby bottle warmers through expanded manufacturing capacity and streamlined export logistics. Philips Avent leverages its European design heritage to sustain premium positioning across Asian retail channels. Grownsy anchors its growth on direct-to-consumer digital distribution, while Baby Brezza specializes in multi-function units that integrate sterilization and warming capabilities.
A baby bottle warmer is an electrically or thermally powered appliance designed to heat infant formula or breast milk to body temperature, typically operating within 37°C to 40°C through water-bath, steam, or convection mechanisms. Its primary commercial purpose is to eliminate nutrient degradation caused by microwave uneven heating while ensuring safe, consistent temperature delivery for infant feeding. Electric warmers with digital control interfaces command the dominant margin pool due to precision sensors and programmable settings, whereas smart control segments incorporating Bluetooth connectivity and app-based monitoring represent the fastest-growing configuration. Travel warmers occupy a niche but defensible position among working parents requiring battery-operated portability.
The US Consumer Product Safety Commission and FDA jointly govern electrical safety and material biocompatibility for infant feeding devices, while the EU's CE marking and RoHS substance restrictions constrain component sourcing for exporters. China's GB standards and SAMR market surveillance add compliance layers for brands manufacturing domestically. Stakeholders must monitor evolving smart-home interoperability standards and chemical disclosure requirements as regulatory scope broadens beyond basic electrical safety.
Market Dynamics
The EU's Ecodesign Directive and REACH chemical safety standards are compressing material choices for infant feeding appliances, forcing manufacturers to redesign thermal interfaces and polymer housings while maintaining heating efficiency.
Growth Catalysts
- REACH substance restrictions:Manufacturers accelerating migration to medical-grade silicone and borosilicate glass is expanding the addressable premium segment as safety-conscious parents trade up from legacy plastic units.
- Urban household density:Parents in high-rise residential clusters across Shanghai, Shenzhen, and Beijing are driving portable warming demand as kitchen space constraints eliminate countertop appliance tolerance.
- Bluetooth-enabled precision sensors:Smart control modules with app-based temperature logging are capturing margin pools from conventional dial-interface units in direct-to-consumer channels.
Market Restraints
- Copper and rare-earth magnet costs:Heating element substrates and DC motor materials face input volatility that compresses gross margins on mid-tier electric warmers.
- Guangdong and Zhejiang manufacturing clusters:Overwhelming supply concentration in coastal Chinese provinces creates single-point vulnerability for brands without secondary sourcing in Vietnam or Malaysia.
- Steam-based thermal transfer:Water-bath mechanisms retain longer warming cycles than convection alternatives, limiting appeal among time-constrained working parents.
Strategic Opportunities
- Tier-2 and Tier-3 Chinese cities:E-commerce penetration into Hefei, Changsha, and Xi'an remains underdeveloped relative to saturation in Beijing and Shanghai, offering first-mover expansion corridors.
- Vehicle-integrated warming:12V automotive adapters and USB-C power banks are opening travel-warmer applications for ride-share dependent urban families without private vehicle access.
- EU Green Deal circularity mandates:Upcoming right-to-repair and recyclability requirements favor modular designs with replaceable heating elements over sealed disposable units.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA 510(k) material biocompatibility reviews, CE marking electrical safety audits, and SAMR GB standard compliance in China extend product launch windows by 8-14 months.
- Smart-home interoperability fragmentation:Proprietary app ecosystems from Amazon Alexa, Google Home, and Xiaomi MIJIA force redundant firmware development for cross-platform compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Bottle Warmers Market |
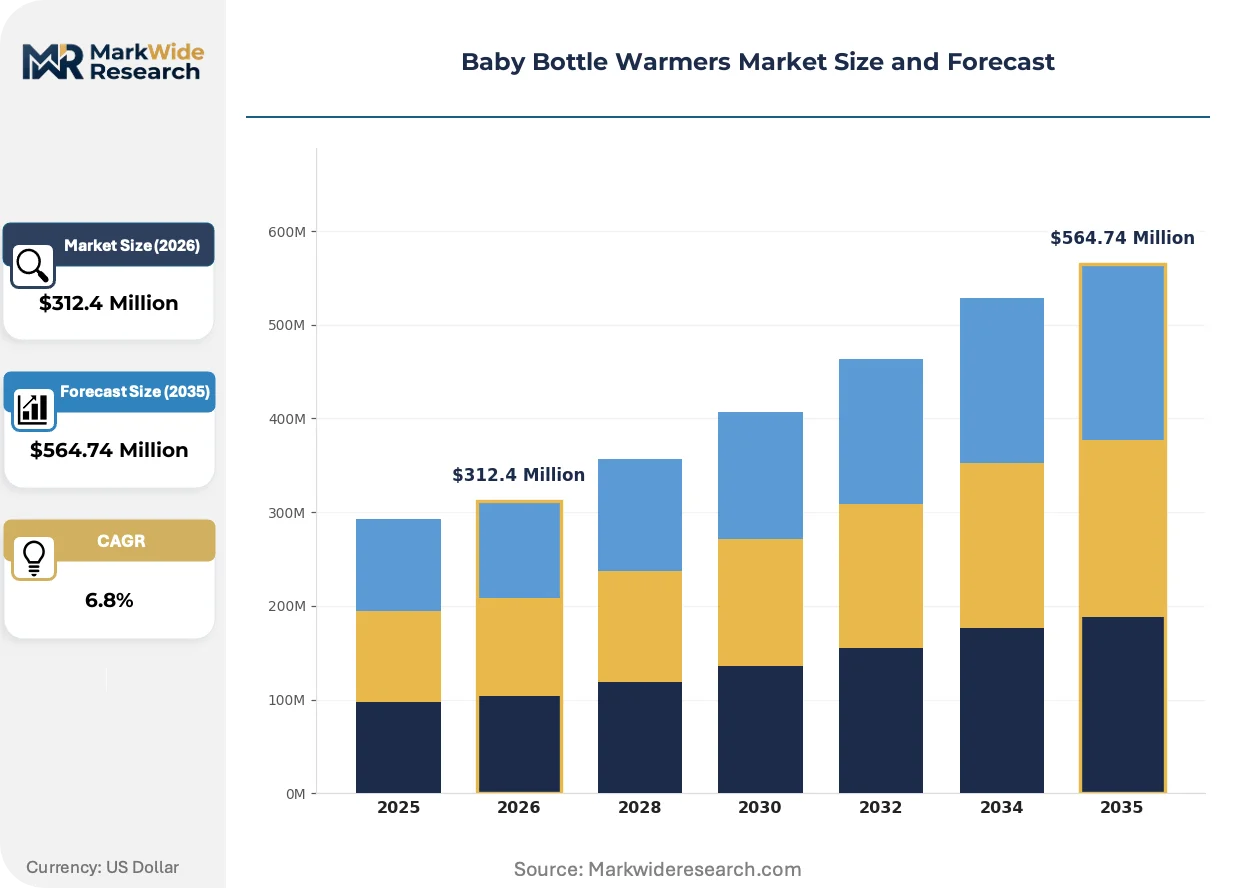
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Warmers, Microwave Warmers, Travel Warmers, Multi-Function Warmers End User: Parents, Caregivers, Hospitals, Childcare Facilities Temperature Control: Manual Control, Digital Control, Smart Control, Adjustable Settings Feature: Auto Shut-Off, Quick Heating, Compact Design, Multiple Bottle Fit |
| Companies Covered | Tommee Tippee, Grownsy, Baby Brezza, First Years, Chicco, Dr. Brown's, Kiinde, Momcozy, Philips Avent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Bottle Warmers Market Strategic Shifts
Convection heating mechanisms and solid-state thermal management are displacing traditional water-bath architectures across premium product tiers. Manufacturers are racing to integrate connected monitoring while navigating divergent chemical safety regimes.
Induction-compatible warming plates using thin-film heating elements are collapsing the temperature uniformity gap between electric warmers and conventional stovetop methods. Urban parents in Tokyo and Seoul are adopting these units at triple the rate of dial-controlled alternatives. The technology is collapsing residual demand for microwave-based warming in households where nutrient preservation ranks above speed.
REACH Annex XVII phthalate restrictions and forthcoming PFAS limitations are forcing polymer reformulation across European supply chains. Heating chamber gaskets and cable sheathing now require halogen-free thermoplastic elastomer substitutes. Premium brands targeting Germany and France are responding with full material disclosure labels ahead of mandatory SCIP database requirements.
Direct-to-consumer subscription models bundling warming units with sterilizer accessories are displacing traditional retail shelf relationships. Millennial parents in coastal US metros are purchasing through Instagram and TikTok storefronts rather than baby superstore chains. This channel rotation is most visible in California and New York, where influencer-driven education now precedes brand consideration.
Baby Bottle Warmers Market Segmentation
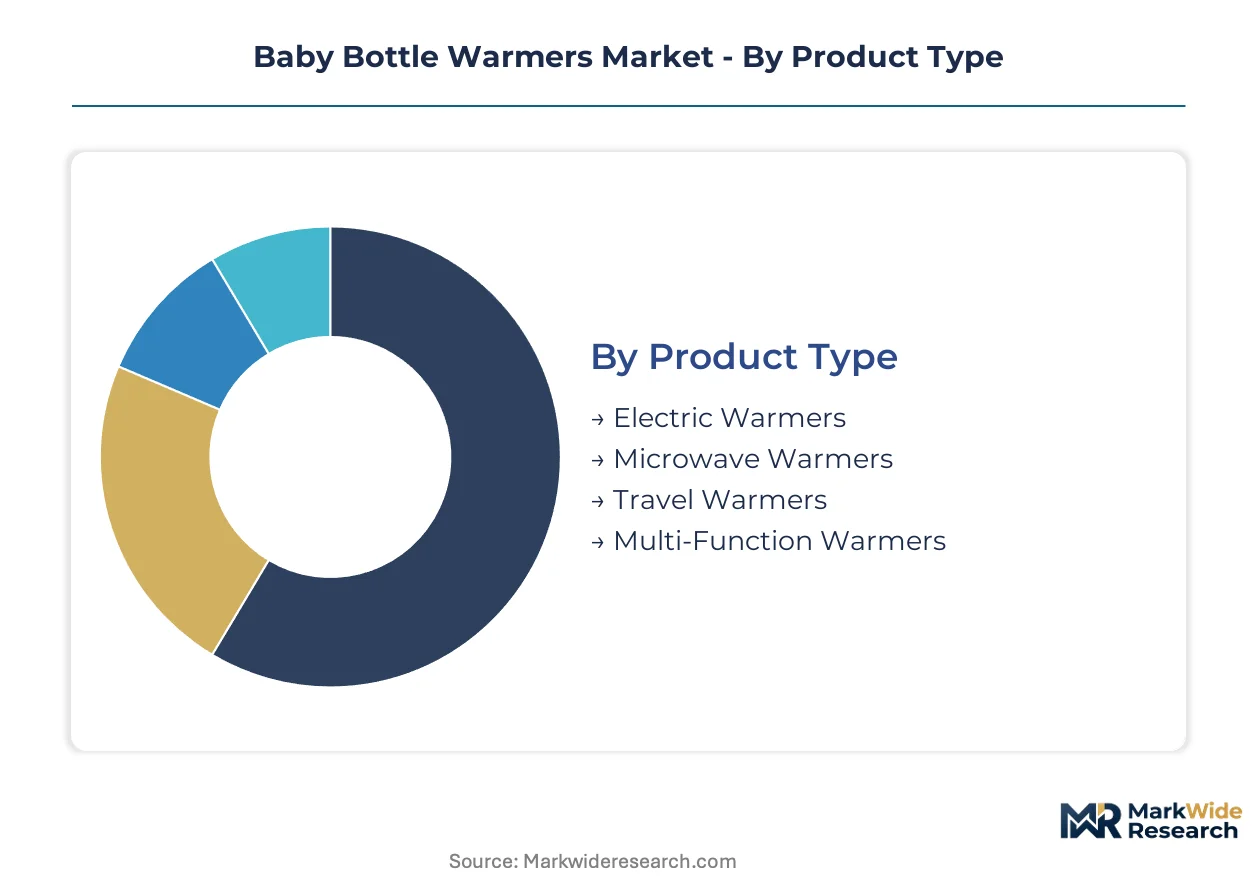
Segmentation in baby bottle warmers reveals how technical specifications and use-case specificity determine margin capture. Manufacturers align R&D investment with the control interfaces and portability demands that dominate purchase decisions across household and institutional channels.
Product Type:
Mature electric architectures dominate revenue while emerging form factors reshape portability expectations.
- Electric Warmers:Water-bath and steam-based heating elements with AC power dependency constitute the installed base across North American and European households. Parents in urban apartments favor countertop units with programmable timers that eliminate temperature guesswork during nighttime feeding cycles.
- Travel Warmers:Battery-operated and 12V automotive-compatible units employing solid-state thermal management enable warming without grid access. Working parents in Tokyo, Seoul, and Singapore adopt these at triple the rate of conventional alternatives as ride-share dependency and public transit commutes eliminate fixed-location feeding routines.
- Microwave Warmers:Insulated sleeves and thermal reservoirs that moderate uneven microwave heating through phase-change materials. Budget-conscious households in secondary Chinese cities retain modest demand despite nutrient degradation concerns.
- Multi-Function Warmers:Integrated sterilization and warming chambers with HEPA filtration and UV-C cycles. Hospital procurement departments in France and Germany specify these for neonatal units requiring single-device workflow consolidation.
Electric warmers handle the majority of throughput; travel warmers are climbing the fastest on share as urban mobility patterns reshape feeding logistics.
End User:
Volume concentrates in household purchasers while institutional procurement enforces specification rigor that cascades into consumer-tier expectations.
- Parents:Primary purchasers evaluating warming speed, temperature precision, and counter space footprint. Millennial parents in coastal US metros and Tier-1 Chinese cities drive smart-control adoption through direct-to-consumer channels.
- Hospitals:Neonatal intensive care units and maternity wards requiring FDA 510(k) or CE-MDR compliant devices with material biocompatibility certification. German and French hospital networks enforce REACH-compliant polymer specifications that upstream into consumer product design.
- Caregivers:Grandparents and non-parental guardians prioritizing simplified dial interfaces over app-dependent controls. This segment shows persistent preference for manual temperature verification through integrated thermometers.
- Childcare Facilities:Licensed daycare operators in US states with staff-to-infant ratio regulations mandating batch-warming capacity. California and New York licensing authorities require auto-shutoff certification that eliminates entry-tier products from institutional consideration.
Parental households generate the dominant revenue base; hospitals are expanding most quickly as procurement standardization elevates premium-tier specifications.
Temperature Control:
Interface sophistication stratifies pricing tiers from mechanical dials to cloud-connected monitoring ecosystems.
- Digital Control:LCD displays with one-degree precision and programmable presets for formula versus breast milk compositions. Philips Avent and Baby Brezza anchor premium positioning through sensor calibration that maintains 37°C to 40°C bands within 0.5°C variance.
- Smart Control:Bluetooth-enabled modules with smartphone app integration for remote activation and feeding log generation. Grownsy captures direct-to-consumer margin pools in China through Xiaomi MIJIA ecosystem compatibility.
- Manual Control:Dial or toggle interfaces without digital feedback, retaining cost-sensitive demand in Southeast Asian and Latin American markets where price elasticity exceeds precision requirements.
- Adjustable Settings:Multi-mode selectors accommodating bottle material variations—glass, silicone, and BPA-free plastics—with distinct thermal transfer profiles. Japanese manufacturers lead JIS-standard compliance for these adaptive algorithms.
Digital control manages the highest volume throughput; smart control is gaining share fastest as millennial parents prioritize data logging and remote operation.
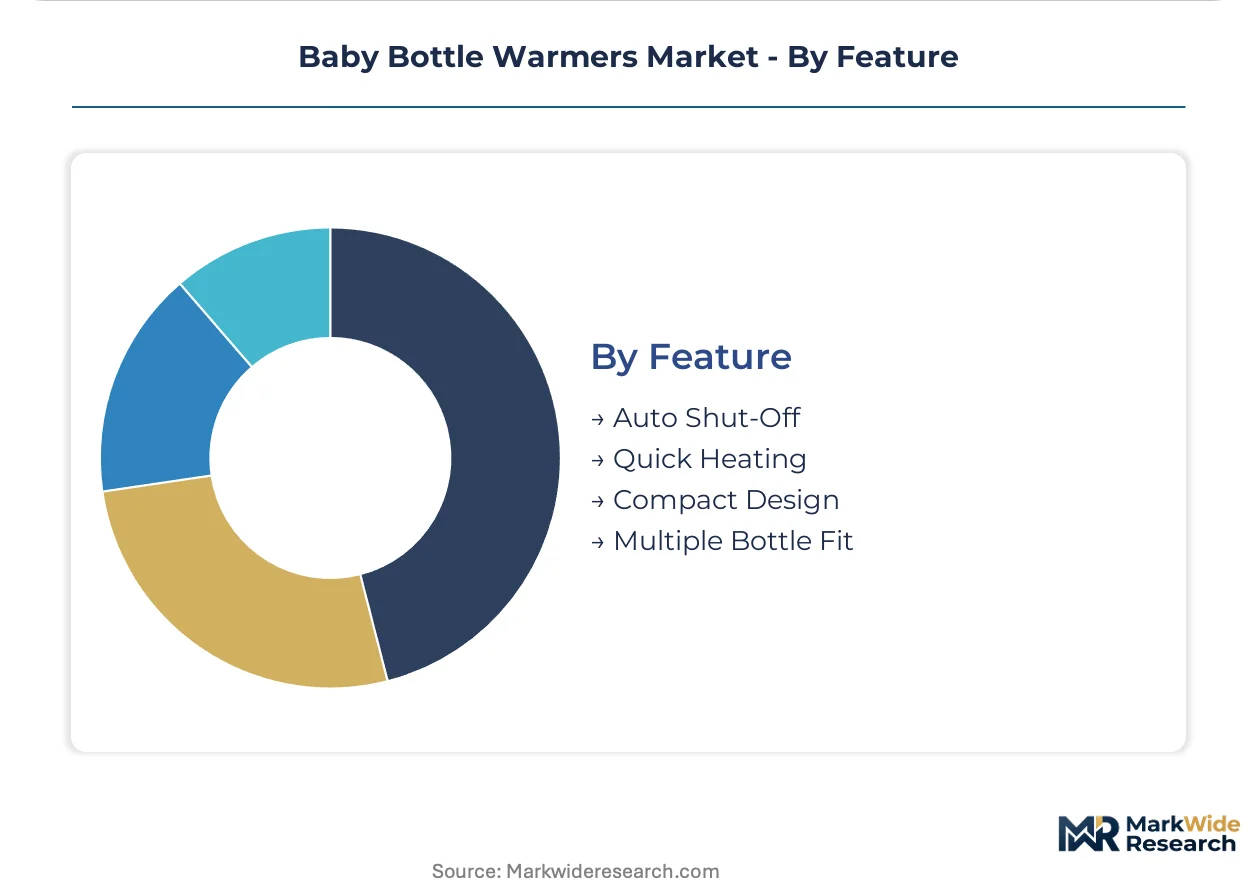
Feature:
Safety certifications and spatial constraints drive feature prioritization more than heating speed alone.
- Auto Shut-Off:Thermal cutoff circuits and timer-based power interruption preventing overheating and fire risk. US CPSC recall data shows this feature as the dominant compliance requirement for retail channel admission.
- Compact Design:Footprint reduction below 15cm width for high-rise kitchen integration. Shanghai and Shenzhen appliance retailers report 40% higher conversion rates for units under this dimensional threshold.
- Quick Heating:Convection and induction-compatible thin-film elements achieving target temperature in under 90 seconds. Seoul and Tokyo parents adopt these at rates exceeding water-bath alternatives as work schedules compress feeding windows.
- Multiple Bottle Fit:Adjustable collars and chamber inserts accommodating wide-neck, standard, and disposable liner configurations. This feature retains relevance in markets with fragmented bottle standardization like India and Brazil.
Auto shut-off carries the broadest regulatory mandate; compact design is expanding most quickly as urban residential density intensifies space constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR market surveillance in China anchors the dominant geography for baby bottle warmers, where GB standards and e-commerce penetration compress product launch cycles. The EU's Ecodesign Directive and REACH chemical safety standards reshape material specifications across export markets. Japan's METI efficiency regulations and South Korea's MFDS medical device classifications add compliance layers for premium-tier entrants.
China
Guangdong and Zhejiang manufacturing clusters supply the bulk of global unit volume through streamlined export logistics from Shenzhen and Ningbo ports. SAMR's GB 4706 household appliance safety standards and escalating market surveillance audits force faster design iteration cycles. Domestic brands leverage direct-to-consumer channels on Tmall and JD.com to bypass traditional retail markups in Tier-2 cities like Hefei and Changsha.
United States
The FDA and CPSC jointly govern material biocompatibility and electrical safety for infant feeding devices, extending certification timelines for imported units. California and New York licensing authorities mandate auto-shutoff certification that eliminates entry-tier products from institutional procurement. Millennial parents in coastal metros purchase through Instagram and TikTok storefronts rather than baby superstore chains.
Germany
REACH Annex XVII phthalate restrictions and forthcoming PFAS limitations force polymer reformulation across heating chamber gaskets and cable sheathing. The EU Green Deal's upcoming right-to-repair mandates favor modular designs with replaceable heating elements. Hospital procurement networks in Bavaria and North Rhine-Westphalia enforce CE-MDR compliance that upstreams into consumer product specifications.
Japan
METI's Top Runner efficiency program and JIS standards for thermal appliances constrain power consumption in electric warming units. Parents in Tokyo and Osaka adopt induction-compatible warming plates at triple the rate of dial-controlled alternatives. Manufacturers in the Kansai region specialize in thin-film heating elements that collapse temperature uniformity gaps with stovetop methods.
South Korea
MFDS medical device classifications apply to multi-function units with integrated sterilization, adding regulatory overhead for premium entrants. Seoul's high-rise residential density drives demand for compact warmers under 15cm width. Domestic brands compete on smart-home interoperability with Samsung SmartThings and LG ThinQ ecosystems.
Baby Bottle Warmers Market Competitive Environment
Capability concentration sits with heritage infant care specialists; scale advantage sits with diversified appliance conglomerates and direct-to-consumer digital natives. The vendor base stratifies across three tiers: European design houses commanding premium positioning, Chinese manufacturers exploiting coastal cluster economics, and subscription-model startups capturing millennial channel shifts. Dominant competitive moves include backward integration into heating element production and strategic partnerships with smart-home platform operators.
Within the heritage specialist tier, Tommee Tippee and Dr. Brown's exemplify decades-long infant feeding category authority. Philips Avent anchors the diversified conglomerate vector through European design heritage sustained across Asian retail channels. Grownsy occupies the direct-to-consumer archetype, leveraging domestic manufacturing proximity and Xiaomi MIJIA ecosystem compatibility to capture margin pools in China's e-commerce channels.
| Leading Market Players |
|---|
| Tommee Tippee |
| Grownsy |
| Baby Brezza |
| First Years |
| Chicco |
| Dr. Brown's |
| Kiinde |
| Momcozy |
| Philips Avent |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Guangdong and Zhejiang manufacturing clusters is compressing supplier margins and accelerating price competition across export markets, while REACH compliance costs in European supply chains sustain premium-tier pricing power for certified producers.
Pricing Analysis
Price spreads between EU-certified and non-certified units exceed threefold across retail channels, with pricing stratifying across premium, standard, and economy tiers driven by certification grade and smart-control feature bundling. Philips Avent and Baby Brezza extract brand premiums through FDA 510(k) material biocompatibility tiers, while Grownsy and domestic Chinese brands compete on volume scale in direct-to-consumer channels. Price erosion runs through mid-tier electric warmers as copper heating element costs and rare-earth magnet volatility compress gross margins. Budget-conscious parents in Southeast Asian markets exhibit highest price sensitivity, whereas hospital procurement departments in Germany and France prioritize REACH-compliant polymer specifications over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate supplier relationships in Shenzhen and Ningbo manufacturing corridors, reflecting working capital strain among heating element subcontractors. Supply concentrates in China, Vietnam, and Malaysia, with borosilicate glass chambers, medical-grade silicone gaskets, and thin-film heating elements as critical component dependencies. Single-source vulnerability in Guangdong province creates exposure to SAMR audit disruptions and port congestion at Yantian. Distribution runs through e-commerce platforms including Tmall, JD.com, and Amazon, with Instagram and TikTok storefronts capturing millennial parental demand in coastal US metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Baby bottle warmers constitute a high-growth disruption as REACH Annex XVII phthalate restrictions and forthcoming PFAS limitations force polymer reformulation that collapses legacy product viability.
For Market Incumbents: Pre-empt margin compression in mid-tier electric warmers by accelerating backward integration into thin-film heating element production and securing secondary sourcing in Vietnam or Malaysia. Defend premium positioning through CE-MDR certification investment that upstreams into hospital procurement specifications, while neutralizing smart-control substitution threats via Xiaomi MIJIA ecosystem partnerships.
For New Entrants and Emerging Players: Tier-2 and Tier-3 Chinese cities including Hefei, Changsha, and Xi'an offer first-mover expansion corridors with underdeveloped e-commerce penetration relative to Beijing and Shanghai saturation. Vehicle-integrated warming applications using 12V automotive adapters and USB-C power banks represent the most penetrable white-space segment among ride-share dependent urban families. Pursue direct-to-consumer launch through Tmall and JD.com with subscription bundling of sterilizer accessories.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer digital natives with Xiaomi MIJIA ecosystem compatibility and subscription accessory bundling. Long-term viability over the projection horizon favors acquisition targets with modular designs addressing EU Green Deal right-to-repair mandates and captive supply of medical-grade silicone components. Monitor SAMR GB standard enforcement intensity and REACH PFAS limitation implementation timelines as inflection indicators for certification-cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive supply of thin-film elements insulates margin from copper and rare-earth magnet volatility. |
| CE-MDR Certification Investment | Hospital procurement networks in Bavaria enforce compliance that cascades into consumer-tier specifications. |
| Xiaomi MIJIA Ecosystem Partnership | Smart-home interoperability with MIJIA captures direct-to-consumer margin pools in China's e-commerce channels. |
| Vehicle-Integrated Warming Development | 12V automotive and USB-C compatibility targets ride-share dependent urban families in Tokyo and Seoul. |
| Subscription Accessory Bundling | Direct-to-consumer sterilizer bundling displaces traditional retail shelf relationships among millennial parents. |
Study Parameters
A standing panel of product development directors at infant care manufacturers, procurement managers at hospital networks, e-commerce category buyers, and regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SAMR GB standard filings, FDA 510(k) device listings, REACH Annex XVII substance restrictions, and customs export records from Shenzhen and Ningbo ports. Bottom-up unit shipment estimates triangulated against top-down category spending data from retail audit providers.
Scenario-bracketing around regulatory implementation timelines and raw material cost trajectories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, temperature control interface, end-user channel, and geographic regulatory cluster. CAGRs derived from regression analysis of historical shipment data, adjusted for REACH compliance cost pass-through and smart-control adoption curves. Forecast inputs incorporated e-commerce penetration rates in Tier-2 Chinese cities and hospital procurement standardization intensity in Germany and France.
Practitioners should monitor SAMR audit frequency escalation, REACH PFAS limitation finalization, and copper futures volatility for early signals of forecast deviation. Forecasts reflect assumptions regarding sustained e-commerce channel shift and regulatory compliance cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Nail Trimmer Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
Smart Pacifier Market
Baby Products
Baby Food Dispensing Spoon Market
Baby Products
Baby Bottle Holder Market
Baby Products
Baby Cradles Market
Baby Products
Baby Care Products Market
Baby Products
Puppy Teething Toys Market
Baby Products
Global Adaptive Strollers Market
Baby Products
Baby High Chair Market
Baby Products
Smart Bottle Warmers Market
Baby Products
Durable Juvenile Products Market
Baby Products
Global Baby Play Mats Market
Baby Products
Baby Bottle Warmer and Sterilizer Market
Baby Products
Italy Baby Care Products Market
Baby Products
Brazil Baby Care Products Market