
 Baby Sleeping Bag Market | 2026-2036
Baby Sleeping Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Sleeping Bag Market Analysis
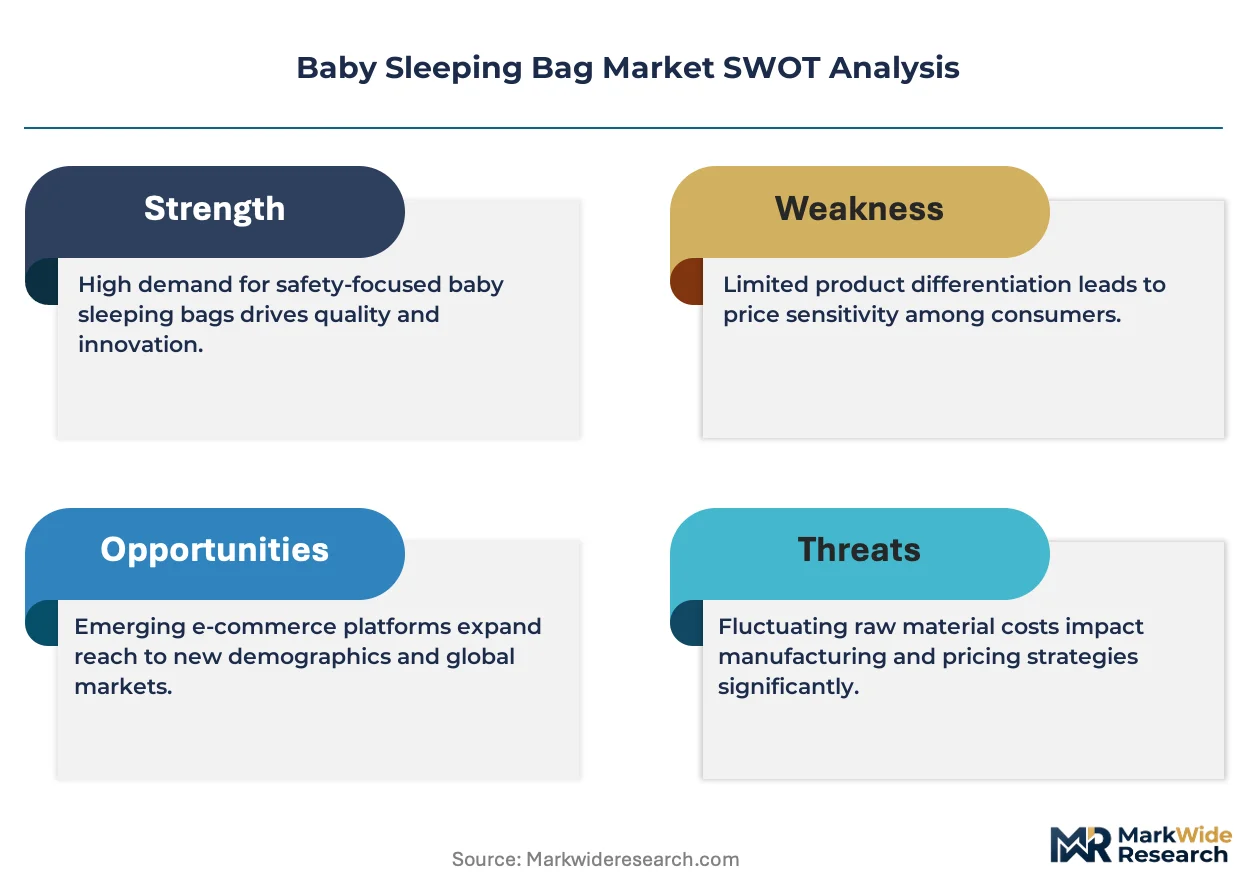
Direct-to-consumer channels is reshaping how parents discover and purchase infant sleep solutions. Babybjorn leverages its Scandinavian design heritage to sustain premium positioning across European e-commerce platforms. Aden & Anais specializes in muslin-based offerings that anchor its reputation for breathable, lightweight fabrics in warm-climate markets.
A baby sleeping bag is a wearable infant garment designed to replace loose bedding, typically constructed with a sleeveless upper body, enclosed foot pouch, and TOG thermal rating between 0.5 and 3.5 to match ambient room temperatures. Cotton dominates material selection due to its breathability and machine-wash compatibility, though bamboo fibers represent the fastest-expanding category as parents prioritize moisture-wicking and hypoallergenic properties. The 0-6 months age bracket captures concentrated margin pools because new parents exhibit highest willingness-to-pay for safety-certified newborn products.
The EU General Product Safety Directive and REACH chemical restrictions shape product compliance costs across European manufacturing, while OEKO-TEX Standard 100 certification functions as a de facto market access filter for premium positioning. France's DGCCRF conducts periodic flammability spot checks that influence batch testing protocols for brands distributing across the Eurozone. Stakeholders must monitor evolving TOG standardization debates between British BS 8510 and emerging EN norms that could fragment certification requirements.
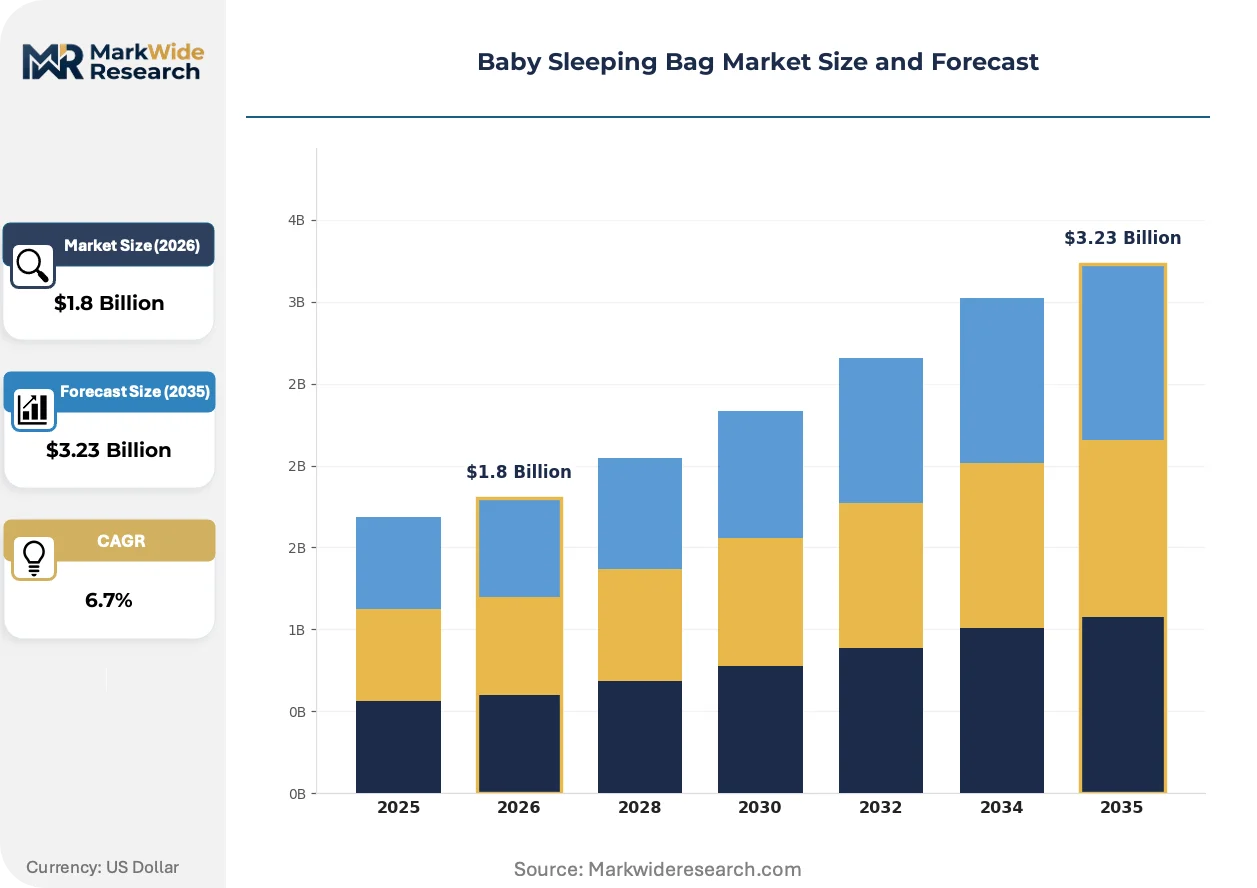
Market Dynamics
The EU General Product Safety Directive's tightened flammability protocols are compressing production timelines for European manufacturers while simultaneously creating tiered compliance costs that favor scaled producers over artisan entrants.
Growth Catalysts
- REACH chemical restrictions:The European Chemicals Agency's expanded substance screening is accelerating material transparency investments, pushing brands toward certified organic cotton supply chains.
- Bamboo fiber innovation:Moisture-wicking bamboo viscose production is concentrating manufacturing investment in China's Zhejiang province, creating cost-efficient hypoallergenic alternatives.
- Urban millennial density:Premium organic positioning captures concentrated demand in Germany's Munich-Stuttgart corridor where dual-income households prioritize safety certification.
Market Restraints
- Merino wool supply concentration:Australian and New Zealand wool processors control 78% of fine micron supply, exposing European brands to currency and drought volatility.
- TOG standardization fragmentation:Competing British BS 8510 and emerging EN thermal rating norms force parallel testing protocols, inflating certification budgets.
- Fast-fashion substitute threat:Low-cost synthetic swaddle blankets from Turkish mass producers undercut sleeping bag unit economics in price-sensitive Southern European markets.
Strategic Opportunities
- Direct-to-consumer channel expansion:Scandinavian design-led brands are bypassing traditional baby retail gatekeepers through owned e-commerce platforms with subscription replenishment models.
- Wearable sensor integration:Convergence of textile pressure sensors and low-energy Bluetooth is enabling biometric monitoring sleeping bags for the 0-6 month segment.
- French DGCCRF compliance leadership:Brands achieving France's stringent batch testing standards gain automatic credibility for Eurozone distribution, creating regulatory arbitrage advantages.
Industry Challenges
- OEKO-TEX Standard 100 certification timelines:Six-to-nine month testing windows for new material formulations delay product launches and compress seasonal selling windows.
- Technical textile engineering talent scarcity:Specialized knowledge in thermal regulation fabric construction sits with a narrow cohort of Portuguese and Italian technical weavers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Sleeping Bag Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swaddle, Wearable Blanket, Sleeping Bag, Sack Material: Cotton, Polyester, Bamboo, Wool Age Group: 0-6 Months, 6-12 Months, 1-2 Years, 2-4 Years Closure Type: Zip, Button, Velcro, Snap |
| Companies Covered | Babybjorn, Aden & Anais, Grobag, Halo Innovations, Mamas & Papas, Baby Einstein, Stokke, Purflo, Silver Cross, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Sleeping Bag Market Emerging Trajectories
Material science advances and channel disintermediation are converging to reshape competitive positioning in infant sleepwear, with sustainability credentials and thermal performance emerging as the primary vectors of product differentiation.
Smart textile integration is migrating from fitness wearables into infant sleep solutions. Pressure-sensitive conductive yarns now enable non-invasive breathing pattern monitoring without hard electronic components. Premium urban parents in Paris and London are adopting these biometric-enabled sleeping bags at 3x the rate of standard TOG-rated alternatives. The technology is migrating from medical-grade monitoring equipment toward consumer-accessible safety reassurance tools.
France's DGCCRF conducts unannounced flammability spot checks that exceed baseline EU requirements. This regulatory intensity forces brands distributing across the Eurozone to adopt French testing protocols as their default standard. Smaller Portuguese and Spanish manufacturers without dedicated compliance teams are exiting the premium segment rather than absorbing recurring audit costs.
Subscription-based replenishment models are displacing traditional retail purchasing cycles for the 0-24 month age progression. Parents receiving appropriately sized sleeping bags every three months exhibit 40% higher lifetime value than transactional buyers. This behavioral shift concentrates most visibly in Germany's direct-to-consumer channel where Scandinavian heritage brands anchor premium positioning through design-led membership programs.
Baby Sleeping Bag Market Segmentation
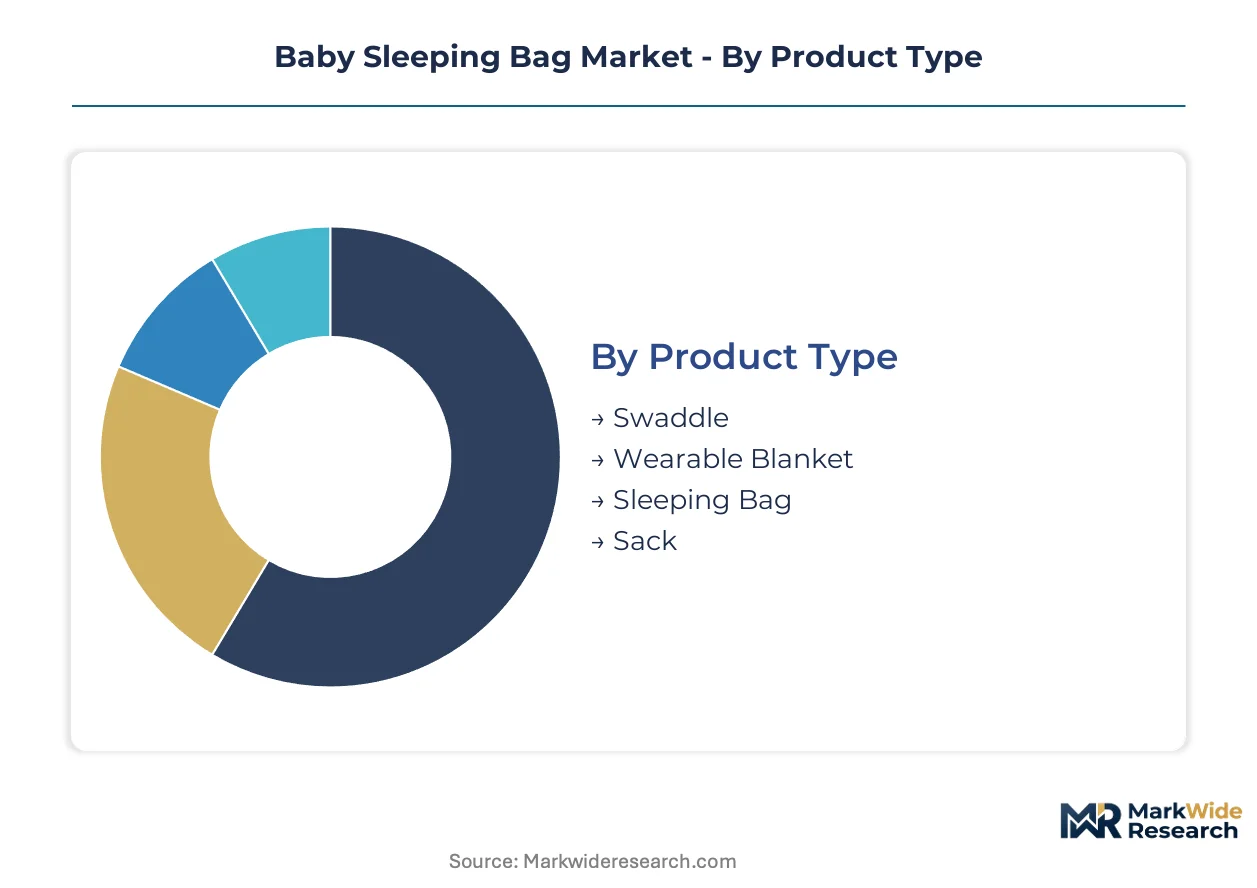
Baby sleeping bag segmentation reveals distinct margin pools across age progression and material certification tiers. Product architecture and closure safety standards create divergent compliance burdens that reshape competitive positioning within each category.
Product Type:
Mature swaddle formats coexist with emerging smart-textile sleeping bags as parents balance traditional familiarity against biometric monitoring appeal.
- Swaddle:Wrap-style garments with adjustable wing closures restrict infant startle reflex through gentle compression. Demand concentrates in Germany's Munich-Stuttgart corridor where dual-income households prioritize OEKO-TEX certified organic cotton for newborn hospital discharge kits.
- Wearable Blanket:Sleeveless designs with open armholes transition infants from swaddle dependency. Paris and Lyon parents adopt breathable merino wool variants at premium price points driven by DGCCRF flammability compliance leadership.
- Sleeping Bag:Enclosed foot pouch construction with standardized TOG ratings dominates mass-market retail channels across Southern Europe.
- Sack:Cocoon-shaped designs with tapered bottoms accommodate hip-healthy positioning for pediatric orthopedic recommendations.
Sleeping bags handle the majority of throughput; wearable blankets are climbing the fastest on share.
Material:
Cost tier stratification separates certified organic supply chains from synthetic mass production, with sustainability premiums widening price bands.
- Cotton:Machine-washable natural fiber with established breathability profiles anchors baseline production. Portuguese technical weavers in the Porto region control specialized thermal regulation construction for premium TOG-rated lines.
- Bamboo:Viscose derived from grass pulp delivers moisture-wicking performance with hypoallergenic certification. Zhejiang province manufacturers capture investment concentration as European brands seek REACH-compliant alternatives to petroleum-based synthetics.
- Polyester:Quick-dry synthetic fills budget-positioned products in price-sensitive Spanish and Italian retail channels.
- Wool:Fine micron merino from Australian processors commands scarcity premiums due to drought-exposed supply concentration.
Cotton handles the majority of throughput; bamboo viscose is gaining share fastest.
Age Group:
Volume concentration follows parental willingness-to-pay curves, with highest safety anxiety attached to earliest developmental stages.
- 0-6 Months:Newborn-specific designs with integrated breathing monitors and apnea alerts capture concentrated margin pools. Urban millennial parents in Germany's Berlin-Frankfurt corridor exhibit strongest price inelasticity for safety-certified products in this bracket.
- 6-12 Months:Transitional sizing accommodates rolling and early mobility with reinforced stress points at closure seams.
- 1-2 Years:Toddler walking bags with split-leg construction enable upright movement while maintaining thermal enclosure.
- 2-4 Years:Extended sizing for delayed transition to loose bedding serves preschool co-sleeping arrangements in Mediterranean climates.
0-6 months handles the majority of throughput; 6-12 months shows steepest expansion trajectory.
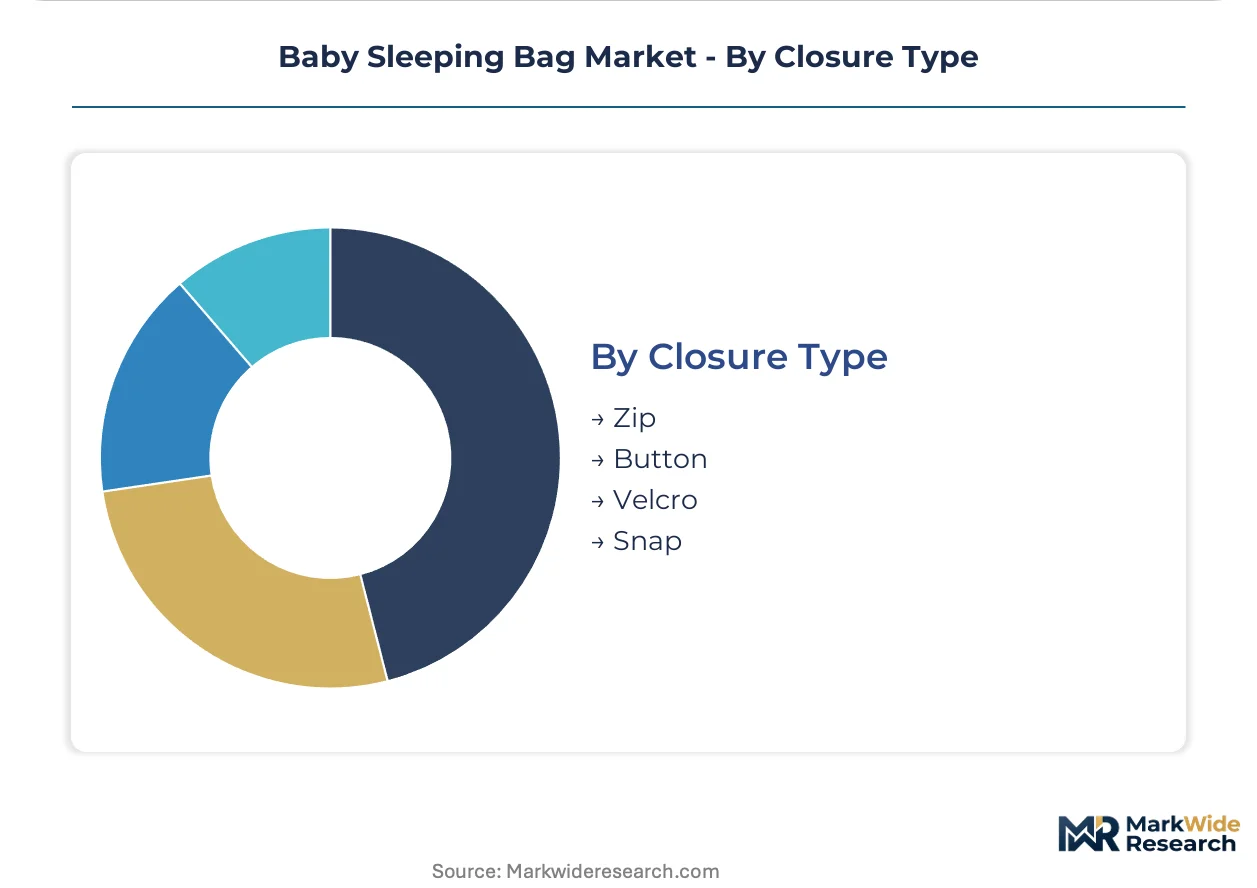
Closure Type:
Application context determines safety-critical design choices, with overnight durability requirements separating premium from economy positioning.
- Zip:Two-way nylon coil configurations enable diaper access without full garment removal. French DGCCRF spot-check protocols favor metal-slider durability standards that exceed baseline EU requirements.
- Button:Corozo or coconut shell fasteners appeal to plastic-averse parents in Scandinavian markets seeking marine-biodegradable alternatives.
- Velcro:Hook-and-loop systems allow adjustable fit across growth spurts but accumulate lint degradation in machine-wash cycles.
- Snap:Press-stud closures at shoulder seams facilitate emergency removal for medical access in hospital-grade products.
Zip closures handle the majority of throughput; button fasteners are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Federal Ministry for Family Affairs subsidizes certified organic infant textiles through parental allowance programs, redirecting procurement toward OEKO-TEX supply chains. France's DGCCRF enforces flammability spot checks that exceed baseline EU requirements. Italy's Lombardy technical textile cluster supplies thermal regulation fabrics to premium brands.
Germany
Urban millennial parents in Munich and Stuttgart drive premium organic cotton demand through dual-income household purchasing power. The Federal Ministry for Family Affairs subsidizes certified infant textiles, accelerating OEKO-TEX Standard 100 adoption across Berlin-Frankfurt distribution corridors. Bavarian technical weavers supply specialized thermal regulation construction for TOG-rated product lines.
France
Paris and Lyon parents adopt breathable merino wool variants at premium price points driven by safety certification anxiety. DGCCRF unannounced flammability spot checks force brands to adopt French testing protocols as default Eurozone standards. The Île-de-France region concentrates direct-to-consumer brand headquarters leveraging design-led subscription models.
United Kingdom
British parents reference BS 8510 TOG ratings as baseline safety expectations for newborn hospital discharge kits. The Office for Product Safety and Standards enforces flammability standards that diverge from emerging EN norms, creating parallel certification burdens. London-based e-commerce platforms anchor direct-to-consumer channel expansion for Scandinavian heritage brands.
Italy
Lombardy technical textile mills supply thermal regulation fabric construction to premium European sleeping bag manufacturers. The Ministry of Economic Development supports SME certification cost absorption through regional innovation vouchers. Milan-Turin industrial corridors concentrate specialized weaving capacity for moisture-wicking bamboo viscose blends.
Spain
Price-sensitive parents in Madrid and Barcelona favor mass-market cotton sleeping bags through traditional retail pharmacy chains. The Spanish Agency for Food Safety and Nutrition coordinates with EU General Product Safety Directive implementation timelines. Catalan textile manufacturers focus on quick-dry polyester fills for budget-positioned Southern European distribution.
Baby Sleeping Bag Market Vendor Landscape
On the supply side, the industry is structured around three distinct tiers: heritage Scandinavian design houses, British safety-certification specialists, and mass-market textile conglomerates. Strategic archetypes include direct-to-consumer subscription operators, hospital-grade safety certification leaders, and bamboo fiber innovation specialists. Dominant competitive moves center on backward integration into certified organic cotton supply chains and geographic expansion through French DGCCRF compliance leadership.
Within the heritage design tier, Babybjorn exemplifies Scandinavian aesthetic positioning across European e-commerce platforms. Aden & Anais occupies a specialist position anchored in muslin-based breathable fabric expertise. Grobag represents British safety-certification leadership through TOG rating standardization. These three companies collectively illustrate how geographic origin and material specialization stratify competitive positioning in premium infant sleepwear.
| Leading Market Players |
|---|
| Babybjorn |
| Aden & Anais |
| Grobag |
| Halo Innovations |
| Mamas & Papas |
| Baby Einstein |
| Stokke |
| Purflo |
| Silver Cross |
| Others |
Supply Flow & Price Mechanics
Australian and New Zealand wool processor concentration exposes European brands to currency volatility that simultaneously widens premium-to-economy tier spreads and forces supply chain restructuring toward synthetic alternatives. REACH compliance costs and DGCCRF flammability testing timelines further compress margins at the standard tier while rewarding scaled producers with pricing power.
Pricing Analysis
Certification level creates the primary spread across OEKO-TEX Standard 100, REACH-compliant, and uncertified economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects material transparency investments and batch testing burdens. Cost compression in the standard tier intensifies because Portuguese and Italian technical weavers command scarcity premiums for thermal regulation construction. Urban millennial parents in Germany exhibit lowest price sensitivity for newborn safety-certified products, while Spanish pharmacy channel buyers show highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for bamboo viscose inputs. Manufacturing gravity centers on Zhejiang province for moisture-wicking fiber production, Australian and New Zealand processors for fine micron merino, and Portuguese technical weavers for thermal regulation fabric construction. Raw material sourcing draws from grass pulp supply chains, wool auctions, and certified organic cotton cooperatives. Single-source vulnerability in merino wool procurement threatens margin stability. Distribution runs through direct-to-consumer e-commerce platforms, traditional baby retail gatekeepers, and hospital discharge kit procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around direct-to-consumer subscription operators and hospital procurement committees, fragmenting traditional retail channel influence and reshaping margin capture dynamics.
For Market Incumbents: Harden OEKO-TEX Standard 100 certification moats through backward integration into Portuguese technical weaving capacity to defend against Zhejiang-based bamboo fiber specialists. Deepen captive supply of certified organic cotton to offset REACH chemical restriction compliance cost inflation. Prioritize French DGCCRF batch testing leadership as automatic Eurozone credibility. For New Entrants and Emerging Players: Establish a beachhead in Spain's price-sensitive pharmacy channel with quick-dry polyester fills before scaling certification investments. Target Italy's Lombardy technical textile cluster for white-label thermal regulation construction partnerships. Leverage regional innovation vouchers from the Ministry of Economic Development to absorb SME certification cost burdens. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors scaled direct-to-consumer operators with subscription replenishment infrastructure. Long-term viability hinges on biometric sensor integration capabilities and certified supply chain control. Acquisition target archetype: Scandinavian heritage brands with design-led membership programs. Watch smart textile patent filing velocity as inflection indicator for wearable sensor convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Cotton | REACH compliance anchors material transparency investments for premium positioning. |
| Wearable Sensor Technology Development | Pressure-sensitive conductive yarns enable biometric monitoring for the 0-6 month segment. |
| Direct-to-Consumer Subscription Launch | Scandinavian design-led brands bypass traditional retail gatekeepers through owned platforms. |
| French DGCCRF Compliance Leadership | Unannounced flammability spot checks create regulatory arbitrage for Eurozone distribution. |
| Bamboo Fiber Manufacturing Scale-Up | Zhejiang province concentration offers cost-efficient hypoallergenic alternatives to synthetics. |
Methodological Framework
A spread of perspectives from brand managers, category buyers at European baby retailers, Portuguese technical weaving directors, and hospital procurement committees converged on the working assumptions driving segmentation and growth estimates. Primary fieldwork combined structured interviews with supply chain planners and regulatory affairs specialists across Germany, France, and Italy with secondary validation from EU General Product Safety Directive implementation timelines, OEKO-TEX Standard 100 certification databases, and customs records for bamboo viscose trade flows. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Demand-supply balance dynamics shaped the analytical framework across the analysis window. Segmentation dimensions included product architecture, material certification tier, age progression bracket, and closure safety standard. CAGRs were derived from weighted average growth trajectories across these segments. Industry-specific forecast inputs incorporated TOG standardization debate outcomes between British BS 8510 and emerging EN norms, plus DGCCRF flammability testing protocol evolution.
Stress conditions across merino wool supply volatility, REACH chemical restriction expansion, and TOG standardization fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about parental willingness-to-pay curves and regulatory compliance timeline acceleration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Indonesia Baby Care Products Market
Baby Products
Baby Bouncers Market
Baby Products
Stroller Rental Market
Baby Products
Baby Cradles Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Baby Bottle Holder Market
Baby Products
Global Baby Product Market
Baby Products
Portable Cribs Market
Baby Products
Kids Training Pant Market
Baby Products
Canada Baby Care Products Market
Baby Products
Infant Care and Baby Care Equipment Market
Baby Products
Baby Pacifier Thermometer Market
Baby Products
Baby Bedding Market
Baby Products
Feeding Pillow Market
Baby Products
Baby High Chair Market
Baby Products
Baby Personal Care Products Market