
 Global Baby Car Seats Market | 2026-2036
Global Baby Car Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Global Baby Car Seats Market Analysis
E-commerce distribution is fragmenting as direct-to-consumer platforms and specialty baby retailers compete for shelf space and search visibility. Graco leverages its multi-channel logistics network to sustain wholesale partnerships alongside owned digital storefronts. Britax anchors its position through specialist independent retailers that demand technical training and installation support. Maxi-Cosi competes aggressively on European marketplace platforms where ISOFIX-compatible SKUs dominate search rankings.
Baby car seats are child restraint systems engineered from energy-absorbing foam, reinforced polymer shells, and textile harness assemblies designed to protect occupants during frontal and side-impact collisions. Manufacturing integrates injection-molded plastic frames with flame-retardant fabric covers that must pass dynamic sled testing at specified velocity thresholds. Convertible seats occupy the largest revenue pool because they span multiple age groups and reduce replacement frequency for cost-conscious households. ISOFIX installation systems command premium positioning as vehicle compatibility becomes a decisive purchase filter. All-in-one seats represent the fastest structural expansion as manufacturers consolidate R&D spending across fewer platform variants.
The US National Highway Traffic Safety Administration enforces FMVSS 213 compliance testing, while the European Union applies ECE R44/04 and the successor i-Size regulation under UN ECE R129. China's GB 27887 standard mandates CCC certification for all imported and domestic child restraint products. Stakeholders must monitor regulatory divergence between i-Size's mandatory rear-facing provisions and varying US state-level booster age thresholds when configuring regional product portfolios.
Market Dynamics
Regulatory divergence between i-Size and FMVSS 213 is fragmenting product portfolios as manufacturers engineer distinct platform variants for European and North American certification. This compliance bifurcation concentrates R&D spending among firms with multi-regional testing infrastructure.
Growth Catalysts
- ECE R129 i-Size mandate:Mandatory rear-facing provisions until 15 months in the European Union are accelerating replacement cycles for forward-facing inventory. Retailers in Germany and France report inventory turnover compression.
- Polymer shell advances:Energy-absorbing copolymer injection molding is reducing unit weight by 15-20% while maintaining dynamic sled performance. Lightweighting expands vehicle compatibility for compact car segments.
- Millennial parent cohort:First-time buyers aged 28-35 in the United States demonstrate willingness-to-pay premiums for ISOFIX installation systems. This demographic concentrates in suburban metropolitan clusters.
Market Restraints
- Polypropylene resin volatility:Shell manufacturing depends on petroleum-derived feedstocks with quarterly price swings exceeding 12%. Cost pass-through mechanisms remain incomplete in private-label contracts.
- Testing infrastructure concentration:Dynamic sled certification facilities cluster in Michigan, Stuttgart, and Shanghai. Capacity constraints extend compliance timelines for new market entrants.
- Extended rear-facing physical limits:Cabin geometry in subcompact vehicles prevents proper installation of rear-facing seats for children above 22 kilograms. This technical ceiling segments addressable demand.
Strategic Opportunities
- India's BIS certification expansion:Mandatory AIS-072 compliance for imported child restraints creates first-mover advantages for ISOFIX-compatible platform localization. Domestic vehicle assembly growth supports aftermarket attachment.
- Subscription-based seat cycling:Direct-to-consumer rental models address rapid growth-phase transitions from infant carriers to booster configurations. Logistics networks in the Netherlands and Denmark demonstrate unit economics viability.
- Sensor-integrated harness systems:Convergence of MEMS accelerometers with textile-embedded pressure monitoring enables real-time installation feedback. This technology bundle commands premium positioning in Scandinavian markets.
Industry Challenges
- Certification engineer scarcity:FMVSS 213 and UN ECE R129 testing protocols require specialized biomechanical expertise. Recruitment competition with automotive OEM safety divisions constrains talent pipelines.
- Legacy inventory obsolescence:Retailer holdings of pre-i-Size European stock face markdown pressure as regulatory deadlines approach. Channel conflict emerges between clearance pricing and new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Baby Car Seats Market |
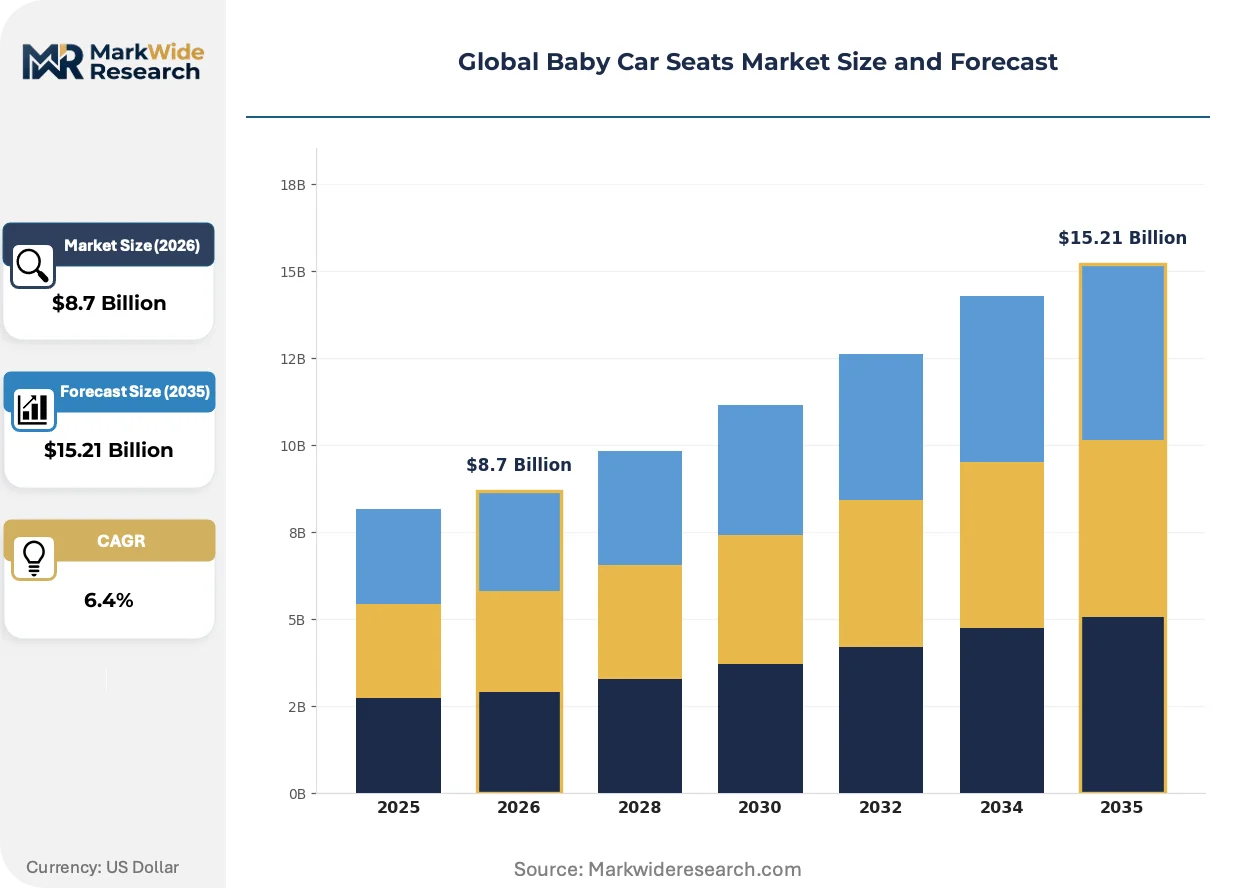
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Seats, Convertible Seats, Booster Seats, All-in-One Seats Installation Type: ISOFIX, Seatbelt, LATCH, Built-in Base Material: Plastic, Fabric, Metal, Foam Age Group: Newborn, Toddler, Preschool, School Age |
| Companies Covered | Graco, Britax, Maxi-Cosi, Chicco, Recaro, Dorel Industries, Newell Brands, Goodbaby International, Cybex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Baby Car Seats Market Emerging Trajectories
Material science advances and installation system standardization are compressing product development cycles while elevating safety performance thresholds. These forces are reshaping competitive differentiation from hardware durability toward integrated ecosystem compatibility.
Smart restraint technology is migrating from luxury vehicle OEM partnerships to aftermarket accessory integration. Premium parent segments in Sweden and California are adopting Bluetooth-enabled installation verification systems that communicate with smartphone applications. This connectivity layer is migrating from hardware premiumization toward subscription-enabled service models that manufacturers use to capture lifetime value beyond initial purchase.
The European Union's CSRD disclosure requirements are mandating supply chain carbon footprint documentation for child restraint imports. Manufacturers sourcing polymer shells from Asian contract molders must now verify Scope 3 emissions or risk marketplace delisting. German retailers are responding by prioritizing suppliers with EPD-certified production facilities, compressing procurement timelines for uncertified vendors.
Millennial and Gen Z parents are consolidating purchase research within video-centric social platforms before entering physical retail environments. Specialty baby retailers in the United Kingdom and Australia report showrooming rates exceeding 40% as price comparison happens in-aisle via mobile devices. This behavior pattern is most pronounced among first-time buyers seeking peer validation for safety-critical decisions.
Global Baby Car Seats Market Segmentation
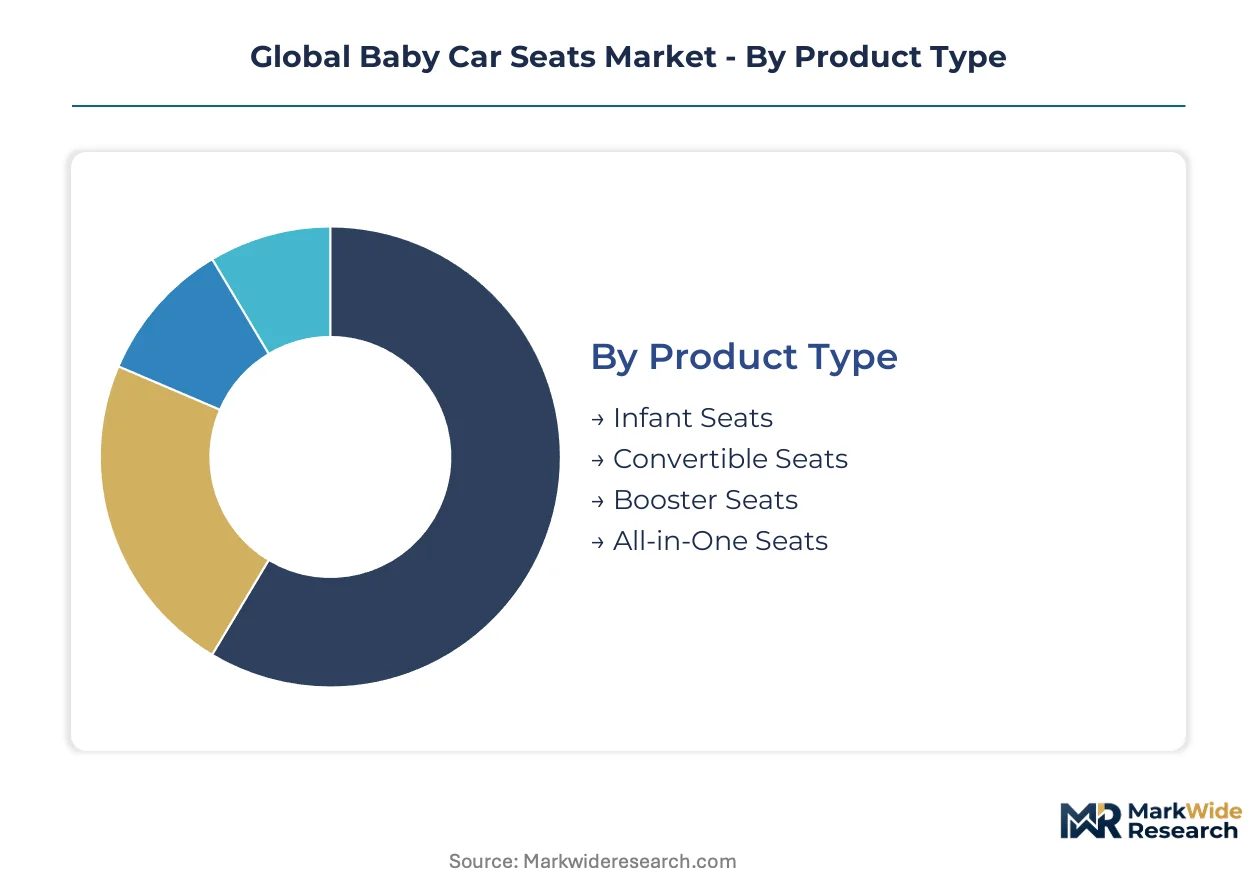
Product architecture in the baby car seats market determines compliance pathways, replacement cycles, and margin structures. Segmentation reveals how manufacturers allocate R&D across platform variants and which installation systems command premium positioning.
Product Type:
Mature convertible configurations coexist with emerging all-in-one platforms as households seek fewer replacement purchases.
- Convertible Seats:Dual-facing designs accommodate rear-facing infants and forward-facing toddlers through adjustable recline mechanisms and extended harness height ranges. Demand concentrates in suburban United States households where vehicle ownership spans 10-15 years and parents prioritize multi-stage utility. ISOFIX-compatible variants in Germany and France sustain premium pricing against regulatory replacement cycles.
- All-in-One Seats:Integrated platforms span newborn through booster configurations via modular headrest assemblies and removable harness systems. Growth accelerates among millennial parents in California and Texas seeking single-purchase solutions. Manufacturers consolidate tooling investments across fewer SKUs while capturing lifetime value.
- Infant Seats:Rear-facing-only carriers with detachable bases dominate hospital discharge protocols in US metropolitan clusters.
- Booster Seats:Backless and high-back variants address school-age transition requirements where vehicle seat belt geometry becomes compatible.
Convertible seats retain volume leadership; all-in-one configurations hold the steepest expansion curve.
Installation Type:
Cost tier stratification separates standardized belt routing from rigid attachment systems requiring vehicle interface compatibility.
- ISOFIX:Rigid lower anchor connectors with top-tether stabilization eliminate belt routing errors and reduce installation time to under 60 seconds. European regulatory mandates under ECE R129 i-Size have driven penetration above 80% in Germany, France, and Sweden. Vehicle fleet compatibility lists now filter purchase decisions before retail consideration.
- LATCH:Lower anchors and tethers for children systems dominate United States installations where FMVSS 213 compliance requires standardized anchor spacing. Aftermarket retrofit kits address legacy vehicle populations in rural Texas and Florida markets.
- Seatbelt:Universal routing paths accommodate rental fleets and multi-vehicle households lacking dedicated anchor hardware.
- Built-in Base:Integrated vehicle seat designs in premium Swedish and German OEM lineups capture installation liability within manufacturer warranty terms.
ISOFIX commands the premium tier; LATCH maintains broadest geographic coverage.
Material:
Application-specific performance requirements dictate polymer selection against flammability and impact absorption benchmarks.
- Plastic:Injection-molded polypropylene copolymer shells form the primary energy management structure, with wall thickness optimization reducing unit weight 15-20% while maintaining dynamic sled performance. German and Chinese molding facilities supply tier-one manufacturers with just-in-sequence delivery.
- Foam:Expanded polystyrene and copolymer energy absorbers line shell interiors for impact force distribution.
- Fabric:Flame-retardant polyester blends face CSRD disclosure requirements under EU supply chain documentation mandates.
- Metal:Steel reinforcement bars in harness yoke assemblies provide tensile strength for dynamic loading scenarios.
Plastic dominates bill-of-materials weight; foam innovations drive lightweighting trajectories.
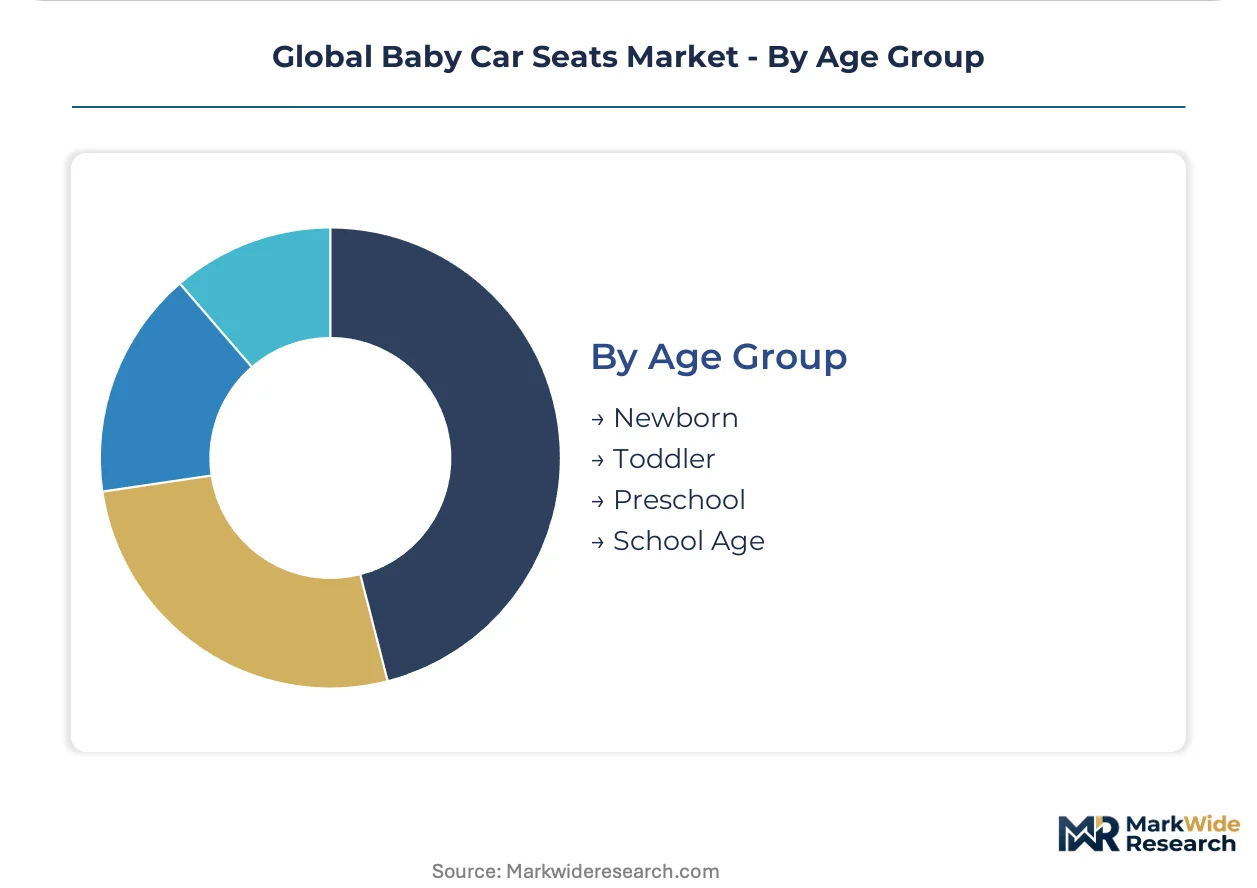
Age Group:
Customer type segmentation aligns physiological development stages with regulatory phase-out thresholds.
- Newborn:Rear-facing-only systems with 4-35 pound weight ratings address hospital discharge requirements and early motor vehicle transport in United States urban corridors.
- Toddler:Forward-facing harness seats with 5-point restraint systems transition children 2-4 years as ECE R129 mandates extend rear-facing minimums to 15 months.
- Preschool:High-back booster configurations elevate seated height for proper seat belt fit across shoulder and lap contact points.
- School Age:Backless boosters and seat belt positioners serve final restraint phase before adult belt geometry compatibility.
Toddler configurations sustain replacement frequency; school-age products face longest usage intervals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government mandates for extended rear-facing provisions and vehicle fleet expansion among young families are concentrating demand in markets with elevated safety enforcement and rising birth rates. NHTSA testing protocols in the United States, ECE R129 i-Size in the European Union, and GB 27887 certification in China create distinct compliance environments that fragment manufacturer portfolios.
United States
Suburban metropolitan clusters in Texas, California, and Florida drive replacement cycles as millennial parents prioritize ISOFIX-compatible installations. NHTSA enforces FMVSS 213 compliance with standardized LATCH anchor spacing that shapes product development timelines. Detroit's automotive safety testing corridor hosts dynamic sled certification facilities serving domestic manufacturers.
Germany
First-time parents in Bavaria and North Rhine-Westphalia demonstrate willingness-to-pay premiums for i-Size certified platforms with mandatory 15-month rear-facing provisions. KBA vehicle type approval processes integrate child restraint compatibility checks into OEM homologation. Stuttgart's polymer molding cluster supplies energy-absorbing copolymer shells to tier-one seat manufacturers.
China
Rising vehicle ownership among young families in Shanghai, Beijing, and Guangzhou accelerates aftermarket attachment as GB 27887 CCC certification becomes standard for imported products. SAMR market surveillance tightens compliance verification at port-of-entry inspection points. Yangtze River Delta injection molding facilities dominate polypropylene shell production for domestic and export markets.
India
AIS-072 mandatory compliance for imported child restraints creates localization incentives as domestic vehicle assembly expands in Maharashtra and Tamil Nadu. BIS certification timelines extend market entry barriers for new entrants. Gurugram's automotive component corridor attracts ISOFIX platform assembly investments from multinational suppliers.
United Kingdom
Specialty baby retailers in London and Manchester face showrooming rates exceeding 40% as parents conduct video-centric research on social platforms before purchase. DVLA vehicle registration data informs regional marketing targeting for compatible installation systems. Midlands-based textile suppliers adapt flame-retardant fabric production to meet CSRD disclosure requirements.
Global Baby Car Seats Market Vendor Landscape
On the supply side, the industry is consolidating around multi-regional testing infrastructure and polymer shell manufacturing scale. Tier-one manufacturers maintain captive relationships with injection molding facilities in Germany and China to secure just-in-sequence delivery. Three strategic archetypes dominate: full-range portfolio owners spanning infant through booster configurations, ISOFIX installation specialists, and private-label contract manufacturers serving mass-market retail channels. Competitive moves concentrate on regulatory pre-certification investments and direct-to-consumer platform development.
Within the premium-tier vector, Maxi-Cosi and Cybex exemplify European ISOFIX specialists competing on i-Size certification depth, while Graco represents North American full-range portfolio owners with multi-channel logistics capabilities. Britax occupies a position between these archetypes through specialist retailer partnerships demanding technical training support. These companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Graco |
| Britax |
| Maxi-Cosi |
| Chicco |
| Recaro |
| Dorel Industries |
| Newell Brands |
| Goodbaby International |
| Cybex |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor shapes cost dynamics across polymer shell sourcing from Chinese injection molders, concentrating supply-side leverage among manufacturers with captive molding partnerships while downstream price differentiation stratifies between i-Size-certified premium tiers and belt-routed economy configurations.
Pricing Analysis
Certification level under UN ECE R129 i-Size versus FMVSS 213 compliance creates the primary spread between premium ISOFIX platforms and standard belt-routed alternatives. Three-tier pricing structure across premium, standard, and economy levels anchors on installation system complexity, with polymer shell lightweighting commanding additional margin capture. Pricing pressure stems from polypropylene resin volatility feeding through private-label contract terms. First-time millennial parents in suburban United States clusters demonstrate lowest price sensitivity for ISOFIX-compatible configurations, while multi-vehicle households in rural Texas and Florida markets prioritize economy tier belt-routed seats.
Supply Chain Analysis
Goodbaby International and Dorel Industries contract manufacturing facilities in China, Germany, and Mexico hold dominant polymer shell production capacity for tier-one brands. Polypropylene copolymer resin draws from petroleum-derived feedstocks in Yangtze River Delta and Stuttgart molding clusters, with textile harness assemblies sourcing from Midlands-based flame-retardant fabric suppliers. Single-source vulnerability concentrates in dynamic sled certification infrastructure clustering around Michigan, Stuttgart, and Shanghai testing corridors. Distribution runs through wholesale partnerships with specialty baby retailers alongside direct-to-consumer platform fulfillment from regional logistics nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks cyclical recovery patterns tied to millennial and Gen Z birth rate cohorts entering peak family formation years, with replacement cycle compression under extended rear-facing mandates amplifying demand elasticity.
For Market Incumbents: Harden multi-regional testing infrastructure against certification engineer scarcity by recruiting biomechanical specialists from automotive OEM safety divisions before talent pipeline constraints tighten. Deepen backward integration into polymer shell molding through captive facility investments in Germany and China, insulating margin position from quarterly resin volatility exceeding twelve percent. Prioritize i-Size pre-certification investments ahead of regulatory deadline inventory obsolescence.
For New Entrants and Emerging Players: India's underpenetrated AIS-072 compliance environment offers first-mover positioning as domestic vehicle assembly expansion in Maharashtra and Tamil Nadu accelerates aftermarket attachment. Target subscription-based seat cycling models in Netherlands and Denmark logistics corridors where unit economics viability has been demonstrated. Pursue direct-to-consumer platform launches with ISOFIX-compatible SKUs to bypass wholesale margin compression.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified consumer goods parents seeking to monetize non-core child restraint divisions lacking dedicated R&D scale. Long-term viability favors acquisition of ISOFIX installation specialists with established European marketplace platform presence and i-Size certification depth. Monitor BIS certification timeline extensions in India as inflection indicator for localization incentive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| i-Size Certification Pre-Investment | Accelerates European market access ahead of ECE R129 mandate deadlines. |
| Polymer Shell Lightweighting R&D | Reduces unit weight fifteen to twenty percent while maintaining sled performance. |
| Direct-to-Consumer Platform Launch | Bypasses wholesale margin compression and captures first-party customer data. |
| Subscription-Based Seat Cycling Model | Addresses rapid growth-phase transitions with proven Netherlands logistics economics. |
| India AIS-072 Localization Investment | Positions for mandatory compliance expansion in domestic vehicle assembly growth. |
Methodological Framework
Initial hypotheses were tested against primary input from product development executives at tier-one manufacturers, regulatory compliance officers, specialty baby retailer category managers, and polymer molding facility operations directors, then refined through secondary validation against NHTSA FMVSS 213 filing databases, ECE R129 type approval registries, SAMR CCC certification records, and customs trade flow documentation, with bottom-up unit shipment modeling triangulated against top-down market value reconstruction.
Demand-supply-balance framing across the analysis window segmented volume and value outputs by product architecture, installation system type, polymer material grade, and age group compatibility tier, with CAGRs derived from regression against vehicle ownership rates among young families and regulatory replacement cycle compression. Forecast inputs incorporated i-Size mandate phase-in schedules and polypropylene resin price elasticity coefficients.
Practitioners should monitor BIS certification timeline shifts, ECE R129 enforcement variance across EU member states, and polypropylene feedstock price volatility for early signals requiring forecast revision. Cross-checking against NHTSA Fatality Analysis Reporting System safety outcome data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Food Dispensing Spoon Market
Baby Products
Diaper Bag Market
Baby Products
Baby Prams and Strollers Market
Baby Products
Global Smart Connected Baby Monitors Market
Baby Products
China Maternity Goods Market
Baby Products
Baby Bottle Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Portable Cribs Market
Baby Products
South Africa Baby Care Products Market
Baby Products
Baby Changing Light Market
Baby Products
Baby Powder Market
Baby Products
Kids Training Pant Market
Baby Products
Baby Bedding Market
Baby Products
Brazil Baby Care Products Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Baby Feeding Bottles Market