
 Feather Meal Market | 2026-2036
Feather Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Feather Meal Market Analysis
North American rendering capacity is shifting toward higher-value hydrolyzed outputs as energy and labor costs pressure conventional processing economics. Darling Ingredients leverages vertical integration across poultry collection and protein refining to sustain margin capture through the value chain. Tyson Foods anchors supply security through captive rendering volumes tied to its processing plant network. JG Pears competes on specialized steam-hydrolyzed grades for European aquaculture and pet food channels.
Feather meal is a rendered protein product derived from poultry feathers processed under heat and pressure to break down keratin into digestible amino acids, typically yielding crude protein content of 80-85% with variable cystine levels depending on hydrolysis intensity. Its primary commercial purpose centers on supplying cost-effective protein and sulfur-containing amino acids to monogastric and aquatic animals where soybean meal or fishmeal economics prove prohibitive. Hydrolyzed feather meal occupies the premium tier in product type segmentation due to superior amino acid digestibility coefficients that command pricing premiums in shrimp and broiler diets. Aquaculture application pools are expanding fastest structurally, while poultry nutrition retains volume dominance as the mature baseline demand segment. Powder form leads current shipment volumes though granular grades are gaining traction in automated feed mill systems.
USDA and FDA jointly govern feather meal inclusion rates and labeling under the Federal Food, Drug, and Cosmetic Act, with state-level feed control officials conducting facility inspections that shape interstate commerce access. EPA regulations on rendering plant emissions and wastewater discharge create compliance cost differentials that favor larger, capital-intensive processors over regional operators. Feed manufacturers and integrators must monitor evolving FDA guidance on novel rendering technologies and their implications for Generally Recognized As Safe status determinations.
Market Dynamics
The EU Green Deal's circular bioeconomy mandates are redirecting poultry processing waste streams into regulated feed ingredient channels, compressing supply timelines and concentrating procurement among certified processors.
Growth Catalysts
- Fishmeal displacement in aquaculture:Vietnamese and Indonesian shrimp and tilapia producers are expanding hydrolyzed feather meal inclusion as marine protein costs escalate.
- EU Green Deal waste valorization:The circular bioeconomy framework creates regulatory pull for poultry byproduct upcycling into standardized feed inputs.
- Steam hydrolysis technology:Advanced thermal processing improves keratin digestibility coefficients, unlocking premium pricing in monogastric diets.
Market Restraints
- Energy cost volatility:Natural gas and electricity price spikes inflate rendering plant operating costs, squeezing regional processor margins.
- Supply concentration risk:North American rendering capacity clusters among vertically integrated poultry processors, limiting third-party sourcing options.
- Digestibility variability:Inconsistent hydrolysis intensity across batches creates amino acid coefficient uncertainty, constraining formulation precision.
Strategic Opportunities
- Indonesian aquaculture expansion:Export-oriented shrimp producers seek cost-competitive protein alternatives to secure EU and US market access.
- Pet food humanization:Premium pet food manufacturers are sourcing specialized steam-hydrolyzed grades for high-protein positioning.
- Automated feed mill integration:Granular feather meal grades compatible with pneumatic conveying systems open channel partnerships with integrated livestock operations.
Industry Challenges
- Skilled rendering technologist shortage:Specialized expertise in keratin hydrolysis optimization and quality control remains scarce outside major processing hubs.
- GRAS determination timelines:FDA review of novel rendering technologies for Generally Recognized As Safe status creates multi-year commercialization delays.
- Legacy batch system integration:Continuous hydrolysis reactor deployment requires costly retrofitting of existing rendering infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feather Meal Market |
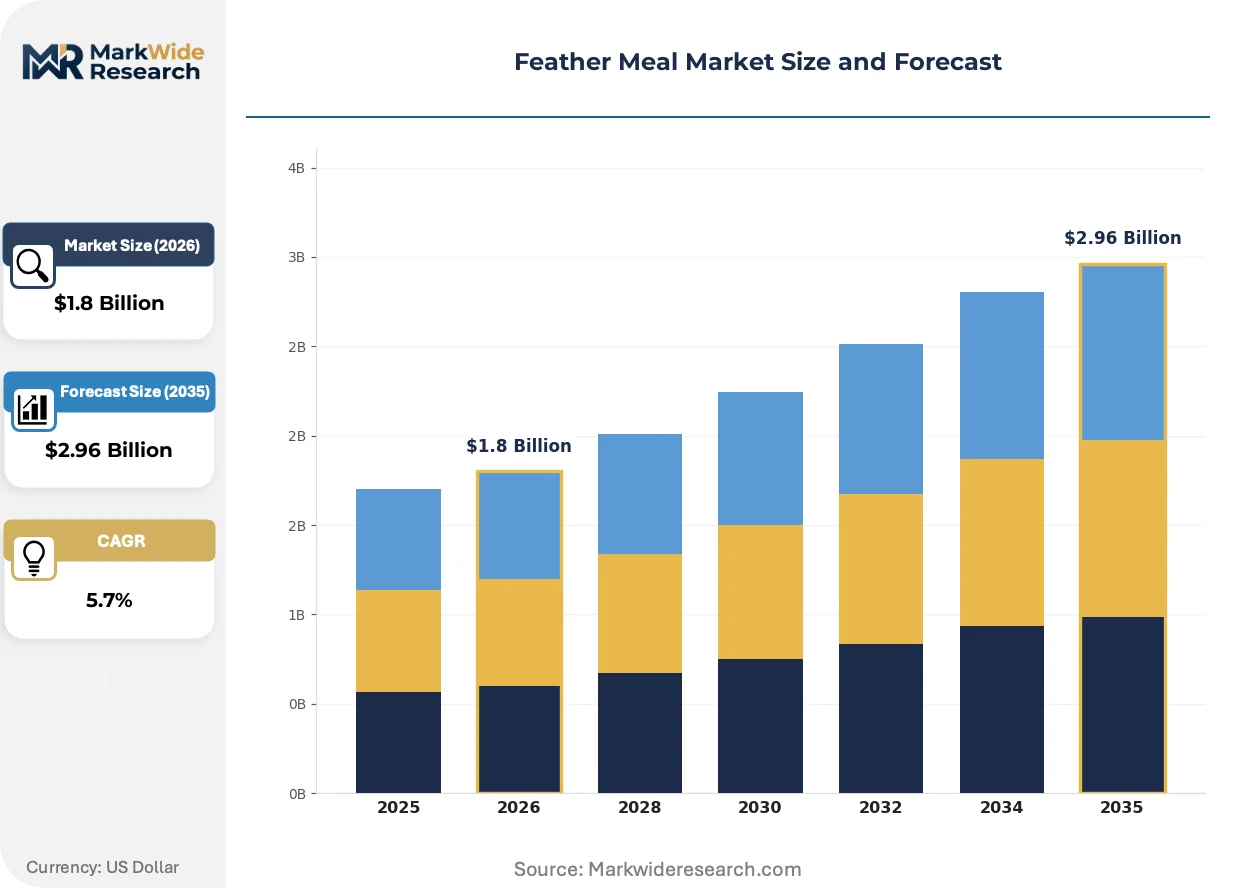
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Feather Meal, Conventional Feather Meal, Steam-Hydrolyzed Feather Meal, Feather Protein Concentrate End User: Animal Feed, Fertilizers, Pet Food, Aquaculture Application: Poultry Nutrition, Livestock Nutrition, Aquatic Nutrition, Organic Fertilizers Form: Powder, Granular, Flakes, Liquid |
| Companies Covered | Darling Ingredients, Tyson Foods, JG Pears, West Coast Reduction Ltd., Sanimax Industries Inc., Valley Proteins, Inc., FASA Group, Kleingarn Agrarprodukte, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feather Meal Market Emerging Trajectories
Processing technology convergence and regulatory pressure on circular resource use are compressing the gap between commodity rendering outputs and specialized feed ingredients. Three developments are restructuring competitive positioning.
Enzymatic pre-treatment systems are unifying protein extraction efficiency with energy consumption reduction. Southeast Asian aquaculture feed formulators are adopting hybrid thermal-enzymatic processes at pilot scale. This convergence is unifying cost structures across premium and standard hydrolysis grades, eroding historical price stratification.
REACH chemical safety registration in Europe is tightening traceability requirements for rendered proteins entering the feed chain. Poultry processors must now document contaminant screening protocols and chain-of-custody records. Aquaculture ingredient distributors serving EU export markets are prioritizing suppliers with verified REACH-compliant documentation systems.
Feed mill buyers are consolidating procurement around long-term offtake agreements with certified renderers. Spot market purchasing for hydrolyzed feather meal is contracting as integrators seek supply security. This concentration is most visible among Vietnam's vertically integrated shrimp producers locking in multi-year contracts with Indonesian rendering facilities.
Feather Meal Market Segmentation
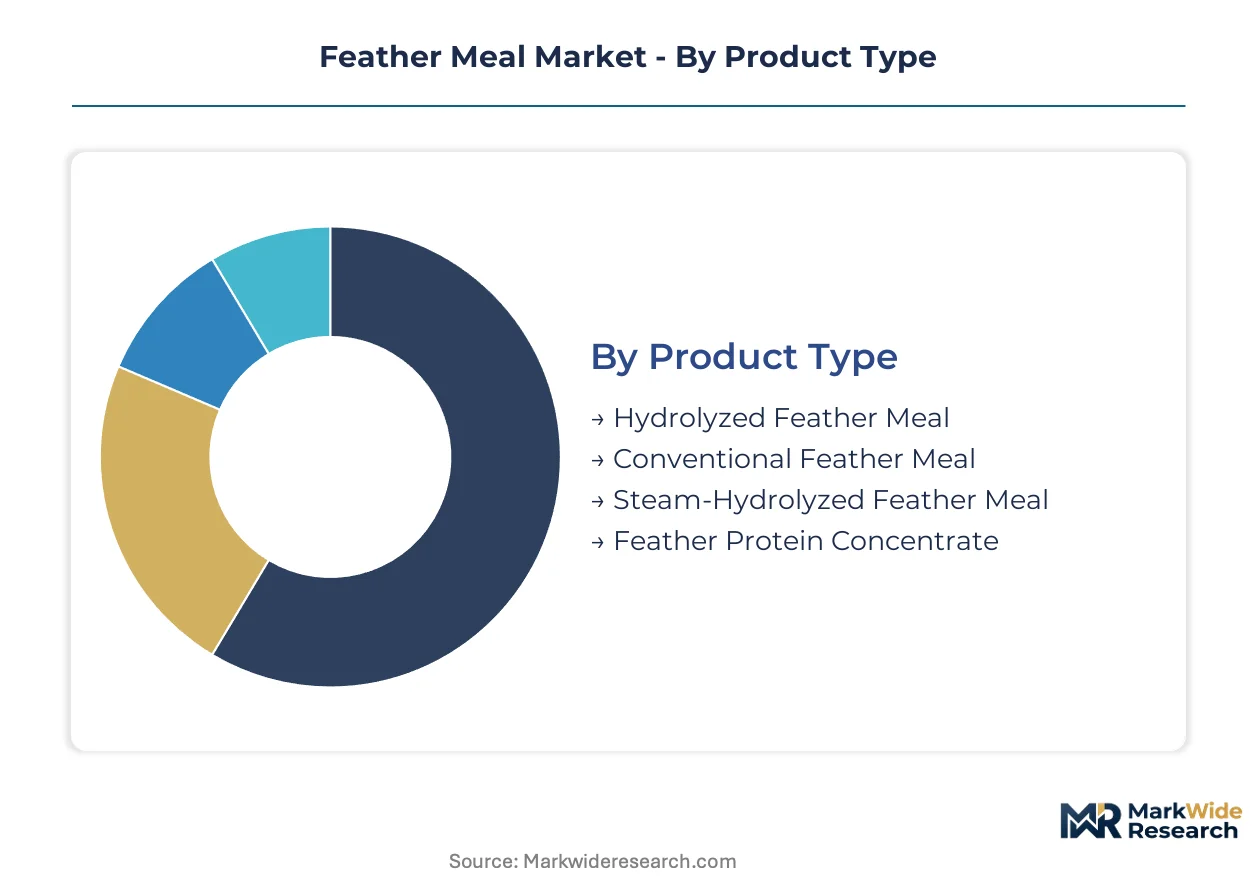
Feather meal segmentation reflects divergent processing intensities and end-use specifications that command distinct pricing tiers. Supply concentration among integrated poultry processors shapes which grades achieve scale economics versus specialty positioning.
Product Type:
Supply concentration among vertically integrated renderers favors capital-intensive hydrolysis technologies that achieve consistent keratin breakdown.
- Hydrolyzed Feather Meal:Heat and pressure processing breaks keratin into digestible amino acids with 80-85% crude protein content. Vietnamese shrimp feed formulators source this grade to replace fishmeal in export-oriented aquaculture operations where digestibility coefficients determine inclusion rates.
- Steam-Hydrolyzed Feather Meal:Advanced thermal processing achieves superior amino acid bioavailability through controlled steam injection. European pet food manufacturers pay premiums for this grade to support high-protein positioning in humanized product lines.
- Conventional Feather Meal:Standard rendering yields lower digestibility suitable for ruminant feed and fertilizer applications where amino acid precision matters less.
- Feather Protein Concentrate:Further refined isolates target specialized monogastric formulations requiring concentrated sulfur amino acid profiles.
Today's leader: Hydrolyzed Feather Meal. Tomorrow's challenger: Steam-Hydrolyzed Feather Meal.
End User:
Cost tier differentiation separates commodity protein buyers from premium segment purchasers willing to pay for certified supply chains.
- Animal Feed:Broiler and layer integrators constitute the volume baseline, sourcing hydrolyzed grades for sulfur amino acid supplementation in corn-soy diets.
- Aquaculture:Indonesian and Vietnamese shrimp producers represent the steepest expansion trajectory as marine protein costs drive alternative sourcing.
- Pet Food:Premium positioning demands specialized steam-hydrolyzed grades with documented contaminant screening for humanization trends.
- Fertilizers:Slow-release nitrogen applications accept conventional grades where protein content rather than amino acid profile drives purchasing.
Volume dominance: Animal Feed. Margin expansion: Aquaculture.
Application:
Maturity gradients separate established poultry nutrition from emerging aquatic feed formulations requiring precise amino acid balancing.
- Poultry Nutrition:Mature demand segment where hydrolyzed feather meal supplements methionine and cystine in broiler grower diets.
- Aquatic Nutrition:Shrimp and tilapia producers in Southeast Asia are expanding inclusion rates fastest as fishmeal displacement accelerates.
- Livestock Nutrition:Swine and ruminant applications favor cost-optimized conventional grades where digestibility requirements are less stringent.
- Organic Fertilizers:Niche positioning for feather meal in certified organic crop production systems.
Established base: Poultry Nutrition. Emerging pool: Aquatic Nutrition.
Form:
Customer type separation distinguishes automated feed mill operators from smaller compounders with manual handling capabilities.
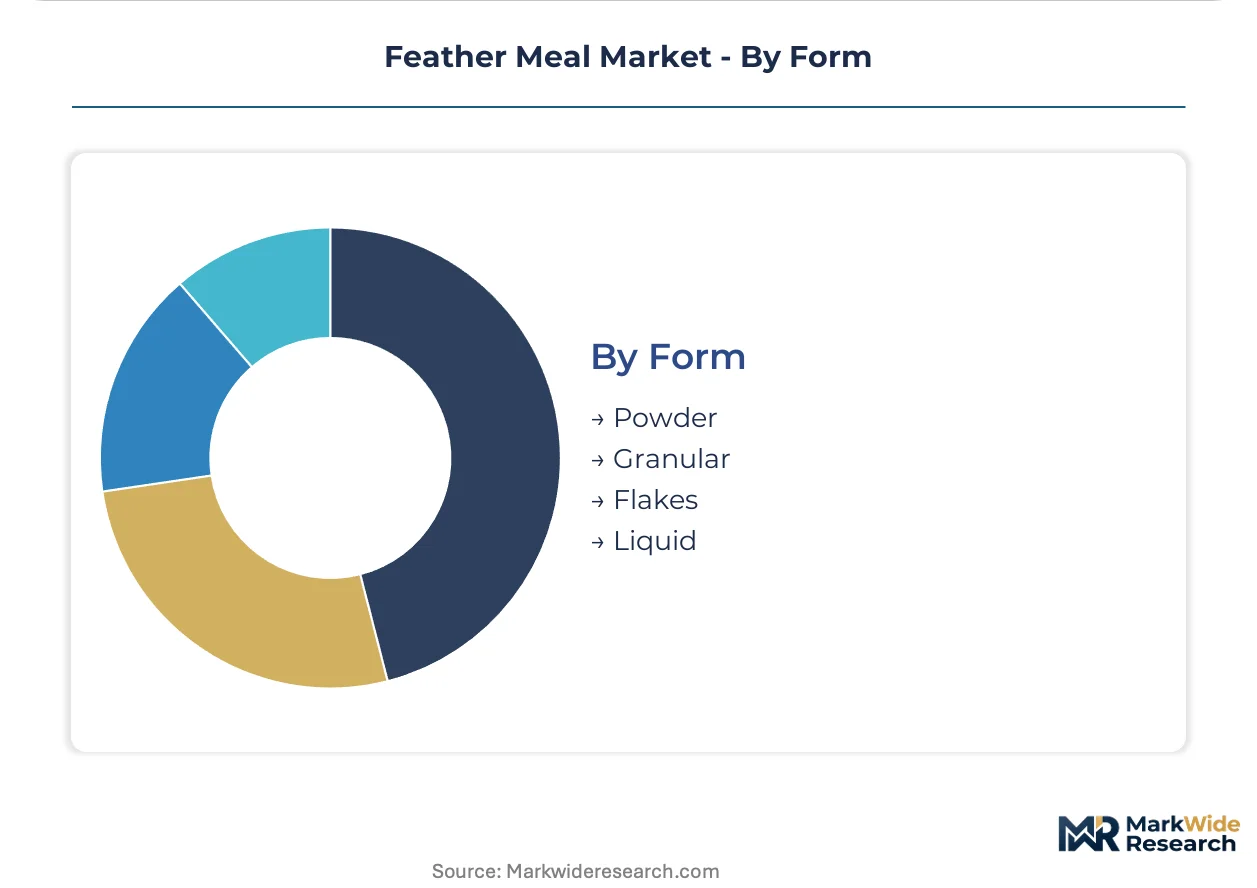
- Powder:Dominates current shipment volumes for standard feed mill incorporation, though dust handling challenges constrain some operations.
- Granular:Gaining traction among integrated livestock operations with pneumatic conveying systems that demand flowability.
- Flakes:Specialty form for specific aquaculture feed extrusion processes requiring particular particle geometry.
- Liquid:Emerging format for specialized industrial applications and certain fertilizer manufacturing processes.
Current standard: Powder. Automation enabler: Granular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting feather meal production toward jurisdictions with lower compliance costs for rendering emissions and wastewater discharge. Vietnam and Indonesia attract capacity expansion due to streamlined environmental permitting relative to EU and North American standards.
United States
Poultry integrators in Arkansas and Georgia drive demand for hydrolyzed feather meal as captive rendering volumes secure sulfur amino acid supply chains. EPA regulations on rendering plant emissions create capital barriers that favor Darling Ingredients and Tyson Foods with existing compliance infrastructure. The Southeast processing corridor concentrates capacity where integrated operations achieve scale economics.
Germany
REACH chemical safety registration tightens traceability requirements for rendered proteins entering EU feed channels. The EU Green Deal's circular bioeconomy mandates redirect poultry byproduct streams into regulated ingredient pathways. Bavarian rendering clusters adapt documentation systems to serve aquaculture exporters requiring verified contaminant screening.
Vietnam
Shrimp producers in the Mekong Delta expand hydrolyzed feather meal procurement to displace fishmeal in export-oriented aquaculture diets. The Ministry of Agriculture and Rural Development oversees feed ingredient standards that align with EU import requirements. Ho Chi Minh City-based feed compounders lock in multi-year offtake agreements with Indonesian rendering facilities.
Indonesia
Tilapia and shrimp operations in Java and Sumatra represent the steepest demand expansion trajectory for cost-competitive protein alternatives. National feed safety regulations administered by the Drug and Food Control Agency shape import substitution strategies. Surabaya rendering hubs scale steam-hydrolysis capacity to serve Vietnamese aquaculture procurement.
Canada
Health Canada and PMRA jointly govern rendered protein inclusion rates under the Feeds Act with provincial inspectors conducting facility audits. Alberta and Manitoba rendering operations supply North American aquaculture feed manufacturers seeking non-US sourcing options. Winnipeg-area processors invest in hydrolysis technology to capture premium pricing from monogastric feed formulators.
Feather Meal Market Vendor Landscape
North American producers anchor one tier; European specialists hold certification-driven positioning in premium aquaculture and pet food channels. The vendor base clusters around vertically integrated poultry processors with captive rendering volumes and independent regional operators serving fertilizer and commodity feed applications. Three archetypes dominate: integrated agribusiness conglomerates with backward control over protein refining, independent rendering specialists competing on hydrolysis technology, and aquaculture-focused ingredient distributors curating certified supply chains. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure long-term offtake agreements.
Among US-based integrators, Darling Ingredients and Tyson Foods exemplify the conglomerate archetype with in-house production of poultry byproduct streams. JG Pears occupies a position within the European specialist tier, representing certification-focused competitors serving premium aquaculture and pet food channels. These three companies illustrate how geographic origin and corporate structure map onto divergent strategic positioning in global protein markets.
| Leading Market Players |
|---|
| Darling Ingredients |
| Tyson Foods |
| JG Pears |
| West Coast Reduction Ltd. |
| Sanimax Industries Inc. |
| Valley Proteins, Inc. |
| FASA Group |
| Kleingarn Agrarprodukte |
| Alltech |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap renderers across the American Southeast anchor supply discipline through generational ownership structures that resist margin-eroding spot sales. Their patient capital matches poultry processor contract cycles, creating pricing stability that private-equity-rolled competitors sacrifice for quarterly returns. This ownership fragmentation concentrates bargaining power among vertically integrated conglomerates while tiering access for third-party formulators.
Pricing Analysis
Distributor margins in Vietnamese aquaculture channels absorb the steepest compression as feed compounders consolidate procurement around direct renderer relationships. Three-tier pricing structure across premium steam-hydrolyzed, standard hydrolyzed, and conventional grades separates EU-certified exporters from regional fertilizer suppliers. Pricing pressure stems from natural gas cost volatility inflating thermal processing economics. Shrimp producers in the Mekong Delta exhibit highest price sensitivity, while European pet food manufacturers tolerate premiums for REACH-documented supply chains.
Supply Chain Analysis
Freight cost differentials between Indonesian rendering hubs and Vietnamese aquaculture centers favor Surabaya-Jakarta corridor capacity expansion over distant North American sourcing. Raw material flows draw from poultry processing clusters in Arkansas, Georgia, and North Carolina, with secondary dependence on Brazilian and Thai feather waste exports. Single-source vulnerability concentrates in vertically integrated Tyson and Darling captive volumes. Distribution runs through long-term offtake agreements rather than spot markets, with Ho Chi Minh City compounders locking multi-year contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by Vietnamese shrimp producers substituting toward documented digestibility coefficients over commodity protein sourcing. Premium specification adherence now determines EU market access eligibility.
For Market Incumbents: Cement supply security through backward integration into Indonesian rendering capacity before regional environmental permitting tightens. Lock multi-year offtake agreements with Mekong Delta compounders facing fishmeal cost escalation. Prioritize steam-hydrolysis certification investment to defend margin position against enzymatic pre-treatment disruptors. For New Entrants and Emerging Players: Launch via toll-processing partnerships with underutilized Indonesian rendering assets serving Vietnamese aquaculture distributors. Target granular grade production for automated feed mill integration in Thailand's expanding poultry sector. Penetrate through documented REACH compliance services rather than commodity protein competition. For Investors and Strategic Acquirers: Valuations sit cheapest among independent Southeast Asian renderers lacking EU export certification infrastructure. Five-to-ten year viability hinges on circular bioeconomy regulatory alignment across multiple jurisdictions. Monitor FDA GRAS determination timelines for novel hydrolysis technologies as inflection signal for technology-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Steam-Hydrolysis Capacity Expansion | Surabaya facilities capture premium pricing from Vietnamese shrimp feed formulators. |
| Backward Integration into Rendering | Tyson and Darling secure captive feather meal supply against third-party sourcing risk. |
| REACH Compliance Documentation | European pet food manufacturers demand verified contaminant screening protocols. |
| Long-Term Offtake Agreements | Ho Chi Minh City compounders lock supply security for export-oriented aquaculture. |
| Enzymatic Pre-Treatment Piloting | Southeast Asian formulators test hybrid thermal-enzymatic cost convergence. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with rendering plant managers, aquaculture feed formulators, poultry procurement leads, and EU regulatory affairs specialists with secondary validation against USDA rendering statistics, Vietnamese Ministry of Agriculture feed import records, EPA emissions compliance databases, and REACH registration filings. Bottom-up capacity modeling and top-down protein substitution demand estimates were triangulated against trade flow data.
Segment-weighting across the projection horizon applied hydrolysis intensity tiers, end-use application splits, and geographic regulatory clusters to derive volume and value trajectories. CAGRs emerged from elasticity modeling of fishmeal price substitution triggers and poultry processing volume correlations. Forecast inputs incorporated EU Green Deal waste valorization mandates and Indonesian environmental permitting velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under energy price shock scenarios or FDA GRAS determination delays. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Upcycled Food Products Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Microalgae Based Products Market
Alternative Food Sources
Gluten Substitute Market
Alternative Food Sources
Insect Snacks Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Gluten Replacer Market
Alternative Food Sources
Dunaliella Salina Market
Alternative Food Sources
Asia-Pacific Meal Replacement Products Market
Alternative Food Sources
Mycoprotein Products Market