
 Fennel Powder Market | 2026-2036
Fennel Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Fennel Powder Market Analytics
Specialized agronomy expertise in fennel cultivation is bifurcating the competitive landscape into vertically integrated growers and commodity traders. McCormick and Company leverages its global procurement network to secure premium Indian and Egyptian fennel crops. Frontier Natural Products sustains its position through certified organic supply chains and direct farmer relationships. Mountain Rose Herbs differentiates via small-batch processing and stringent quality protocols for medicinal-grade powder.
Fennel powder consists of dried, ground fruits from Foeniculum vulgare, typically containing 1-6% essential oil by weight with anethole as the dominant aromatic compound, produced through sun-drying or mechanical dehydration followed by milling to 60-80 mesh particle size. The organic product type commands premium positioning as clean-label formulations displace conventional alternatives in North American and European retail. Within end users, the food industry anchors volume demand through seasoning and flavoring applications, while pharmaceutical buyers prioritize standardized essential oil content for digestive remedy formulations. Distribution through specialty stores and online channels is expanding fastest as direct-to-consumer spice brands bypass traditional wholesale tiers.
India's FSSAI mandates pesticide residue limits and labeling standards for powdered spices sold domestically, while the USDA organic seal governs export eligibility into United States retail channels. The EU's REACH framework and EFSA botanical safety assessments shape import requirements for fennel powder entering European food and supplement markets. Stakeholders must monitor evolving maximum residue limits across multiple jurisdictions and align procurement geography with certification portfolios to maintain market access.
Market Dynamics
Clean-label reformulation across processed food categories is compressing demand for synthetic flavor alternatives and elevating botanical powders with traceable provenance. This structural pull is redrawing procurement hierarchies and certification requirements for fennel powder suppliers.
Growth Catalysts
- EU organic retail mandates:Germany's organic supermarket chains now require batch-level traceability for spice inputs, accelerating certified fennel powder placement in private-label seasoning lines.
- Pharmaceutical standardization:Digestive health supplement manufacturers are specifying anethole content thresholds, creating specification-grade demand that commands premium positioning.
- India's PLI scheme for food processing:Domestic value-addition incentives are expanding mechanical dehydration capacity and reducing raw material export dependency.
Market Restraints
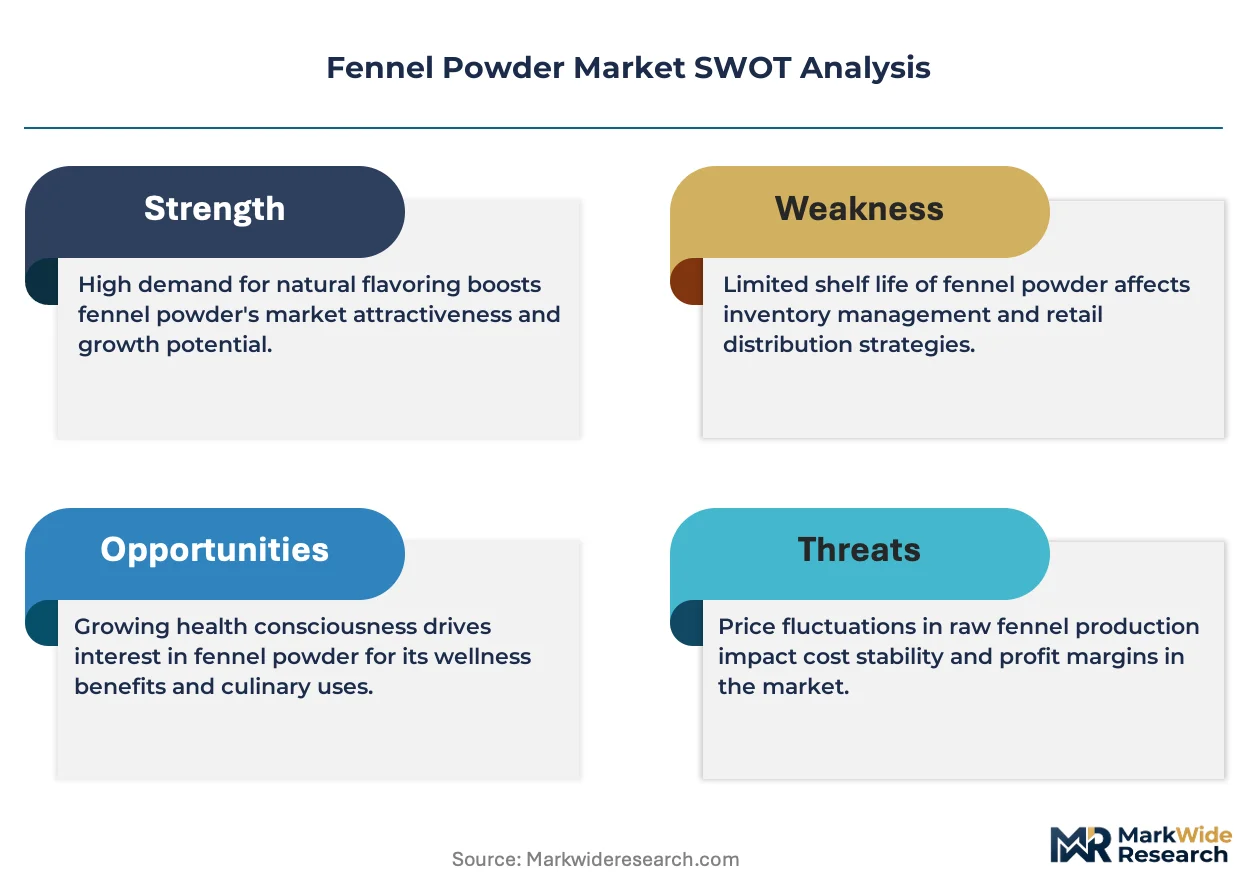
- Input cost volatility:Fennel seed prices fluctuate with monsoon reliability in Gujarat and Rajasthan, compressing processor margins during poor harvest cycles.
- Supply concentration risk:Premium organic cultivation clusters in Egypt's Nile Delta face climate vulnerability and limited alternative sourcing.
- Regulatory friction:REACH registration requirements for essential oil concentrates create compliance barriers for small-scale European importers.
Strategic Opportunities
- Underpenetrated North American medicinal use:Functional food brands in the United States are incorporating fennel powder into gut-health positioned products with limited domestic competition.
- Direct-to-consumer channel expansion:Specialty spice subscription services bypass wholesale tiers and capture full retail margin.
- Technology convergence:Near-infrared spectroscopy combined with blockchain verification enables real-time quality authentication for premium buyers.
Industry Challenges
- Agronomy skill scarcity:Specialized knowledge of organic fennel cultivation and post-harvest handling is concentrated among aging farmer networks in India and Turkey.
- Certification timeline compression:USDA organic and EU organic conversions require three-year transition periods that strain working capital for contract growers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fennel Powder Market |
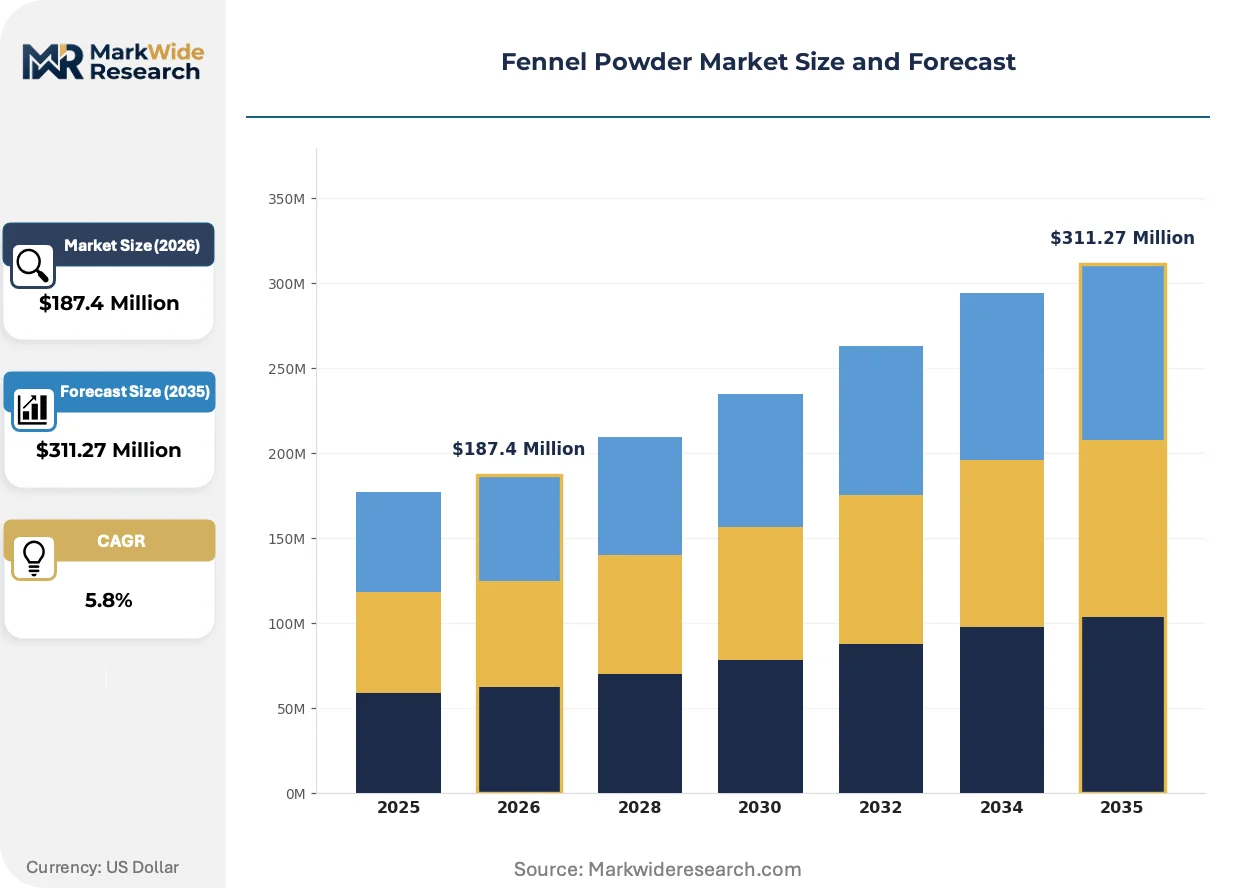
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Instant, Powdered End User: Food Industry, Pharmaceutical, Cosmetics, Others Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale Application: Seasoning, Herbal Remedies, Baking, Flavoring |
| Companies Covered | Mangalam Seeds, McCormick and Company, Frontier Natural Products, Herbs Egypt, Mountain Rose Herbs, Agrocrops, Ocean Overseas, Ambika Global, Steenbergs Organic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fennel Powder Market Evolving Landscape
Processing technology and verification systems are converging to reshape how fennel powder quality is assured and communicated. These shifts are elevating transparency from marketing claim to operational infrastructure.
Steam-treated fennel powder is supplanting conventional irradiated product in European organic supply chains. Premium spice brands in Germany and the Netherlands are adopting steam sterilization to meet retailer clean-label requirements. This thermal process preserves volatile oil integrity while eliminating microbial contamination risks that previously forced synthetic preservative use.
EFSA's evolving botanical safety assessments are tightening maximum residue limits for fennel powder entering supplement applications. The agency's 2023 revised guidance on pyrrolizidine alkaloids forced reformulation across digestive remedy portfolios. Manufacturers are responding by sourcing from controlled irrigation districts with documented crop rotation protocols.
Specialty stores and direct online channels are capturing share from traditional wholesale spice distributors. Direct-to-consumer brands in North America and Western Europe are building subscription models around single-origin fennel powder with harvest-date transparency. This disintermediation is most visible in United States coastal metro markets where consumers prioritize provenance verification over price convenience.
Fennel Powder Market Segmentation
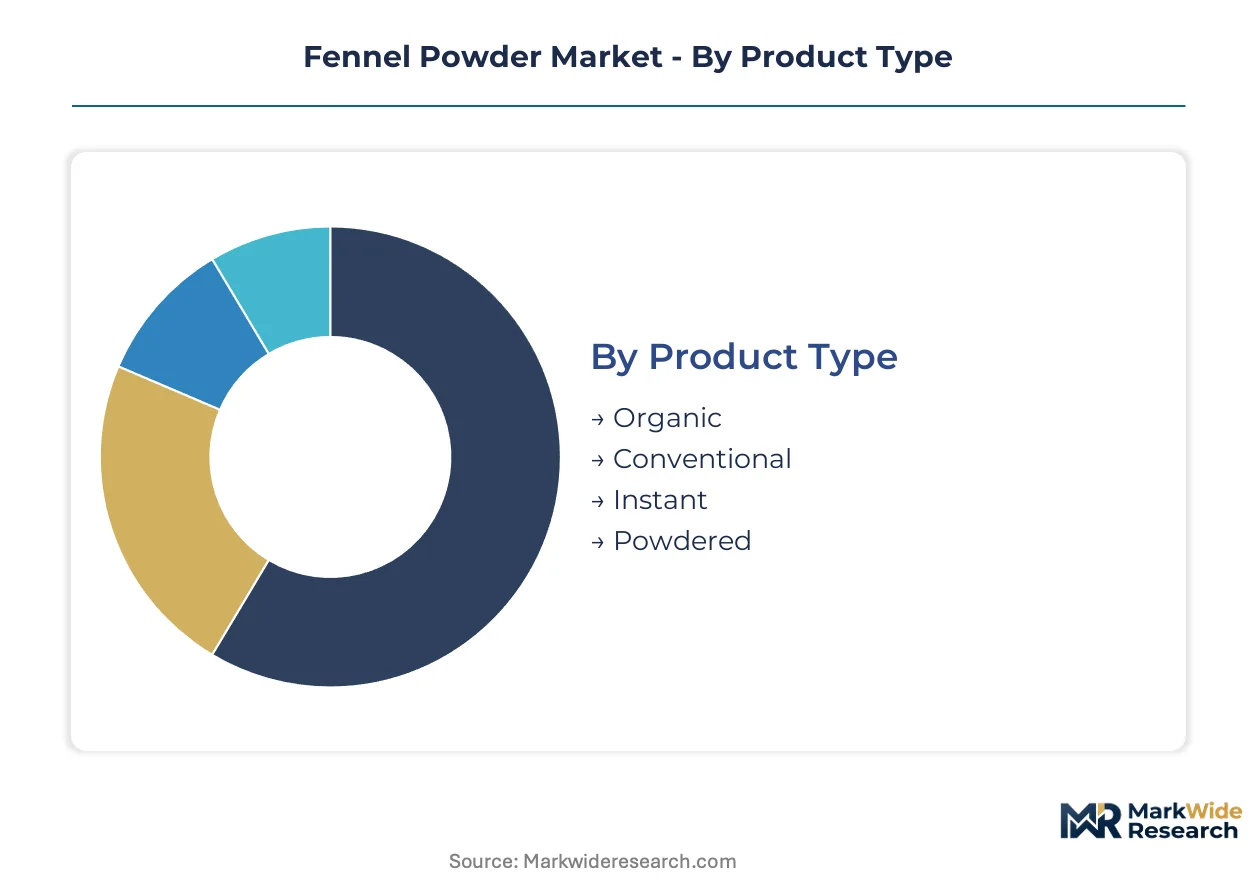
Segmentation in fennel powder markets separates commodity traders from premium-positioned suppliers. Certification grade, distribution channel selection, and end-use specification requirements determine margin capture and procurement hierarchy placement.
Product Type:
Margin pools concentrate in certified organic supply chains where three-year transition barriers limit supplier entry.
- Organic:USDA and EU organic seals command 20-40% price premiums over conventional alternatives. Germany's organic supermarket chains now mandate batch-level traceability, pulling Indian and Egyptian certified supply into private-label seasoning programs.
- Conventional:Sun-dried or mechanically dehydrated fruits with standard essential oil content of 1-4% by weight. Volume demand from industrial food processors in India and Turkey prioritizes cost efficiency over provenance documentation.
- Instant:Spray-dried extracts designed for rapid dissolution in beverage applications. Functional drink manufacturers in North America specify standardized anethole thresholds.
- Powdered:Standard 60-80 mesh milling for general seasoning use. Commodity trading houses in Gujarat and Rajasthan dominate procurement.
The dominant share belongs to Conventional, while Organic is closing the gap fastest.
End User:
Application-driven specification requirements split procurement between bulk commodity buyers and precision-grade pharmaceutical purchasers.
- Food Industry:Seasoning blend manufacturers represent volume demand concentration. Clean-label reformulation across European processed food categories is elevating traceable botanical powders over synthetic flavor alternatives.
- Pharmaceutical:Digestive remedy formulators specify standardized essential oil content of 4-6% anethole. EFSA's revised pyrrolizidine alkaloid guidance forced sourcing shifts to controlled irrigation districts with documented crop rotation.
- Cosmetics:Fragrance and personal care applications utilize fennel powder for natural positioning. Formulators prioritize steam-sterilized material to eliminate microbial contamination risks.
- Others:Veterinary feed and aromatherapy niche applications. Limited specification requirements favor commodity-grade supply.
Food Industry retains volume leadership, though Pharmaceutical specifications yield superior unit economics.
Distribution Channel:
Channel selection determines margin capture, with disintermediation enabling direct-to-consumer brands to bypass wholesale tier compression.
- Online:Subscription spice services with harvest-date transparency. Coastal metro markets in the United States prioritize provenance verification over price convenience.
- Supermarkets:Mass retail placement requires scale and private-label manufacturing capacity. German organic chains now require steam-treated product to meet clean-label mandates.
- Specialty Stores:Independent spice merchants and natural food cooperatives. Curated single-origin positioning supports premium pricing.
- Wholesale:Traditional spice distributors serving industrial food processors. Margin compression intensifies with commodity trading concentration.
Wholesale channels handle the greatest volume, yet Online expansion is climbing the fastest.
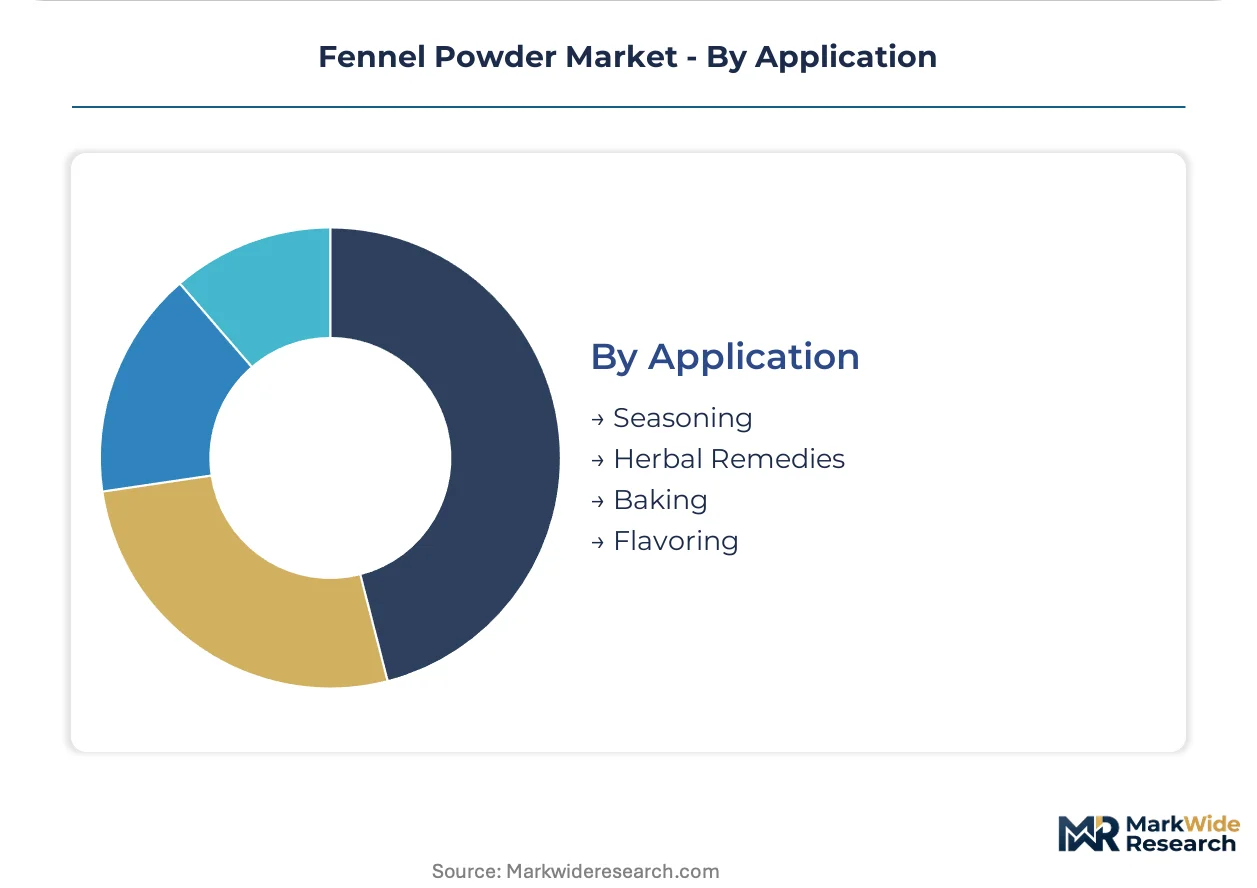
Application:
Functional use cases separate commodity seasoning demand from specification-grade therapeutic applications.
- Seasoning:Blended spice formulations for meat, soup, and sauce applications. European clean-label mandates are displacing synthetic flavor alternatives.
- Herbal Remedies:Digestive health supplements with standardized anethole content. EMA and FDA botanical safety assessments govern formulation requirements.
- Baking:Artisan bread and confectionery flavoring. Lower essential oil thresholds acceptable for heat-stable applications.
- Flavoring:Beverage and dairy product incorporation. Instant-dissolving extracts preferred for liquid applications.
Seasoning anchors volume consumption, while Herbal Remedies demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI's pesticide residue mandates and India's PLI scheme for food processing anchor the dominant geography, while EFSA's botanical safety assessments and Germany's organic retail traceability requirements reshape import flows across Western Europe.
India
Gujarat and Rajasthan cultivation clusters supply the bulk of global fennel seed output, with mechanical dehydration capacity expanding under PLI scheme incentives. FSSAI mandates pesticide residue limits and labeling standards for domestic powdered spice sales. Processing concentration in Unjha and Rajkot reduces raw material export dependency as value-addition infrastructure scales.
Germany
Organic supermarket chains now require batch-level traceability for spice inputs, pulling certified fennel powder into private-label seasoning programs. EFSA's REACH framework and revised pyrrolizidine alkaloid guidance govern import eligibility for supplement applications. Hamburg and Frankfurt distribution hubs handle specification-grade pharmaceutical procurement with documented crop rotation protocols.
United States
Functional food brands incorporate fennel powder into gut-health positioned products with limited domestic cultivation competition. USDA organic seal governs retail channel eligibility, while FDA botanical safety assessments shape supplement formulation requirements. Coastal metro markets in California and New York prioritize provenance verification through direct-to-consumer subscription channels.
Egypt
Nile Delta organic cultivation clusters face climate vulnerability and limited alternative sourcing for premium spice buyers. EFSA import requirements and REACH registration obligations create compliance barriers for European market access. Alexandria processing facilities concentrate steam-sterilization capacity for clean-label European supply chains.
Netherlands
Amsterdam and Rotterdam serve as consolidation points for Indian and Egyptian organic supply entering European distribution. EFSA's evolving maximum residue limits force alignment of procurement geography with certification portfolios. Specialty spice importers leverage the country's logistics infrastructure to bypass traditional wholesale tiers.
Fennel Powder Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with procurement network scale separating global seasoning houses from regional organic traders. The competitive landscape bifurcates between vertically integrated growers with captive cultivation and commodity traders relying on spot market sourcing. Three archetypes dominate: global procurement networks securing premium crops, certified organic specialists with direct farmer relationships, and small-batch processors emphasizing medicinal-grade protocols. Dominant competitive moves include backward integration into dehydration capacity and technology convergence around blockchain verification systems.
Among integrated seasoning houses, McCormick and Company leverages global procurement networks to secure premium Indian and Egyptian fennel crops, representing the scale-driven archetype. Frontier Natural Products and Mountain Rose Herbs occupy positions within the certified organic and small-batch specialist tiers respectively, with the former sustaining market presence through direct farmer relationships and the latter differentiating via stringent quality protocols for medicinal-grade powder. These three exemplify how certification grade and processing scale determine procurement hierarchy placement.
| Leading Market Players |
|---|
| Mangalam Seeds |
| McCormick and Company |
| Frontier Natural Products |
| Herbs Egypt |
| Mountain Rose Herbs |
| Agrocrops |
| Ocean Overseas |
| Ambika Global |
| Steenbergs Organic |
| Others |
Value Network & Pricing Analysis
Steam sterilization replacing irradiated treatment in European organic channels is simultaneously shifting procurement geography toward Egypt and India while compressing margins for processors lacking certified dehydration capacity. This substitution dynamic elevates batch-level traceability requirements and redistributes pricing power toward vertically integrated growers with captive steam-treatment facilities.
Pricing Analysis
Indian conventional fennel powder trades at substantial discounts to German organic retail channels, with geographic spreads reflecting certification grade and provenance documentation intensity. Three-tier pricing structure across organic-certified, conventional-mechanical, and sun-dried commodity levels captures value from traceability investments. Cost compression in conventional tiers is intensifying because Gujarat monsoon volatility feeds raw material price swings. Industrial food processors in Turkey and India exhibit highest price sensitivity, while pharmaceutical buyers specifying anethole thresholds accept premium positioning.
Supply Chain Analysis
Strategic stockpiling dominates procurement behavior among European seasoning houses facing EFSA's evolving residue limits, contrasting with just-in-time preferences among North American functional food brands. Supply concentrates in India's Gujarat and Rajasthan cultivation belts, with Egyptian Nile Delta organic clusters serving premium European demand. Processing draws from fennel seed, natural gas for dehydration, and steam-treatment equipment inputs. Single-source vulnerability concentrates in Egypt's climate-exposed organic zones. Distribution runs through Amsterdam and Rotterdam consolidation hubs before final-mile placement in German supermarket chains and United States direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service offerings for smallholder transition support represent a faster-expanding recurring layer than commodity powder trading, creating attach opportunities around three-year organic conversion programs and blockchain verification subscriptions.
For Market Incumbents: Fortify backward integration into mechanical dehydration capacity in Gujarat and Rajasthan to secure margin capture as PLI scheme incentives attract new processing entrants. Deepen direct farmer relationships in Egypt's Nile Delta to defend against climate-driven supply disruption. Prioritize steam-sterilization certification investment to meet German supermarket chain mandates. For New Entrants and Emerging Players: Differentiate on single-origin harvest-date transparency for United States coastal metro subscription channels where provenance verification commands premium positioning. Target underpenetrated North American pharmaceutical-grade specifications with anethole-standardized product. Pursue white-label manufacturing partnerships with direct-to-consumer spice brands bypassing wholesale tiers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors certified organic specialists with documented farmer networks and captive processing infrastructure. Long-term viability hinges on regulatory alignment across REACH, USDA organic, and FSSAI jurisdictions. Acquisition focus should center on Indian processors with PLI scheme qualification and Egyptian organic traders with established European retail relationships. Watch EFSA maximum residue limit revisions as inflection indicator for sourcing geography shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dehydration Capacity | PLI scheme incentives in Gujarat reduce raw material export dependency for Indian processors. |
| Organic Certification Investment | USDA and EU organic seals unlock 20-40% price premiums in German supermarket chains. |
| Steam Sterilization Adoption | EFSA botanical safety assessments displace irradiated product in European clean-label supply chains. |
| Blockchain Verification Deployment | Near-infrared spectroscopy integration enables real-time quality authentication for pharmaceutical buyers. |
| Direct-to-Consumer Channel Expansion | Subscription models bypass wholesale margin compression in United States coastal metro markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with spice processing executives, organic certification officers, and pharmaceutical procurement managers; and secondary validation through FSSAI regulatory filings, EFSA safety assessments, USDA organic certification databases, and customs trade records. Bottom-up volume modeling triangulated against top-down value estimates derived from PLI scheme disbursement data and European organic retail audit sources.
Across the projection horizon, the analytical framework segmented volume and value outputs by certification grade, end-use specification intensity, distribution channel tier, and regional regulatory cluster. CAGRs were computed from annualized growth trajectories anchored in disclosed processing capacity expansions and import flow documentation. Forecast inputs incorporated monsoon reliability indices for Gujarat cultivation belts and EFSA guidance revision timelines for pyrrolizidine alkaloid thresholds.
Forecasts assume regulatory continuity in FSSAI pesticide residue regimes, USDA organic certification standards, and REACH registration requirements; material policy shifts would require re-modeling. Revision becomes warranted when EFSA maximum residue limit adjustments or PLI scheme modifications cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Africa Spice and Herb Extracts Market
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
Europe Seasoning and Spices Market
Spices and Seasonings
Europe Spice and Herb Extracts Market
Spices and Seasonings
Cardamom Oil Market
Spices and Seasonings
Malaysia Spices and Seasonings Market
Spices and Seasonings
Global Spices and Stimulants Market
Spices and Seasonings
Ginger Oil Market
Spices and Seasonings
Middle East and Africa Food Micronized Salt Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Lemon Salt Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
Coleus and Turmeric Market
Spices and Seasonings
White Pepper Market