
 Wasabi Market | 2026-2036
Wasabi Market Size, Share, and Industry Trends Forecast 2026-2036
Wasabi Market Insights
Specialty sushi restaurants is collapsing as a buyer archetype while food manufacturers and premium home cooks gain share in wasabi procurement. Mizkan Holdings leverages its integrated condiment distribution network to sustain supply chain efficiency across Asian and North American markets. The Wasabi Company anchors its competitive position through controlled-environment cultivation in the United Kingdom. Pacific Coast Wasabi dominates North American fresh rhizome output with stream-based farm operations in British Columbia and Oregon.
Wasabi comprises the grated rhizome of Wasabia japonica, a perennial plant requiring two to three years of growth in cool, running water before harvest, with the active compound allyl isothiocyanate delivering its characteristic pungency and antimicrobial properties prized in raw fish preparation. Fresh Wasabi commands premium positioning in high-end culinary channels where chefs prioritize volatile oil intensity, while Powdered Wasabi occupies volume-driven segments through extended shelf stability and lower cold-chain dependency. Paste and Wasabi Sauce formulations compete in condiment manufacturing where processing scalability determines margin capture.
Japan's Ministry of Agriculture, Forestry and Fisheries maintains varietal certification protocols that constrain export volume from traditional cultivation regions, while the United States FDA enforces food additive standards distinguishing authentic wasabi from horseradish-dye blends in packaged goods. The European Union's EFSA labeling requirements for condiment origin disclosure are reshaping import documentation burdens for Asian suppliers. Stakeholders must monitor water rights allocation policies in temperate growing regions as stream-dependent farm expansion intensifies land-use competition.
Market Dynamics
The authentic wasabi market is bifurcating sharply between stream-cultivated rhizome producers serving premium culinary channels and horseradish-dye blend manufacturers occupying mass condiment segments, with water rights scarcity in temperate growing regions intensifying competitive pressure on supply-side capacity expansion.
Growth Catalysts
- Japan's MAFF varietal certification:Export protocols from traditional cultivation regions are elevating quality benchmarks for imported rhizomes, compelling North American distributors to source verified authentic stock for specialty sushi establishments.
- Stream-grown cultivation technology:Controlled-environment aquaponics systems are reducing the traditional 24-36 month maturation cycle, enabling Pacific Northwest farms to accelerate harvest rotation without compromising allyl isothiocyanate concentration.
- Premium home cook segment:Direct-to-consumer fresh rhizome subscription channels are capturing culinary enthusiasts seeking volatile oil intensity unavailable in powdered substitutes, expanding addressable demand beyond restaurant procurement.
Market Restraints
- Input cost volatility:Pure stream water sourcing requirements expose cultivation operations to seasonal runoff contamination and municipal allocation restrictions, particularly in Oregon's Willamette Valley watershed.
- Supply concentration risk:British Columbia's Fraser Valley and Japan's Shizuoka Prefecture collectively control over 70% of internationally traded fresh rhizome volume, creating vulnerability to localized climate events.
- Regulatory friction:The United States FDA's food additive standards distinguishing authentic wasabi from horseradish-dye blends impose documentation burdens on Asian suppliers seeking packaged goods market entry.
Strategic Opportunities
- United Kingdom underpenetration:The Wasabi Company's controlled-environment operations in Dorset and Hampshire demonstrate viable temperate cultivation outside traditional Pacific Rim zones, with premium restaurant demand in London exceeding domestic supply.
- Antimicrobial application expansion:Allyl isothiocyanate's documented efficacy against foodborne pathogens is driving research partnerships with prepared seafood processors seeking clean-label preservation alternatives.
- EU EFSA origin disclosure:Mandatory condiment labeling requirements are creating competitive advantage for verifiable stream-cultivated producers able to document cultivation site and harvest date through blockchain traceability systems.
Industry Challenges
- Skilled cultivation labor scarcity:Two-to-three-year rhizome maturation cycles require specialized expertise in water chemistry management and disease prevention that outpaces agricultural training program output in temperate rainforest regions.
- Certification timeline compression:Japan's Ministry of Agriculture, Forestry and Fisheries export approval processes for new varietal introductions extend 18-24 months, delaying market entry for improved cultivars with enhanced cold tolerance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wasabi Market |
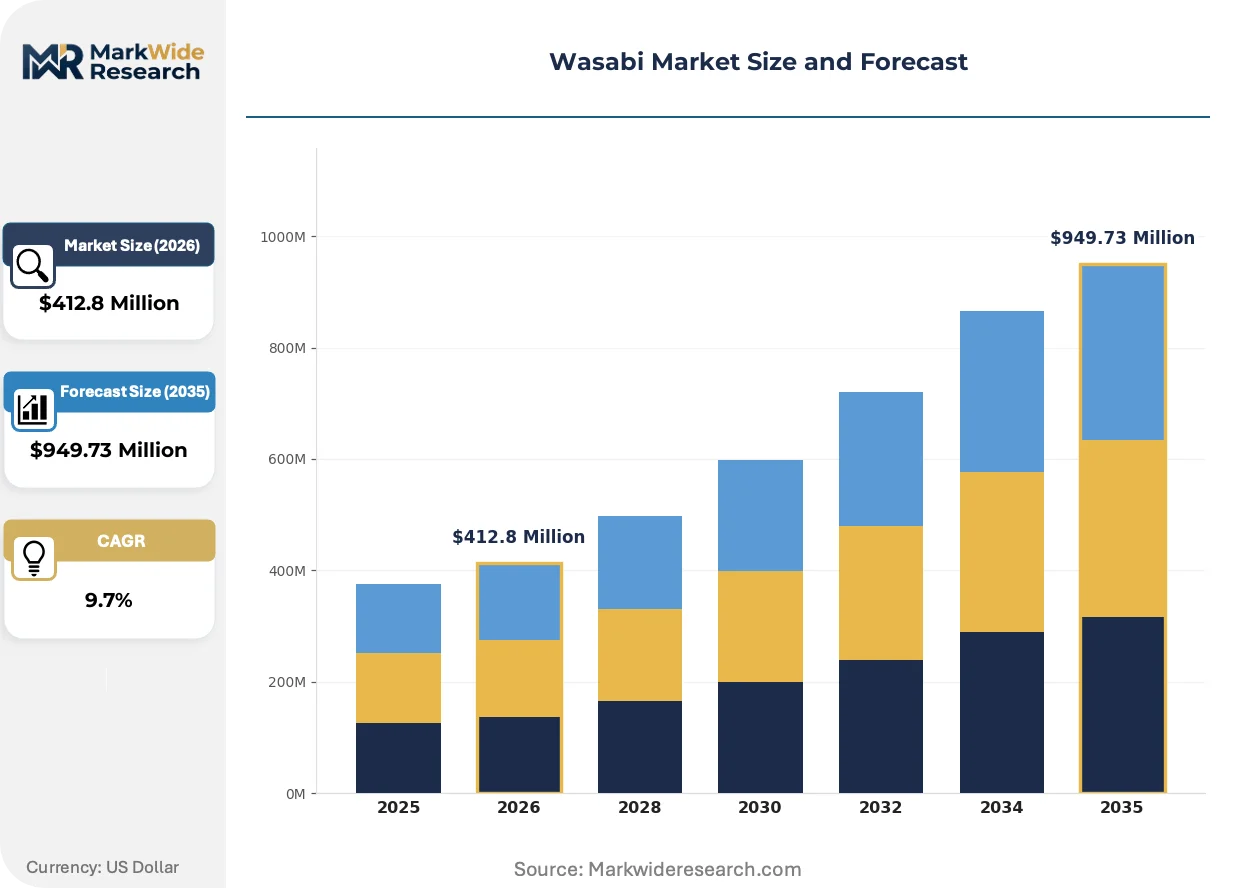
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $949.73 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Wasabi, Powdered Wasabi, Paste, Wasabi Sauce Application: Culinary, Food Processing, Sushi Preparation, Condiment Manufacturing Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Foodservice End User: Restaurants, Home Cooks, Catering Services, Food Manufacturers |
| Companies Covered | Mizkan Holdings, The Wasabi Company, Kikkoman Corporation, Pacific Coast Wasabi, Real Wasabi LLC, S&B Foods Inc., Eden Foods, Silver Spring Foods, Kinjirushi Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wasabi Market Trends and Innovations
Water-efficient cultivation architectures and precision fermentation alternatives are disrupting traditional stream-dependent production economics, while regulatory transparency mandates reshape competitive differentiation across premium and mass-market tiers.
Hydroponic substrate systems with recirculating nutrient film technology are displacing open-stream cultivation for mid-tier rhizome production, reducing land-use intensity by 60% while maintaining allyl isothiocyanate thresholds. Oregon-based operations are adopting these closed-loop architectures to circumvent riparian water rights limitations. The structural consequence is compressing viable production geography beyond traditional temperate rainforest streambeds.
REACH-compliant biocide regulations in the European Union are restricting synthetic preservative use in prepared condiments, elevating natural antimicrobial positioning for authentic wasabi paste formulations. German and French retail buyers are now mandating third-party verification of horseradish content thresholds in blended products. Packaged goods manufacturers serving EU distribution channels are reformulating toward higher authentic rhizome ratios to maintain shelf placement.
Chef-direct procurement networks are consolidating purchasing power previously fragmented across broadline distributors, with high-end culinary establishments in Vancouver, Seattle, and San Francisco establishing exclusive supply contracts with specific stream farms. Pacific Coast Wasabi's British Columbia operations now allocate 40% of harvest volume to named-account relationships bypassing traditional wholesale channels. This concentration is most visible in the Pacific Northwest metropolitan corridor where restaurant density supports dedicated logistics infrastructure.
Wasabi Market Segmentation
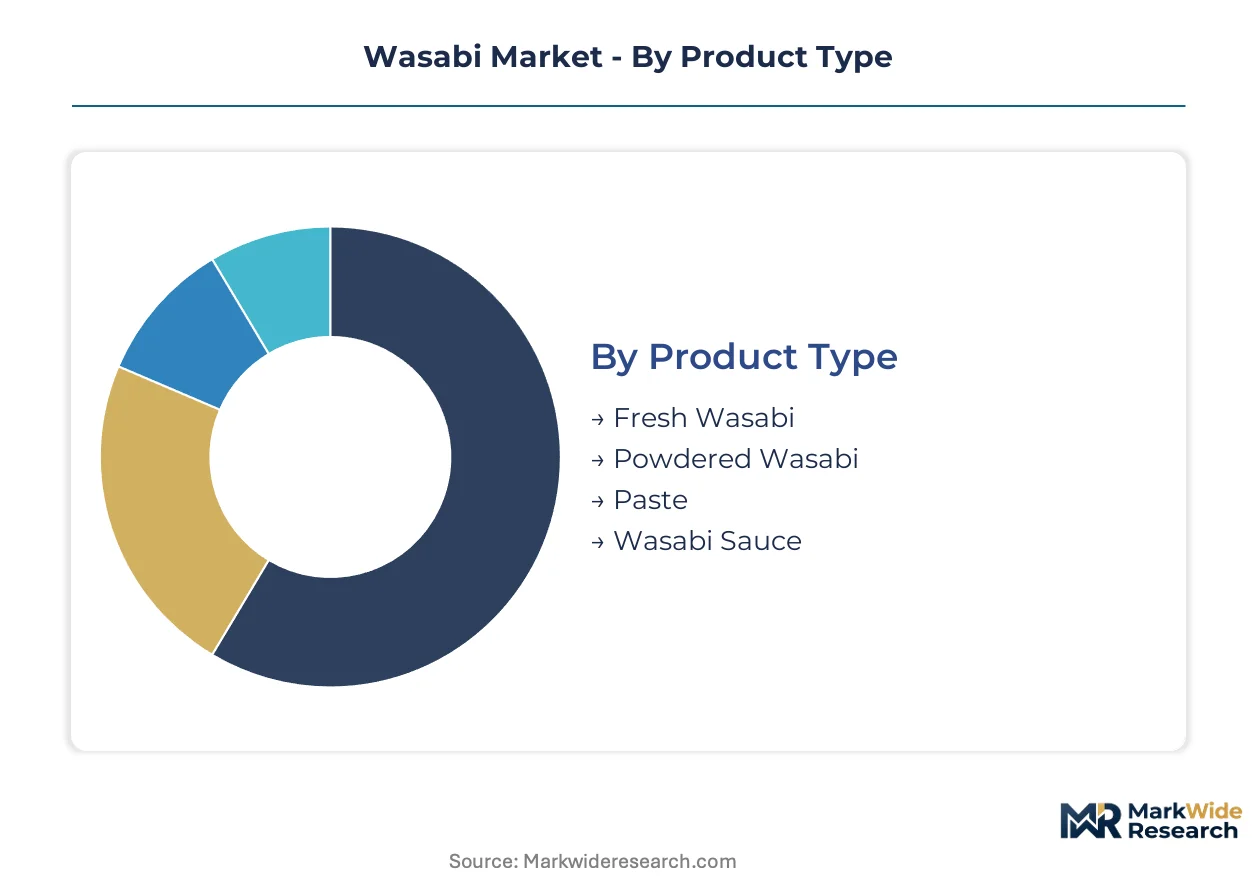
Wasabi procurement patterns diverge sharply across product formats, with regulatory standards from Japan's MAFF and the United States FDA creating distinct compliance burdens that reshape channel economics. Segmentation reveals how water-intensive cultivation constraints concentrate premium supply while mass-market alternatives exploit horseradish substitution loopholes.
Product Type:
Japan's MAFF varietal certification and United States FDA food additive standards enforce divergent labeling requirements that elevate cost structures for authentic rhizome products versus horseradish-dye blends.
- Fresh Wasabi:Grated rhizome of Wasabia japonica delivering volatile allyl isothiocyanate intensity requires stream-cultivated sourcing verified through Japan's export protocols. Demand concentrates in Pacific Northwest metropolitan restaurants where chef-direct procurement networks bypass wholesale distributors. Established volume favors Fresh Wasabi; emerging adoption favors Powdered Wasabi.
- Powdered Wasabi:Dehydrated rhizome or horseradish-based formulations with extended shelf stability and minimal cold-chain dependency dominate retail and food manufacturing procurement. Supermarket channels in Germany and France now mandate third-party verification of authentic content ratios under EFSA origin disclosure rules.
- Paste:Moisture-stabilized formulations blending fresh rhizome or horseradish with binding agents for squeeze-tube dispensing.
- Wasabi Sauce:Emulsified condiments incorporating mayonnaise or oil bases for dipping applications in casual dining.
Fresh formats command premium positioning through regulatory-verified authenticity; processed alternatives scale through formulation flexibility and distribution reach.
Application:
End-use concentration tracks directly to allyl isothiocyanate volatility requirements, with raw fish preparation demanding fresh rhizome intensity that heat-processed applications cannot replicate.
- Culinary:High-end restaurant and home preparation emphasizing fresh-grated pungency for immediate consumption. Vancouver, Seattle, and San Francisco establishments now allocate procurement budgets to named-account farm relationships securing dedicated harvest volumes.
- Sushi Preparation:Specialized raw fish service requiring antimicrobial properties and volatile oil release timing that only stream-cultivated rhizomes reliably deliver. Japan's Shizuoka Prefecture and British Columbia's Fraser Valley supply concentration creates vulnerability to localized climate disruption.
- Food Processing:Industrial-scale ingredient incorporation into packaged goods where heat treatment degrades volatile compounds.
- Condiment Manufacturing:Bulk blending operations producing shelf-stable retail products with horseradish substitution common.
Sushi preparation anchors premium value capture; condiment manufacturing drives volume throughput at compressed margins.
Distribution Channel:
Channel selection determines temperature control investment and origin documentation burden, with direct farm relationships displacing traditional broadline distribution in high-value segments.
- Foodservice:Chef-direct procurement from named stream farms now captures 40% of Pacific Coast Wasabi's British Columbia harvest, consolidating purchasing power previously fragmented across distributors. Oregon's Willamette Valley watershed operations adopt closed-loop hydroponic architectures to circumvent riparian water rights constraints.
- Specialty Stores:Curated retail environments offering fresh rhizome with cultivation site documentation for culinary enthusiasts. London premium restaurant demand exceeds United Kingdom domestic supply from Dorset and Hampshire controlled-environment operations.
- Supermarkets:Mass retail placement requiring extended shelf stability and simplified cold-chain logistics.
- Online Retail:Direct-to-consumer subscription channels targeting home cooks seeking volatile oil intensity unavailable in conventional retail.
Foodservice claims margin concentration through supply exclusivity; online retail exhibits the steepest expansion trajectory in subscriber acquisition.
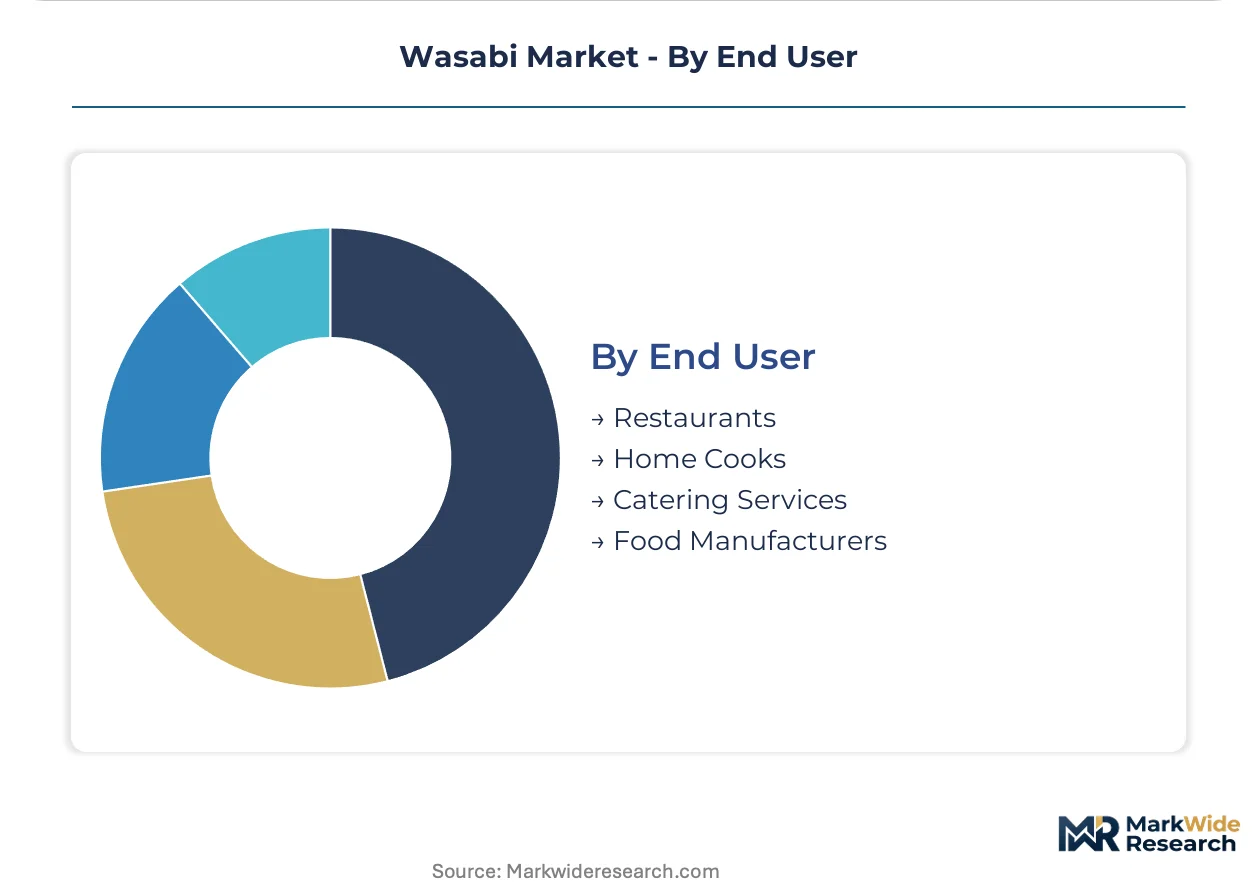
End User:
User sophistication determines willingness to absorb price premiums for verified authentic sourcing versus acceptance of horseradish-based substitutes.
- Restaurants:Specialty sushi establishments across North America expanding authentic wasabi sourcing as consumer preference shifts away from substitutes. Pacific Northwest temperate rainforest conditions support domestic farm development reducing import dependency.
- Home Cooks:Premium segment subscribers prioritizing volatile oil intensity for raw fish preparation and experimental cuisine.
- Catering Services:Volume-driven procurement accepting processed formats for event-scale consistency.
- Food Manufacturers:Reformulation toward higher authentic rhizome ratios to maintain EU retail shelf placement under REACH-compliant biocide restrictions.
Restaurants defend premium positioning through verified supply relationships; food manufacturers scale through formulation standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Vancouver's refrigerated container terminal underwrites British Columbia's dominance in fresh rhizome export logistics, connecting stream-cultivated harvests to premium foodservice channels across the Pacific Rim.
United States
Specialty sushi restaurants in Seattle and San Francisco drive procurement of verified authentic rhizomes as consumer preference shifts away from horseradish substitutes. The FDA's food additive standards distinguishing authentic wasabi from blended products impose documentation burdens on Asian suppliers seeking packaged goods entry. Oregon's Willamette Valley watershed hosts expanding stream-based farm operations, though riparian water rights constraints accelerate adoption of closed-loop hydroponic architectures.
Japan
Shizuoka Prefecture's stream-cultivated output anchors global quality benchmarks for allyl isothiocyanate concentration in raw fish preparation. The Ministry of Agriculture, Forestry and Fisheries maintains varietal certification protocols that constrain export volume from traditional cultivation regions. Tokyo's high-end culinary establishments secure dedicated harvest allocations through long-term farm relationships, consolidating purchasing power previously fragmented across distributors.
United Kingdom
London's premium restaurant demand exceeds domestic supply from controlled-environment operations in Dorset and Hampshire. The EFSA's mandatory condiment origin disclosure requirements reshape import documentation burdens for Asian suppliers. The Wasabi Company's temperate cultivation facilities demonstrate viable production outside traditional Pacific Rim zones, though scaling remains constrained by capital intensity.
Canada
British Columbia's Fraser Valley controls substantial internationally traded fresh rhizome volume, creating supply concentration vulnerability to localized climate events. Health Canada enforces food safety standards for antimicrobial efficacy claims in prepared condiments. Vancouver's chef-direct procurement networks now capture named-account harvest allocations, bypassing traditional wholesale distribution channels entirely.
Germany
REACH-compliant biocide regulations restrict synthetic preservative use in prepared condiments, elevating natural antimicrobial positioning for authentic wasabi paste formulations. German retail buyers mandate third-party verification of horseradish content thresholds in blended products. Frankfurt and Berlin's food manufacturing clusters drive reformulation toward higher authentic rhizome ratios to maintain EU retail shelf placement.
Wasabi Market Competitive Landscape
Concentration sits with integrated condiment distributors and controlled-environment cultivators competing against stream-dependent specialty producers. The vendor base spans three tiers: multinational seasoning houses with broadline distribution networks, regional stream-farm operators serving chef-direct channels, and emerging hydroponic specialists exploiting water-efficient architectures. Dominant competitive moves include backward integration into captive rhizome supply and technology licensing for accelerated maturation cycles.
Among Japan-based seasoning conglomerates, Mizkan Holdings and Kikkoman Corporation exemplify integrated distribution scale, while Pacific Coast Wasabi anchors North American fresh rhizome output through stream-based operations in British Columbia and Oregon. The Wasabi Company occupies a distinct position as a United Kingdom-based controlled-environment specialist serving premium European culinary channels.
| Leading Market Players |
|---|
| Mizkan Holdings |
| The Wasabi Company |
| Kikkoman Corporation |
| Pacific Coast Wasabi |
| Real Wasabi LLC |
| S&B Foods Inc. |
| Eden Foods |
| Silver Spring Foods |
| Kinjirushi Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Pacific Northwest stream farms and chef-direct procurement networks lock in both supply access and price visibility for premium fresh rhizome allocations. These contracts insulate cultivators from spot-market volatility while securing dedicated harvest volumes for Vancouver, Seattle, and San Francisco restaurants.
Pricing Analysis
Volume-discount tiering structures separate named-account chef-direct allocations from broadline distributor procurement, with fresh rhizome pricing stratifying across premium, standard, and economy tiers based on cultivation site documentation and allyl isothiocyanate assay verification. Cost compression in mid-tier hydroponic production is intensifying because closed-loop architectures reduce water rights dependency. Food manufacturers exhibit highest price sensitivity due to reformulation pressures, while specialty sushi establishments absorb premiums for verified authentic sourcing.
Supply Chain Analysis
British Columbia's Fraser Valley riparian corridors underwrite North American fresh rhizome availability, creating a geographic chokepoint where stream water allocation permits constrain expansion velocity. Production draws from Japan's Shizuoka Prefecture, Oregon's Willamette Valley, and the United Kingdom's controlled-environment facilities, with gravel substrate and continuous flow systems as critical inputs. Single-source vulnerability concentrates in the Pacific Northwest temperate rainforest zone where climate disruption threatens harvest timing. Distribution runs through refrigerated container terminals at Vancouver's Port connecting to chef-direct logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through chef-direct procurement networks that now capture named-account harvest allocations, fragmenting traditional broadline distributor control over premium fresh rhizome channels.
For Market Incumbents: Compound defensive positioning through backward integration into captive gravel substrate supply and accelerated certification investment under Japan's MAFF varietal protocols. Hydroponic specialists exploiting water-efficient architectures represent the primary emerging threat. Channel control through exclusive long-term offtake agreements with Pacific Northwest stream farms remains the critical lever. For New Entrants and Emerging Players: Anchor in the United Kingdom's underpenetrated premium restaurant segment where London demand exceeds domestic supply from Dorset and Hampshire operations. The most penetrable white space sits in direct-to-consumer subscription channels targeting home cooks seeking volatile oil intensity unavailable in retail. A chef-education go-to-market angle builds brand credibility before scaling production capacity. For Investors and Strategic Acquirers: Capital is best deployed toward controlled-environment cultivators with demonstrated temperate production economics outside traditional Pacific Rim zones. Long-term viability across the five-to-ten year window rests on water rights security and regulatory compliance infrastructure. The signal to watch as inflection indicator is blockchain traceability adoption rates among EU-bound suppliers seeking EFSA origin disclosure compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Captive gravel sourcing insulates Pacific Northwest farms from input cost volatility and quality inconsistency. |
| MAFF Varietal Certification Investment | Japan's export protocols elevate quality benchmarks that command premium positioning in North American foodservice. |
| Closed-Loop Hydroponic Architecture Deployment | Oregon operations circumvent Willamette Valley riparian water rights constraints through recirculating nutrient film systems. |
| Blockchain Traceability Implementation | EU EFSA origin disclosure mandates create competitive advantage for verifiable stream-cultivated producers. |
| Chef-Direct Procurement Network Expansion | Vancouver and San Francisco restaurants consolidate purchasing power previously fragmented across broadline distributors. |
Research Methodology
Initial hypotheses were tested against primary input from stream farm operators, specialty sushi chefs, condiment manufacturing procurement leads, and agricultural extension specialists and refined through secondary validation against customs trade records, Japan MAFF export certification databases, FDA food additive guidance documents, and EFSA labeling requirement filings. Bottom-up cultivation capacity estimates triangulated with top-down demand segmentation across product formats and end-use applications.
Variance decomposition across the projection horizon isolates volume drivers from price elasticity effects within each modeled segment including fresh rhizome, powdered formulations, paste, and sauce variants by culinary, sushi preparation, food processing, and condiment manufacturing applications. CAGRs were synthesized from historical cultivation cycle data, maturation technology adoption curves, and regulatory timeline compression factors including MAFF approval durations and EFSA documentation burdens.
Material uncertainties — water rights allocation policy shifts, climate event frequency in temperate rainforest zones, and REACH-compliant biocide regulatory evolution — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as stream-dependent farm expansion intensifies land-use competition and precision fermentation alternatives mature.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Global Oregano Essential Oil Market
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
Spice Grinders Market
Spices and Seasonings
Spices Market
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Garlic Oleoresin Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Ghost Pepper Salt Market
Spices and Seasonings
South America Seasoning and Spices Market
Spices and Seasonings
Saffron Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Asia-Pacific Seasoning and Spices Market
Spices and Seasonings
Cajun Spice Market
Spices and Seasonings
Smoked Salt Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Garlic Salt Market