
 Paprika Color Market | 2026-2036
Paprika Color Market Size, Share, and Industry Trends Forecast 2026-2036
Paprika Color Market Analytics
ISO 22000 certification is redrawing competitive boundaries for paprika color suppliers seeking access to multinational food manufacturer supply chains. Chr. Hansen Holding A/S leverages its integrated fermentation and extraction infrastructure to sustain premium positioning across European dairy and savory applications. Synthite Industries Ltd. anchors its cost structure through captive Capsicum sourcing in southern India, while Sensient Technologies Corporation competes on formulation expertise for beverage emulsions.
Paprika color comprises carotenoid pigments—principally capsanthin and capsorubin—extracted from dried Capsicum annuum fruits using solvent or supercritical CO2 methods, yielding oleoresins with color values typically ranging from 40,000 to 140,000 CU depending on processing intensity. The natural type segment dominates volume owing to clean-label mandates in processed foods, while liquid formulations command margin premiums in beverage applications where dispersion stability determines performance. Powder forms occupy the cost-efficient tier for seasoning blends and dry mixes, with granule and paste variants serving niche meat-processing applications where fat-soluble delivery matters.
FDA color additive regulations under 21 CFR 73.340 govern paprika oleoresin use in US food applications, while the EU F-Gas Regulation and REACH framework constrain solvent-based extraction methods and residual limits. India's FSSAI and BIS standards for natural food colors create parallel compliance tracks for exporters targeting the domestic processed food sector. Stakeholders must monitor evolving EU Green Deal provisions on sustainable extraction and the trajectory of supercritical CO2 capacity buildouts as regulatory pressure on petrochemical solvents intensifies.
Market Dynamics
REACH registration requirements for imported extracts are tightening purity thresholds across European supply chains, forcing extraction facilities to upgrade solvent recovery systems and validate residual limits through third-party laboratories.
Growth Catalysts
- Clean-label mandates:Processed meat manufacturers in the European Union are expanding procurement of natural colorants to replace synthetic alternatives in cured and emulsified products.
- Capsicum annuum cultivation clusters:Regional extraction capacity in Spain and Hungary supports localized supply chains, reducing import dependency for oleoresin production.
- Supercritical CO2 extraction:This solvent-free processing method is gaining traction among suppliers targeting premium beverage applications where residual solvent limits are most stringent.
Market Restraints
- Capsicum input volatility:Weather-dependent harvests in Andhra Pradesh and Karnataka create raw material price swings that compress margins for non-integrated processors.
- EU F-Gas Regulation constraints:Petrochemical solvent-based extraction faces phase-down pressures, requiring capital-intensive equipment retrofits before compliance deadlines.
- Annatto and turmeric substitution:These alternative natural colorants compete on cost in dairy and snack applications where hue flexibility exists.
Strategic Opportunities
- Underpenetrated beverage emulsions:Liquid paprika color formulations command premium positioning in functional drinks and ready-to-drink cocktails where dispersion stability determines performance.
- EU Green Deal tailwinds:Sustainable extraction certification programs are creating preferential procurement channels among multinational food manufacturers with net-zero commitments.
- ISO 22000 convergence:Food safety management system certification is becoming a de facto requirement for entry into multinational supply chains, favoring mid-tier suppliers with documented hazard controls.
Industry Challenges
- Analytical chemistry skill gaps:Carotenoid quantification and color unit standardization require specialized technicians that extraction facilities struggle to recruit in secondary processing hubs.
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and FSSAI compliance creates documentation bottlenecks that delay market entry by 12-18 months for new suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paprika Color Market |
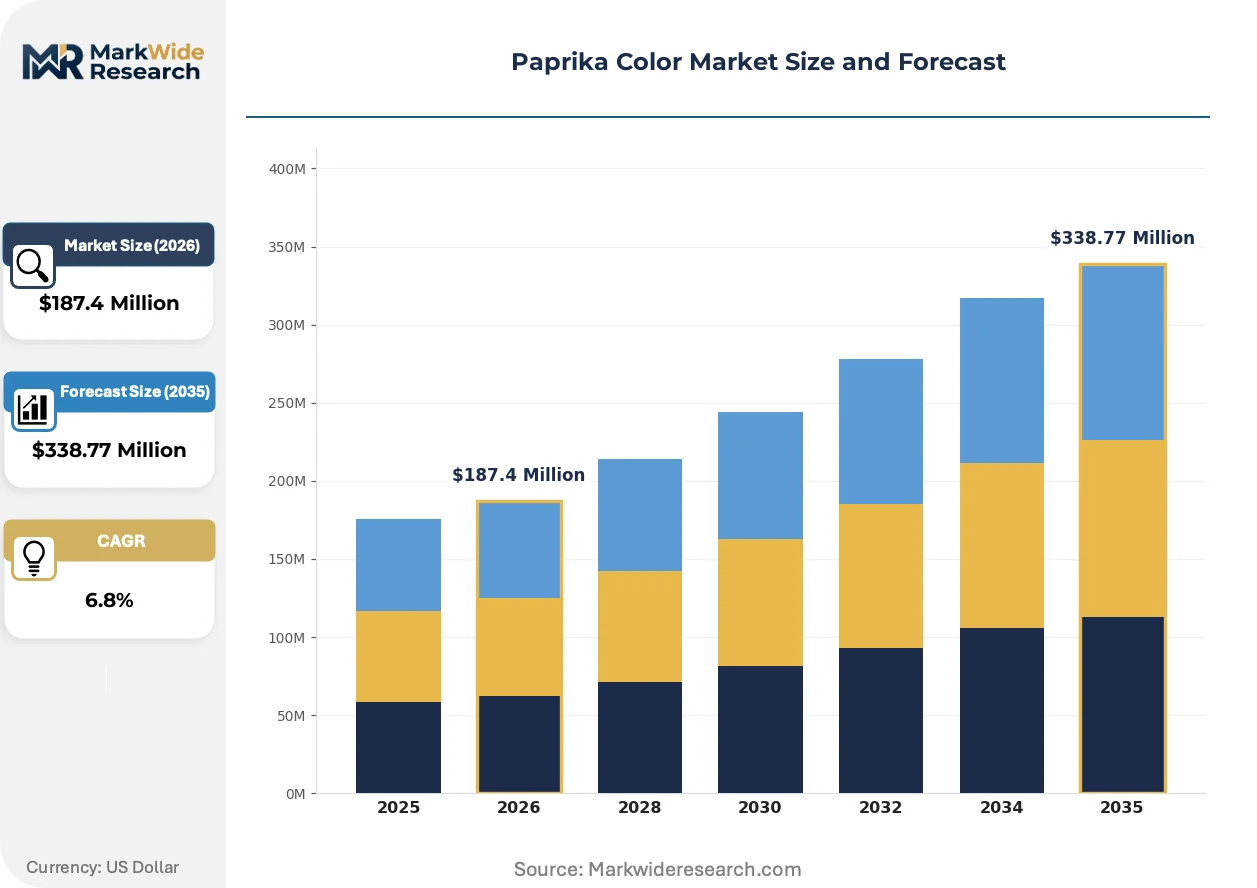
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Natural, Synthetic, Organic, Inorganic Application: Food Industry, Cosmetics, Pharmaceuticals, Nutraceuticals Form: Powder, Liquid, Granule, Paste End User: Food Manufacturers, Cosmetic Producers, Medication Developers, Dietary Supplement Firms |
| Companies Covered | Ungerer & Company, Chr. Hansen Holding A/S, DDW Color, Kalsec Natural Ingredients, ColorMaker Inc., Synthite Industries Ltd., Blue Lily Organics, Sensient Technologies Corporation, Plant Lipids, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paprika Color Market Evolving Landscape
Extraction technology and regulatory chemistry are converging to reshape how paprika color reaches end-use formulations, with sustainability metrics now embedded in procurement specifications.
Supercritical CO2 extraction systems are miniaturizing from industrial-scale installations to modular units capable of 50-200 liter batch processing. Mid-sized ingredient suppliers in Italy and Germany are adopting these compact systems to serve regional dairy and savory manufacturers with shorter lead times. This distributed processing model is compressing the traditional concentration of extraction capacity in India and Spain, enabling just-in-time oleoresin production closer to formulation facilities.
The EU F-Gas Regulation is accelerating solvent transition timelines for extraction facilities operating within the European Economic Area. Industrial consequence includes mandatory reporting of fluorinated greenhouse gas emissions from solvent recovery systems, with penalties for non-compliance escalating through 2030. Spanish and Hungarian extraction clusters are most affected, with facilities in Murcia and Kalocsa investing in thermal oxidation upgrades to maintain operating licenses.
Buyer concentration among multinational food manufacturers is consolidating supplier qualification requirements around integrated sustainability reporting. Direct procurement relationships are displacing traditional ingredient distributor networks for high-volume paprika color contracts. This channel compression is most visible in Germany and the Netherlands, where dairy and meat processing conglomerates now mandate farm-to-facility traceability for carotenoid inputs.
Paprika Color Market Segmentation
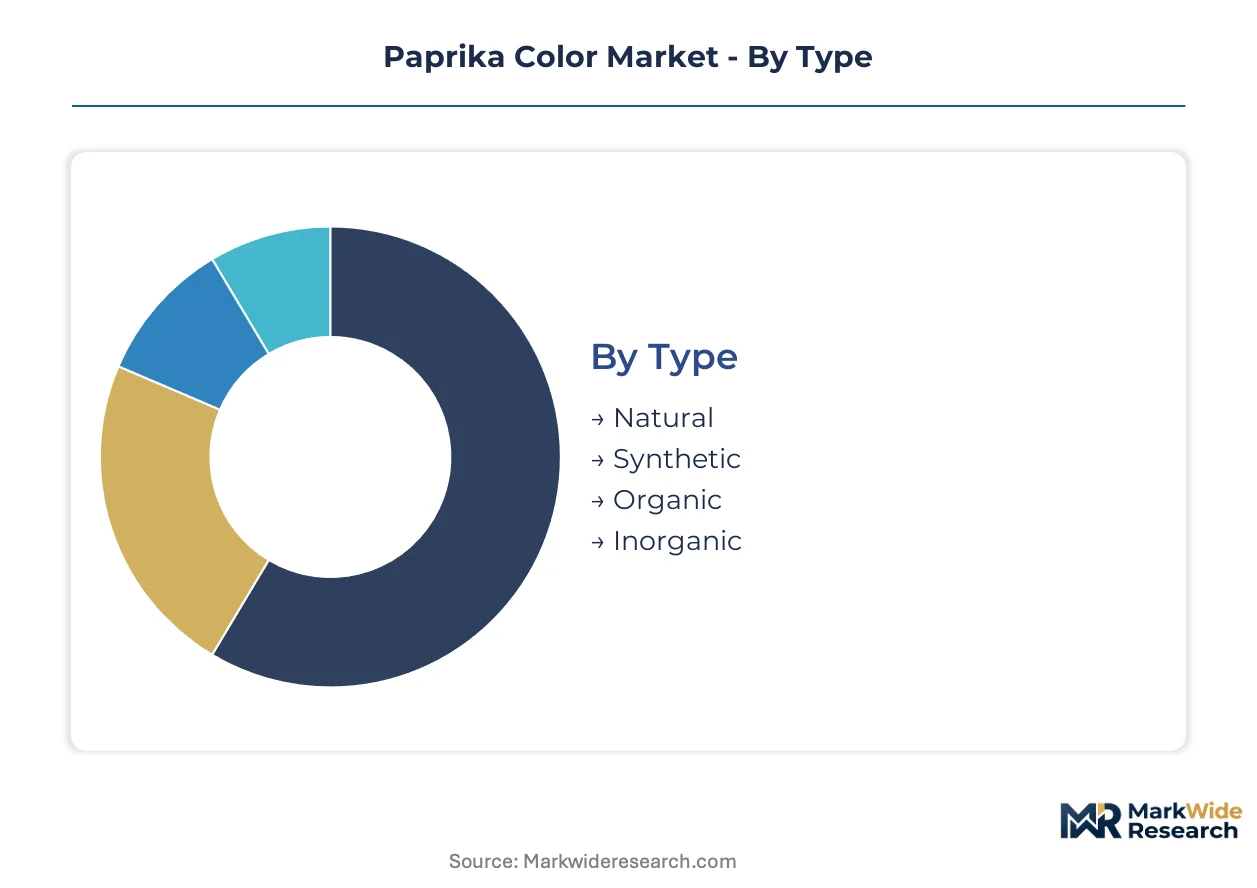
Paprika color procurement splits sharply between natural extraction methods favored by clean-label food manufacturers and synthetic alternatives competing on cost in industrial applications. Understanding these segment boundaries clarifies where formulation expertise, regulatory compliance burdens, and margin premiums concentrate across supplier tiers.
Type:
Margin pools sit heaviest in natural extracts where capsanthin concentration and solvent-free processing commands premium positioning, while synthetic variants compete on standardized color values at thinner spreads.
- Natural:Carotenoid pigments—principally capsanthin and capsorubin—extracted from dried Capsicum annuum fruits using solvent or supercritical CO2 methods, yielding oleoresins with color values typically ranging from 40,000 to 140,000 CU. Processed meat manufacturers in Spain and Hungary are expanding procurement of these extracts to meet clean-label mandates in cured and emulsified products, though REACH registration requirements for imported extracts are tightening purity thresholds that force extraction facilities to upgrade solvent recovery systems.
- Synthetic:Chemically synthesized azo and non-azo colorants engineered for batch-to-batch consistency and lower unit costs. Demand concentrates in industrial food applications where hue flexibility exists and regulatory scrutiny of natural claims is less stringent, particularly in cost-sensitive seasoning blends and dry mixes where powder forms dominate.
- Organic:Certified organic extraction from Capsicum cultivation meeting EU organic regulation standards for pesticide residue and genetic modification.
- Inorganic:Mineral-based colorants including iron oxides and titanium dioxide alternatives for applications requiring thermal stability beyond carotenoid degradation points.
Natural holds installed capacity. Synthetic is rotating up the share rankings in emerging market processed food sectors.
Application:
Volume concentration tracks toward food industry procurement where beverage emulsions and meat processing drive formulation complexity, while pharmaceutical applications demand the most intensive certification documentation.
- Food Industry:Dominant consumption channel spanning dairy, savory, beverage, and processed meat applications where dispersion stability and fat-soluble delivery determine performance specifications. Liquid formulations command margin premiums in functional drinks and ready-to-drink cocktails, while powder forms occupy the cost-efficient tier for seasoning blends.
- Cosmetics:Lip and cheek colorants leveraging paprika oleoresin for warm tone profiles in natural-positioned beauty products. EU REACH framework and FDA color additive regulations create parallel compliance tracks that delay market entry for new suppliers lacking established regulatory affairs infrastructure.
- Pharmaceuticals:Tablet coating and capsule coloration requiring excipient compatibility validation and batch release documentation under pharmacopeial standards.
- Nutraceuticals:Softgel and gummy applications where carotenoid bioavailability claims intersect with color functionality.
Food Industry anchors current procurement volumes. Nutraceuticals is climbing the fastest as functional positioning expands beyond basic supplementation.
Form:
Processing intensity and dispersion requirements create three distinct cost tiers, with liquid formulations demanding the most sophisticated emulsion stabilization technology.
- Powder:Spray-dried or plated variants serving seasoning blends, dry mixes, and cost-sensitive applications where reconstitution in aqueous systems is acceptable. India's FSSAI and BIS standards for natural food colors create compliance tracks for exporters targeting the domestic processed food sector with this most commoditized form.
- Liquid:Oil-dispersed or water-miscible emulsions requiring specialized formulation expertise for beverage applications where dispersion stability determines performance. Supercritical CO2 extraction is gaining traction among suppliers targeting premium beverage applications where residual solvent limits are most stringent.
- Granule:Agglomerated forms for controlled release in meat-processing applications where fat-soluble delivery matters.
- Paste:High-concentration oleoresin preparations for industrial-scale color dosing in emulsified meat systems.
Powder maintains broadest installed base. Liquid is gaining share fastest as beverage manufacturers consolidate supplier relationships around dispersion performance guarantees.
End User:
Buyer concentration and technical sophistication split sharply between multinational food manufacturers with integrated sustainability reporting requirements and smaller cosmetic producers purchasing through distributor networks.
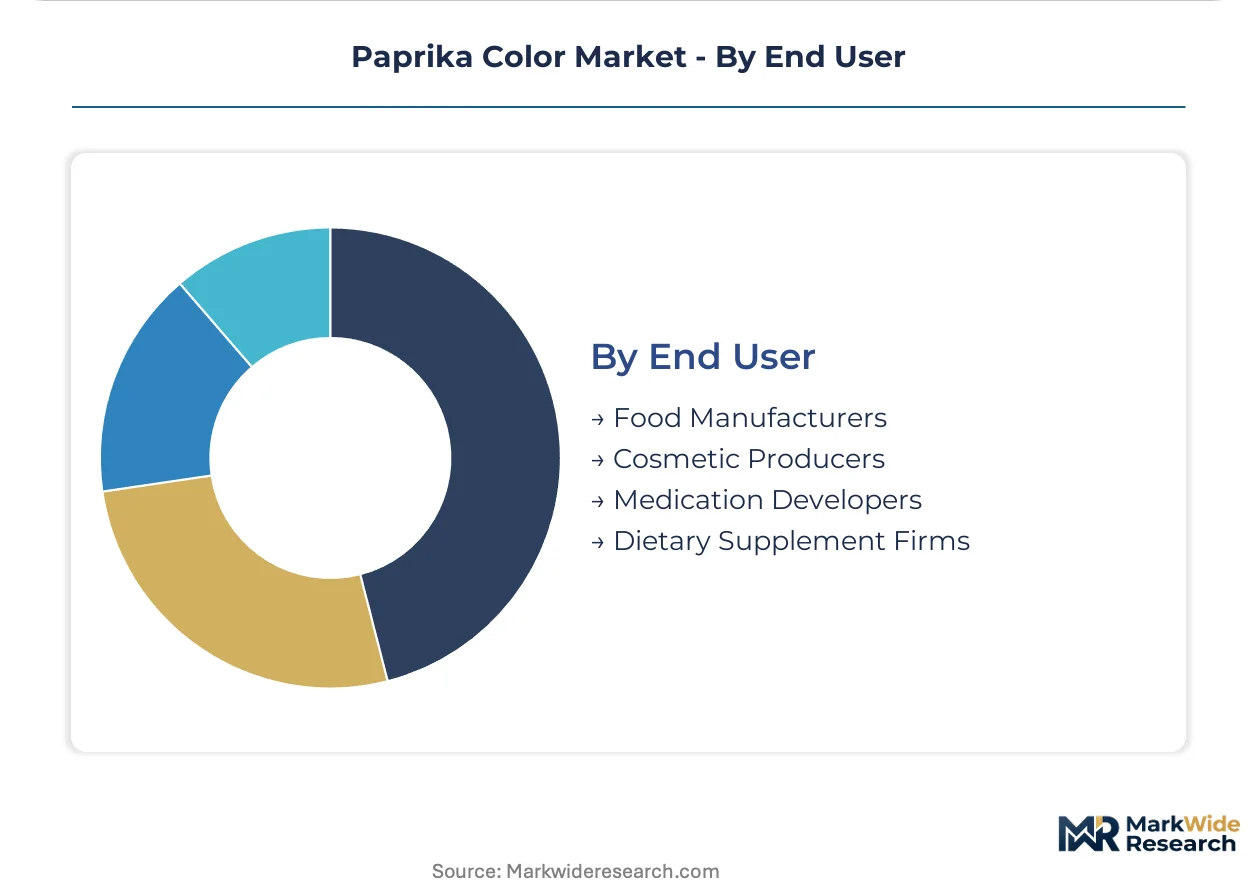
- Food Manufacturers:Multinational dairy and meat processing conglomerates in Germany and the Netherlands now mandate farm-to-facility traceability for carotenoid inputs, displacing traditional ingredient distributor networks for high-volume contracts. ISO 22000 certification is becoming a de facto requirement for entry into these supply chains.
- Cosmetic Producers:Mid-sized natural beauty brands in Italy and France sourcing through regional distributors with shorter lead time requirements.
- Medication Developers:Pharmaceutical firms requiring pharmacopeial-grade documentation and analytical chemistry validation for excipient compatibility.
- Dietary Supplement Firms:Nutraceutical contract manufacturers prioritizing carotenoid bioavailability claims alongside color functionality.
Food Manufacturers hold dominant procurement volume. Dietary Supplement Firms is rotating up the share rankings as functional food positioning blurs category boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal provisions on sustainable extraction are redirecting procurement flows toward certified supply chains in member states with established Capsicum processing infrastructure. REACH registration deadlines are compressing market entry timelines for non-European suppliers. Spain, Hungary, and Germany now anchor regional oleoresin demand through integrated meat and dairy manufacturing clusters.
Spain
Processed meat manufacturers in Murcia and Extremadura are expanding clean-label colorant procurement for cured ham and chorizo applications. The EU F-Gas Regulation mandates thermal oxidation upgrades for solvent recovery systems in extraction facilities. The Murcia extraction cluster is investing in supercritical CO2 capacity to maintain operating licenses under tightening emission thresholds.
Hungary
Kalocsa-based paprika processors supply regional dairy and savory manufacturers with high-color-value oleoresins. REACH registration requirements for imported extracts are forcing domestic facilities to validate residual limits through third-party laboratories. The southern Great Plain cultivation belt supports captive raw material sourcing for integrated extraction operations.
Germany
Dairy conglomerates in Bavaria and North Rhine-Westphalia mandate ISO 22000 certification for carotenoid suppliers entering multinational supply chains. The EU Green Deal's sustainable extraction certification programs are creating preferential procurement channels for net-zero-committed manufacturers. Frankfurt and Hamburg serve as formulation hubs where dispersion expertise determines supplier selection for beverage emulsions.
India
Andhra Pradesh and Karnataka harvest volatility creates raw material price swings that compress margins for non-integrated processors. FSSAI and BIS standards for natural food colors create parallel compliance tracks for exporters targeting the domestic processed food sector. Synthite Industries anchors cost structures through captive Capsicum sourcing in southern Indian cultivation zones.
United States
FDA color additive regulations under 21 CFR 73.340 govern paprika oleoresin use in meat and beverage applications. Clean-label mandates from multinational food manufacturers are displacing synthetic alternatives in cured products. California and Wisconsin dairy processors drive formulation demand for oil-dispersed color systems in cheese and flavored milk applications.
Paprika Color Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and geographic coverage. The supplier base organizes into three tiers: multinational ingredient houses with integrated fermentation infrastructure, mid-sized extraction specialists with captive raw material sourcing, and regional formulators competing on lead time flexibility. Consolidation pressure concentrates among ISO 22000-certified suppliers capable of farm-to-facility traceability documentation. Dominant competitive moves include backward integration into Capsicum cultivation and supercritical CO2 capacity buildouts to meet EU solvent restrictions.
Within the integrated multinational tier, Chr. Hansen Holding A/S and Sensient Technologies Corporation exemplify premium positioning through formulation expertise and dispersion technology. Synthite Industries Ltd. occupies a cost-leadership archetype anchored by captive sourcing in Indian cultivation belts. Kalsec Natural Ingredients and DDW Color represent mid-tier specialists competing on regional compliance agility and shorter certification timelines for multi-jurisdiction market entry.
| Leading Market Players |
|---|
| Ungerer & Company |
| Chr. Hansen Holding A/S |
| DDW Color |
| Kalsec Natural Ingredients |
| ColorMaker Inc. |
| Synthite Industries Ltd. |
| Blue Lily Organics |
| Sensient Technologies Corporation |
| Plant Lipids |
| Others |
Value Network & Pricing Analysis
ISO 22000 certification gates both supply qualification and price differentiation simultaneously, creating a bifurcated market where certified suppliers command premium positioning in multinational food manufacturer supply chains while uncertified processors compete on thinner margins in regional spot markets. This regulatory threshold concentrates pricing power among integrated extraction specialists with documented hazard controls, compressing returns for commodity-oriented suppliers lacking traceability infrastructure.
Pricing Analysis
Certification level (ISO 22000, REACH-registered, FDA-grade) creates the primary spread between premium and commodity tiers. Three-tier pricing structure across premium, standard, and economy levels tracks color value concentration, solvent-free processing claims, and farm-to-facility traceability documentation. Cost compression in the economy tier is intensifying because annatto and turmeric substitution erodes volume commitments from price-sensitive seasoning blend manufacturers. Food manufacturers with net-zero procurement mandates show least price sensitivity, while regional dry mix processors exhibit highest elasticity.
Supply Chain Analysis
India, Spain, and Hungary anchor global oleoresin extraction capacity through distinct competitive archetypes. Indian processors draw from Andhra Pradesh and Karnataka Capsicum cultivation belts, Spanish facilities feed from Murcia and Extremadura clusters, and Hungarian operations source from the southern Great Plain belt. Raw material dependencies center on Capsicum annuum harvests, petrochemical solvents or supercritical CO2 equipment, and third-party analytical validation services. Single-source vulnerability concentrates in weather-dependent Indian harvests that trigger global price contagion. Distribution runs through direct procurement relationships with multinational food manufacturers displacing traditional ingredient distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemistry capability gaps in carotenoid quantification and multi-jurisdiction regulatory documentation create scarcity premiums for suppliers with in-house technical infrastructure. The market rewards integrated operations over fragmented processing networks.
For Market Incumbents: Consolidate backward integration into captive Capsicum cultivation to defend margin position against raw material volatility from Indian monsoon dependency. Expand supercritical CO2 capacity buildouts in EU extraction clusters before F-Gas Regulation phase-down deadlines eliminate solvent-based competitors. Prioritize ISO 22000 certification depth over geographic expansion to maintain preferential procurement channel access.
For New Entrants and Emerging Players: FDA fast-track approval for paprika oleoresin under 21 CFR 73.340 offers the most penetrable regulatory pathway for US beverage emulsion applications where dispersion expertise commands premium positioning. Target underpenetrated functional drink and ready-to-drink cocktail segments with modular supercritical CO2 batch processing systems that compress lead times against Indian and Spanish incumbents. Lead with formulation partnerships rather than commodity oleoresin supply.
For Investors and Strategic Acquirers: REACH registration deadline acceleration reshapes the acquisition landscape toward mid-tier European extraction specialists with validated solvent recovery infrastructure and existing ECHA dossiers. Long-term viability over the next decade hinges on supercritical CO2 transition completion and sustainable extraction certification alignment with EU Green Deal procurement mandates. Acquisition target archetype: ISO 22000-certified regional processors with captive raw material sourcing and underutilized extraction capacity. Signal to monitor: EU F-Gas Regulation enforcement intensity and thermal oxidation upgrade completion rates in Spanish and Hungarian facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Buildout | REACH and F-Gas Regulation compliance secures operating licenses in EU extraction clusters. |
| Backward Integration into Capsicum Cultivation | Captive sourcing in Andhra Pradesh or Murcia belts insulates margins from harvest volatility. |
| ISO 22000 Certification Investment | Food safety management documentation unlocks multinational manufacturer direct procurement. |
| Sustainable Extraction Certification | EU Green Deal alignment creates preferential channels for net-zero-committed dairy processors. |
| Beverage Emulsion Formulation Partnership | Dispersion stability expertise commands premium positioning in functional drink applications. |
Research Methodology
Cross-validation between primary interviews with extraction facility technical directors, regulatory affairs managers at multinational food manufacturers, and procurement leads at dairy and meat processing conglomerates anchors the qualitative findings. Secondary validation draws from ECHA REACH registration databases, FDA color additive filings under 21 CFR 73.340, FSSAI natural food color standards, EU F-Gas Regulation implementation reports, and customs trade data for oleoresin imports. Bottom-up capacity assessments of supercritical CO2 installations triangulate against top-down demand modeling from processed meat and beverage formulation trends.
Sensitivity analysis across extraction technology transition timelines, Capsicum harvest yield scenarios, and regulatory enforcement intensity variations informs the analytical framework. Segmentation dimensions span natural versus synthetic type, powder versus liquid versus paste form, food industry versus cosmetic versus pharmaceutical application, and integrated multinational versus regional specialist supplier tier. CAGRs derive from installed capacity buildout trajectories, clean-label procurement policy adoption curves, and substitution elasticity estimates for annatto and turmeric alternatives. Industry-specific inputs include color unit standardization protocols, solvent residual limit evolution, and farm-to-facility traceability documentation requirements.
Decision-makers should treat outputs as directional under sustained clean-label mandate expansion and REACH registration continuity assumptions; material deviation in EU Green Deal implementation pace or Indian monsoon pattern disruption would warrant model refresh. Recalibration cycles align with material shifts in F-Gas Regulation enforcement thresholds, supercritical CO2 equipment cost curves, and multinational manufacturer net-zero procurement deadline acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Meat Seasonings Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
North American Seasonings and Spices Market
Spices and Seasonings
Global Spices and Stimulants Market
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Cajun Spice Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
Espresso Salt Market
Spices and Seasonings
Spices Market
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Fennel Powder Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Nutmeg Oil Market