
 US Gourmet Salt Market | 2026-2036
US Gourmet Salt Market Size, Share, and Industry Trends Forecast 2026-2036
US Gourmet Salt Market Analytics
Specialty retail margins is reconfiguring profit pools across the US gourmet salt value chain, pulling returns from commodity table salt toward premium branded finishing salts. SaltWorks leverages its Pacific Northwest production base to control supply of artisanal flake and smoked varieties. Jacobsen Salt Co. anchors its position through Oregon-harvested sea salt with traceable coastal provenance. Morton Salt, Inc. competes by extending its legacy infrastructure into gourmet sub-lines distributed through mainstream retail.
Gourmet salt comprises unrefined or minimally processed sodium chloride crystals harvested from seawater evaporation, underground rock deposits, or saline springs, typically retaining trace minerals that influence color, moisture, and flavor intensity for culinary finishing and ingredient applications. Sea salt and flavored salt command the strongest margin expansion as chefs and home cooks trade up from iodized table salt, while rock salt maintains steady volume in grinder-format retail. Premium and organic grades within the quality grade dimension attract disproportionate shelf-space investment from specialty stores and online retail channels seeking differentiation against supermarket private labels.
FDA oversight of sodium content claims and USDA organic certification requirements directly constrain labeling strategies and production input sourcing for domestic gourmet salt producers. State-level cottage food laws and commercial kitchen standards in California and New York further fragment compliance burdens for small-batch harvesters. Stakeholders must monitor evolving FDA guidance on front-of-package sodium warnings and organic integrity enforcement, as these rules will determine which producers retain access to premium price tiers versus facing reformulation or exclusion.
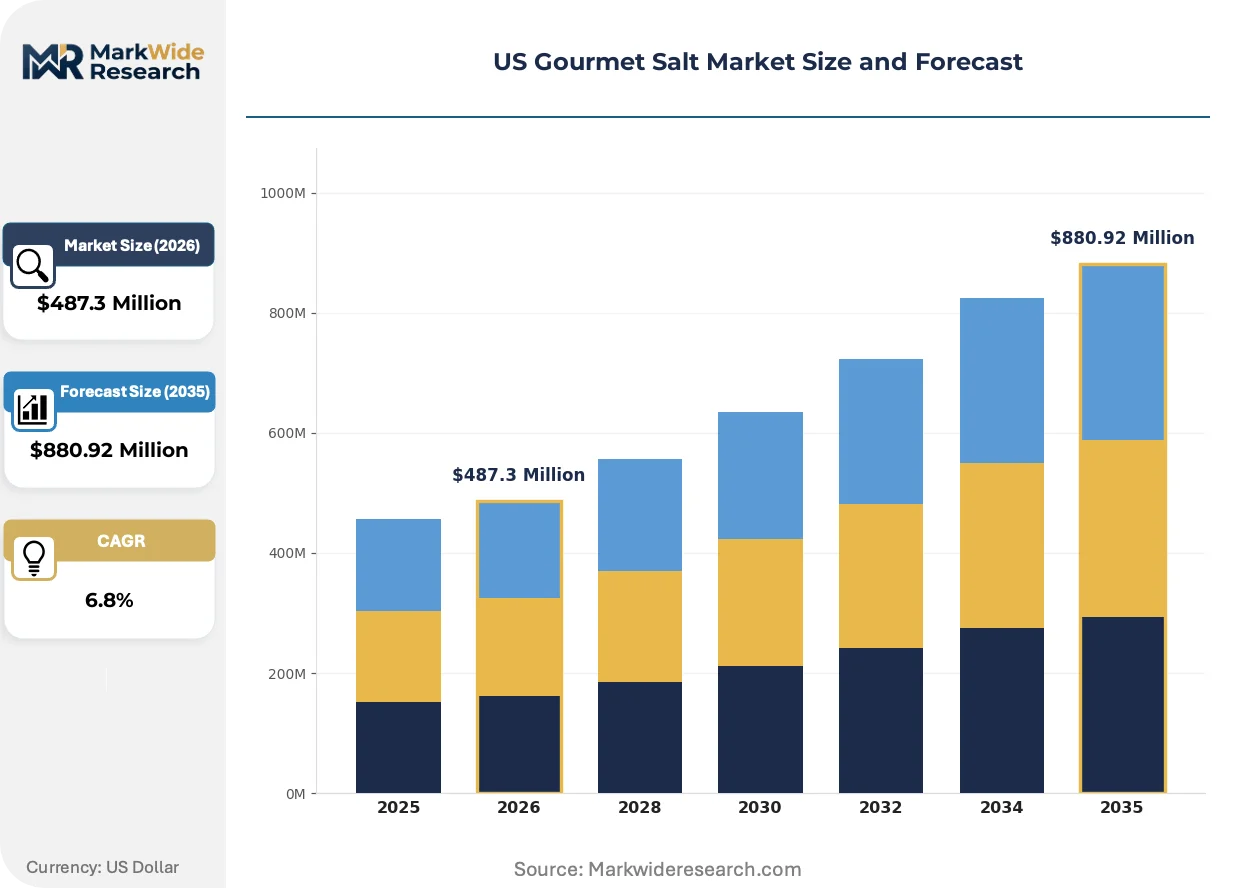
Market Dynamics
Chef-driven food culture in California, New York, and the Pacific Northwest is pulling procurement toward traceable coastal provenance and artisanal finishing varieties, compressing shelf space for commodity iodized salt and rewarding producers with USDA organic certification and FDA-compliant labeling infrastructure.
Growth Catalysts
- USDA Organic Certification:Premium shelf placement at Whole Foods Market and specialty retailers requires certified organic inputs, creating pull-through demand for Oregon-harvested sea salt and mineral-retained rock varieties.
- Direct-to-Consumer Infrastructure:E-commerce fulfillment networks in Seattle and Brooklyn enable small-batch harvesters to bypass traditional distributor markups and capture full retail margin.
- Foodservice Procurement Standards:James Beard Award-recognized restaurants in Los Angeles and Manhattan specify flake salt and smoked finishing varieties for plated presentation, institutionalizing premium salt as a kitchen staple.
Market Restraints
- Pacific Northwest Weather Volatility:Solar evaporation ponds in coastal Oregon face rainfall disruption that compresses harvest windows and concentrates supply risk among artisanal producers.
- FDA Sodium Content Oversight:Front-of-package warning requirements and nutrient content claim restrictions constrain marketing language for flavored and finishing salt lines.
- Imported Himalayan Rock Salt:Pakistani-mined pink salt competes on mineral-aesthetic positioning at lower price points, pressuring domestic premium rock salt margins.
Strategic Opportunities
- Private Label Partnerships:Trader Joe's and regional specialty grocers seek exclusive coastal-provenance lines, offering volume commitments that amortize fixed certification costs.
- Functional Ingredient Convergence:Probiotic and adaptogenic salt blends target wellness-oriented consumers in Austin and Denver, expanding addressable use cases beyond culinary finishing.
- State Cottage Food Law Expansion:California AB 626-style microenterprise kitchen permits enable home-based harvesters to test market traction before commercial kitchen investment.
Industry Challenges
- Salinity Analysis Technician Shortage:Accurate mineral profiling and moisture-content verification require trained laboratory staff, constraining quality-control scaling for small-batch operations.
- Organic Integrity Audit Burden:USDA National Organic Program requires annual third-party inspections of evaporation sites and handling facilities, creating compliance timeline friction for coastal harvesters.
- Legacy Distributor Integration:Mainstream foodservice broadliners lack temperature-controlled handling protocols for moisture-sensitive flake varieties, forcing producers to build parallel logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Gourmet Salt Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Table Salt, Sea Salt, Rock Salt, Flavored Salt Quality Grade: Regular, Premium, Organic, Natural Packaging Type: Bottles, Pouches, Bulk Packs, Jars Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service |
| Companies Covered | Morton Salt, Inc., SaltWorks, Maldon Crystal Salt Company, Salty Wahine, Amagansett Sea Salt Co., Alaska Pure Sea Salt Company, Selina Naturally, The Spice Lab, Jacobsen Salt Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Gourmet Salt Market Evolving Landscape
Production technology and regulatory positioning are converging to separate artisanal harvesters with certified infrastructure from commodity competitors, while demand-side purchasing behavior shifts toward subscription and direct sourcing models that reward traceability investments.
Solar evaporation monitoring systems equipped with IoT salinity sensors and automated weather-station integration are hybridizing traditional harvest methods with precision agriculture. Oregon and California coastal producers deploy these systems to optimize pond rotation and predict harvest yields. The technology is compressing yield variance and enabling harvesters to pre-sell contracted volumes to restaurant groups before crystallization completes.
FDA draft guidance on front-of-package sodium warning symbols is reshaping labeling strategies for flavored salt producers. The proposed rule would require prominent warnings on products exceeding sodium thresholds, forcing reformulation of seasoned varieties or exclusion from mainstream retail placement. Premium producers in the Pacific Northwest are responding by emphasizing mineral-content differentiation and shifting marketing toward culinary finishing use cases rather than table-salt replacement.
Restaurant procurement teams are consolidating supplier relationships and demanding lot-level traceability documentation for ESG reporting. Independent chefs in Brooklyn and Los Angeles now specify harvest date, coastal coordinates, and organic certification batch numbers on purchase orders. This behavior is most visible in fast-casual chains with chef-founder credentials, where ingredient storytelling supports premium menu pricing and social media marketing content.
US Gourmet Salt Market Segmentation
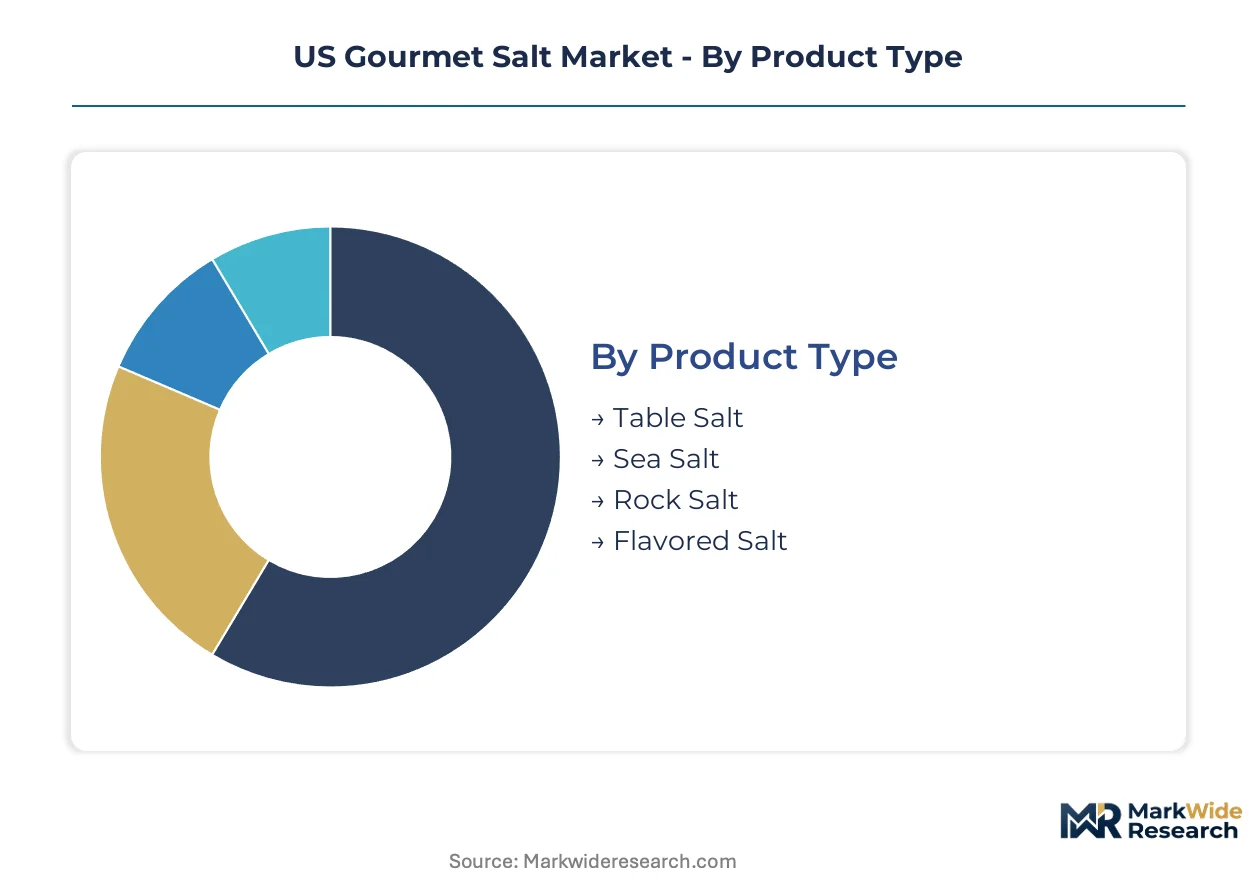
Gourmet salt producers configure product lines across four intersecting dimensions to capture margin at different stages of the value chain. Segmentation strategy determines access to USDA organic certification, FDA-compliant labeling, and chef-driven procurement channels.
Product Type:
Composition and harvest method separate culinary-grade sodium chloride into distinct functional categories with divergent margin profiles.
- Sea Salt:Crystals form through solar evaporation of seawater, retaining trace magnesium and calcium that influence moisture retention and flavor intensity. James Beard Award-recognized restaurants in Los Angeles and Manhattan specify Pacific Northwest-harvested flake varieties for plated presentation, pulling procurement toward traceable coastal provenance.
- Flavored Salt:Base salt infused with smoked wood, herbs, or spice blends during finishing stages. Austin and Denver wellness consumers drive demand for probiotic and adaptogenic salt blends, expanding addressable use cases beyond traditional culinary applications.
- Table Salt:Refined sodium chloride with uniform crystal structure for general cooking and baking applications.
- Rock Salt:Underground-mined halite crystals, typically deployed in grinder-format retail for texture-driven finishing.
Sea salt commands the established base. The steepest expansion runs through flavored salt.
Quality Grade:
Certification tier determines shelf placement economics and price realization across retail channels.
- Organic:USDA National Organic Program certification requires third-party inspection of evaporation sites and handling facilities. Whole Foods Market and specialty retailers mandate certified organic inputs for premium shelf placement, creating pull-through demand for Oregon-harvested production.
- Premium:Mineral-retained varieties with documented harvest coordinates and moisture-content verification. Brooklyn and Los Angeles restaurant procurement teams now specify lot-level traceability documentation including harvest date and coastal coordinates for ESG reporting.
- Natural:Minimally processed salt without artificial additives, positioned between commodity and certified organic tiers.
- Regular:Standard-grade gourmet salt meeting baseline FDA food labeling requirements without premium certification overhead.
Premium grade commands the established base. The steepest expansion runs through organic.
Packaging Type:
Format selection shapes moisture sensitivity management and channel access for different consumption occasions.
- Jars:Glass containers with sealed lids protect flake and smoked varieties from humidity degradation. Temperature-controlled handling protocols required for moisture-sensitive formats force producers to build parallel logistics networks outside mainstream foodservice broadliners.
- Bottles:Dispensing formats suited for high-frequency use in commercial kitchen environments.
- Pouches:Flexible packaging for refill and subscription direct-to-consumer models in Seattle and Brooklyn e-commerce fulfillment networks.
- Bulk Packs:Volume formats for foodservice procurement and private label partnerships with Trader Joe's and regional specialty grocers.
Jars command the established base. The steepest expansion runs through pouches.
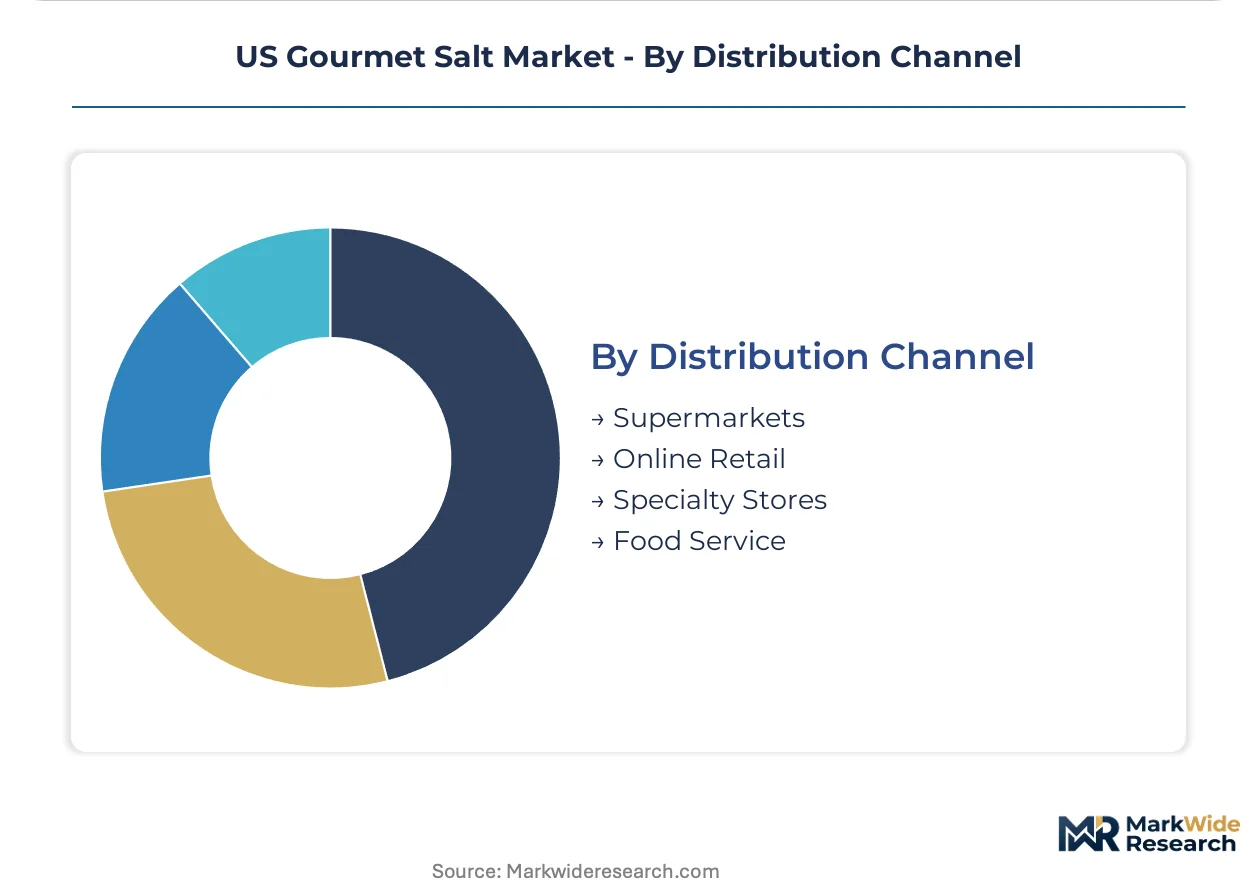
Distribution Channel:
Channel selection determines margin capture and regulatory compliance burden for harvesters at different scale levels.
- Specialty Stores:Curated retail environments in California, New York, and Pacific Northwest population centers reward traceability investments with disproportionate shelf-space allocation. FDA draft guidance on front-of-package sodium warning symbols is forcing reformulation strategies for flavored lines placed in these channels.
- Online Retail:Direct-to-consumer infrastructure enables small-batch harvesters to bypass traditional distributor markups and capture full retail margin.
- Supermarkets:Mainstream retail placement requires compliance with front-of-package warning requirements and nutrient content claim restrictions.
- Food Service:Restaurant and institutional procurement with consolidated supplier relationships and documented traceability requirements.
Specialty stores command the established base. The steepest expansion runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across US sub-regions. The Pacific Northwest favors traceable coastal provenance and artisanal finishing varieties. California and New York drive chef-driven procurement with ESG documentation requirements. Interior markets remain price-sensitive, gravitating toward bulk rock salt and grinder-format retail.
Pacific Northwest
Oregon and Washington coastal harvesters supply flake and smoked varieties to James Beard Award-recognized restaurants. FDA food labeling requirements and USDA organic certification standards constrain small-batch operations. Solar evaporation ponds in coastal Oregon face rainfall disruption that compresses harvest windows.
California
Los Angeles and San Francisco chef-driven food culture pulls procurement toward premium sea salt with documented harvest coordinates. State-level cottage food laws and commercial kitchen standards fragment compliance burdens for microenterprise harvesters. Direct-to-consumer infrastructure in Los Angeles enables subscription models bypassing traditional distributor markups.
New York Metro
Manhattan and Brooklyn restaurants specify lot-level traceability documentation including harvest date and organic certification batch numbers. FDA draft guidance on front-of-package sodium warning symbols forces reformulation strategies for flavored salt lines. E-commerce fulfillment networks in Brooklyn support small-batch harvesters capturing full retail margin.
Mountain West
Austin and Denver wellness consumers drive demand for probiotic and adaptogenic salt blends expanding beyond culinary applications. State cottage food law expansion enables home-based harvesters to test market traction. Functional ingredient convergence targets wellness-oriented consumers seeking mineral-content differentiation.
Southeast
Florida and Georgia markets show growing interest in gourmet salt for home cooking and specialty retail. Imported Himalayan rock salt from Pakistan competes on mineral-aesthetic positioning at lower price points. Private label partnerships with regional specialty grocers offer volume commitments amortizing fixed certification costs.
US Gourmet Salt Market Competitive Landscape
Capability concentration sits with artisanal harvesters holding USDA organic certification and FDA-compliant labeling infrastructure; scale advantage sits with legacy processors extending mainstream distribution networks. The market structures around three tiers: certified artisanal producers, regional specialty harvesters, and diversified commodity players. Dominant competitive moves include private label partnerships with specialty grocers and direct-to-consumer channel development bypassing traditional markups.
Within the certified artisanal tier, SaltWorks and Jacobsen Salt Co. exemplify Pacific Northwest producers leveraging coastal provenance for premium positioning. Morton Salt, Inc. occupies a position representing legacy infrastructure extension into gourmet sub-lines. These three anchors illustrate the capability-scale tension: coastal harvesters control traceability narratives while diversified processors capture mainstream retail shelf space.
| Leading Market Players |
|---|
| Morton Salt, Inc. |
| SaltWorks |
| Maldon Crystal Salt Company |
| Salty Wahine |
| Amagansett Sea Salt Co. |
| Alaska Pure Sea Salt Company |
| Selina Naturally |
| The Spice Lab |
| Jacobsen Salt Co. |
| Others |
Value Network & Pricing Analysis
Pacific Northwest weather volatility compresses harvest windows for solar evaporation operations, forcing artisanal producers to absorb yield variance costs that widen spreads between premium coastal-provenance grades and commodity rock salt alternatives. This climate-driven supply constraint simultaneously tightens availability of Oregon-harvested flake varieties and rewards producers with USDA organic certification infrastructure capable of securing long-term offtake contracts with specialty retailers.
Pricing Analysis
Long-term offtake agreements dominate procurement between certified artisanal harvesters and James Beard Award-recognized restaurant groups, insulating premium pricing from spot-market fluctuations in commodity salt. Three-tier pricing structure across premium organic, premium non-organic, and natural grade levels reflects certification overhead and traceability documentation costs. Pricing pressure stems from Pakistani-mined Himalayan rock salt competing on mineral-aesthetic positioning at lower price points, compressing margins for domestic premium rock salt. Foodservice procurement teams show lowest price sensitivity due to ESG reporting requirements, while bulk private label buyers for regional specialty grocers negotiate hardest on volume commitments.
Supply Chain Analysis
FDA food labeling requirements function as de facto export controls on domestic gourmet salt positioning, restricting marketing language for flavored varieties and constraining channel access for non-compliant producers. Supply concentrates in coastal Oregon and Washington for artisanal flake and smoked varieties, with Pakistan and India anchoring rock salt feedstocks. Raw material dependencies include seawater salinity profiles, hardwood smoking inputs, and organic certification-compliant handling facilities. Single-source vulnerability runs through solar evaporation pond operations exposed to rainfall disruption. Distribution runs through parallel logistics networks outside mainstream foodservice broadliners, as temperature-controlled handling protocols for moisture-sensitive flake varieties exceed legacy distributor capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated restaurant procurement teams demanding lot-level traceability documentation, fragmenting supplier margins and forcing harvesters to absorb certification audit burdens previously distributed across distributor networks.
For Market Incumbents: Insulate premium positioning by deepening backward integration into coastal evaporation site ownership and accelerating USDA organic certification batch processing capacity. Threats from Pakistani rock salt importers and FDA front-of-package sodium warning proposals require defensive investment in mineral-content differentiation narratives and culinary finishing use-case marketing rather than table-salt replacement positioning. For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure targeting Brooklyn and Los Angeles home cooks before pursuing foodservice penetration, as e-commerce fulfillment networks enable full retail margin capture without legacy distributor integration costs. The Mountain West wellness segment offers most penetrable white space for probiotic and adaptogenic salt blends, with Austin and Denver consumers expanding addressable use cases beyond traditional culinary applications. For Investors and Strategic Acquirers: FDA draft guidance on front-of-package sodium warning symbols reshapes the acquisition landscape by forcing reformulation investments that favor targets with existing compliance infrastructure and R&D bandwidth. Long-term viability centers on certified artisanal producers with traceable coastal provenance and organic integrity audit capabilities. Watch for final FDA rule publication as inflection signal determining which flavored salt portfolios retain mainstream retail access versus facing exclusion.| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Investment | Unlocks premium shelf placement at Whole Foods Market and specialty retailers requiring certified inputs. |
| Direct-to-Consumer Channel Development | Bypasses traditional distributor markups through Seattle and Brooklyn e-commerce fulfillment networks. |
| Private Label Partnership Formation | Amortizes fixed certification costs through volume commitments with Trader Joe's and regional grocers. |
| IoT-Enabled Harvest Monitoring Deployment | Compresses yield variance through solar evaporation pond salinity sensors and weather-station integration. |
| Functional Ingredient Line Extension | Captures Austin and Denver wellness consumers seeking probiotic and adaptogenic salt blends. |
Research Methodology
Initial hypotheses were tested against primary input from coastal harvest operations managers, specialty retail category buyers, restaurant procurement directors, and FDA regulatory affairs consultants, then refined through secondary validation. Primary research drew from structured interviews with Oregon and Washington solar evaporation facility operators, Brooklyn and Los Angeles chef-owners, and Whole Foods Market shelf-space planners. Secondary sources included FDA guidance documents, USDA National Organic Program audit protocols, customs trade data on Pakistani rock salt imports, and SEC filings from diversified commodity salt processors. Bottom-up volume modeling from harvest site capacity and top-down value triangulation from retail price audits were cross-referenced for convergence.
Demand-supply balance framing anchored the analytical framework across the analysis window, with consumption projections calibrated against chef-driven procurement standards and home cook subscription adoption patterns. Segmentation dimensions modeled included product type, quality grade tier, packaging format, and distribution channel structure, supplemented by regional clustering around coastal provenance preference zones. CAGRs were derived from iterative reconciliation of historical volume trajectories and forward-looking procurement contract visibility. Industry-specific forecast inputs incorporated Pacific Northwest rainfall pattern distributions and FDA rulemaking timeline scenarios.
Practitioners should monitor FDA final guidance publication, USDA organic integrity enforcement actions, and Pacific Northwest climate anomaly frequency for early signals requiring forecast reassessment. Forecasts reflect assumptions regarding continued chef-driven food culture pull in California and New York, stable Pakistani rock salt import flows, and gradual direct-to-consumer channel share expansion. Material shifts in FDA sodium warning implementation scope or catastrophic evaporation pond weather events would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Onion Oil Market
Spices and Seasonings
Paprika Color Market
Spices and Seasonings
North American Seasonings and Spices Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Frankincense Extract Market
Spices and Seasonings
Basil Essential Oil Market
Spices and Seasonings
Herb Oil Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Turmeric Oleoresin Market
Spices and Seasonings
Onion Essential Oil Market
Spices and Seasonings
Herbs and Spices Market
Spices and Seasonings
Himalayan Salt Market
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Nutmeg Oil Market
Spices and Seasonings
South America Seasoning and Spices Market
Spices and Seasonings
Dried Herbs Market