

High Performance Mercury Sorbent Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Mercury Sorbent Market Insights
The customer base for mercury sorbents is broadening beyond traditional coal-fired utilities to encompass cement manufacturers and waste incineration operators facing tightening emission limits. BASF leverages its polymer chemistry expertise to develop specialized sorbent formulations for non-utility applications. Albemarle Corporation anchors its position through bromine-activated carbon technology leadership and captive mineral sourcing. Johnson Matthey differentiates via integrated catalyst-sorbent systems that address multi-pollutant control requirements.
High performance mercury sorbents are engineered materials designed to capture elemental and oxidized mercury from flue gas streams at temperatures between 120°C and 180°C, typically comprising activated carbon substrates impregnated with sulfur, halogens, or metal oxides to enhance chemisorption capacity. These sorbents serve the primary industrial purpose of enabling combustion and process industries to comply with stringent mercury emission regulations while maintaining operational continuity. Sulfur-impregnated carbon dominates current procurement volumes due to proven efficacy in coal-combustion applications and established supply chains, though metal oxide sorbents represent the fastest-expanding category as regenerable systems gain traction in chlor-alkali and gold mining sectors where sorbent lifecycle costs determine adoption. Dry sorbent injection occupies the largest deployment mode share given minimal capital requirements for retrofit installations, while fixed bed reactor configurations command premium pricing in continuous-process chemical manufacturing.
EPA MATS enforcement in the United States, China's MEE emission standards for thermal power, and the EU Industrial Emissions Directive collectively shape product certification requirements and procurement specifications across major demand centers. Compliance timelines in these jurisdictions directly determine sorbent specification stringency and testing protocol adoption. Stakeholders must monitor regulatory harmonization efforts between national mercury emission frameworks and emerging carbon capture retrofits that may alter flue gas chemistry and sorbent performance requirements.
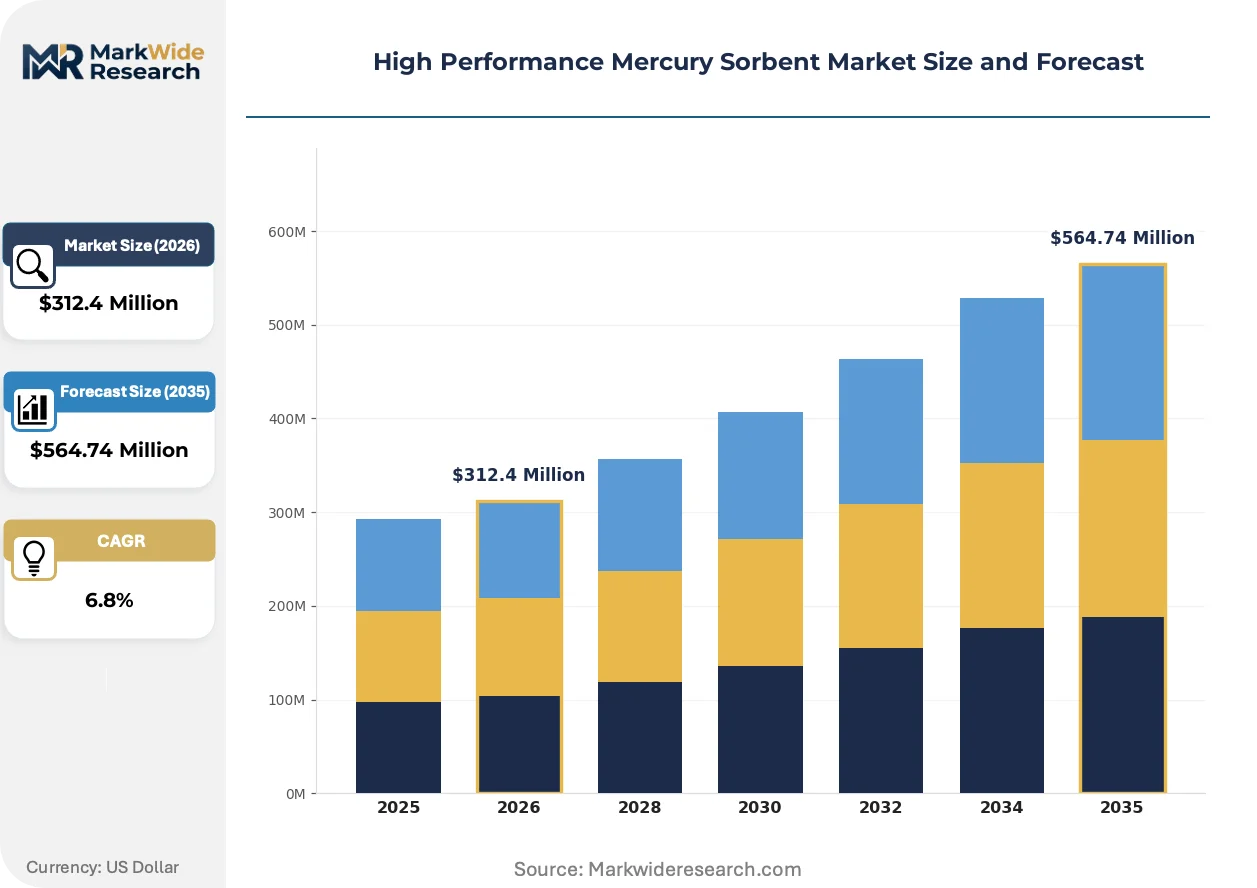
Market Dynamics
Activated carbon injection systems are consolidating procurement power among North American utilities retrofitting under EPA MATS compliance deadlines, compressing sorbent specification diversity into standardized sulfur-impregnated formulations.
Growth Catalysts
- EPA MATS Enforcement:Coal-fired utilities in the United States face binding mercury emission limits that mandate continuous sorbent injection, creating baseline demand for high-capacity activated carbon formulations.
- China MEE Standards:State-owned power generators under tightening thermal power emission rules in China are accelerating halogenated sorbent replacement with next-generation metal oxide systems.
- Cement Kiln Retrofits:European cement manufacturers facing EU Industrial Emissions Directive mercury caps are adopting dry sorbent injection for preheater exhaust streams.
Market Restraints
- Petroleum Coke Price Volatility:Activated carbon substrate costs fluctuate with calcined petroleum coke feedstock availability, squeezing margin stability for sorbent formulators.
- Chinese Supply Concentration:Over sixty percent of bromine-activated carbon precursor manufacturing concentrates in Shandong Province, exposing buyers to regional logistics disruptions.
- Halogenated Sorbent Phase-Out:Bromine-impregnated formulations face mounting regulatory friction under REACH authorization restrictions in European markets.
Strategic Opportunities
- Gold Mining Tailings:Artisanal and small-scale gold mining operations in Indonesia and Ghana present underpenetrated demand for regenerable metal oxide sorbents in retort off-gas treatment.
- EU Carbon Border Adjustment:The CBAM framework creates regulatory tailwind for mercury control technology exports to carbon-intensive industries in Eastern European accession states.
- Waste-to-Energy Expansion:Municipal waste incineration capacity additions across Poland and Turkey are opening procurement channels for multi-pollutant sorbent-catalyst bundles.
Industry Challenges
- Flue Gas Chemistry Expertise Gap:Utilities struggle to source process engineers capable of optimizing sorbent injection rates across variable coal sulfur content and load cycling.
- MATS Compliance Testing Delays:EPA stack testing protocols create twelve-to-eighteen-month certification timelines that stall retrofit project execution.
- Legacy Halogenated Inventory Stranding:Utilities holding pre-2020 brominated sorbent stocks face write-down pressure as state-level mercury limits tighten beyond original MATS floors.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Mercury Sorbent Market Trends and Innovations
Mercury capture technology is converging with multi-pollutant control architectures, forcing sorbent developers to engineer for simultaneous acid gas, particulate, and mercury removal rather than single-species optimization.
Metal oxide sorbents incorporating copper-iron spinel structures are integrating regenerable chemisorption capabilities that enable thermal reactivation in chlor-alkali plant mercury cell retrofits. Chemical process operators in Germany and Japan are piloting these systems to eliminate single-use carbon disposal costs. The technology is integrating closed-loop material flows that compress lifecycle expenditure below ten-year total cost thresholds for continuous-process industries.
China's MEE is tightening mercury emission monitoring requirements for thermal power stacks above 300 megawatts, mandating continuous emissions monitoring systems with hourly data transmission. This enforcement shift is forcing state-owned generators to upgrade from intermittent sorbent dosing to automated injection controls. Northeastern provincial grids are responding by consolidating procurement through central SOE purchasing platforms that standardize sulfur-impregnated carbon specifications.
Utility procurement departments are unbundling sorbent supply from installation engineering, creating separate contracting lanes for material, injection hardware, and performance guarantees. This fragmentation is compressing supplier margins while elevating the role of specialized system integrators in North American retrofit markets. The pattern is most visible in PJM Interconnection territory where merchant generators prioritize operational flexibility over bundled service contracts.
High Performance Mercury Sorbent Market Segmentation
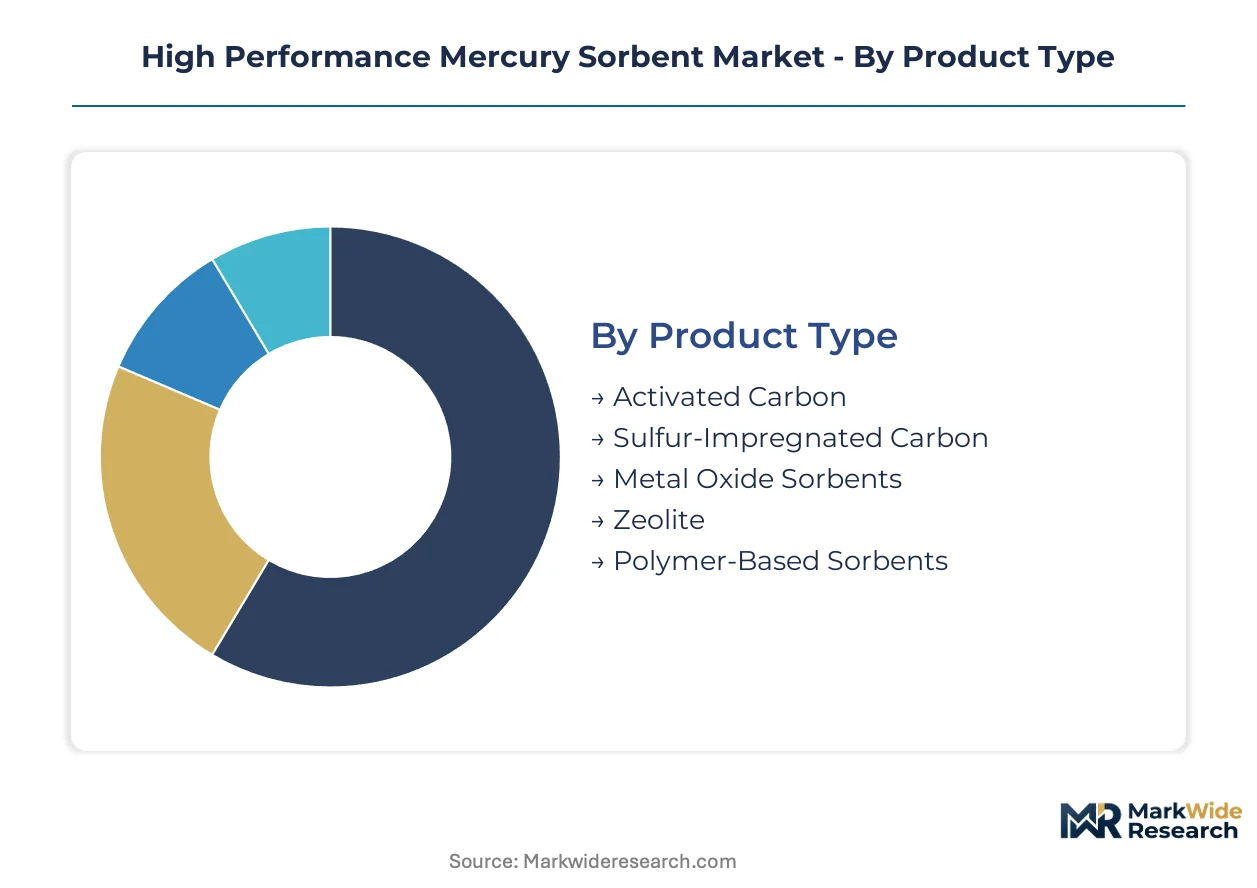
Mercury sorbent procurement patterns diverge sharply across product chemistry and deployment configuration, with retrofit timelines and regulatory enforcement intensity determining specification choices. Understanding these segment boundaries enables suppliers to align R&D investment with upgrade cycles that dominate utility and industrial purchasing decisions.
Product Type:
Replacement cycles for mercury capture materials accelerate as EPA MATS enforcement tightens and China's MEE standards force halogenated formulation retirements, reshaping procurement toward next-generation substrates.
- Activated Carbon:Standard activated carbon substrates serve as the baseline material for flue gas treatment, typically manufactured from calcined petroleum coke or coconut shell precursors. Coal-fired utilities in the United States anchor procurement volumes as MATS compliance deadlines compress specification diversity into standardized formulations.
- Sulfur-Impregnated Carbon:Sulfur-impregnated variants dominate current procurement due to proven chemisorption efficacy for elemental mercury capture across 120°C to 180°C operating windows. Northeastern Chinese provincial grids are consolidating procurement through state-owned enterprise purchasing platforms that standardize these specifications.
- Metal Oxide Sorbents:Copper-iron spinel structures enable thermal reactivation in continuous-process industries.
- Zeolite:Microporous aluminosilicate frameworks offer alternative capture mechanisms for specific flue gas chemistries.
- Polymer-Based Sorbents:Specialized polymer formulations target non-utility applications requiring tailored surface chemistry.
Sulfur-impregnated carbon sits at the top of the volume ranking, with metal oxide sorbents climbing the fastest.
Application:
End-use concentration patterns reflect regulatory enforcement geography, with binding emission limits in specific jurisdictions determining where sorbent demand materializes.
- Coal-Fired Power Generation:Flue gas treatment systems at thermal power plants represent the foundational demand segment, with continuous sorbent injection mandated under binding mercury emission limits. United States utilities retrofitting under EPA MATS deadlines generate baseline procurement for high-capacity activated carbon formulations.
- Waste Incineration:Municipal waste-to-energy facilities require mercury control for combustion exhaust streams, with capacity additions across Poland and Turkey opening procurement channels for multi-pollutant sorbent-catalyst bundles.
- Chlor-Alkali Production:Mercury cell retrofits in Germany and Japan are piloting regenerable metal oxide systems to eliminate single-use carbon disposal costs.
- Cement Manufacturing:European cement producers facing EU Industrial Emissions Directive mercury caps adopt dry sorbent injection for preheater exhaust streams.
- Gold Mining:Artisanal and small-scale operations in Indonesia and Ghana present underpenetrated demand for regenerable sorbents in retort off-gas treatment.
Coal-fired power generation commands the largest installed base, though waste incineration is expanding most quickly.
End User Industry:
Customer capability maturity varies across industrial sectors, with procurement sophistication determining whether buyers prioritize unit sorbent cost or total lifecycle expenditure.
- Energy Producers:Electric utilities and independent power producers operate the most standardized procurement processes, with PJM Interconnection merchant generators unbundling sorbent supply from installation engineering.
- Chemical Manufacturers:Chlor-alkali and specialty chemical operators prioritize regenerable systems where closed-loop material flows compress ten-year total cost thresholds.
- Metal Refiners:Gold mining and non-ferrous smelting operations face process-specific mercury exposure requiring customized capture solutions.
- Construction Materials Suppliers:Cement and lime producers confront mercury caps in kiln exhaust with retrofit-driven procurement timing.
Energy producers maintain the deepest procurement volumes, while chemical manufacturers are gaining share fastest.
Deployment Mode:
Capital availability and operational continuity requirements dictate whether facilities adopt low-injection retrofits or engineered reactor systems.
- Dry Sorbent Injection:Minimal capital requirements for retrofit installations make this the dominant deployment mode, with pneumatic injection systems feeding sorbent into flue gas ducts upstream of particulate control devices.
- Fixed Bed Reactors:Engineered containment systems command premium pricing in continuous-process chemical manufacturing where operational continuity justifies higher upfront investment.
- Fluidized Bed Reactors:Suspended particle contact configurations serve specific process gas conditions requiring enhanced mass transfer.
- Regenerable Systems:Thermal reactivation capabilities enable material reuse, attracting chlor-alkali operators seeking to eliminate disposal cost streams.
Dry sorbent injection holds the largest deployment share, with regenerable systems showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers specializing in flue gas treatment cluster around coal basins and industrial corridors where mercury control retrofit activity concentrates procurement expertise.
United States
Coal-fired utilities in the PJM Interconnection and Southwest Power Pool drive sorbent procurement as EPA MATS enforcement tightens. The EPA stack testing protocols create twelve-to-eighteen-month certification timelines that compress retrofit schedules. Merchant generators in Texas and Illinois unbundle sorbent supply from installation engineering to prioritize operational flexibility.
China
State-owned power generators in Shandong and Shanxi provinces face MEE emission limits for thermal power stacks above 300 megawatts. The Ministry of Ecology and Environment mandates continuous emissions monitoring with hourly data transmission. Northeastern provincial grids consolidate procurement through central SOE purchasing platforms that standardize sulfur-impregnated carbon specifications.
Germany
Chlor-alkali operators in the Rhine-Ruhr industrial region pilot regenerable metal oxide systems to eliminate single-use carbon disposal costs. REACH authorization restrictions on halogenated formulations accelerate phase-out timelines. Chemical process manufacturers in Ludwigshafen and Leverkusen integrate closed-loop material flows that compress lifecycle expenditure below ten-year thresholds.
Poland
Municipal waste incineration capacity additions in Warsaw and Krakow open procurement channels for multi-pollutant sorbent-catalyst bundles. The EU Industrial Emissions Directive mercury caps apply to new waste-to-energy installations. Cement manufacturers in the Silesian Voivodeship adopt dry sorbent injection for preheater exhaust streams.
Japan
Chlor-alkali plant mercury cell retrofits in the Keihin industrial corridor test regenerable copper-iron spinel sorbents for thermal reactivation. METI industrial emission guidelines shape procurement specifications for continuous-process industries. Chemical manufacturers in the Chubu region evaluate closed-loop systems to reduce material disposal liabilities.
High Performance Mercury Sorbent Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates with polymer chemistry expertise, mineral sourcing specialists with captive bromine assets, and catalyst system integrators offering multi-pollutant bundles. Competitive moves concentrate on backward integration into precursor manufacturing and technology licensing partnerships for regenerable system deployment.
Among Germany-based diversified chemical conglomerates, BASF represents the polymer chemistry specialist archetype with capabilities extending to tailored sorbent formulations. Albemarle Corporation anchors the mineral-integrated tier through bromine-activated carbon technology positioning and captive sourcing structures. Johnson Matthey occupies the system integrator position with multi-pollutant control architectures that combine catalyst and sorbent functionality.
| Leading Market Players |
|---|
| BASF |
| Albemarle Corporation |
| Johnson Matthey |
| Honeywell |
| Calgon Carbon Corporation |
| Axens |
| Ecolab |
| Norit |
| NEI |
| Others |
Pricing and Supply Chain Analysis
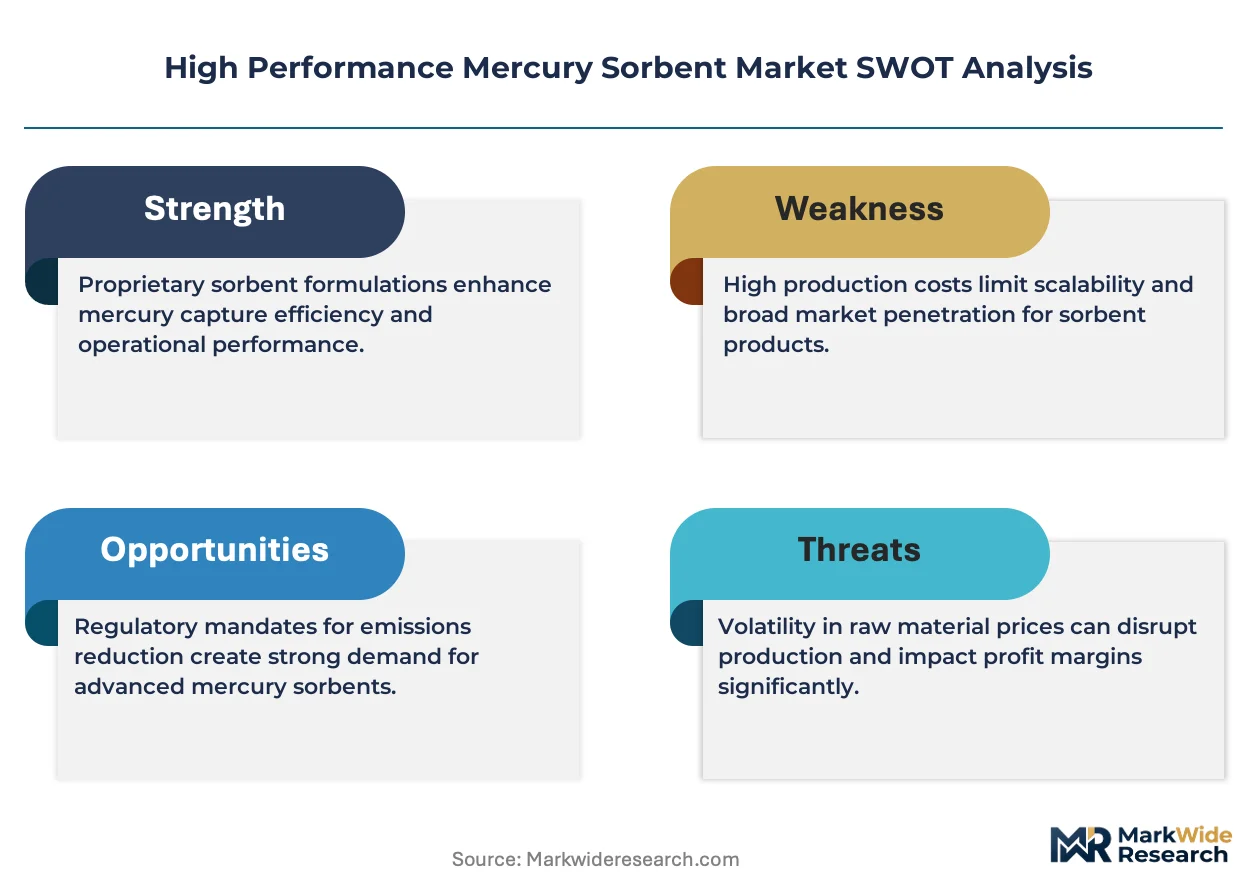
Halogenated sorbent phase-outs under REACH authorization restrictions are simultaneously compressing formulation margins and accelerating supplier consolidation toward sulfur-impregnated carbon specialists with captive precursor access. This chemistry transition rewards integrated producers while squeezing standalone formulators dependent on spot-market petroleum coke feedstock.
Pricing Analysis
The bundled-vs-unbundled service split now defines transaction structures, with PJM Interconnection merchant generators unbundling sorbent supply from installation engineering to prioritize operational flexibility. Pricing stratifies across performance-guaranteed, specification-standard, and commodity-injection tiers, with quality grade and volume scale as primary differentiation drivers. Cost compression in standard sulfur-impregnated formulations is intensifying because northeastern Chinese SOE purchasing platforms consolidate procurement into centralized tenders. Cement manufacturers and waste incineration operators exhibit highest price sensitivity due to retrofit-driven capital constraints, while chlor-alkali producers prioritize lifecycle cost over unit pricing for regenerable systems.
Supply Chain Analysis
Process engineering talent shortages in Shandong Province and the Rhine-Ruhr industrial region constrain activated carbon precursor expansion despite demand acceleration. Manufacturing concentrates in China, the United States, and Germany, with supply chains drawing from calcined petroleum coke, coconut shell char, and bromine derivatives as critical inputs. Single-source vulnerability in Shandong's bromine-activated carbon precursor base exposes buyers to regional logistics disruptions. Distribution runs through direct utility procurement channels, system integrator partnerships, and state-owned enterprise central purchasing platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The High Performance Mercury Sorbent Market functions as a stable compounder, with EPA MATS enforcement and China's MEE standards creating durable baseline demand that resists cyclical downturns.
For Market Incumbents: Deploy backward integration into calcined petroleum coke and coconut shell precursor production to defend margin position against feedstock volatility. BASF and Albemarle Corporation should accelerate polymer chemistry and bromine-captive sourcing respectively, while consolidating halogenated formulation retirements to avoid inventory stranding as REACH restrictions tighten.
For New Entrants and Emerging Players: System integrators lacking sorbent manufacturing represent the most accessible channel partner type for technology licensing arrangements. Artisanal gold mining operations in Indonesia and Ghana offer the most penetrable white-space, with regenerable metal oxide sorbents addressing disposal cost pain points. Municipal waste incineration procurement channels in Poland and Turkey provide secondary entry via multi-pollutant bundle positioning.
For Investors and Strategic Acquirers: Roll-up economics work for specialized metal oxide sorbent developers because regenerable system adoption in chlor-alkali and gold mining compresses customer acquisition costs through reference selling. The five-to-ten-year viability window favors platform consolidation around copper-iron spinel technology leaders. Monitor EPA stack testing protocol backlogs as the critical inflection signal—accelerated certification timelines would unlock retrofit project execution and sorbent procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Captive petroleum coke supply insulates margin stability against calcined feedstock price spikes. |
| Regenerable System Technology Licensing | Copper-iron spinel patents enable penetration of chlor-alkali mercury cell retrofit demand in Germany and Japan. |
| Multi-Pollutant Bundle Development | Combined catalyst-sorbent offerings capture waste-to-energy procurement in Poland and Turkey. |
| SOE Purchasing Platform Alignment | Standardized sulfur-impregnated specifications secure volume allocation in northeastern Chinese provincial grids. |
| Artisanal Mining Channel Partnership | Retort off-gas treatment distributors in Indonesia and Ghana open regenerable sorbent adoption. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade flow databases, and technical specification audits — were reconciled against primary fieldwork. Plant managers at coal-fired utilities, procurement leads at chlor-alkali operators, EPC contractors specializing in flue gas treatment, and distribution channel partners provided operational validation. Secondary sources included EPA enforcement databases, MEE emission standard disclosures, EU ETS installation records, customs trade statistics, and SEC 10-K filings from diversified chemical conglomerates. Bottom-up capacity modeling and top-down demand projection were triangulated to constrain estimate variance.
Data-stream reconciliation across the projection horizon applied segment-specific growth coefficients derived from regulatory compliance timelines. The analytical framework modeled chemistry type, deployment configuration, end-use industry, and geographic enforcement intensity as core segmentation dimensions. CAGRs were computed from installed base turnover rates and replacement cycle acceleration under tightening emission limits. Forecast inputs incorporated MATS compliance deadline clustering, MEE continuous monitoring mandates, and REACH authorization phase-out schedules.
Revisions become necessary when regulatory enforcement intensity shifts, flue gas chemistry alterations from carbon capture retrofits materialize, or petroleum coke feedstock availability constrains precursor supply. Forecasts reflect assumptions about standard adoption curves and technology substitution elasticities. Material deviation in EPA stack testing timelines, Chinese SOE procurement centralization velocity, or bromine supply chain disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.