
 Sodium Phosphate Tribasic Market | 2026-2036
Sodium Phosphate Tribasic Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Phosphate Tribasic Market Analytics
EU Green Deal phosphate recovery targets are expanding the addressable market for reclaimed tribasic sodium phosphate in fertilizer and industrial applications. PhosAgro Group leverages captive phosphate rock reserves to sustain cost leadership across European and Asian supply lanes. Prayon S.A. specializes in high-purity food-grade production, occupying premium positions in bakery and dairy additive markets. ICL Group Ltd. anchors North American distribution through integrated logistics networks serving municipal water treatment operators.
Sodium phosphate tribasic, chemically formulated as Na₃PO₄ with anhydrous and dodecahydrate variants, functions primarily as an alkalizing agent, sequestrant, and water softener in industrial and food systems. Industrial grade dominates volume flows into boiler water treatment and metal surface preparation, while pharmaceutical grade commands margin concentration due to stringent USP and EP certification requirements. Food-grade demand clusters around pH buffering and emulsifying applications in processed cheese and meat systems, with antioxidant functionality gaining traction in clean-label formulations.
EPA effluent guidelines limit phosphate discharge from metal finishing operations, compelling US manufacturers to optimize tribasic sodium phosphate dosing in closed-loop systems. EFSA reviews of phosphate additive safety in processed foods are reshaping formulation thresholds across EU member states, while China's GB standards govern industrial-grade specifications for domestic chemical manufacturing. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging purity and sustainability mandates.
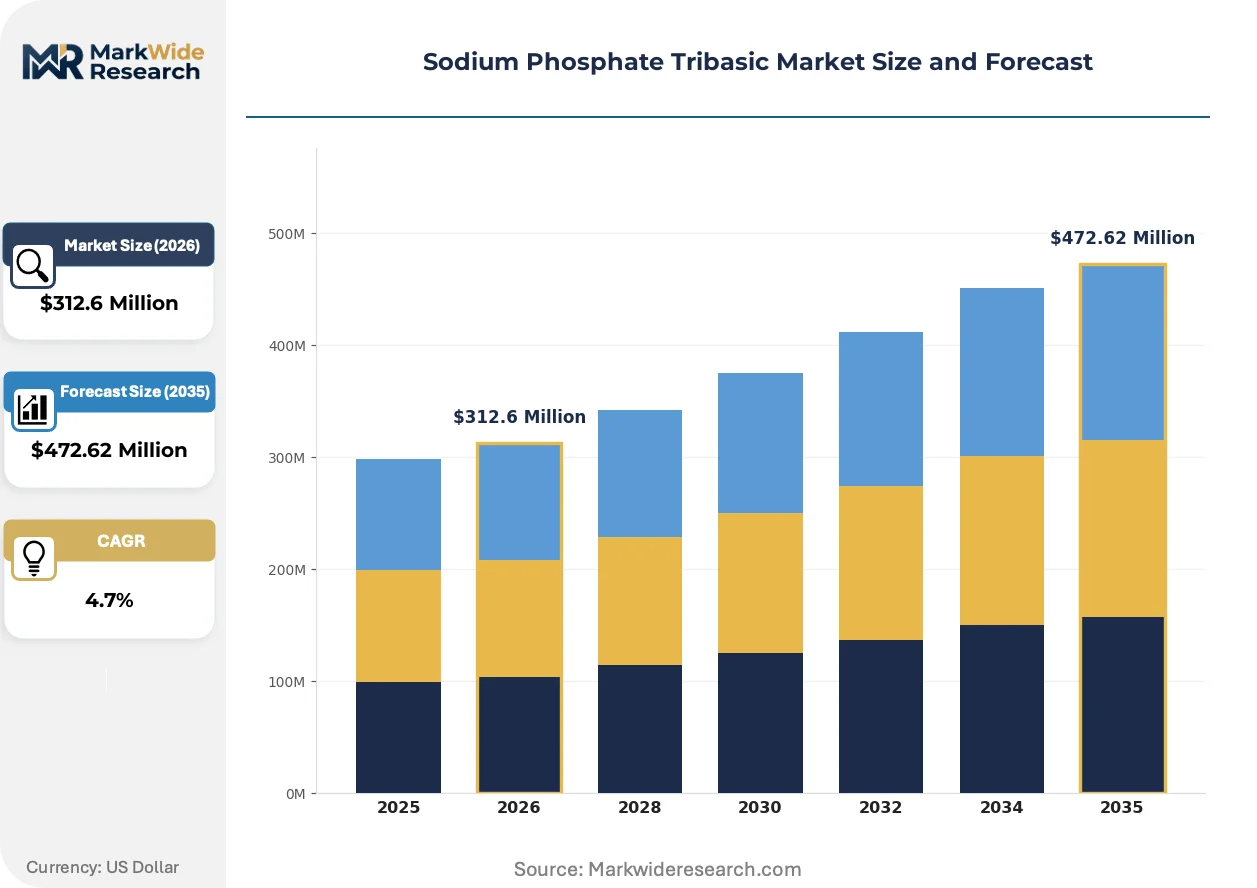
Market Dynamics
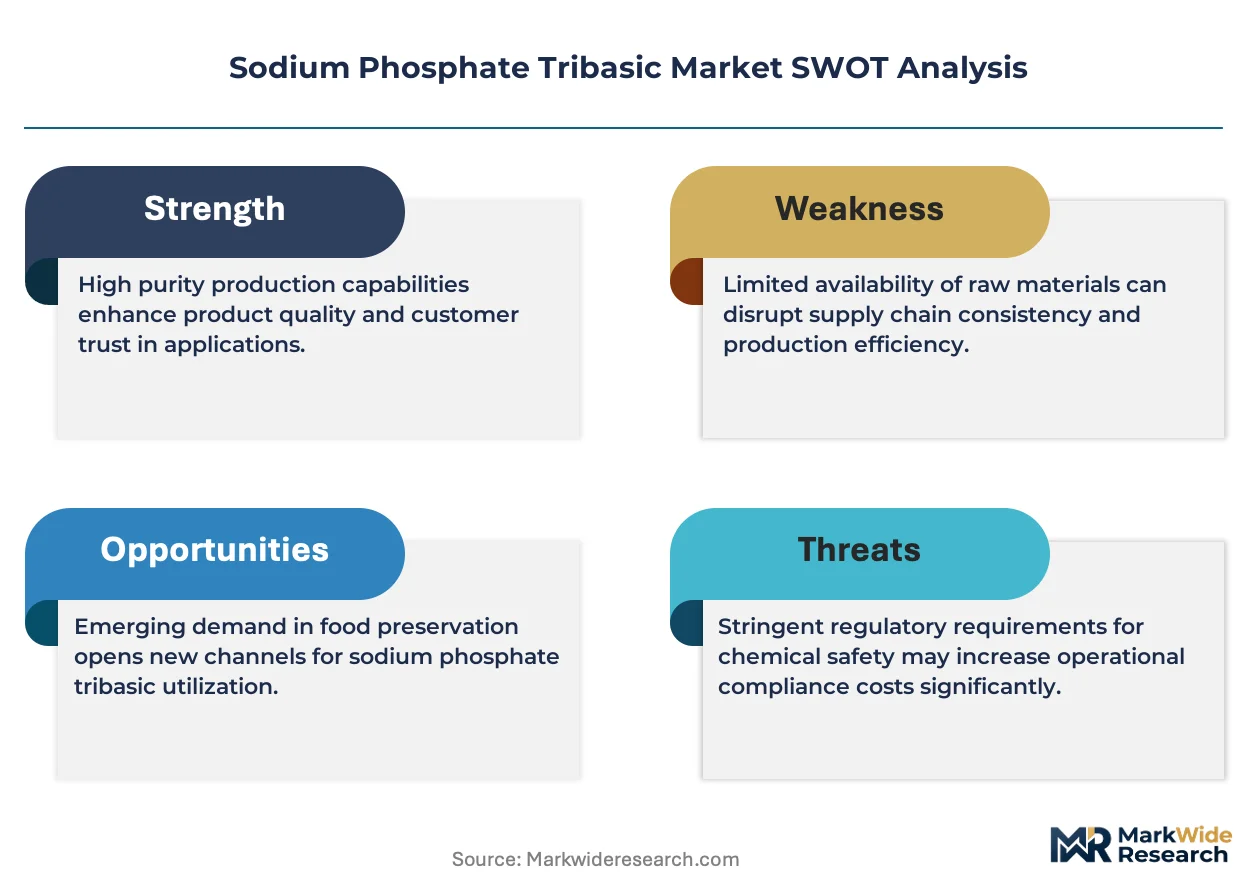
REACH compliance in Europe is tightening purity thresholds for phosphate compounds used in food-contact materials, forcing producers to reconfigure purification processes and redirect industrial-grade capacity toward higher-margin pharmaceutical and food-grade streams.
Growth Catalysts
- Boiler water treatment expansion:Water treatment facilities in the United States are expanding procurement of industrial-grade tribasic sodium phosphate for boiler and cooling tower applications, driven by aging infrastructure replacement cycles.
- EU Green Deal phosphate recovery:EU Green Deal phosphate recovery targets are expanding the addressable market for reclaimed tribasic sodium phosphate in fertilizer and industrial applications across member states.
- China's chemical manufacturing corridor:Demand is concentrating in China's chemical manufacturing corridor, where domestic producers supply regional detergent and fertilizer formulators with cost-competitive industrial-grade material.
Market Restraints
- Phosphate rock supply concentration:Captive phosphate rock reserves concentrate upstream supply leverage with a handful of integrated producers, limiting cost-competitive entry for standalone tribasic sodium phosphate manufacturers.
- EPA effluent discharge limits:EPA effluent guidelines limit phosphate discharge from metal finishing operations, compelling US manufacturers to optimize dosing in closed-loop systems rather than expanding consumption.
- Alternative sequestrants:Zeolite-based and polyacrylate water softeners are displacing tribasic sodium phosphate in select laundry detergent formulations, particularly in Nordic markets with stringent ecolabel requirements.
Strategic Opportunities
- Clean-label antioxidant positioning:Antioxidant functionality in tribasic sodium phosphate is gaining traction in clean-label processed meat and cheese formulations, opening premium pricing tiers previously occupied by synthetic alternatives.
- Reclaimed phosphate valorization:Municipal wastewater treatment plants in Germany and the Netherlands are installing struvite recovery units, creating new feedstock streams for fertilizer-grade tribasic sodium phosphate production.
- Direct-to-formulator digital channels:Specialty chemical distributors are launching digital procurement platforms for mid-volume food and pharmaceutical formulators, compressing traditional multi-tier distribution margins.
Industry Challenges
- USP and EP certification timelines:Pharmaceutical-grade qualification requires 18-24 month stability validation protocols, creating working capital intensity and customer lock-in risk during qualification gaps.
- Legacy boiler system incompatibility:Industrial water treatment operators face integration complexity when retrofitting automated phosphate dosing controllers onto pre-1990 boiler infrastructure with analog control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Phosphate Tribasic Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $472.62 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Laboratory Grade End User: Food Industry, Pharmaceutical Industry, Chemical Manufacturing, Agriculture Application: pH Buffering, Nutrient Supplement, Antioxidant, Emulsifying Agent Packaging Type: Bulk Bags, Bottles, Drums, Pails |
| Companies Covered | Innophos Holdings, Inc., PhosAgro Group, Prayon S.A., ICL Group Ltd., The Mosaic Company, WENGFU GROUP CO. LTD., Yuntianhua Co., Ltd., Hubei Xingfa Chemicals Group Co. Ltd., Guizhou Sino-Phos Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Phosphate Tribasic Market Evolving Landscape
Process intensification and regulatory stringency are converging to reshape how tribasic sodium phosphate is manufactured, purified, and specified across industrial, food, and pharmaceutical tiers.
Membrane filtration-crystallization hybrid systems are modularizing production lines for food-grade tribasic sodium phosphate, enabling producers to switch between anhydrous and dodecahydrate variants within single-shift changeovers. European and North American specialty chemical manufacturers are adopting these systems to reduce energy intensity and water consumption. This modularizing capability is compressing minimum efficient scale thresholds, allowing regional producers to challenge commodity importers on lead time and customization.
EFSA reviews of phosphate additive safety in processed foods are reshaping formulation thresholds across EU member states, with draft opinions suggesting reduced acceptable daily intake levels for certain population segments. Food manufacturers are responding by reformulating with lower phosphate loads or seeking alternative emulsifying systems in processed cheese and meat applications. The dairy additive segment faces the most immediate reformulation pressure, with several major processors accelerating clean-label transition timelines ahead of final guidance publication.
Buyer concentration among multinational detergent and fertilizer formulators is compressing contract negotiation cycles and unbundling technical service from base chemical supply. Procurement teams at major European and Asian formulators are shifting toward multi-year framework agreements with indexed pricing and dedicated volume allocations, displacing spot-market purchasing for industrial-grade material. This pattern is most visible in Germany and China's Yangtze River Delta, where integrated chemical parks enable just-in-time delivery coordination.
Sodium Phosphate Tribasic Market Segmentation
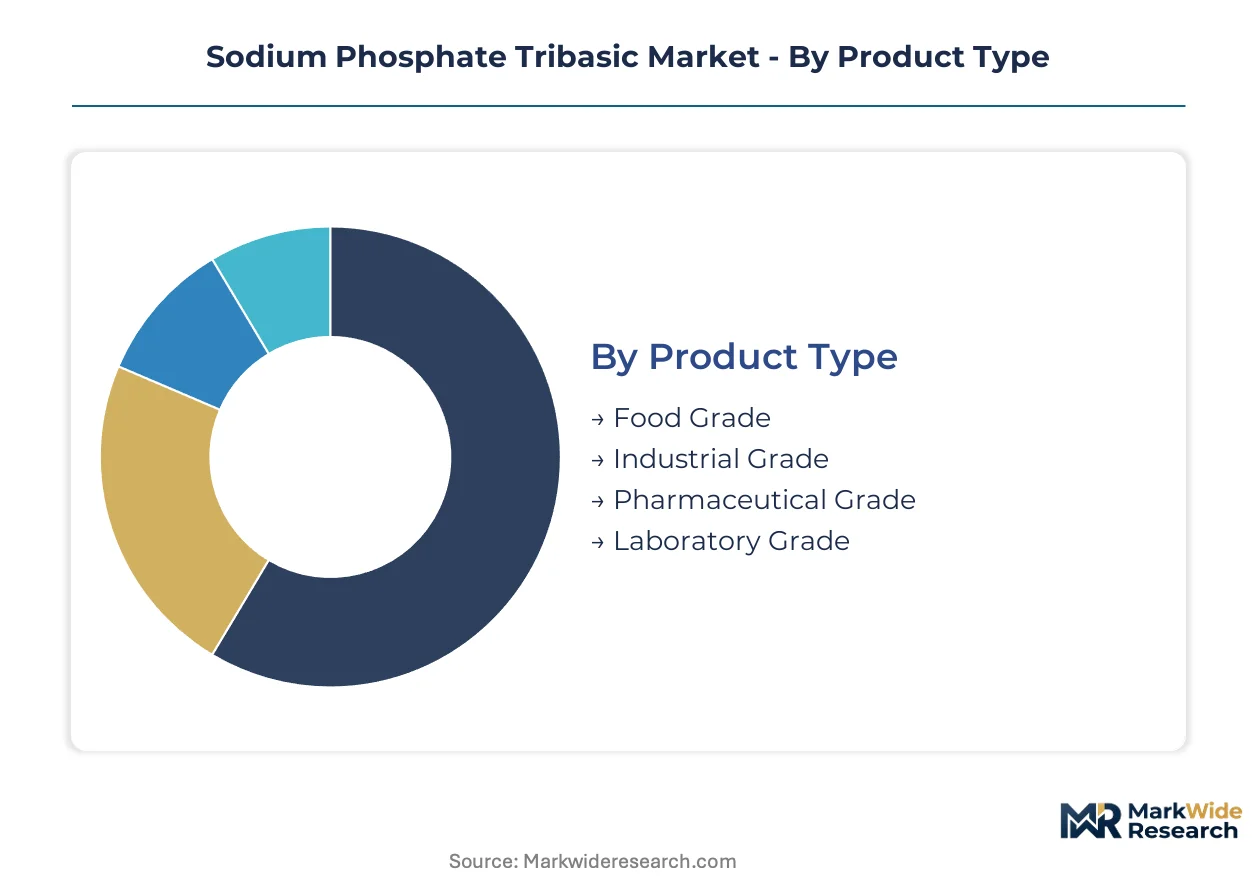
Segmentation in sodium phosphate tribasic reflects divergent purity mandates across regulatory jurisdictions. Product grade determines specification stringency, while end-use application dictates volume scale and margin structure.
Product Type:
Customization intensity escalates from commodity industrial grades through certified pharmaceutical tiers, with purification protocols and documentation requirements expanding proportionally.
- Industrial Grade:Technical-grade Na₃PO₄ serves boiler water treatment and metal surface preparation with moderate purity thresholds. Demand concentrates in United States municipal water facilities replacing aging infrastructure, though EPA effluent limits constrain discharge-intensive applications.
- Food Grade:Refined tribasic sodium phosphate meets FDA and EFSA purity standards for pH buffering and emulsification in processed cheese and meat systems. China's domestic producers supply regional dairy processors with cost-competitive material certified under GB standards.
- Pharmaceutical Grade:USP and EP-certified material requires 18-24 month stability validation protocols.
- Laboratory Grade:ACS-specification material serves analytical chemistry and research applications with batch-level traceability.
Most installed capacity flows through Industrial Grade. Expansion is steepest in Pharmaceutical Grade.
End User:
Volume concentration versus margin capture varies sharply across customer categories, with procurement scale inversely correlating to specification intensity.
- Chemical Manufacturing:Large-scale detergent and fertilizer formulators consume industrial-grade tribasic sodium phosphate in continuous-process operations. Germany's integrated chemical parks and China's Yangtze River Delta corridor anchor procurement concentration, with buyers shifting toward multi-year framework agreements.
- Food Industry:Processed cheese and meat processors utilize food-grade material for pH control and emulsification. EFSA draft opinions on reduced acceptable daily intake levels are accelerating reformulation timelines across EU dairy operations.
- Pharmaceutical Industry:Parenteral and oral dosage form manufacturers require certified material with documented stability data.
- Agriculture:Fertilizer blenders incorporate reclaimed phosphate from struvite recovery units in Germany and the Netherlands.
Chemical Manufacturing commands the largest volume share. Pharmaceutical Industry delivers the steepest margin expansion trajectory.
Application:
Functional role determines formulation load and substitution vulnerability, with antioxidant positioning gaining premium traction in clean-label segments.
- pH Buffering:Alkalizing functionality stabilizes processed food systems and industrial water chemistry. Boiler water treatment facilities in the United States specify tribasic sodium phosphate for alkalinity control, though legacy analog control architectures complicate automated dosing retrofits.
- Emulsifying Agent:Protein interaction properties enable fat dispersion in processed cheese and meat applications. Nordic markets with stringent ecolabel requirements are displacing phosphate emulsifiers with alternative systems in select detergent formulations.
- Antioxidant:Metal chelation properties extend shelf life in clean-label processed meat formulations.
- Nutrient Supplement:Phosphorus bioavailability supports agricultural fertilizer and animal feed applications.
pH Buffering accounts for the majority of installed demand. Antioxidant functionality is climbing the fastest as clean-label reformulation accelerates.
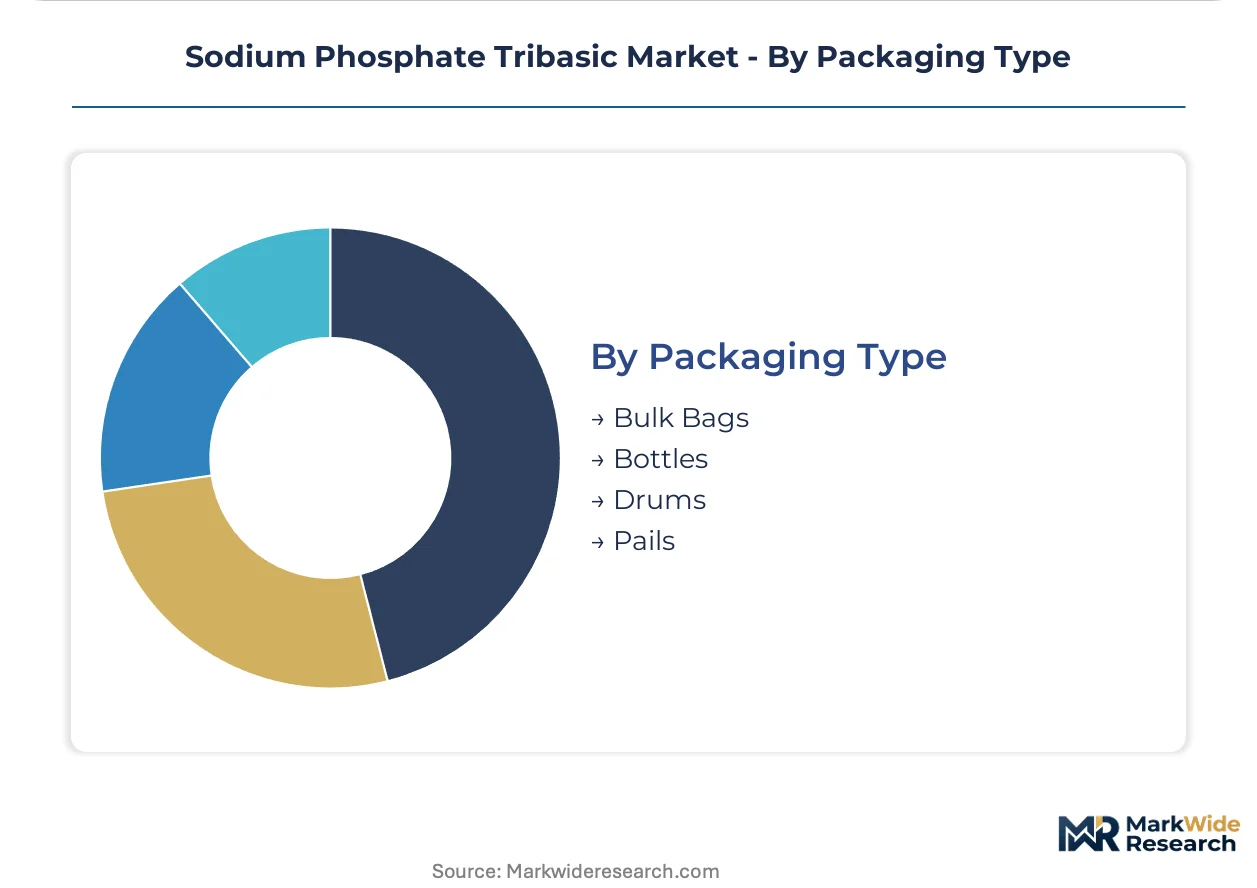
Packaging Type:
Logistics configuration aligns with customer scale and handling infrastructure, with bulk formats dominating integrated chemical park deliveries.
- Bulk Bags:One-ton flexible intermediate bulk containers serve high-volume chemical manufacturing and agriculture customers with pneumatic conveying systems. China's domestic producers leverage bulk format economics for regional detergent and fertilizer corridor deliveries.
- Drums:Steel and fiber drums provide intermediate-scale containment for food and pharmaceutical processors with batch handling requirements.
- Bottles:Laboratory-grade material in container sizes from 500g to 25kg serves analytical and research applications.
- Pails:Plastic pails offer stackable containment for mid-volume food industry customers with limited bulk handling infrastructure.
Bulk Bags move the largest volume tonnage. Bottles deliver the highest unit margin realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The sodium phosphate tribasic industry traces its modern scale to nineteenth-century German chemical engineering, with Leverkusen and Ludwigshafen establishing the first integrated phosphate processing complexes that supplied European textile and metallurgical industries.
United States
Municipal water treatment facilities across the Rust Belt and Sun Belt are replacing aging boiler infrastructure, driving procurement of industrial-grade tribasic sodium phosphate for alkalinity control. EPA effluent guidelines constrain discharge-intensive metal finishing applications, compelling closed-loop system optimization. The Gulf Coast petrochemical corridor anchors domestic production capacity serving regional formulators.
Germany
Integrated chemical parks in North Rhine-Westphalia and Lower Saxony coordinate just-in-time deliveries to detergent and fertilizer formulators shifting toward multi-year framework agreements. EU Green Deal phosphate recovery targets are expanding struvite valorization from municipal wastewater plants in the Netherlands and Germany into fertilizer-grade feedstock. The country's national chemical regulator enforces REACH compliance thresholds for food-contact material purity.
China
Domestic producers in the Yangtze River Delta and Sichuan-Chongqing corridor supply regional detergent and fertilizer formulators with cost-competitive industrial-grade material. GB standards govern industrial-grade specifications for chemical manufacturing applications. Yunnan and Guizhou provinces concentrate phosphate rock mining operations feeding downstream tribasic sodium phosphate synthesis.
Netherlands
Municipal wastewater treatment operators in Rotterdam and Amsterdam are installing struvite recovery units, creating reclaimed phosphate feedstock streams for fertilizer-grade production. The country's national environmental agency coordinates with German counterparts on cross-border phosphate recovery logistics. The Port of Rotterdam serves as a distribution hub for European industrial-grade material flows.
India
Detergent manufacturers in Gujarat and Maharashtra are expanding phosphate-based formulation capacity for domestic and export markets. The Bureau of Indian Standards governs industrial chemical purity specifications. The Mumbai-Pune industrial corridor concentrates mid-scale tribasic sodium phosphate processing operations serving regional food and pharmaceutical formulators.
Sodium Phosphate Tribasic Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and geographic integration dimensions, with pharmaceutical-grade certification and captive phosphate rock reserves defining tier boundaries. The market exhibits moderate concentration, with integrated mining-chemical conglomerates controlling upstream leverage while regional specialists compete on lead time and customization. Three archetypes dominate: vertically integrated phosphate rock holders, high-purity food-grade specialists, and regional commodity processors serving domestic detergent corridors. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing long-term offtake agreements to defend volume positions.
Within the integrated mining-chemical tier, PhosAgro Group exemplifies upstream control through captive phosphate rock reserves spanning European and Asian supply lanes. Prayon S.A. and ICL Group Ltd. occupy positions on the high-purity and distribution-anchored vectors respectively, with the former representing food-grade specialization and the latter exemplifying North American logistics integration. Among Asia-Pacific-based producers, WENGFU GROUP CO. LTD. and Yuntianhua Co., Ltd. sit within the scale-driven commodity tier serving regional formulator demand.
| Leading Market Players |
|---|
| Innophos Holdings, Inc. |
| PhosAgro Group |
| Prayon S.A. |
| ICL Group Ltd. |
| The Mosaic Company |
| WENGFU GROUP CO. LTD. |
| Yuntianhua Co., Ltd. |
| Hubei Xingfa Chemicals Group Co. Ltd. |
| Guizhou Sino-Phos Chemical Co. Ltd. |
| Others |
Value Network & Pricing Analysis
EU Green Deal phosphate recovery mandates gate qualified supply access and premium-tier pricing power by requiring documented circular-economy provenance for fertilizer-grade material. Buyers in Germany and the Netherlands pay structural premiums for reclaimed tribasic sodium phosphate certified under struvite recovery protocols, while industrial-grade spot markets in China's Yangtze River Delta corridor trade at cost-parity levels constrained by phosphate rock input volatility.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, food, and industrial grades anchors transaction economics, with USP and EP certification commanding the widest spreads over technical-grade material. Price differentiation rests on purity validation protocols and captive phosphate rock access, with PhosAgro Group leveraging upstream reserves to undercut standalone processors. Cost compression in industrial-grade streams is intensifying because Chinese domestic producers are expanding dodecahydrate capacity. Detergent formulators in Germany's chemical parks exhibit the highest price sensitivity, while parenteral pharmaceutical manufacturers accept premium pricing for documented stability data.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Shanghai coordinate hub-and-spoke deliveries to downstream formulators with just-in-time inventory protocols. Supply concentrates in China, Russia, and Morocco through phosphate rock mining corridors that feed downstream tribasic sodium phosphate synthesis. Raw material dependencies include phosphate rock concentrate, caustic soda, and thermal energy inputs. Single-source vulnerability runs through Morocco's OCP Group and Russian phosphate holdings amid trade restriction uncertainty. Distribution runs through integrated chemical parks in Germany and China's Yangtze River Delta with pneumatic bulk handling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-compliant European premiums and cost-optimized Chinese industrial-grade output, with regulatory compliance cost differentials exceeding purification technology gaps.
For Market Incumbents: To counter zeolite-based sequestrant displacement in Nordic detergent markets, PhosAgro Group and Prayon S.A. should deepen backward integration into struvite recovery feedstocks and secure multi-year framework agreements with Rotterdam-anchored distributors. Certification investment in pharmaceutical-grade capacity buffers margin erosion in commoditized industrial streams. For New Entrants and Emerging Players: Capture the reclaimed phosphate valorization segment in the Netherlands and Germany by installing modular membrane filtration-crystallization systems sized for municipal wastewater struvite offtake. Municipal procurement officers in Rotterdam and Amsterdam represent the most penetrable buyer archetype given EU Green Deal mandate alignment. A direct-to-formulator digital channel bypasses incumbent distributor markups for mid-volume food-grade customers. For Investors and Strategic Acquirers: Roll-up economics work for regional pharmaceutical-grade specialists because USP and EP certification timelines create 18-24 month customer lock-in windows that deter switching. Long-term viability hinges on phosphate rock reserve access or circular-economy feedstock positioning. Watch EFSA final guidance on processed food phosphate thresholds as the signal for accelerated clean-label reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Struvite Recovery | EU Green Deal compliance secures premium-tier pricing for fertilizer-grade output in Germany and the Netherlands. |
| Pharmaceutical-Grade Capacity Expansion | USP certification opens parenteral dosage form markets with structural margin protection against industrial-grade commoditization. |
| Long-term Supply Agreement with Municipal Water Operators | Indexed pricing frameworks with Rust Belt boiler treatment facilities lock in volume against spot-market volatility. |
| Membrane Filtration-Crystallization Modularization | Single-shift changeover capability between anhydrous and dodecahydrate variants challenges commodity importer lead times. |
| Direct-to-Formulator Digital Platform Launch | Compression of multi-tier distribution margins captures mid-volume food and pharmaceutical processor procurement. |
Research Methodology
Direct dialogue with phosphate plant managers, detergent procurement leads at European formulators, distribution channel partners in Rotterdam and Houston, and technical R&D directors at specialty chemical manufacturers grounded qualitative findings. Secondary validation drew from customs and trade data, Cefic chemical industry reports, SEC 10-K filings of listed phosphate producers, and EPA effluent guideline documentation. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators to ensure cross-method consistency.
Segment-level volume and value estimates emerged from disaggregated modeling across product grade tiers, end-use industry categories, packaging format types, and regional production hub clusters. CAGRs were derived from regression analysis of historical consumption patterns and forward-projected regulatory mandate implementation timelines. Key forecast inputs included REACH compliance cost trajectories, EFSA additive safety review schedules, and China's GB standards enforcement intensity across provincial chemical manufacturing corridors.
Underlying measurement precision varies by segment; pharmaceutical-grade and food-grade categories carry tighter precision than commodity industrial-grade flows given certification documentation density. Forecasts reflect documented assumptions regarding regulatory implementation timelines and phosphate rock supply continuity. Decision-makers should treat outputs as directional within the stated assumption set, acknowledging that EPA effluent guideline revisions or EFSA threshold determinations could materially revise demand trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Airbag Propellant Chemicals Market
Chemicals
Sodium Aluminum Hydride Market
Chemicals
Southeast Asia Construction Chemicals Market
Chemicals
Waterborne Curing Agents Market
Chemicals
Cyclopentylamine Market
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Global Organobromine Market
Chemicals
4-Methyl-2-Pentanone Market
Chemicals
6 Hexanediol Market
Chemicals
Isopropyl Alcohol (IPA) Market
Chemicals
SLS and LABSA Market
Chemicals
Brazil Methanol Market
Chemicals
Bakers Ammonia Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Pyromellitic Dianhydride Market