
 Global Posture Corrector Market | 2026-2036
Global Posture Corrector Market Size, Share, and Industry Trends Forecast 2026-2036
Global Posture Corrector Market Foresight
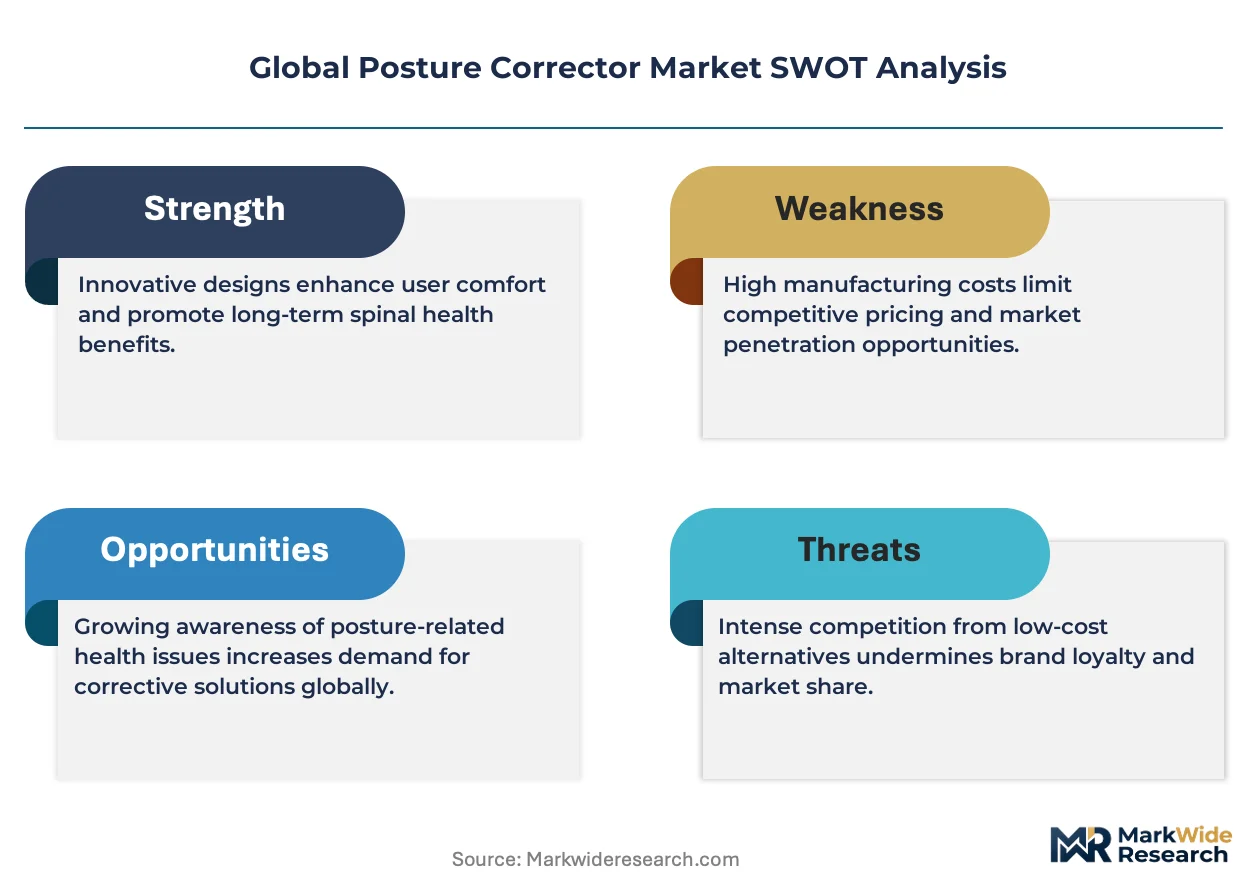
Multi-source material procurement is pivoting toward vertically integrated neoprene and nylon production as tariff exposure reshapes supplier strategies. Swedish Posture anchors its Nordic manufacturing base to sustain premium positioning across European physiotherapy channels. Ottobock leverages its orthopedic technology heritage to dominate the medical-grade back brace segment. Comfy Brace competes through direct-to-consumer online distribution, bypassing traditional retail markups entirely.
A posture corrector is a biomechanical support garment engineered to realign spinal curvature and redistribute musculoskeletal load, typically constructed from breathable neoprene blends with adjustable tension straps and rigid or semi-rigid stays. These devices functionally reduce kyphotic stress and cervical strain during prolonged static positioning, serving both preventive wellness and post-injury rehabilitation applications. Back braces occupy the largest revenue pool due to chronic lower back pain prevalence, while shoulder supports represent the fastest-expanding category driven by athletic training adoption and rotator cuff injury incidence. Neoprene leads material selection for its thermal retention and elasticity, though cotton-spandex hybrids gain traction among consumers prioritizing skin breathability and extended wear comfort.
FDA 510(k) clearance requirements govern medical posture correctors marketed in the United States, while the EU MDR mandates notified body certification for products claiming therapeutic benefit across European markets. Japan's PMDA enforces comparable device classification standards that constrain market entry timelines for non-domestic manufacturers. ISO 13485 quality management certification functions as a de facto prerequisite for contract manufacturing partnerships and hospital procurement eligibility. Stakeholders must monitor evolving ergonomic equipment taxonomies under national occupational safety frameworks, as reclassification could shift reimbursement pathways and channel economics.
Market Dynamics
EU MDR conformity pressure is compressing market access timelines and forcing manufacturers to consolidate notified body relationships, while occupational wellness mandates across Germany and Nordic states accelerate B2B procurement velocity.
Growth Catalysts
- EU MDR Certification Requirements:Stricter notified body oversight for therapeutic claims is filtering out low-quality imports and elevating compliant manufacturers' pricing power across member states.
- Corporate Ergonomic Mandates:Germany's occupational health standards now explicitly subsidize lumbar support devices, accelerating enterprise procurement cycles for office worker segments.
- Neoprene Thermal Properties:Material science advances in breathable polymer blends extend daily wear duration, expanding addressable use cases beyond acute rehabilitation into preventive wellness.
Market Restraints
- Petrochemical Input Volatility:Crude oil price fluctuations directly compress neoprene margins, forcing manufacturers to absorb costs or risk volume erosion in price-sensitive channels.
- Asian Supply Concentration:Nylon and neoprene production clusters in coastal China create tariff exposure and logistics fragility for brands without captive supply arrangements.
- Medical-Grade Certification Friction:FDA 510(k) clearance timelines and PMDA device classification delays extend market entry costs for non-domestic manufacturers targeting premium therapeutic positioning.
Strategic Opportunities
- Athletic Training Adoption:Rotator cuff injury incidence among amateur sports participants in Australia and Canada is expanding shoulder support demand beyond clinical rehabilitation settings.
- Cotton-Spandex Hybrid Materials:Skin breathability prioritization among extended-wear consumers creates white space for comfort-positioned brands to capture premium positioning.
- Direct-to-Consumer Channel Expansion:Bypassing traditional physiotherapy and retail markups enables margin capture and customer data ownership for digitally native entrants.
Industry Challenges
- ISO 13485 Certification Timeline:Quality management system implementation for hospital procurement eligibility requires 12-18 month validation cycles that strain working capital.
- Reimbursement Pathway Uncertainty:National occupational safety frameworks are reclassifying ergonomic equipment taxonomies, creating revenue recognition risk for products shifting between wellness and medical categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Posture Corrector Market |
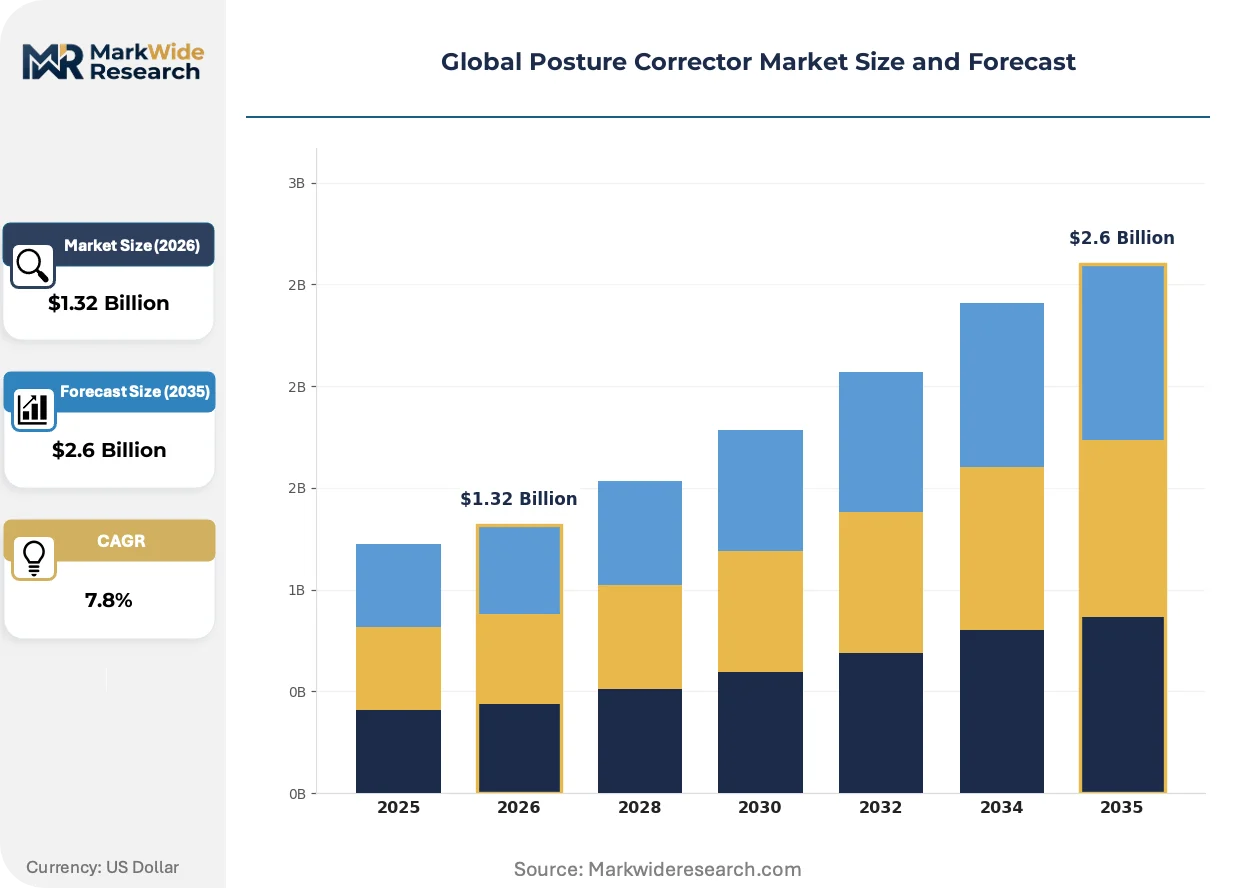
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.6 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Back Brace, Shoulder Support, Lumbar Belt, Neck Brace, Full Body Harness, Waist Trainer Material: Neoprene, Nylon, Cotton, Spandex, Polyester, Foam End User: Office Workers, Athletes, Seniors, Students, Physical Therapists, Fitness Enthusiasts Distribution Channel: Online Retailers, Specialty Stores, Pharmacies, Medical Supply Stores, Fitness Centers, Direct Sales |
| Companies Covered | BackJoy, Swedish Posture, Upright, Aspen Medical Products, BodyRite, Ottobock, Babaka, Comfy Brace, Mueller Sports Medicine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Posture Corrector Market Shifts & Advancements
Biomechanical sensor integration and material science convergence are redefining product value propositions, while regulatory fragmentation across major economies forces parallel certification strategies.
Smart textile technology incorporating pressure sensors and haptic feedback is expanding into preventive posture training applications. Corporate wellness programs in Germany and Sweden are piloting connected devices that alert wearers to slouching in real-time. This convergence of wearable electronics with orthopedic support is expanding into premium pricing tiers previously occupied by passive mechanical braces.
EU MDR implementation is tightening clinical evidence requirements for products claiming therapeutic benefit across European markets. Manufacturers must now submit biomechanical efficacy data to notified bodies, extending certification timelines. The medical-grade back brace segment faces the steepest compliance burden, with smaller brands retreating to wellness positioning to avoid regulatory costs.
Employer-sponsored procurement is displacing individual out-of-pocket purchase as the dominant volume driver in developed economies. Large enterprises in the United States and Germany now negotiate direct supply agreements with manufacturers, compressing distributor margins. This concentration is most visible in the office worker segment, where occupational health departments centralize purchasing decisions for ergonomic equipment.
Global Posture Corrector Market Segmentation
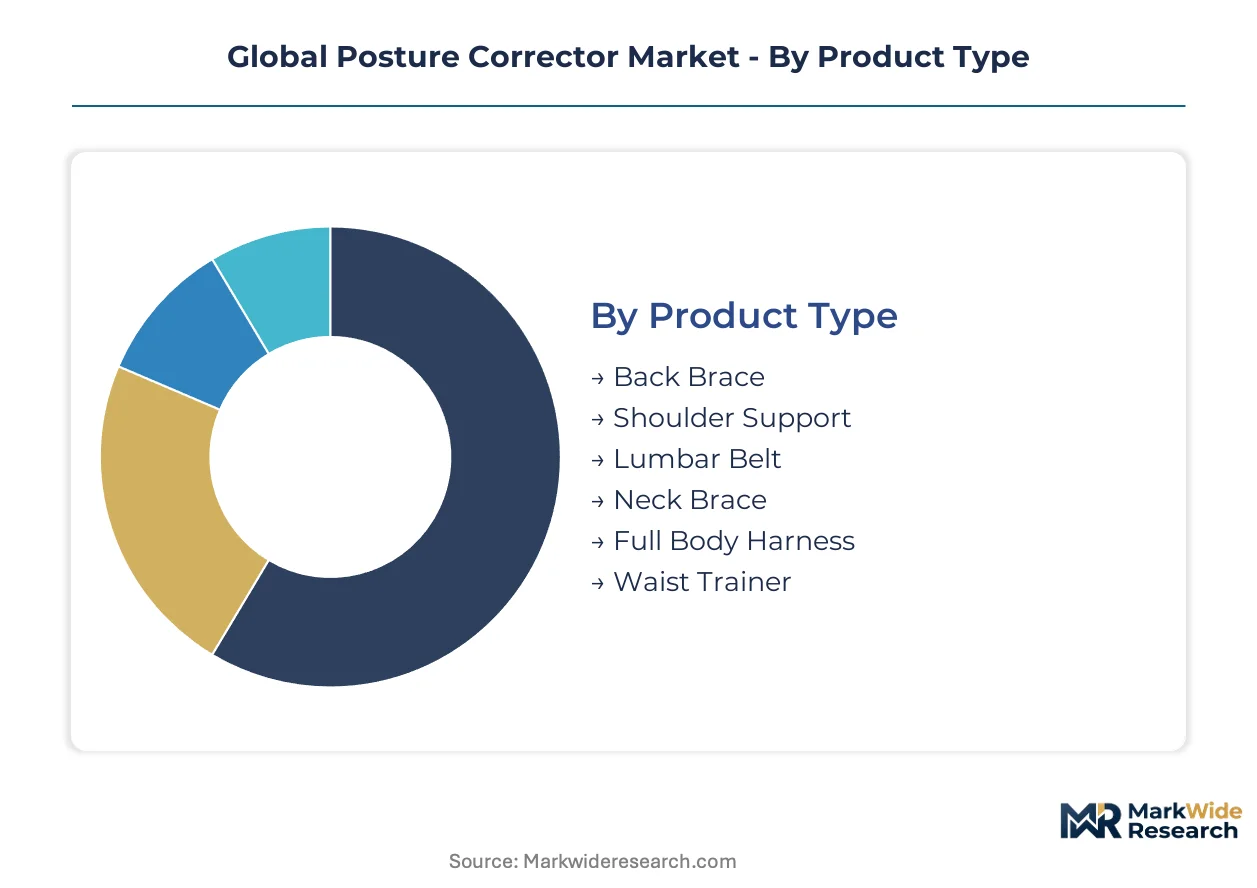
Product differentiation across the posture corrector market follows biomechanical function, material performance, and procurement channel economics. Segmentation reveals where technical specification drives premium pricing versus where commoditization pressures dominate volume channels.
Product Type:
Biomechanical support intensity and anatomical coverage range define the technology hierarchy across wearable orthopedic devices.
- Back Brace:Rigid or semi-rigid structural stays combined with adjustable compression straps provide lumbar stabilization for chronic pain management and post-surgical recovery. Demand concentrates among Germany's aging workforce where occupational health subsidies accelerate enterprise procurement cycles for seated laborers.
- Shoulder Support:Rotator cuff stabilization garments with adjustable deltoid compression target athletic training and overuse injury prevention. Australia's amateur sports participants and Canada's recreational athletes are expanding shoulder support adoption beyond clinical rehabilitation into preventive wellness applications.
- Lumbar Belt:Flexible compression wraps with thermal retention properties support lower back fatigue during prolonged standing or lifting activities.
- Neck Brace:Cervical collars and posture collars address forward head syndrome from screen-based work environments.
- Full Body Harness:Integrated shoulder-lumbar systems redistribute postural load across multiple anatomical zones for comprehensive spinal alignment.
- Waist Trainer:Compression-focused garments prioritize aesthetic contouring with secondary postural benefits through core engagement feedback.
Back brace leads on scale; shoulder support leads on momentum.
Material:
Cost tier stratification separates medical-grade specifications from consumer wellness positioning through polymer chemistry and textile engineering choices.
- Neoprene:Synthetic rubber polymer delivers thermal retention and elastic compression with moisture-resistant properties ideal for extended daily wear. Petrochemical input volatility directly compresses manufacturer margins, forcing cost absorption or price escalation in tariff-exposed supply chains.
- Cotton:Natural fiber prioritizes skin breathability and hypoallergenic contact surfaces for sensitive users and tropical climates. Extended-wear consumers in wellness segments are shifting procurement toward cotton-spandex hybrids that sacrifice thermal properties for comfort during all-day office use.
- Nylon:High tensile strength synthetic enables lightweight structural support with abrasion resistance for athletic applications.
- Spandex:Elastane content provides adjustable fit range and dynamic compression response across body movement patterns.
- Polyester:Cost-efficient synthetic offers moisture wicking and dimensional stability for high-volume manufacturing.
- Foam:Cushioning layers distribute pressure points in rigid brace interfaces and collar padding systems.
Neoprene dominates revenue concentration; cotton gains share fastest among comfort-positioned brands.
End User:
Application context determines whether procurement flows through institutional reimbursement, employer subsidy, or individual out-of-pocket purchase channels.
- Office Workers:Sedentary laborers experiencing cervical strain and lumbar fatigue from prolonged static positioning represent the fastest-expanding buyer segment. Corporate ergonomic wellness programs in Germany and the United States are penetrating enterprise settings with centralized occupational health procurement.
- Physical Therapists:Clinical practitioners prescribe medical-grade devices for post-injury rehabilitation and biomechanical correction protocols. FDA 510(k) clearance and EU MDR notified body certification requirements filter supplier eligibility for therapeutic claims, elevating compliant manufacturers' hospital procurement access.
- Athletes:Amateur and professional sports participants utilize shoulder supports and lumbar belts for injury prevention and training load management.
- Seniors:Aging demographics with degenerative spinal conditions drive demand for rigid back braces and full body harness systems.
- Students:Adolescent users addressing postural development during growth phases and heavy backpack load carriage.
- Fitness Enthusiasts:Gym-based consumers prioritizing form correction during resistance training and core stability work.
Office worker procurement is displacing individual purchase as the dominant volume driver; physical therapist channels sustain premium pricing through certification requirements.
Distribution Channel:
Customer type and margin capture objectives dictate whether brands pursue markup-heavy intermediaries or direct relationship economics.
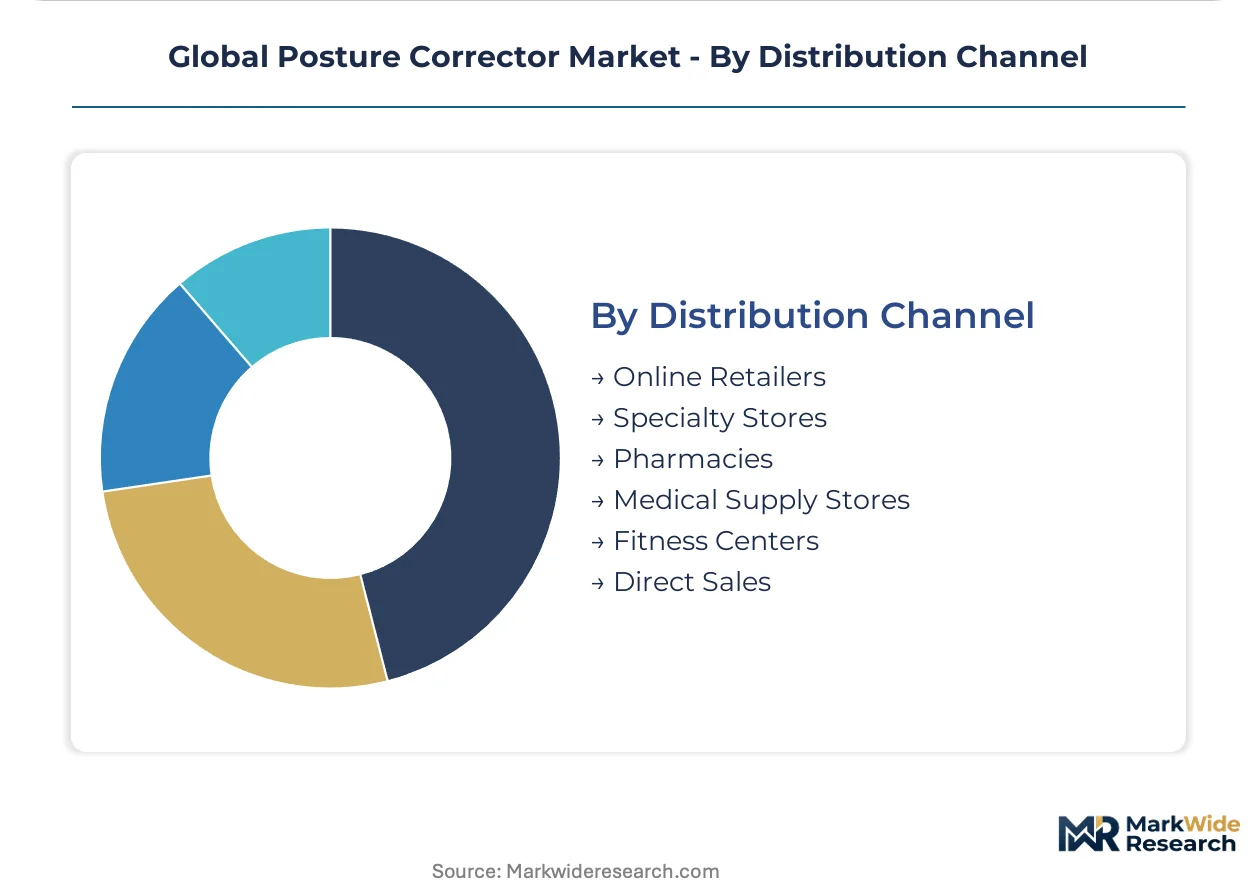
- Online Retailers:E-commerce platforms enable direct-to-consumer distribution with customer data ownership and bypassed retail markups. Digitally native entrants like Comfy Brace compete entirely through this channel, capturing margin that traditional physiotherapy distribution forfeits to intermediary layers.
- Specialty Stores:Orthopedic and ergonomic retailers provide fitting consultation and product education for complex medical-grade selections. German and Nordic physiotherapy channels sustain premium positioning for Swedish Posture and Ottobock through trained staff recommendation authority.
- Pharmacies:Accessible retail locations serve wellness-positioned consumers seeking over-the-counter lumbar belts and posture collars without prescription requirements.
- Medical Supply Stores:Durable medical equipment distributors handle reimbursement-eligible devices for post-surgical and workers' compensation claims.
- Fitness Centers:On-site retail captures impulse purchase from athletic training users immediately post-workout.
- Direct Sales:Manufacturer-owned channels including brand websites and subscription models build recurring revenue relationships.
Online retailers lead on volume expansion; specialty stores lead on margin preservation through clinical credibility transfer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's occupational health apparatus anchors the developed-world demand profile for posture correctors, with corporate ergonomic mandates and aging workforce demographics sustaining premium procurement volumes across lumbar support categories.
Germany
Enterprise procurement cycles for office worker segments accelerate through explicit occupational health subsidies for lumbar support devices. The EU MDR notified body certification requirements filter supplier eligibility, elevating compliant manufacturers' hospital procurement access. Bavaria's industrial corridor concentrates physiotherapy channel distribution for medical-grade back braces.
United States
Corporate wellness program penetration drives employer-sponsored procurement as the dominant volume channel for sedentary laborer segments. FDA 510(k) clearance requirements govern medical posture correctors marketed for therapeutic benefit claims. The Pacific Northwest tech corridor pilots connected posture training devices with real-time haptic feedback integration.
Japan
Aging demographics with degenerative spinal conditions sustain demand for rigid structural braces and full body harness systems. The PMDA enforces device classification standards that constrain market entry timelines for non-domestic manufacturers. Tokyo's metropolitan occupational health departments centralize ergonomic equipment purchasing decisions for white-collar enterprises.
Australia
Amateur sports participants expand shoulder support adoption beyond clinical rehabilitation into preventive wellness applications. The country's national therapeutic goods regulator maintains comparable device standards to FDA and PMDA frameworks. Sydney and Melbourne physiotherapy channels sustain premium positioning for athletic training procurement.
Canada
Recreational athlete segments drive rotator cuff stabilization garment demand through fitness center and specialty retail channels. Health Canada device classification requirements align with ISO 13485 quality management prerequisites for hospital procurement eligibility. Ontario's corporate ergonomic wellness programs penetrate enterprise settings with centralized occupational health purchasing.
Global Posture Corrector Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer disruption through bypassed retail markups and customer data ownership. The vendor base stratifies across medical-grade certification holders, wellness-positioned comfort brands, and digitally native e-commerce specialists. Three archetypes dominate: orthopedic technology heritage players leveraging clinical credibility, Nordic manufacturing base anchors sustaining premium positioning, and online-only distributors capturing margin through eliminated intermediary layers. Competitive moves concentrate on notified body relationship consolidation under EU MDR pressure and backward integration into captive neoprene supply arrangements.
Within the orthopedic technology tier, Ottobock exemplifies medical-grade back brace dominance through hospital procurement channel access. Swedish Posture anchors Nordic manufacturing credibility across European physiotherapy channels. Comfy Brace represents digitally native direct-to-consumer positioning through entirely online distribution architecture. These three occupy distinct competitive vectors—clinical certification, regional manufacturing heritage, and margin-capturing channel disruption—without direct segment overlap.
| Leading Market Players |
|---|
| BackJoy |
| Swedish Posture |
| Upright |
| Aspen Medical Products |
| BodyRite |
| Ottobock |
| Babaka |
| Comfy Brace |
| Mueller Sports Medicine |
| Others |
Supply & Pricing Matrix
EU MDR notified body certification requirements gate qualified supply and premium-tier pricing access for posture corrector manufacturers seeking therapeutic positioning across member states. Compliance investment separates certified medical-grade suppliers from wellness-positioned competitors, compressing margin structures for non-compliant entrants while elevating pricing power for notified body-approved producers serving hospital procurement channels.
Pricing Analysis
Petrochemical input pass-through dynamics dominate pricing structures as neoprene and nylon feedstock volatility compress manufacturer margins. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and channel economics, with FDA-cleared medical devices commanding substantial premiums over wellness-positioned alternatives. Pricing pressure stems from tariff exposure on Asian-sourced polymer inputs, forcing cost absorption or selective price escalation. Individual out-of-pocket consumers exhibit highest price sensitivity, while employer-sponsored procurement through occupational health departments demonstrates lowest sensitivity due to subsidy mechanisms.
Supply Chain Analysis
Single-source vulnerability sits with coastal China production clusters for neoprene polymer and nylon textile inputs. Manufacturing concentration in China, Vietnam, and Bangladesh feeds global distribution networks, with raw material dependencies on petroleum-derived synthetic rubbers, elastane blends, and breathable cotton-spandex hybrids. Tariff exposure and logistics fragility constitute the dominant structural risk for brands lacking captive supply arrangements. Distribution runs through physiotherapy specialty channels for premium medical-grade devices and direct-to-consumer platforms for wellness-positioned alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU MDR implementation accelerating demand filtration toward certified manufacturers and compressing access timelines for non-compliant competitors.
For Market Incumbents: Lock in notified body relationships under consolidating EU MDR oversight to defend hospital procurement access against emerging digitally native entrants bypassing traditional channels. Deepen backward integration into captive neoprene supply arrangements to mitigate petrochemical input volatility and tariff exposure. Prioritize ISO 13485 quality management certification maintenance to sustain GPO eligibility and physical therapist channel authority. For New Entrants and Emerging Players: Cotton-spandex hybrid prioritizers represent an underserved buyer archetype seeking skin breathability for extended daily office wear, creating white-space opportunity outside neoprene-dominated medical-grade positioning. Target direct-to-consumer distribution architecture to capture margin eliminated through physiotherapy and retail intermediary layers. Athletic training segments in Australia and Canada offer penetrable entry points for shoulder support specialization beyond saturated back brace competition. For Investors and Strategic Acquirers: Roll-up economics work for notified body-certified mid-cap manufacturers because EU MDR compliance burdens are filtering smaller competitors toward wellness repositioning or exit. Five-to-ten year viability centers on clinical credibility transfer and hospital system contract concentration. Watch for reimbursement pathway reclassification under national occupational safety frameworks as the critical inflection signal shifting products between wellness and medical categories.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | Filters market access and elevates compliant manufacturers' hospital procurement pricing power across Germany and Nordic states. |
| Backward Integration into Neoprene Supply | Mitigates petrochemical margin compression and tariff exposure for brands with captive polymer production arrangements. |
| Direct-to-Consumer Channel Launch | Enables margin capture and customer data ownership for digitally native entrants bypassing physiotherapy markups. |
| Smart Textile Sensor Integration | Expands premium pricing tiers through real-time haptic feedback convergence with orthopedic support applications. |
| Corporate Wellness Program Partnership | Secures employer-sponsored procurement volume displacement of individual out-of-pocket purchase in German and US enterprises. |
Research Methodology
Coverage spans Germany, United States, Japan, Australia, and Canada, with primary inputs from each market's stakeholder ecosystem. Primary interviews with orthopedic device procurement managers, physiotherapy channel distributors, corporate occupational health officers, and notified body certification consultants combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, PMDA device classification records, and hospital GPO contract disclosures. Bottom-up manufacturer shipment analysis and top-down demographic demand modeling provided triangulation across data sources.
Granularity-level modeling addressed product type, material composition, end-user application, and distribution channel dimensions at the country level across the projection horizon. CAGRs derived from regression analysis against occupational health expenditure trends, aging demographic projections, and corporate wellness program penetration rates. Forecast inputs incorporated EU MDR implementation timelines, petrochemical price indices, and reimbursement pathway reclassification risk assessments.
Underlying measurement precision varies by segment; medical-grade back braces with FDA clearance carry tighter precision than wellness-positioned posture collars due to procurement database transparency. Forecasts reflect documented assumptions regarding regulatory implementation schedules, tariff regime stability, and employer subsidy continuation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Hand Hygienic Product Market
Personal Grooming Products
Europe Hair Styling Tools Market
Personal Grooming Products
Handheld Massager Market
Personal Grooming Products
Electric Hair Clipper and Trimmer Market
Personal Grooming Products
North America Hair Styling Tools Market
Personal Grooming Products
AI Toothbrush Market
Personal Grooming Products
Epilators Market
Personal Grooming Products
Sexual Lubricant Market
Personal Grooming Products
Self-Tanning Products Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Smart Body Scales Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Global Consumer Use IPL Hair Removal Devices Market
Personal Grooming Products
Insect Repellent Wipes Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
Shoe Insert Market