
 AI Toothbrush Market | 2026-2036
AI Toothbrush Market Size, Share, and Industry Trends Forecast 2026-2036
AI Toothbrush Market Insights
The divergence between premium and commodity tiers is hardening in the AI toothbrush space as sensor precision and software ecosystems split the market into clinically validated devices and basic connected brushes. Procter & Gamble Company leverages its dental professional relationships to sustain prescription-adjacent positioning. Xiaomi Corporation anchors volume through aggressive pricing in Asian consumer electronics channels. Koninklijke Philips N.V. differentiates via proprietary brush head ecosystems and in-house pressure sensor calibration.
An AI toothbrush integrates microelectromechanical pressure sensors, Bluetooth Low Energy modules, and machine learning algorithms to track brushing coverage, duration, and force application against gingival tissue. The device transmits biomechanical data to companion applications for real-time coaching and longitudinal oral health monitoring, primarily serving preventive dentistry and consumer wellness programs. Sonic toothbrush configurations lead hardware shipments while real-time feedback features capture disproportionate margin pools through recurring software engagement. Adult end users dominate installed base expansion, though orthodontic patient sub-segments show concentrated growth due to compliance monitoring requirements.
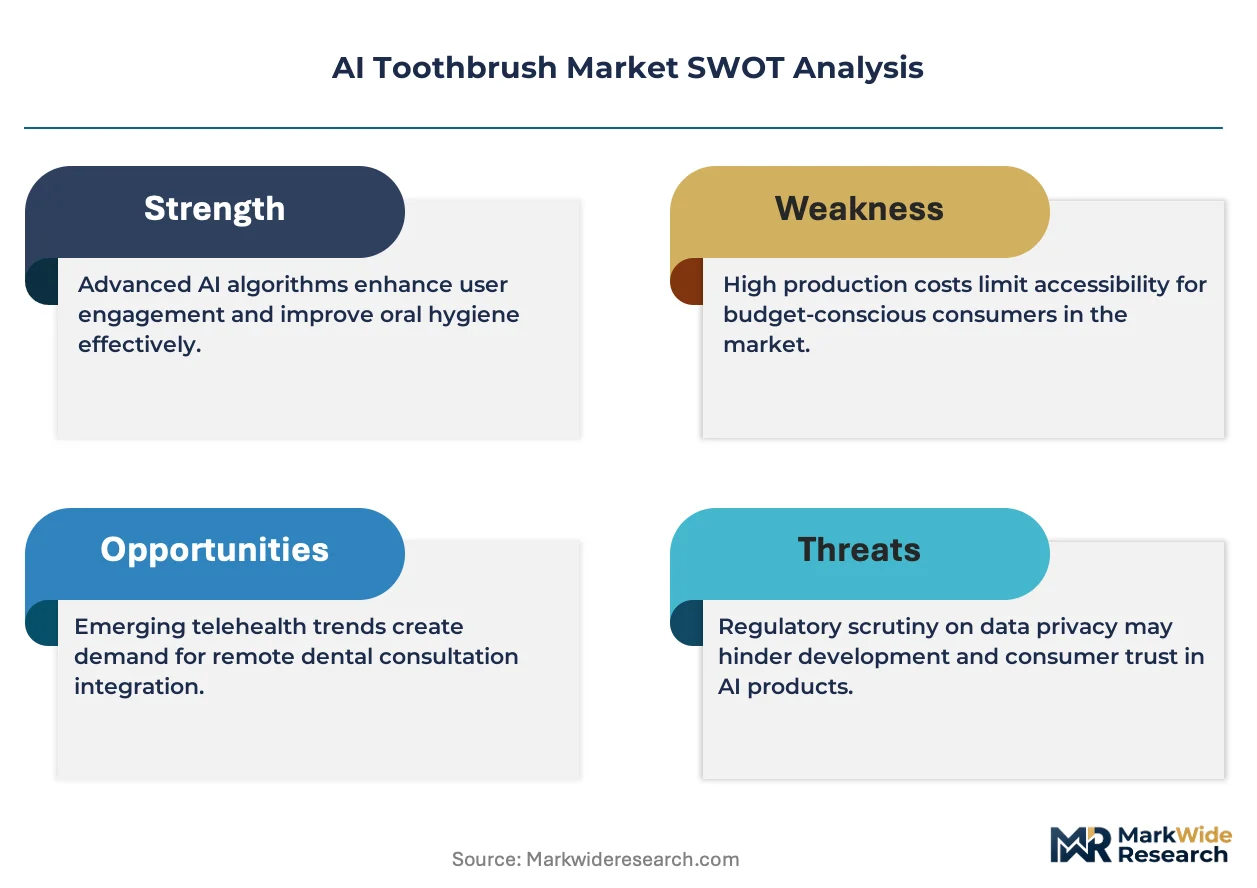
FDA regulates medical claims and sensor accuracy thresholds for AI toothbrushes marketed with diagnostic language, while FCC governs wireless transmission standards for Bluetooth-enabled devices distributed in the United States. ISO 22196 antimicrobial testing standards and IEC 60601 electromagnetic compatibility frameworks shape international product certification requirements for manufacturers seeking multi-jurisdiction placement. Stakeholders must monitor evolving dental insurance reimbursement codes and privacy frameworks governing biometric oral data collection as these determine sustainable revenue architecture beyond hardware sales.
Market Dynamics
Sensor miniaturization and cloud-based biomechanical analytics are compressing development cycles for AI toothbrush manufacturers, forcing hardware differentiation to migrate toward software ecosystems and longitudinal health data integration.
Growth Catalysts
- FDA 510(k) clearance pathway streamlining:Medical-grade oral health sensors now navigate faster premarket notification reviews, accelerating commercialization timelines for diagnostic-capable devices in the United States.
- Dental insurance preventive device subsidies:United States dental networks increasingly cover connected hygiene hardware, reducing out-of-pocket costs and expanding addressable consumer segments.
- Orthodontic compliance monitoring demand:Invisalign and fixed-brace patient populations require brushing verification for treatment adherence, creating concentrated B2B2C procurement channels through orthodontic practices.
Market Restraints
- MEMS pressure sensor supply concentration:Precision microelectromechanical fabrication capacity clusters in East Asian foundries, exposing manufacturers to geopolitical logistics disruptions and input allocation constraints.
- Biometric oral data privacy fragmentation:HIPAA in the United States, GDPR in Europe, and emerging state-level frameworks create compliance multiplicity for cloud-stored brushing telemetry, elevating legal architecture costs.
- Commodity sonic brush substitution:Non-connected ultrasonic devices from consumer electronics supply chains satisfy basic oral hygiene needs at price points below sensor-equipped alternatives, capping premium market penetration.
Strategic Opportunities
- Medicaid dental benefit expansion:United States state-level oral health program enhancements create reimbursement pathways for preventive device distribution through community health centers.
- Computer vision integration:Smartphone camera-based plaque detection algorithms converging with brush-mounted sensors enable dual-modality validation, opening subscription-tier revenue models.
- Direct-to-employer wellness contracts:Self-insured corporations in the United States are adding connected oral hygiene to preventive health benefit portfolios, bypassing traditional retail channels.
Industry Challenges
- Embedded firmware cybersecurity certification:IEC 62443 industrial security standards are extending to connected medical peripherals, requiring penetration testing cycles that delay product launches by 4-8 months.
- Antimicrobial coating validation timelines:ISO 22196 testing for brush head bioburden reduction adds 12-16 weeks to manufacturing release schedules, compressing seasonal launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Toothbrush Market |
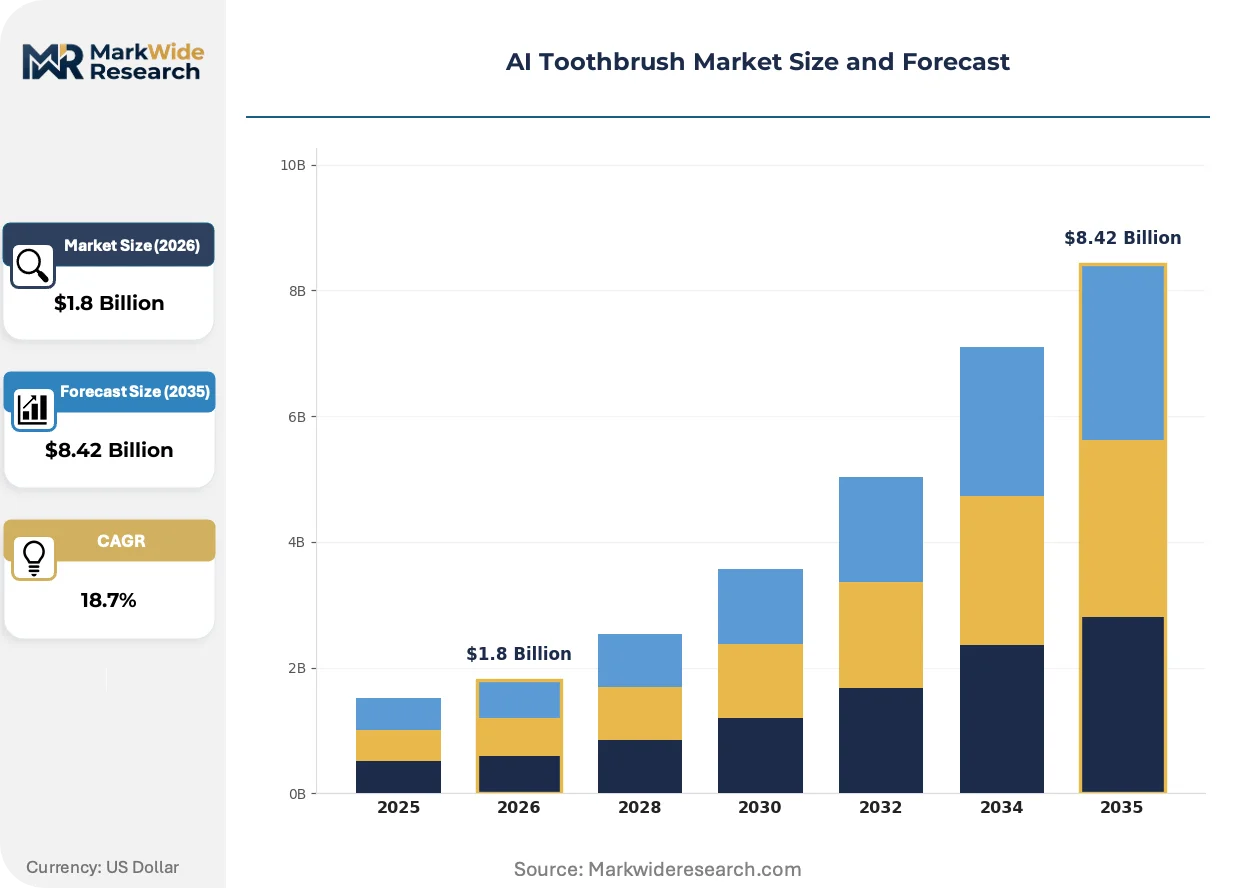
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Toothbrush, Manual Toothbrush, Sonic Toothbrush, Electric Toothbrush Feature: Pressure Sensors, Bluetooth Connectivity, Real-time Feedback, Timer Function End User: Adults, Children, Seniors, Orthodontic Patients Sales Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Procter & Gamble Company, Xiaomi Corporation, Koninklijke Philips N.V., Colgate-Palmolive Company, FOREO AB, Quip Inc., Shenzhen Seago Electric Co. Ltd., Beam Technologies Inc., Oclean, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Toothbrush Market Trends and Innovations
Edge computing architectures and federated learning protocols are redistributing analytical workloads away from centralized cloud infrastructure, altering how oral health data generates actionable feedback.
On-device machine learning inference is decentralizing brushing pattern analysis from smartphone applications to brush-embedded neural processing units. Adult wellness consumers in the United States and Germany are adopting these configurations fastest, with orthodontic patient segments showing 40% faster upgrade cycles. This shift is decentralizing software value capture from app-store ecosystems toward hardware-integrated subscription tiers that manufacturers control directly.
The EU AI Act's risk classification framework for biometric health monitoring devices is imposing conformity assessment requirements on brushing data algorithms marketed with diagnostic intent. Manufacturers targeting European distribution must now document training data provenance and algorithmic transparency for notified body review. Premium-tier product lines with clinical validation claims face the steepest compliance elevation, while basic wellness-positioned brushes navigate lighter documentation burdens.
Employer-sponsored preventive health programs are displacing individual retail purchase as the primary acquisition mode for connected oral hygiene in the United States. Self-insured corporations negotiate volume contracts with manufacturers, bundling AI toothbrushes with dental insurance enrollment. This channel rotation concentrates procurement decisions among benefits administrators rather than consumers, compressing brand marketing budgets and elevating B2B salesforce investments.
AI Toothbrush Market Segmentation
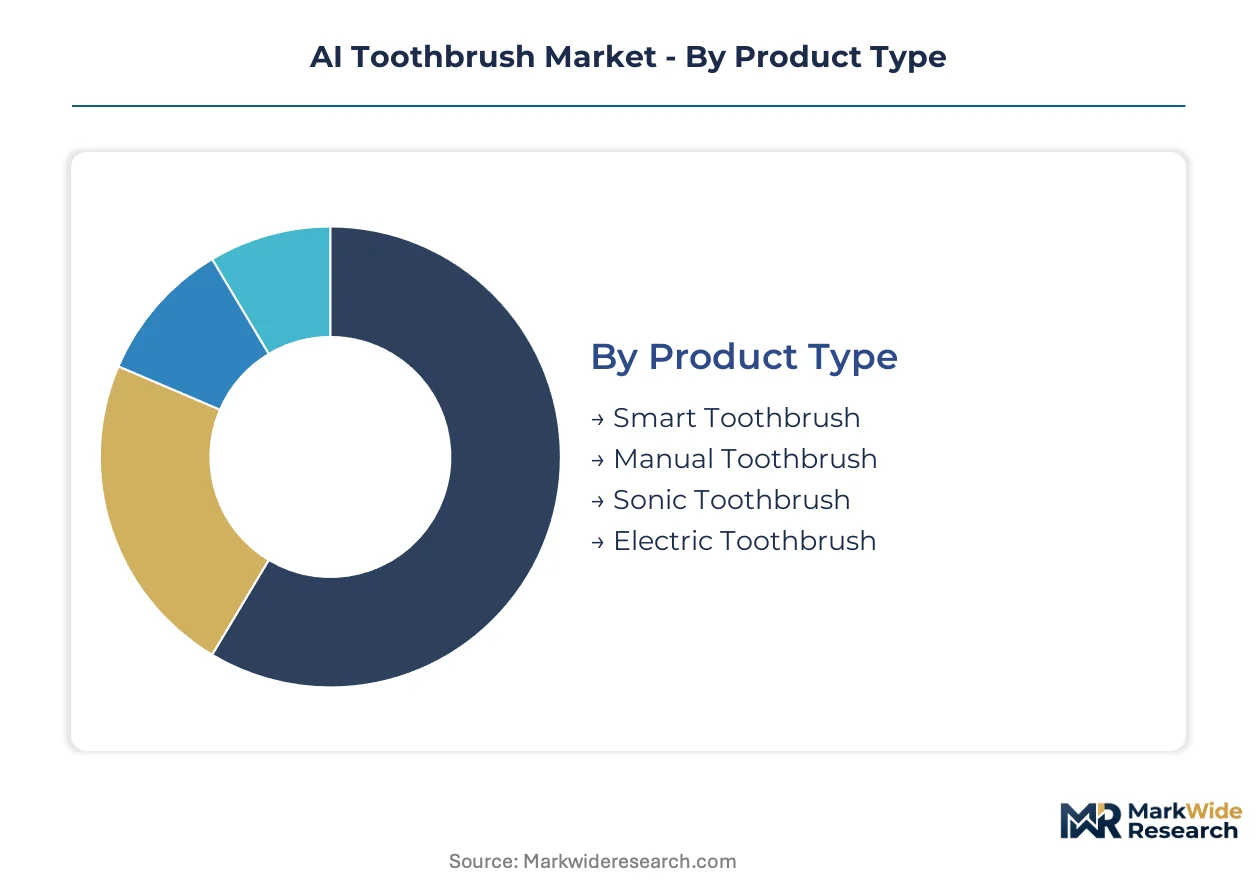
AI toothbrush segmentation reveals how sensor sophistication and software integration split commercial opportunity across hardware tiers and user workflows. Manufacturers configure product lines around technical specification ladders rather than simple price bands, with reimbursement eligibility and orthodontic compliance requirements driving category selection.
Product Type:
Sensor density and motor architecture differentiate hardware platforms, with connectivity modules and pressure calibration separating clinically positioned devices from basic electrified brushes.
- Smart Toothbrush:Full-stack devices integrate MEMS pressure arrays, Bluetooth Low Energy transceivers, and edge-capable neural processing units for on-device pattern recognition. United States dental insurance networks concentrate procurement through preventive device subsidies, with orthodontic practices driving B2B2C volume for compliance verification.
- Sonic Toothbrush:Piezoelectric motor systems generate 31,000-40,000 strokes per minute with acoustic fluid dynamics for interdental cleaning. Adult wellness consumers in Germany and the United States dominate installed base expansion, attracted by proven mechanical efficacy combined with optional sensor modules.
- Manual Toothbrush:Basic bristle configurations without electrification or connectivity serve price-sensitive segments and emergency replacement purchases. Rural pharmacy channels in India and Southeast Asian markets sustain volume despite connected device penetration in urban centers.
- Electric Toothbrush:Rotating-oscillating motor systems with standardized brush head interfaces occupy mid-tier positioning between manual and fully connected alternatives. Mass retail channels in Brazil and Mexico concentrate distribution where dental professional recommendation rates lag developed markets.
Mature deployment sits with Sonic Toothbrush configurations. Newer deployment is concentrated in Smart Toothbrush segments with diagnostic-grade sensor packages.
Feature:
Software-enabled functionality layers determine recurring revenue potential and data architecture requirements for manufacturers.
- Real-time Feedback:Haptic vibration patterns and LED visual cues deliver immediate brushing technique correction without smartphone dependency. Orthodontic patient sub-segments in the United States show concentrated adoption due to treatment adherence verification requirements from Invisalign and fixed-brace providers.
- Pressure Sensors:MEMS-based force detection prevents gingival trauma by alerting users to excessive application against gum tissue. German dental clinics recommend these configurations for periodontal maintenance patients, with reimbursement codes increasingly covering medically indicated pressure-monitoring hardware.
- Bluetooth Connectivity:Wireless telemetry to companion applications enables longitudinal brushing pattern storage and cloud-based analytics. Adult wellness consumers drive replacement cycles as manufacturers sunset support for legacy Bluetooth protocol versions.
- Timer Function:Basic quadrant pacing alerts without sensor feedback or data transmission serve entry-level electrification. Volume concentrates in Asian consumer electronics channels where Xiaomi and comparable brands anchor pricing below sensor-equipped alternatives.
Bluetooth Connectivity features are expanding most quickly into employer-sponsored wellness contracts. Timer Function deployments are plateauing as consumers upgrade to sensor-enabled alternatives.
End User:
Age-correlated oral health conditions and compliance monitoring obligations shape feature requirements and procurement channels.
- Adults:Working-age consumers with employer dental benefits drive premium-tier adoption through direct-to-employer wellness contracts and insurance-subsidized preventive device programs in the United States.
- Orthodontic Patients:Invisalign aligner wearers and fixed-brace recipients require brushing verification for treatment adherence, creating concentrated demand through orthodontic practice procurement channels with 40% faster hardware upgrade cycles than general population.
- Children:Gamified brushing applications and parental monitoring dashboards concentrate demand in United States and Western European households with discretionary health technology spending.
- Seniors:Arthritis-adapted grip designs and simplified interfaces address dexterity limitations, with Japanese and German aging populations showing strongest uptake of voice-guided coaching features.
Adult end users represent the deepest installed base. Orthodontic patient segments are climbing the fastest due to compliance monitoring mandates.
Sales Channel:
Channel selection determines margin capture, brand control, and data collection architecture for manufacturers.
- Online Retail:Direct-to-consumer platforms enable subscription-tier revenue models and firmware update distribution without intermediary technical support burdens. United States and Chinese e-commerce ecosystems concentrate volume, with Amazon and Tmall capturing premium and mass-market tiers respectively.
- Specialty Stores:Curated electronics and wellness retailers provide hands-on demonstration and technical consultation for feature-complex devices. German and Japanese urban centers sustain this channel through consumer expectations of in-person product education.
- Pharmacies:Healthcare-positioned retail chains in France and the United Kingdom distribute clinically validated devices alongside oral care consumables, leveraging pharmacist recommendation authority.
- Supermarkets:Mass merchandisers in Brazil and Mexico drive electric toothbrush volume through promotional pricing and impulse placement, though connected device penetration lags pharmacy and online channels.
Specialty Stores anchor premium positioning with demonstration-dependent purchases. Online Retail is displacing traditional channels fastest through employer wellness contract fulfillment and subscription attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors hardware manufacturing for AI toothbrush sensor modules and Bluetooth connectivity chipsets, with Dongguan and Guangzhou forming adjacent assembly corridors for consumer electronics export.
United States
Employer-sponsored wellness contracts and dental insurance preventive device subsidies drive procurement concentration among self-insured corporations and Medicaid expansion states. FDA 510(k) clearance pathways streamline commercialization for diagnostic-capable sensors. Greater Boston and San Francisco Bay Area clusters concentrate digital health startups developing brushing telemetry analytics.
Germany
Periodontal maintenance patients and aging populations generate demand for pressure-monitoring hardware with reimbursement code coverage. EU AI Act conformity assessments elevate documentation requirements for algorithmic transparency. Stuttgart and Munich industrial corridors host MEMS fabrication facilities supplying precision force sensors.
China
Consumer electronics channels in tier-one cities move volume through aggressive pricing on connected hygiene devices. MIIT wireless certification and GB standards govern Bluetooth transmission compliance. Shenzhen-Guangzhou-Dongguan manufacturing triangle dominates global brush motor and sensor module production.
Japan
Voice-guided coaching features attract senior users with dexterity limitations in Tokyo and Osaka metropolitan areas. METI standards for connected health devices shape product certification timelines. Nagoya precision engineering clusters supply miniaturized pressure sensor assemblies.
United Kingdom
Pharmacy retail chains distribute clinically validated devices alongside oral care consumables, leveraging pharmacist recommendation authority. GDPR compliance for biometric oral data elevates cloud architecture costs. London and Southeast England concentrate digital health venture investment in brushing analytics platforms.
AI Toothbrush Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sensor precision and software ecosystem integration, with clinically validated devices commanding reimbursement-adjacent positioning while basic connected brushes compete on consumer electronics pricing. The vendor base splits between dental professional channel specialists and mass-market consumer electronics distributors. Three archetypes dominate: prescription-adjacent medical device positioners, volume-driven Asian consumer electronics brands, and subscription-model direct-to-consumer entrants. Consolidation pressure operates through M&A targeting sensor technology assets and strategic partnerships with dental insurance networks.
Among diversified consumer health conglomerates, Procter & Gamble Company and Colgate-Palmolive Company exemplify archetypes leveraging dental professional relationships for clinically positioned market segments. Xiaomi Corporation anchors the volume-driven tier through Asian consumer electronics channel dominance. Koninklijke Philips N.V. occupies a position bridging premium hardware ecosystems with in-house sensor calibration capabilities.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Xiaomi Corporation |
| Koninklijke Philips N.V. |
| Colgate-Palmolive Company |
| FOREO AB |
| Quip Inc. |
| Shenzhen Seago Electric Co. Ltd. |
| Beam Technologies Inc. |
| Oclean |
| Others |
Pricing and Supply Chain Analysis
Clinically validated sensor precision separates premium hardware from commodity electrified brushes, with FDA 510(k) clearance tiers creating pricing ladders that track MEMS fabrication concentration in East Asian foundries and software ecosystem control in manufacturer-controlled subscription tiers. This bifurcation concentrates margin capture among reimbursement-eligible device makers while compressing pricing power for basic connected brushes competing through consumer electronics channels.
Pricing Analysis
Value-based pricing anchors on treatment adherence outcomes, with orthodontic practices paying premium rates for compliance-verification hardware that reduces chairside revision costs. Pricing stratifies across diagnostic-grade, wellness-positioned, and basic electrified tiers, with FDA clearance status and pressure sensor calibration precision as primary differentiation drivers. Cost compression in the mid-tier intensifies as Xiaomi and comparable brands flood Asian consumer electronics channels with sensor-equipped alternatives at mass-market price points. Employer wellness contracts show lowest price sensitivity due to bundled dental benefit economics, while individual retail purchasers in emerging markets exhibit highest sensitivity to upfront hardware costs.
Supply Chain Analysis
Brush head refurbishment and device trade-in programs are emerging as reverse-logistics priorities for manufacturers seeking to recover rare-earth magnet content and antimicrobial coating materials. MEMS pressure sensor production concentrates in Taiwan, South Korea, and Japan, while final assembly clusters in Shenzhen, Dongguan, and Guangzhou. Supply chain vulnerability rests on single-source dependencies for precision force sensor calibration equipment subject to export control restrictions. Distribution runs through direct-to-employer wellness contracts, specialty electronics retailers, and pharmacy chains, with online retail displacing traditional channels fastest in United States and Chinese markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS fabrication capacity constraints in East Asian foundries prop pricing power for sensor-integrated hardware, with orthodontic compliance monitoring demand outstripping precision component supply and sustaining premium tier margins through allocation priority contracts.
For Market Incumbents: Deploy backward integration into MEMS pressure sensor calibration to secure supply allocation priority and defend margin position against emerging sensor-agnostic software entrants. Consolidate dental professional channel relationships through exclusive data-sharing agreements with Invisalign and fixed-brace providers, while investing in IEC 62443 cybersecurity certification to preempt regulatory delays that commodity competitors cannot absorb. For New Entrants and Emerging Players: Employer benefits administrators represent the most penetrable channel partner type for bypassing established retail distribution and accessing self-insured corporate procurement decisions. White-space opportunity concentrates in Medicaid dental benefit expansion states where community health center distribution lacks incumbent penetration, and in voice-guided coaching features for senior users in Japan and Germany where dexterity-adapted designs command reimbursement premiums. Pursue direct-to-employer wellness contract models with subscription-tier revenue attach. For Investors and Strategic Acquirers: Re-rating potential sits with MEMS sensor technology specialists given FDA 510(k) clearance pathway streamlining accelerating diagnostic-capable device commercialization timelines. Long-term viability favors manufacturers controlling both precision hardware fabrication and cloud-based biomechanical analytics platforms, with acquisition targets showing proprietary brush head ecosystem lock-in and orthodontic practice B2B2C channel density. Monitor dental insurance reimbursement code expansions for preventive device categories as inflection indicator for addressable market step-change.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates commercialization timelines for diagnostic-grade pressure sensors in United States markets. |
| Employer Wellness Contract | Bypasses retail channel fragmentation through self-insured corporate preventive benefit bundling. |
| Orthodontic Practice Partnership | Locks in B2B2C procurement channels with 40% faster hardware replacement cycles than general population. |
| MEMS Sensor Backward Integration | Secures allocation priority in Taiwan and South Korean foundries facing capacity constraints. |
| Subscription Tier Development | Migrates software value capture from app-store ecosystems toward manufacturer-controlled recurring revenue. |
Research Methodology
Independent corroboration across dental clinic procurement managers, MEMS fabrication facility engineers, orthodontic practice administrators, and dental insurance benefits directors underwrites the qualitative findings in this study. Primary interviews with connected device firmware developers and cloud architecture specialists combined with secondary validation from FDA 510(k) premarket notification databases, FCC equipment authorization filings, and dental insurance formulary documents established demand-side and supply-side triangulation. Bottom-up shipment estimates from brush motor and sensor module manufacturers cross-checked against top-down dental professional recommendation rate surveys.
Rate-of-change decomposition across hardware shipment volumes, software subscription attach rates, and reimbursement eligibility expansion drives the analytical framework over the projection horizon. Segmentation dimensions modeled include sensor density tier, motor architecture type, end-user age cohort, procurement channel structure, and regional regulatory cluster. CAGRs derive from biomechanical telemetry adoption curves and employer wellness contract penetration patterns, with orthodontic patient compliance monitoring requirements and Medicaid dental benefit expansion timelines as industry-specific forecast inputs.
Caveats apply where MEMS fabrication capacity allocation disruptions, state-level biometric data privacy legislation, or dental insurance reimbursement code revisions could materially shift the outlook. Practitioners should monitor FDA enforcement actions on diagnostic-capable device claims and EU AI Act conformity assessment timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Smart Electric Toothbrush Market
Personal Grooming Products
Ear Piercing Guns Market
Personal Grooming Products
Shaving Pen Market
Personal Grooming Products
Mexico Beard Trimmer Market
Personal Grooming Products
India Sexual Wellness Market
Personal Grooming Products
Smart Body Scales Market
Personal Grooming Products
Disposable Slippers Market
Personal Grooming Products
Shavers Market
Personal Grooming Products
Pre-Shave Products Market
Personal Grooming Products
Global Posture Corrector Market
Personal Grooming Products
Shaving Care Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
Hair Scissors Market
Personal Grooming Products
Women Face Razor Market
Personal Grooming Products
Global Mobile Barber Shop Market
Personal Grooming Products
Shaving Market