
 Epilators Market | 2026-2036
Epilators Market Size, Share, and Industry Trends Forecast 2026-2036
Epilators Market Foresight
CE marking under the EU Medical Device Regulation is bifurcating the competitive landscape into certified clinical-grade suppliers and uncertified consumer-device makers. Braun leverages its German engineering heritage to sustain premium positioning across European pharmacy chains. Philips anchors volume through broad retail distribution in North American big-box stores. Panasonic Corporation differentiates via Japanese precision-motor technology that commands loyalty in Asian specialty channels.
An epilator is an electric depilation device employing rotating tweezing discs or pulsating spring mechanisms to grasp and extract hair from the root, typically operating at 20-40 tweezing actions per second for efficient follicle removal. The device serves commercial purposes in home personal care and professional salon settings where clients seek longer-lasting smoothness compared to surface shaving methods. Cordless variants lead volume due to lithium-ion battery advances enabling wet/dry bathroom use, while laser and light-based technologies capture margin pools among consumers seeking permanent hair reduction. The women's segment dominates unit sales though men's body grooming represents the fastest-growing end-user category as social norms shift.
The FDA regulates laser and intense pulsed light epilators as medical devices under 21 CFR 878.4810, requiring 510(k) clearance that limits market entry for unproven light-based technologies. The EU Ecodesign Directive and REACH compliance on battery materials shape product architecture decisions for manufacturers selling into European markets. Stakeholders must monitor evolving battery chemistry regulations and shifting dermatological safety standards as the boundary between cosmetic and medical device classifications continues to tighten.
Market Dynamics
The EU Ecodesign Directive's battery sustainability mandates are forcing manufacturers to abandon alkaline-powered architectures in favor of rechargeable lithium-ion systems, fundamentally restructuring product development cycles and supply chain sourcing for personal grooming devices.
Growth Catalysts
- REACH compliance on battery materials:European chemical safety standards are accelerating R&D investment in nickel-metal hydride alternatives, opening procurement channels for compliant Asian battery suppliers.
- Men's body grooming segment:Shifting social norms around male hair removal are expanding addressable demand beyond traditional female demographics into chest, back, and facial grooming applications.
- Wet/dry bathroom use patterns:Lithium-ion advances enabling full water immersion are capturing preference share from corded salon-grade equipment in residential settings.
Market Restraints
- Cobalt and lithium price volatility:Battery raw material cost swings compress margin stability for cordless variant manufacturers dependent on cylindrical cell supply.
- Clinical-grade certification concentration:CE marking under EU MDR limits pharmacy channel access to a narrow supplier base with documented biocompatibility testing.
- Laser hair removal substitution:Med-spa IPL treatments offer permanent reduction promises that erode repurchase intent for mechanical epilation devices.
Strategic Opportunities
- India's personal care appliance penetration:Urban middle-class expansion in Mumbai and Delhi creates first-time buyer pools with limited exposure to competing salon services.
- EU Green Deal circular economy requirements:Removable battery mandates and repairability scoring systems favor modular design architectures that extend product lifecycles.
- Subscription blade replacement models:Direct-to-consumer replenishment programs for disc cartridges capture recurring revenue streams previously lost to third-party consumable suppliers.
Industry Challenges
- 510(k) clearance timelines:FDA medical device classification for light-based variants extends time-to-market by 18-24 months versus cosmetic-grade mechanical devices.
- Micro-motor precision engineering talent:Japanese and German manufacturing clusters face skilled technician shortages for sub-millimeter tolerance component assembly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epilators Market |
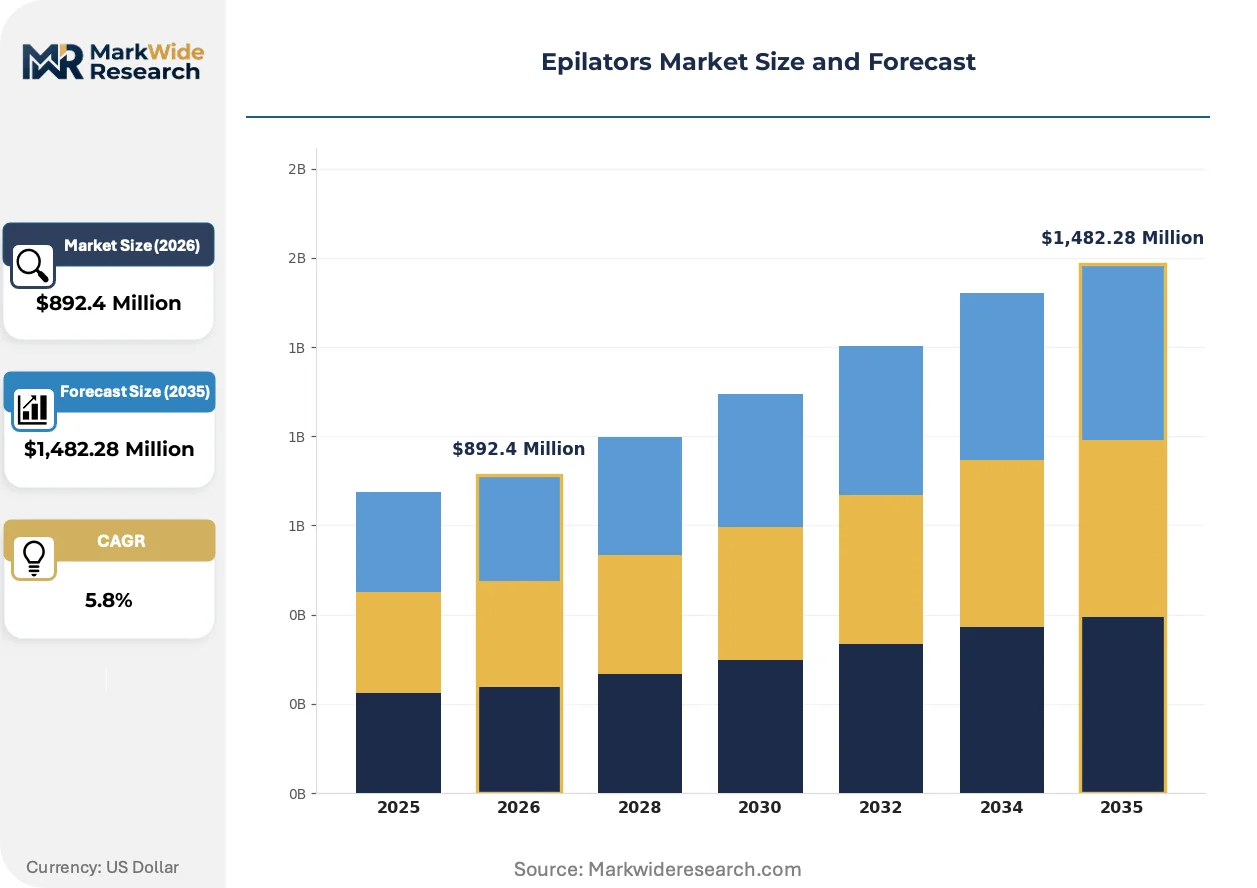
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,482.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded, Cordless, Wet/Dry, Battery Operated End User: Women, Men, Salons, Personal Care Stores Application: Facial Hair Removal, Leg Hair Removal, Underarm Hair Removal, Body Hair Removal Technology: Rotary, Pulsating, Laser, Light-Based |
| Companies Covered | Philips, Braun, Panasonic Corporation, Beurer GmbH, Conair Corporation, Procter & Gamble, Emjoi Inc., Havells India Ltd., Morphy Richards India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epilators Market Shifts & Advancements
Cordless power architectures, regulatory sustainability mandates, and channel disintermediation are converging to redefine how epilation devices reach end-users and what performance benchmarks define category leadership.
Ceramic tweezer discs with antimicrobial coatings are displacing traditional metal architectures in premium device tiers. Dermatology clinics and high-end pharmacy chains in Germany and Switzerland are specifying these variants for post-procedure patient home care. The shift is compressing supplier margins on conventional stainless steel disc production while rewarding surface engineering specialists.
REACH substance restrictions on nickel release rates are tightening dermatological safety thresholds across European markets. Manufacturers must reformulate metal alloys or migrate to ceramic composites to maintain CE marking validity. German pharmacy chains are already delisting non-compliant legacy SKUs ahead of enforcement deadlines.
Specialty beauty retailers are unbundling after-sales service from hardware margins, charging separately for warranty extensions and replacement part programs. This model is visible in North American big-box electronics channels where consumers compare total cost of ownership across competing brands. Independent salon distributors resist the shift, clinging to bundled service contracts that obscure true lifecycle costs.
Epilators Market Segmentation
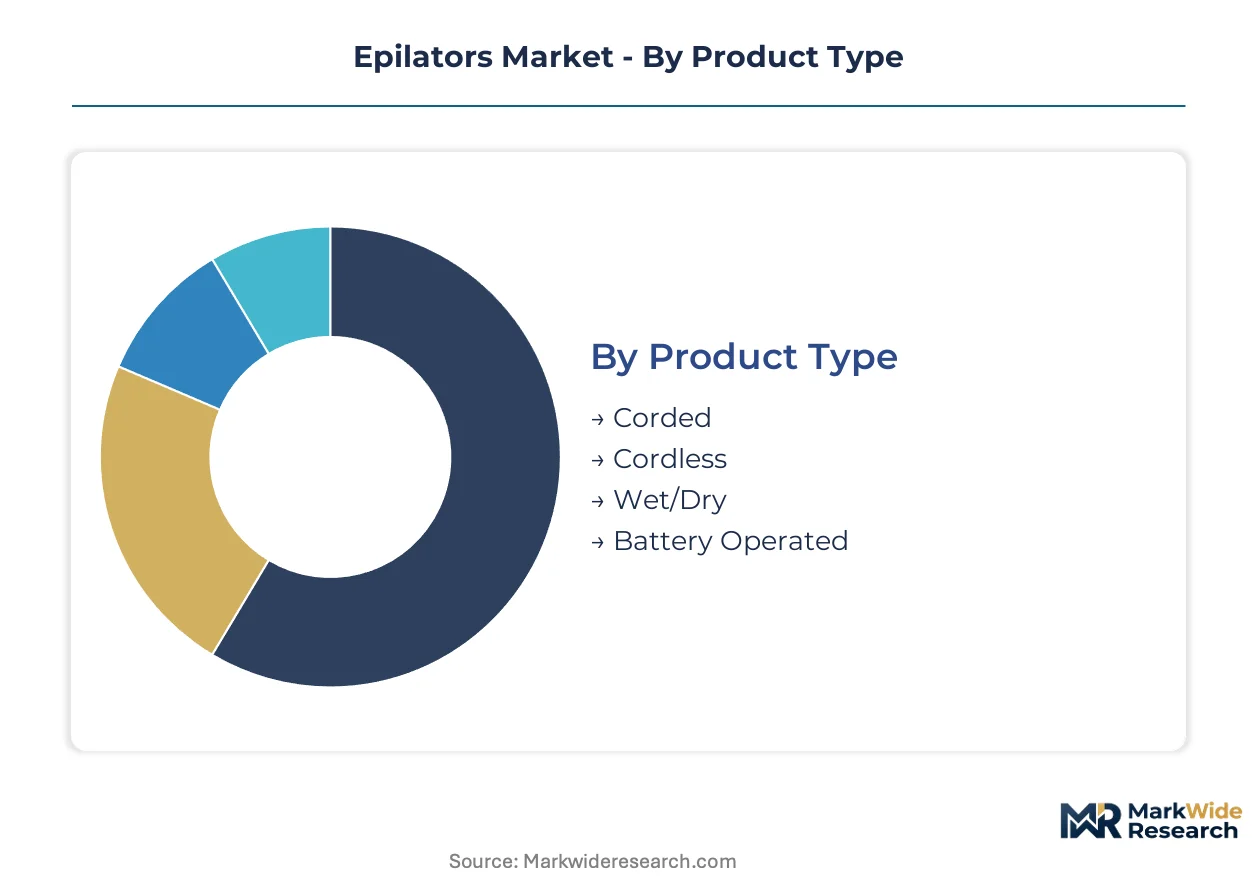
Epilator segmentation reveals how regulatory pressure and battery chemistry mandates are fragmenting product architectures across power systems, user demographics, and clinical-grade certifications. Each dimension carries distinct supply chain implications and margin profiles that shape manufacturer portfolio decisions.
Product Type:
CE marking under EU MDR and Ecodesign Directive battery mandates are bifurcating power architectures into compliant rechargeable systems and legacy corded alternatives with restricted channel access.
- Corded:Salon-grade stationary units deliver sustained power output for professional multi-client use. Demand concentrates in German and Swiss dermatology clinics where clinical-grade certification requirements favor mains-powered reliability over portable convenience.
- Cordless:Lithium-ion architectures enable wet/dry bathroom operation and comply with EU Green Deal removability mandates. Residential adoption in France and Netherlands is climbing fastest as consumers abandon alkaline-powered predecessors ahead of REACH nickel restrictions.
- Wet/Dry:IPX7-rated sealing supports full water immersion for shower use. Japanese precision-motor suppliers dominate component sourcing for this moisture-resistant tier.
- Battery Operated:Alkaline and nickel-metal hydride systems persist in price-sensitive emerging markets. Indian BIS certification delays are slowing compliant rechargeable transitions in Mumbai and Delhi retail channels.
Established volume favors corded; emerging adoption favors cordless.
End User:
Social norm shifts and channel specialization are expanding addressable demand beyond traditional demographic boundaries into male grooming and institutional procurement.
- Women:Core residential segment drives unit economics through pharmacy and big-box retail. German pharmacy chains specify extended warranty programs that lock in replacement part revenue streams.
- Men:Chest, back, and facial grooming applications are expanding most quickly. North American specialty retailers report steepest expansion trajectory as body hair removal destigmatizes among younger demographics.
- Salons:Professional-grade equipment with sterilizable attachments commands premium positioning. Swissmedic certification requirements limit supplier base for clinical deployment.
- Personal Care Stores:Beauty specialty retailers bundle after-sales service separately from hardware margins. Independent distributors in France resist unbundled pricing models that expose true lifecycle costs.
Women anchor current volume; men drive incremental expansion.
Application:
Anatomical specificity determines motor torque requirements, disc geometry, and dermatological safety thresholds across use cases.
- Facial Hair Removal:Precision micro-tweezer arrays with reduced surface contact area address sensitive upper lip and eyebrow zones. FDA 510(k) clearance requirements for light-based variants extend time-to-market versus mechanical alternatives.
- Leg Hair Removal:Wide-disc configurations optimize coverage efficiency for large surface areas. Standard consumer-grade specifications dominate this high-volume category.
- Underarm Hair Removal:Contoured head designs navigate concave anatomy with reduced pinching risk. Antimicrobial ceramic coatings specified by German pharmacy chains command premium pricing.
- Body Hair Removal:Multi-speed motors accommodate varying hair density across chest, back, and arms. Men's segment adoption is reshaping demand composition for high-torque variants.
Leg applications sustain volume leadership; facial precision commands margin premiums.
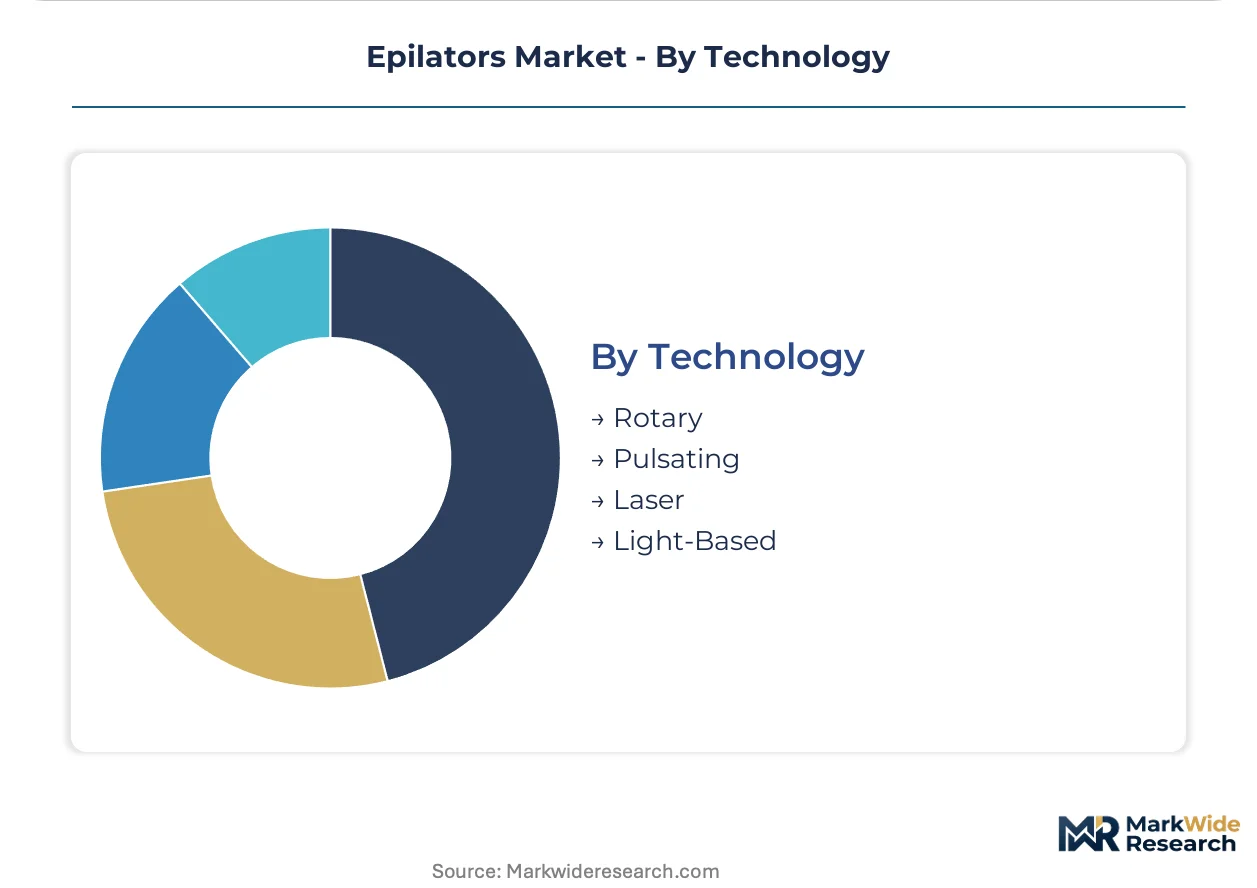
Technology:
Regulatory classification boundaries between cosmetic and medical devices are constraining light-based innovation pipelines while mechanical systems face materials compliance pressure.
- Rotary:Rotating disc assemblies deliver 20-40 tweezing actions per second through coiled spring or metal/ceramic disc architectures. German engineering clusters maintain sub-millimeter tolerance production expertise.
- Pulsating:Rapid-action spring mechanisms extract hair through oscillating plate movement. Japanese motor specialists dominate precision component supply for this category.
- Laser:Diode-based permanent reduction systems classified as medical devices under FDA 21 CFR 878.4810. 510(k) clearance timelines compress addressable market for unproven entrants.
- Light-Based:Intense pulsed light variants compete with med-spa professional treatments. CE marking under EU MDR requires documented biocompatibility testing that narrows competitive field.
Mechanical systems retain volume dominance; light-based technologies capture permanent-reduction margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Working professionals in Germany, the United States, and Japan drive cordless epilator uptake through home grooming routines. Urban middle-class expansion in India and Brazil creates first-time buyer pools with limited exposure to competing salon services.
Germany
Pharmacy chains in Berlin and Munich specify extended warranty programs that lock in replacement part revenue streams. The EU Ecodesign Directive pressures manufacturers toward rechargeable battery architectures. Braun anchors premium retail channels in Bavaria and North Rhine-Westphalia with engineering heritage positioning.
United States
Big-box electronics retailers in Texas and California report steepest expansion in men's body grooming applications. FDA 510(k) clearance requirements for light-based variants extend time-to-market versus mechanical alternatives. Philips captures volume through broad retail distribution in the Northeast and Pacific Coast corridors.
Japan
Specialty beauty channels in Tokyo and Osaka command loyalty for precision-motor technology. METI efficiency standards shape domestic product specifications. Panasonic Corporation differentiates through sub-millimeter tolerance component assembly in the Kansai industrial cluster.
India
Urban middle-class expansion in Mumbai and Delhi creates first-time buyer pools with limited salon service exposure. BIS certification delays slow compliant rechargeable transitions in Maharashtra and Gujarat retail channels. Havells India Ltd. and Morphy Richards India compete in price-sensitive segments across Bangalore and Chennai.
Brazil
Social norm shifts around male hair removal expand addressable demand in São Paulo and Rio de Janeiro. ANVISA medical device classification creates regulatory friction for light-based entrants. Local distributors resist unbundled pricing models that expose true lifecycle costs in the Southeast region.
Epilators Market Competitive Landscape
Player mix skews toward diversified consumer electronics conglomerates with grooming divisions and specialized personal care appliance manufacturers. Market structure concentrates around German engineering heritage brands and Japanese precision-motor specialists competing for pharmacy and specialty channel access. Three archetypes dominate: heritage engineering firms leveraging clinical-grade certifications, volume-oriented conglomerates optimizing retail distribution density, and precision-motor specialists capturing premium positioning through component superiority. Competitive moves center on M&A to acquire dermatological safety testing capabilities and geographic expansion into underpenetrated Indian and Brazilian urban markets.
Within the heritage engineering tier, Braun and Beurer GmbH exemplify German-origin positioning through CE marking compliance and pharmacy channel relationships. Philips represents the volume-oriented conglomerate archetype with broad retail distribution across North American and European mass-market channels. Panasonic Corporation anchors the precision-motor specialist position, leveraging Japanese manufacturing expertise for moisture-resistant and high-torque variants in Asian specialty channels.
| Leading Market Players |
|---|
| Philips |
| Braun |
| Panasonic Corporation |
| Beurer GmbH |
| Conair Corporation |
| Procter & Gamble |
| Emjoi Inc. |
| Havells India Ltd. |
| Morphy Richards India |
| Others |
Supply & Pricing Matrix
CE marking under EU MDR gates both supplier qualification and price stratification simultaneously, as clinical-grade certification creates tiered access to pharmacy channels that command premium positioning while uncertified makers compete on unit economics in mass retail. This regulatory architecture compresses margins for alkaline-powered legacy devices while rewarding rechargeable lithium-ion architectures with extended warranty pricing power.
Pricing Analysis
Cost-plus contracts with cobalt and lithium carbonate indexation dominate procurement agreements for cordless variant manufacturers, creating margin volatility that pricing stratifies across premium, standard, and economy tiers. Brand heritage and dermatological safety certification drive differentiation in German pharmacy channels, while price erosion runs through alkaline-powered segments in Indian price-sensitive retail as BIS compliance delays compress local manufacturer margins. Professional salon buyers exhibit lowest price sensitivity due to sterilization requirements and warranty bundling.
Supply Chain Analysis
Inventory cycles for precision micro-motors stretch 12-16 weeks, constraining responsiveness to demand spikes in wet/dry variants. Component sourcing draws from Japanese motor specialists, German precision-engineering clusters, and Chinese battery cell manufacturers, with cylindrical lithium-ion cells resting on cobalt supply from the DRC and Chilean lithium brine operations. Single-source vulnerability concentrates in sub-millimeter tolerance ceramic disc production, while distribution runs through pharmacy chains in Europe, big-box electronics in North America, and specialty beauty retailers in Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
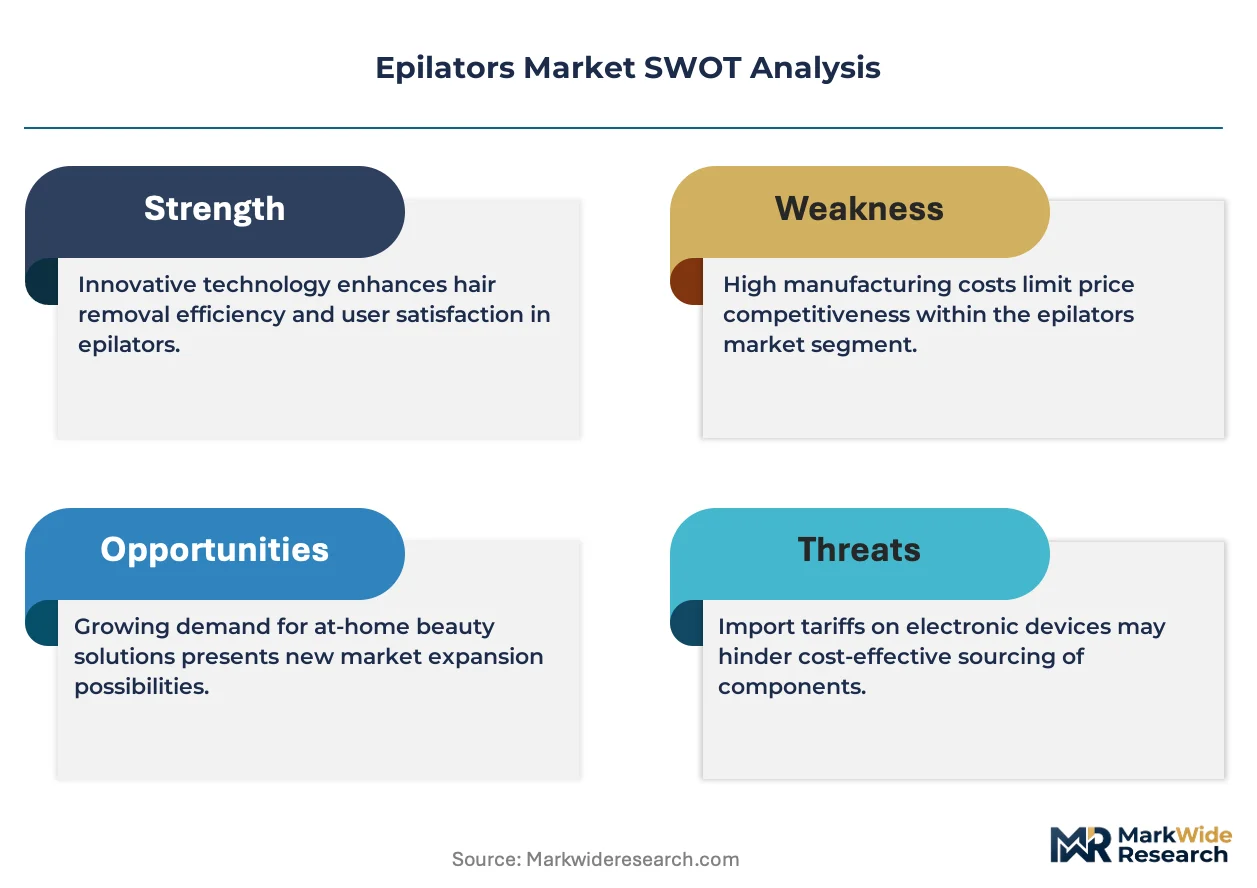
This market demands substitution defense against med-spa IPL treatments that promise permanent hair reduction, eroding repurchase intent for mechanical devices and compressing the addressable base for traditional epilator incumbents.
For Market Incumbents: Consolidate dermatological safety testing capabilities through acquisition of certified testing laboratories, locking out unqualified entrants from CE-marked pharmacy channels. Backward integration into ceramic disc production reduces exposure to Japanese and German precision-engineering talent shortages while capturing margin pools in antimicrobial-coated premium tiers. For New Entrants and Emerging Players: Subscription blade replacement services represent the most penetrable white-space target, as incumbents under-serve direct-to-consumer replenishment demand currently captured by third-party consumable suppliers. India's urban middle-class expansion offers lowest competitive density for compliant rechargeable variants, with entry through e-commerce platforms bypassing BIS certification delays in traditional retail channels. For Investors and Strategic Acquirers: EU MDR enforcement deadlines reshape the acquisition landscape toward certified clinical-grade suppliers with documented biocompatibility testing, as delisting of non-compliant legacy SKUs accelerates consolidation. Target vertically integrated manufacturers with captive ceramic disc production and pharmacy channel relationships. Watch REACH nickel release rate enforcement as the signal indicating margin compression timing for metal-alloy dependent producers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Unlocks pharmacy channel access in Germany and Switzerland where clinical-grade certification commands premium positioning. |
| Backward Integration into Ceramic Disc Production | Reduces dependency on Japanese and German precision-engineering clusters facing skilled technician shortages. |
| Direct-to-Consumer Subscription Launch | Captures recurring revenue streams for replacement cartridges previously lost to third-party consumable suppliers. |
| Battery Removability Design Architecture | Ensures EU Green Deal compliance ahead of repairability scoring mandates extending product lifecycles. |
| Men's Grooming Brand Extension | Addresses fastest-growing end-user segment as social norms shift around male body hair removal. |
Research Methodology
Desk research of customs trade records, EU MDR filing databases, and battery chemistry patent filings preceded structured interviews with product development executives at grooming device manufacturers, procurement leads at German pharmacy chains, and regulatory affairs specialists navigating CE marking pathways. Primary fieldwork with Japanese precision-motor suppliers and Indian BIS certification consultants validated secondary findings on supply constraints and market entry friction. Bottom-up unit economics modeling triangulated against top-down category spend estimates from retail audit data.
Variance decomposition across power system architectures, user demographics, and regional regulatory clusters anchored the analytical framework over the projection horizon. Segmentation modeling captured cordless versus corded adoption patterns, clinical-grade versus consumer-grade certification tiers, and wet/dry bathroom use penetration. CAGRs derived from trend extrapolation of lithium-ion battery cost curves, REACH compliance timeline assumptions, and male grooming social norm diffusion rates across urban middle-class cohorts.
Underlying assumptions cover REACH nickel restriction enforcement schedules and FDA 510(k) clearance timeline stability, with deviation risk concentrated in cobalt price volatility and dermatological safety standard tightening. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Pre-Shave Products Market
Personal Grooming Products
Global Consumer Use IPL Hair Removal Devices Market
Personal Grooming Products
Compostable Toothbrush Market
Personal Grooming Products
Insoles Market
Personal Grooming Products
Global Beard Balm Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
Foot Care Products Market
Personal Grooming Products
Global Sex Toys Market
Personal Grooming Products
Nose & Ear Hair Trimmers Market
Personal Grooming Products
Underarm Sweat Pads Market
Personal Grooming Products
Sexual Lubricant Market
Personal Grooming Products
Wet Shave Market
Personal Grooming Products
Global Mosquito Repellent Products Market
Personal Grooming Products
Self-Tanning Products Market