
 Hand Hygienic Product Market | 2026-2036
Hand Hygienic Product Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Hygienic Product Market Foresight
Modular dispenser-refill bundling is restructuring how facilities managers evaluate total cost of ownership in institutional hygiene programs. GOJO Industries leverages its touch-free hardware ecosystem to sustain recurring consumable revenue across hospital networks. Ecolab dominates foodservice and hospitality channels with bundled chemical-dispensing programs that integrate training and compliance auditing.
Hand hygienic products encompass antimicrobial formulations, surfactant-based cleansers, and alcohol-based rubs engineered to reduce transient microbial flora on epidermal surfaces, typically incorporating active concentrations of ethanol, isopropanol, benzalkonium chloride, or chlorhexidine gluconate within pH-balanced vehicles. Their primary commercial purpose spans infection prevention in clinical settings, food safety assurance in commercial kitchens, and personal health maintenance in residential environments. Foam soaps lead institutional procurement due to per-use cost efficiency and reduced water consumption, while alcohol-based hand sanitizers represent the fastest-growing formulation segment driven by healthcare protocol adoption. Natural and non-alcoholic variants occupy emerging margin pools as clean-label preferences penetrate consumer and select professional channels.
The FDA governs over-the-counter antiseptic drug products through its Tentative Final Monograph framework, while the EPA regulates antimicrobial claims on hard-surface and hand-contact products under FIFRA, creating dual compliance pathways that formulation chemists must navigate. The WHO Guidelines on Hand Hygiene in Health Care establish clinical efficacy benchmarks that national health systems adopt, directly shaping product specifications for hospital tenders. Stakeholders must monitor evolving monograph rulings on triclosan and emerging biocide restrictions across multiple jurisdictions to anticipate reformulation requirements and competitive repositioning.
Market Dynamics
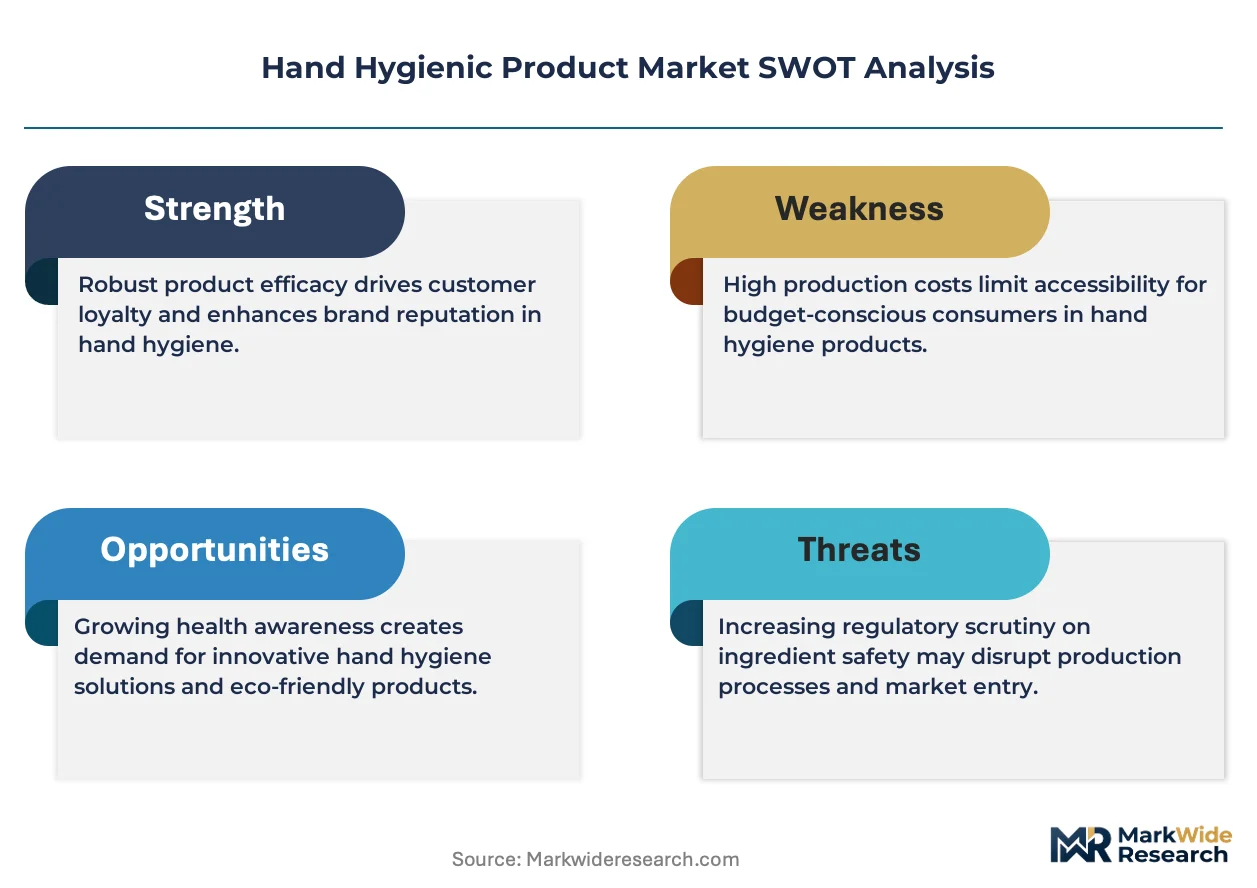
Automated dispenser-to-refill bundling contracts are restructuring procurement economics across hospital networks, compressing vendor margins while locking in multi-year consumable commitments through hardware-software ecosystems.
Growth Catalysts
- WHO Hand Hygiene Guidelines:Clinical efficacy benchmarks embedded in national health system tenders mandate alcohol-based rub formulations, institutionalizing product specifications across procurement channels.
- Foodservice safety protocols:Commercial kitchen HACCP compliance programs drive surfactant-based cleanser volume through mandated hand-wash station density requirements.
- Touch-free sensor technology:Infrared-activated dispensing systems reduce cross-contamination risk perception in high-traffic healthcare corridors, accelerating hardware refresh cycles.
Market Restraints
- Ethanol feedstock volatility:Corn and sugarcane commodity price swings directly compress formulation margins for alcohol-based rub producers without long-term supply contracts.
- EPA FIFRA registration timelines:Antimicrobial claim approvals for novel biocide active ingredients extend 18-36 months, freezing pipeline innovation and favoring incumbent chemistries.
- Waterless cleanser substitution:Alcohol-based hand rubs face displacement pressure from benzalkonium chloride foams in facilities with flammability storage constraints or religious usage restrictions.
Strategic Opportunities
- Clean-label consumer segment:Non-alcoholic, plant-derived formulations capture premium shelf space in retail channels as ingredient transparency preferences migrate from food to personal care.
- India healthcare infrastructure expansion:Ayushman Bharat hospital accreditation standards create institutional demand for WHO-compliant hand hygiene programs in tier-2 and tier-3 cities.
- IoT-enabled compliance monitoring:Sensor-integrated dispensers that log usage events and trigger refill orders are consolidating facility management software stacks into hygiene-as-a-service models.
Industry Challenges
- Formulation chemist talent scarcity:Dual FDA Tentative Final Monograph and EPA FIFRA expertise commands premium compensation, constraining mid-tier manufacturer pipeline development.
- Legacy dispenser infrastructure incompatibility:Proprietary cartridge geometries and electronic lockout mechanisms in installed hardware bases block third-party refill substitution, complicating competitive entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Hygienic Product Market |
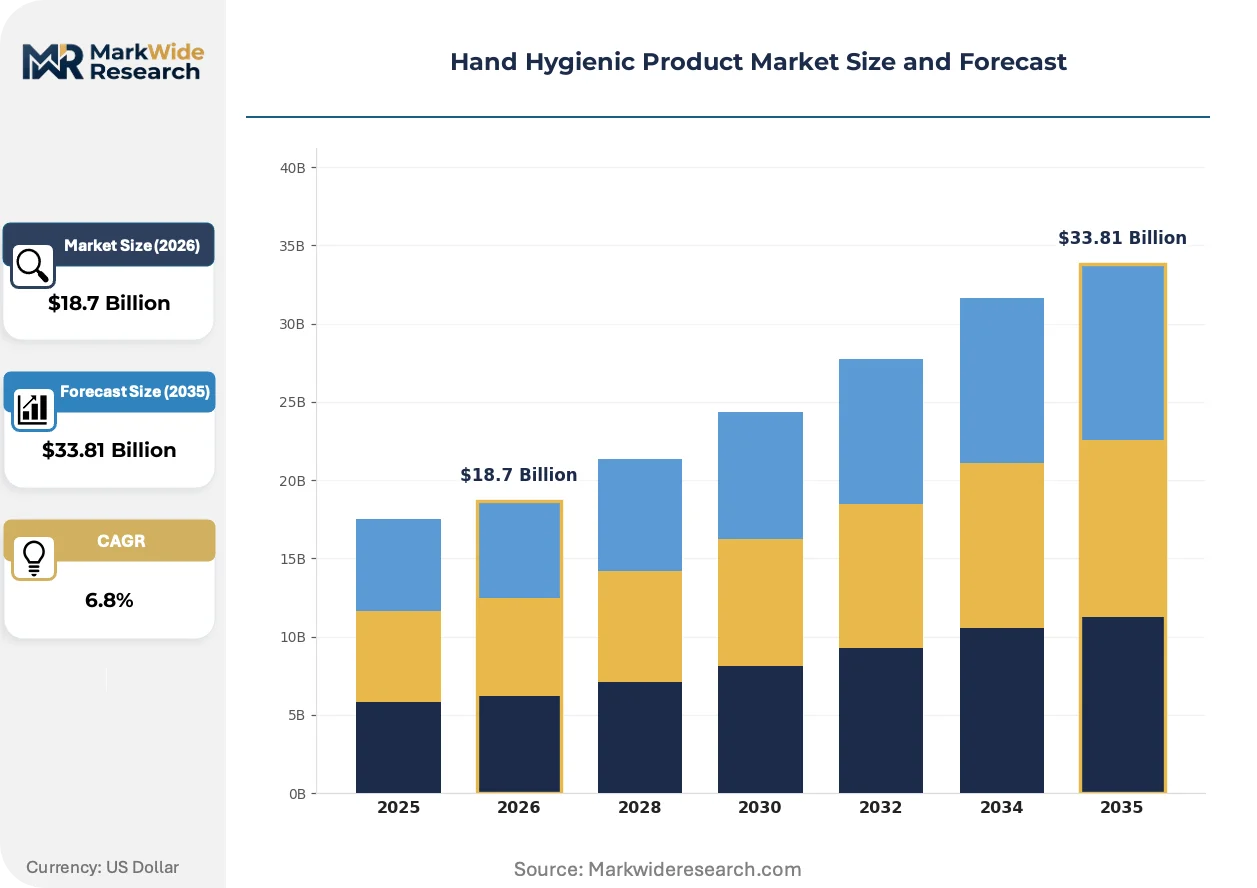
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Sanitizers, Soap Bars, Liquid Soaps, Foam Soaps End User: Hospitals, Schools, Restaurants, Households Distribution Channel: Online Retail, Supermarkets, Pharmacies, Convenience Stores Formulation: Alcohol-Based, Non-Alcoholic, Natural, Antibacterial |
| Companies Covered | GOJO Industries, Reckitt Benckiser Group, Procter and Gamble, Unilever, 3M Company, Ecolab, Henkel AG and Company, The Clorox Company, Kimberly-Clark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Hygienic Product Market Shifts & Advancements
Active ingredient review cycles and connected hardware penetration are compressing product lifecycles while expanding data-rich service layers that transcend commodity formulation sales.
Foam soap concentrate technology is consolidating institutional procurement preferences through per-dose cost efficiency and reduced water consumption metrics that align with facility sustainability targets. Hospital engineering departments specify foam-dispensing hardware in new construction and renovation tenders, displacing liquid soap infrastructure. The technology is consolidating vendor relationships around bundled dispenser-refill contracts that extend contract durations and raise switching costs.
The FDA's ongoing triclosan ban enforcement and benzalkonium chloride safety review are forcing reformulation roadmaps across antiseptic drug product portfolios. Manufacturers must navigate Tentative Final Monograph uncertainty while maintaining supply continuity for hospital formularies. Alcohol-based rubs and alternative biocide chemistries are capturing shelf space and tender specifications as legacy active ingredients face regulatory sunset.
Facility managers now specify outcome-based hygiene compliance contracts that bundle product supply with usage monitoring and staff training accountability. Distributor sales organizations are restructuring compensation around service-level agreements rather than case volume, displacing traditional product-centric relationships. This shift concentrates procurement decision authority with infection prevention departments and quality officers in integrated delivery networks across the United States.
Hand Hygienic Product Market Segmentation
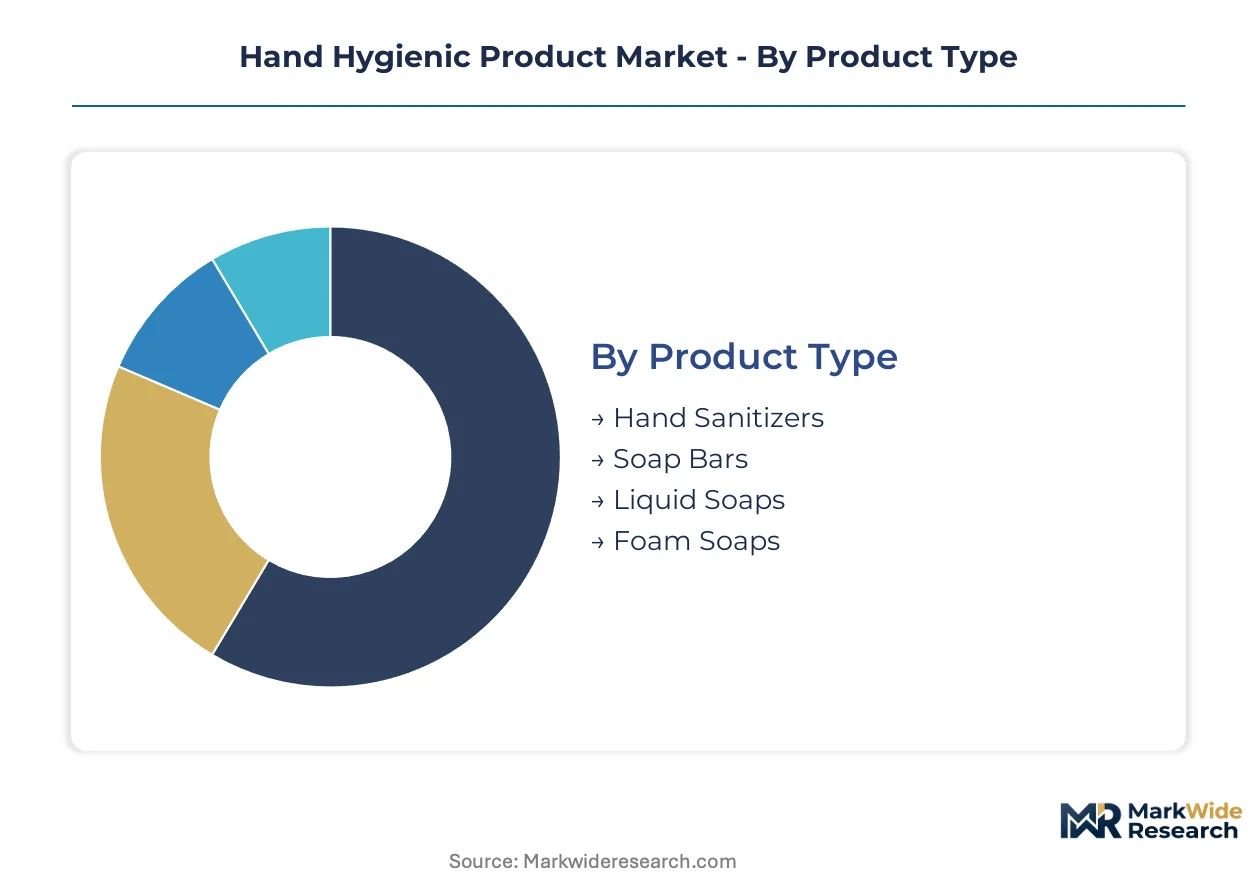
Procurement specifications diverge sharply across hand hygienic product segments, with FDA Tentative Final Monograph compliance for antiseptic drug products creating distinct regulatory tiers that reshape vendor qualification and hospital formulary access.
Product Type:
FDA OTC monograph alignment varies: alcohol-based rubs fall under antiseptic drug rules, while surfactant cleansers navigate cosmetic or EPA FIFRA pathways depending on antimicrobial claims.
- Hand Sanitizers:Ethanol or isopropanol formulations at 60-95% concentration dominate clinical procurement through WHO Guidelines compliance. Demand concentrates in United States hospital networks where Joint Commission accreditation mandates alcohol-based rub availability at point-of-care.
- Foam Soaps:Concentrated surfactant systems dispensed through specialized aerating hardware achieve per-use cost advantages. Engineering departments specify these in new United States healthcare construction for water conservation credits and reduced consumption volume.
- Liquid Soaps:Traditional pump-dispensed formulations retain installed base in older facilities.
- Soap Bars:Solid format persists in residential and select hospitality channels with minimal regulatory burden.
Leading the category by volume: Foam Soaps. Growing fastest: Hand Sanitizers.
End User:
Contract structures and compliance accountability vary dramatically by buyer sophistication, from outcome-based hygiene-as-a-service in integrated delivery networks to transactional retail purchasing.
- Hospitals:Infection prevention departments drive specifications through evidence-based procurement frameworks. United States health systems bundle dispenser hardware, consumable supply, and compliance monitoring into multi-year agreements with infection rate guarantees.
- Restaurants:HACCP compliance programs mandate hand-wash station density and surfactant-based cleanser availability. Food safety audits in United States commercial kitchens enforce product documentation and training record retention.
- Schools:District procurement favors bulk foam soap contracts with durability specifications for high-traffic youth environments.
- Households:Retail shelf placement and seasonal promotional cycles dominate purchase decisions with minimal regulatory interaction.
Contract value concentrates with Hospitals. Steepest expansion trajectory: Restaurants post-pandemic protocol permanence.
Distribution Channel:
Channel selection determines margin capture and customer data access, with institutional direct contracting diverging sharply from retail intermediation.
- Supermarkets:Mass-market velocity drives volume placement for consumer hand sanitizers and soap bars. United States retail chains negotiate slotting fees and promotional calendars that compress manufacturer margins.
- Online Retail:E-commerce penetration accelerates subscription replenishment models and direct-to-consumer clean-label variants. Amazon and specialty health platforms capture growing share of United States household purchasing.
- Pharmacies:Professional recommendation influence sustains premium positioning for dermatologist-tested formulations.
- Convenience Stores:Impulse purchase placement captures travel-size and single-use sanitizer demand.
Volume leadership: Supermarkets. Channel climbing fastest: Online Retail through subscription automation.
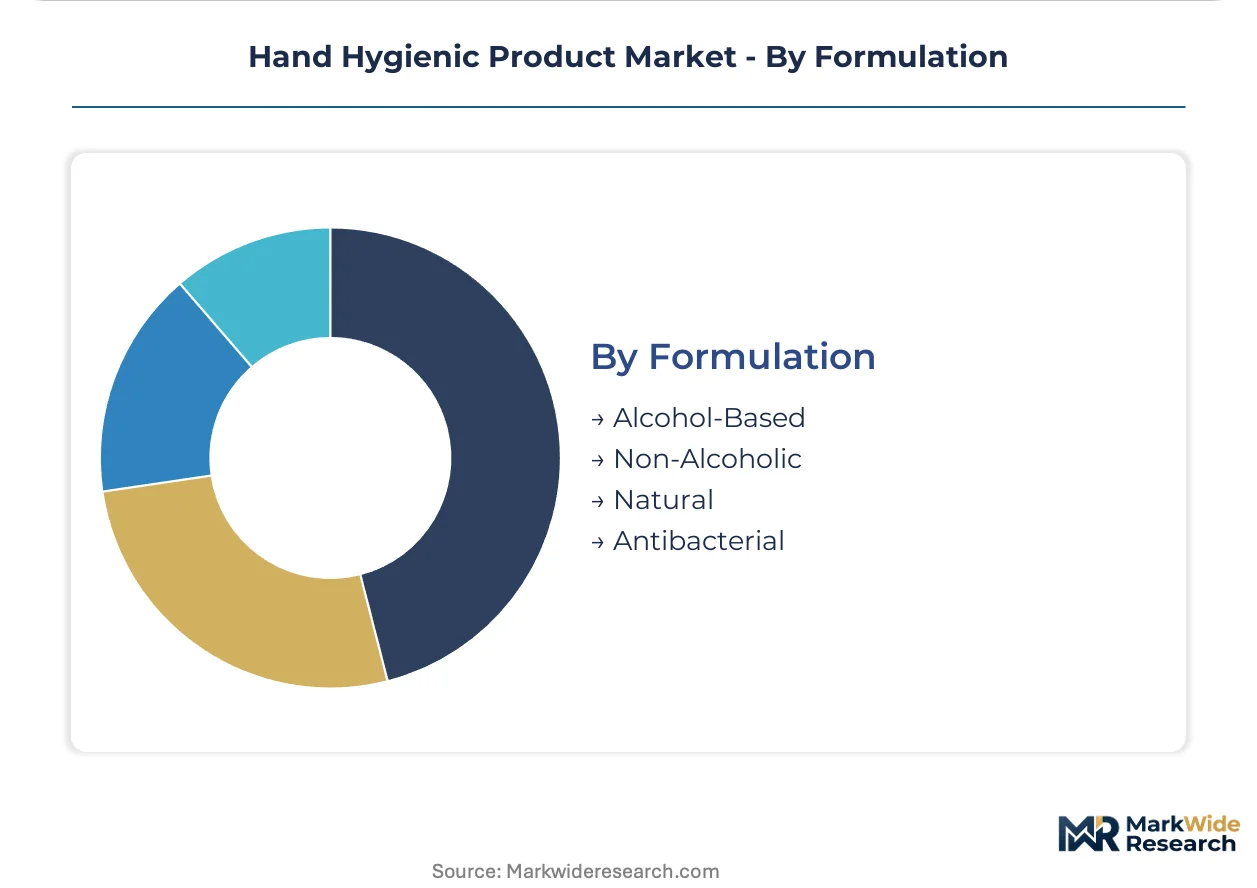
Formulation:
Active ingredient chemistry dictates regulatory pathway, efficacy claim permissibility, and storage safety requirements that segment addressable markets.
- Alcohol-Based:Ethanol and isopropanol formulations at 60-95% concentration meet WHO efficacy benchmarks for healthcare hand hygiene. FDA monograph alignment enables broad-spectrum antiseptic claims in United States clinical marketing.
- Natural:Plant-derived surfactants and essential oil systems capture clean-label premium in retail channels. United States consumer ingredient transparency preferences migrate from food to personal care applications.
- Antibacterial:Benzalkonium chloride and chlorhexidine gluconate alternatives serve facilities with flammability constraints or religious usage restrictions.
- Non-Alcoholic:Quaternary ammonium compound formulations occupy niche institutional segments with specific storage limitations.
Clinical procurement dominance: Alcohol-Based. Gaining share fastest: Natural formulations in retail premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity for hand hygienic products concentrates in the United States and Western Europe, while consumption growth accelerates fastest in emerging Asian healthcare infrastructure. This geographic split shapes trade flows and regulatory harmonization pressures.
United States
Hospital procurement departments drive institutional volume through Joint Commission accreditation mandates. The FDA Tentative Final Monograph governs antiseptic drug claims, while EPA FIFRA regulates hard-surface antimicrobial products. Chicago and Cleveland anchor manufacturing clusters where dispenser hardware and bulk formulation production co-locate.
Germany
Industrial hygiene demand from automotive and pharmaceutical manufacturing sustains premium formulation volumes. ECHA REACH compliance requirements shape biocide active ingredient selection across European formulations. The Rhine-Ruhr corridor hosts concentrated production of automated dispensing systems for export markets.
China
Domestic healthcare infrastructure expansion under Healthy China 2030 drives institutional procurement growth. NMPA and GB standards govern antiseptic product registration and manufacturing quality. Yangtze River Delta manufacturing zones supply alcohol-based rub concentrate for regional healthcare networks.
India
Ayushman Bharat hospital accreditation standards create institutional demand for WHO-compliant hand hygiene programs. CDSCO regulates antiseptic drug products while BIS standards apply to soap and cleanser quality. Maharashtra and Gujarat manufacturing hubs produce cost-competitive surfactant formulations for domestic and export markets.
Brazil
Foodservice safety protocol adoption in commercial kitchens drives surfactant cleanser volume through HACCP compliance mandates. ANVISA governs antiseptic product registration with alignment to Mercosur technical regulations. São Paulo state concentrates formulation manufacturing and distribution infrastructure for Latin American markets.
Hand Hygienic Product Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with institutional contracting capabilities. Market concentration remains moderate with tiered vendor relationships across healthcare, foodservice, and consumer channels. Three archetypes dominate: integrated hygiene service providers, consumer packaged goods multinationals, and specialized dispenser hardware manufacturers. M&A activity targets compliance monitoring technology and regional formulation capacity.
Among integrated hygiene service providers, Ecolab and GOJO Industries exemplify the bundled hardware-consumable-contracting model. Reckitt Benckiser Group occupies a position within the consumer-facing antiseptic tier alongside Procter and Gamble and Unilever. These anchors represent divergent strategic postures: institutional service depth versus retail brand velocity versus manufacturing scale.
| Leading Market Players |
|---|
| GOJO Industries |
| Reckitt Benckiser Group |
| Procter and Gamble |
| Unilever |
| 3M Company |
| Ecolab |
| Henkel AG and Company |
| The Clorox Company |
| Kimberly-Clark |
| Others |
Supply & Pricing Matrix
Automated dispenser-to-refill bundling contracts across United States hospital networks force suppliers to absorb hardware costs upfront while capturing margin through multi-year consumable lock-in. This procurement structure concentrates pricing power with integrated delivery networks that specify outcome-based compliance guarantees.
Pricing Analysis
Margin tightening in institutional tiers reflects automated dispenser hardware subsidies bundled into per-milliliter refill pricing. Three-tier pricing structure across premium WHO-compliant formulations, standard clinical-grade products, and economy surfactant cleansers segments buyer sophistication. Cost compression accelerates in foodservice channels as HACCP audit frequency raises compliance documentation burdens. Hospital procurement committees demonstrate lowest price sensitivity due to infection rate liability exposure, while school districts and municipal buyers negotiate aggressively on per-case metrics.
Supply Chain Analysis
Dual-sourcing requirements in Joint Commission-accredited facilities mandate qualified backup suppliers for alcohol-based rub concentrates and foam soap formulations. Manufacturing concentrates in the United States, Germany, and China, with ethanol feedstock drawing from corn belt agricultural processing and synthetic alcohol production. Benzalkonium chloride and chlorhexidine gluconate active ingredients rest on Indian and Chinese chemical synthesis capacity. Single-source vulnerability permeates specialized dispenser hardware electronics sourced from Yangtze River Delta component clusters. Distribution runs through regional healthcare distributors with GPO contract administration, direct foodservice chemical supply programs, and retail mass-market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist scarcity constrains pipeline development across mid-tier manufacturers, propping pricing for qualified suppliers capable of dual FDA-EPA compliance navigation.
For Market Incumbents: Extend touch-free hardware ecosystem penetration through firmware lock-in and proprietary cartridge geometries that block third-party refill substitution. Build captive ethanol distillation capacity in corn belt proximate to hospital network density to defend margin position against commodity feedstock volatility. Prioritize compliance monitoring software acquisition to deepen hygiene-as-a-service contract durations. For New Entrants and Emerging Players: IoT-enabled dispenser retrofit kits offer a technology-first wedge into installed base infrastructure without requiring proprietary hardware replacement. Target tier-2 and tier-3 Indian hospital networks where Ayushman Bharat accreditation creates WHO-compliant formulation demand without entrenched vendor relationships. Pursue direct contracting with infection prevention departments rather than procurement intermediaries. For Investors and Strategic Acquirers: The window for entry favors compliance monitoring technology specialists with FDA 21 CFR Part 11 validation and hospital IT system integration capabilities. Long-term viability hinges on recurring revenue density rather than transactional formulation sales. Watch for EPA FIFRA registration timeline acceleration as signal for pipeline innovation thaw and incumbent chemistry displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Production | Corn belt distillation capacity insulates margin from agricultural commodity price cycles. |
| IoT Compliance Monitoring Platform Launch | Sensor-integrated dispensers capture usage data for outcome-based hygiene contracting. |
| Natural Formulation Certification Investment | Clean-label positioning captures premium retail shelf space and dermatologist recommendation. |
| India Manufacturing Footprint Expansion | Maharashtra and Gujarat hubs serve Ayushman Bharat hospital network growth with tariff-advantaged supply. |
| EPA FIFRA Registration Acceleration Program | Novel biocide active ingredient approval unlocks formulation differentiation beyond alcohol-based rubs. |
Research Methodology
Document review covered FDA Tentative Final Monograph proceedings, EPA FIFRA registration databases, and WHO Guidelines on Hand Hygiene technical documents, complemented by interviews with hospital infection prevention officers, foodservice safety auditors, and institutional procurement directors. Secondary validation drew from customs trade data, healthcare GPO contract filings, and chemical industry association reports. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, and formulation chemistry dimensions.
Cross-reference between historical procurement volume patterns and expert panel input anchored the analytical framework across the projection horizon. Segmentation modeling incorporated product type, end user sophistication tier, distribution channel structure, and active ingredient regulatory pathway. CAGRs derived from trend extrapolation moderated by regulatory timeline uncertainty and healthcare infrastructure investment cycles. Forecast inputs included hospital construction permit data, HACCP audit frequency trends, and ethanol feedstock futures market indicators.
Several conditions sit outside the modeled scope, including unforeseen biocide active ingredient safety reviews, pandemic-driven demand spikes, and abrupt Joint Commission protocol revisions. Forecasts reflect documented assumptions about regulatory timeline stability and healthcare capital expenditure continuity. Deviation in EPA FIFRA registration pace or WHO guideline revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Disposable Slippers Market
Personal Grooming Products
Insect Repellent Wipes Market
Personal Grooming Products
Heated Razor Starter Kit Market
Personal Grooming Products
US Percussion Massage Gun Market
Personal Grooming Products
Shoe Deodorizer Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
Latin America Hand Soap Market
Personal Grooming Products
Sexual Lubricant Market
Personal Grooming Products
AI Toothbrush Market
Personal Grooming Products
Smart Hairbrush Market
Personal Grooming Products
Lice Combs Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Shavers Market
Personal Grooming Products
Feminine Hygiene Products Market
Personal Grooming Products
Disposable Razor Blades Market
Personal Grooming Products
Infant Mosquito Repellent Market