
 Handheld Massager Market | 2026-2036
Handheld Massager Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Massager Market Analysis
The capital-intensity gap between premium R&D platforms and assembly-heavy budget producers is rotating competitive advantage toward firms with in-house motor and battery engineering. Therabody leverages proprietary percussive drive systems to sustain pricing power in professional sports channels. HoMedics anchors North American retail presence through mass-market distribution partnerships.
A handheld massager is a portable electromechanical or manual device designed to deliver localized mechanical vibration, percussion, or thermal therapy to soft tissue, typically operating at frequencies between 20–60 Hz and amplitudes of 10–16 mm for electric percussive variants. Its primary commercial purpose spans consumer wellness, sports recovery, and clinical adjunct therapy for musculoskeletal relief. Percussion and infrared types command premium positioning due to deeper tissue penetration and heat-assisted circulation benefits. Battery-operated and rechargeable power sources are capturing volume leadership as lithium-ion energy density improvements enable cordless runtime exceeding 150 minutes per charge.
The FDA regulates electric massagers marketed with therapeutic claims as Class I or II medical devices, requiring 510(k) clearance for percussive units with specified power thresholds. The EU MDR and CE marking framework impose biocompatibility and electromagnetic compatibility testing that raises barriers for uncertified Asian exporters. Stakeholders must monitor evolving battery transport regulations from ICAO and IATA, as lithium-cell shipping restrictions increasingly constrain cross-border e-commerce fulfillment speed and cost structures.
Market Dynamics
The handheld massager market is bifurcating around battery chemistry mastery and motor control firmware, as cordless runtime thresholds above 150 minutes separate viable competitors from assembly-only operators dependent on commodity cell suppliers.
Growth Catalysts
- Lithium-ion energy density gains:Cell manufacturers in South Korea and Japan are delivering 20% capacity improvements per generation, enabling professional-grade devices to match corded performance without tethering constraints.
- EU MDR compliance premium:The 2021 Medical Device Regulation reclassification creates a two-tier market where CE-marked therapeutic claims command 40-60% price premiums over general wellness positioning.
- Post-workout recovery normalization:Boutique fitness chains and CrossFit affiliates are standardizing percussive therapy as mandatory cool-down protocol, embedding device expectations into membership value propositions.
Market Restraints
- Cobalt and lithium carbonate volatility:Battery raw material spot markets swing 30-50% quarterly, compressing gross margins for brands without multi-year cathode supply agreements.
- Shenzhen-dominated PCB fabrication:Over 70% of motor control boards concentrate in Pearl River Delta contract manufacturers, creating single-geography disruption exposure.
- Thermal runaway shipping restrictions:IATA lithium battery transport rules add 3-5 days to cross-border fulfillment and require specialized hazmat packaging that erodes direct-to-consumer unit economics.
Strategic Opportunities
- Clinical reimbursement pathways:Physical therapy practices in Germany and the Netherlands are piloting device rental models billable under statutory health insurance adjunct therapy codes.
- AI-guided pressure feedback:Integration of force sensors with smartphone apps enables real-time dosage optimization, differentiating premium tiers from fixed-speed alternatives.
- Specialty pharmacy distribution:CVS and Walgreens are expanding recovery device sections adjacent to pain management aisles, creating impulse purchase exposure to chronic condition shoppers.
Industry Challenges
- Embedded systems firmware talent scarcity:Motor control algorithm development requires rare expertise in sensor fusion and vibration dampening, forcing brands to poach from automotive or robotics sectors.
- 510(k) clearance timelines:FDA review of percussive devices with therapeutic claims stretches 12-18 months, delaying revenue recognition for R&D-heavy entrants.
- Patent thickets around amplitude mechanisms:Early movers have locked 10-16 mm stroke lengths and angled handle geometries, forcing late entrants into inferior ergonomic designs or licensing negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Massager Market |
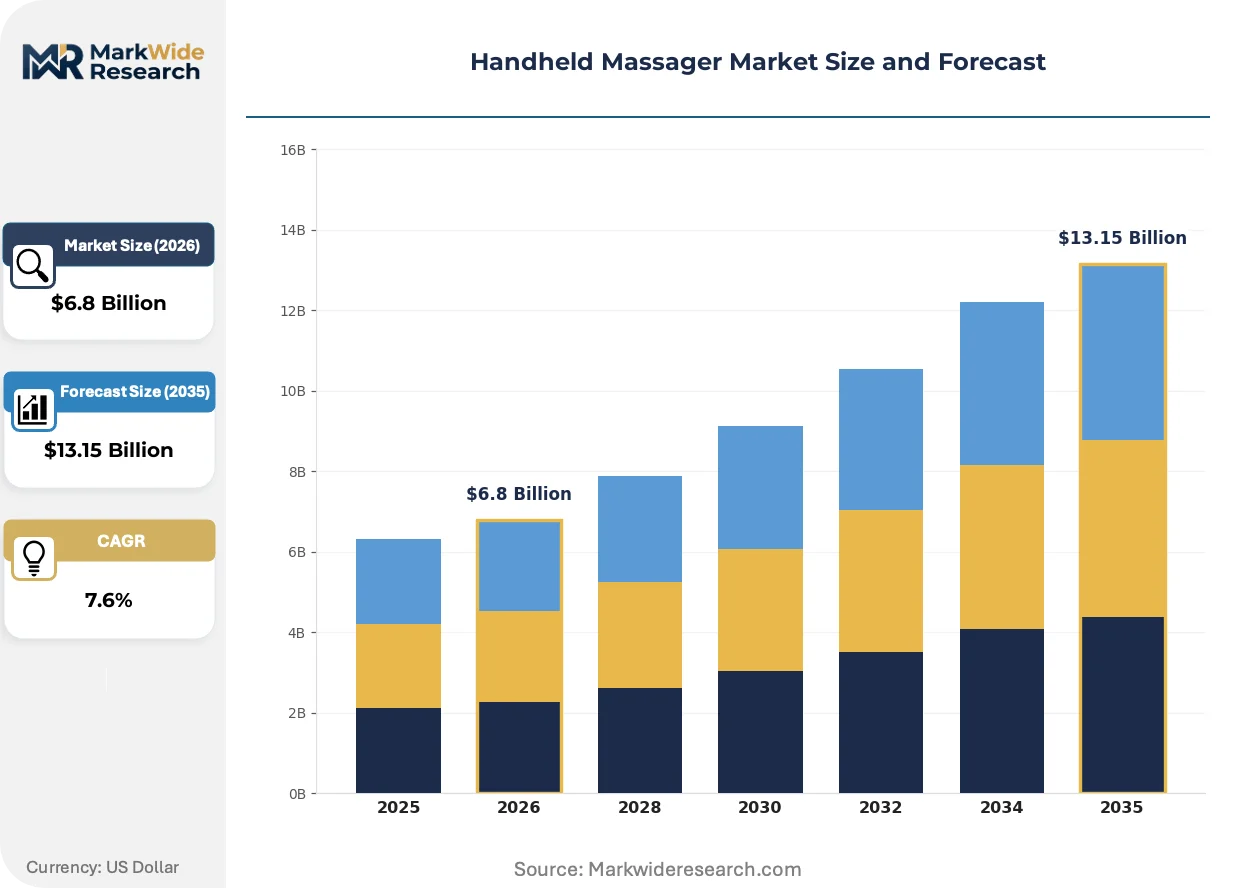
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electric, Manual, Percussion, Infrared Intensity Level: Low, Medium, High, Adjustable Target User: Athletes, Seniors, Office Workers, Fitness Enthusiasts Power Source: Battery-operated, Plug-in, Rechargeable, Corded |
| Companies Covered | Breo, Naipo, Theragun, Therabody, Zyllion, Hyperice, RENPHO, Lifepro, HoMedics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Massager Market Emerging Trajectories
Product architecture is fragmenting into modular subsystems as brands race to swap proprietary motor platforms for standardized component ecosystems that accelerate refresh cycles and reduce service liability.
Brushless DC motor-inverter integration is decomposing the traditional separation between power electronics and mechanical drive trains. Sports medicine clinics and collegiate athletic departments are specifying these unified platforms for fleet standardization. The consolidation is compressing supplier margins for standalone motor vendors while rewarding semiconductor firms with integrated gate driver expertise.
EU MDR technical documentation requirements are forcing manufacturers to maintain post-market surveillance systems with mandatory adverse event reporting to national competent authorities. The compliance burden is eliminating budget private-label exporters from European therapeutic channels. German notified bodies are experiencing 14-month backlog queues, advantaging early filers with established quality management systems.
Subscription-based accessory replenishment is replacing transactional hardware sales for high-usage segments. Marathon training collectives and physical therapy chains are contracting for automated attachment and battery replacement programs. This model is most visible in California and Texas wellness markets where customer lifetime value metrics dominate acquisition cost calculations.
Handheld Massager Market Segmentation
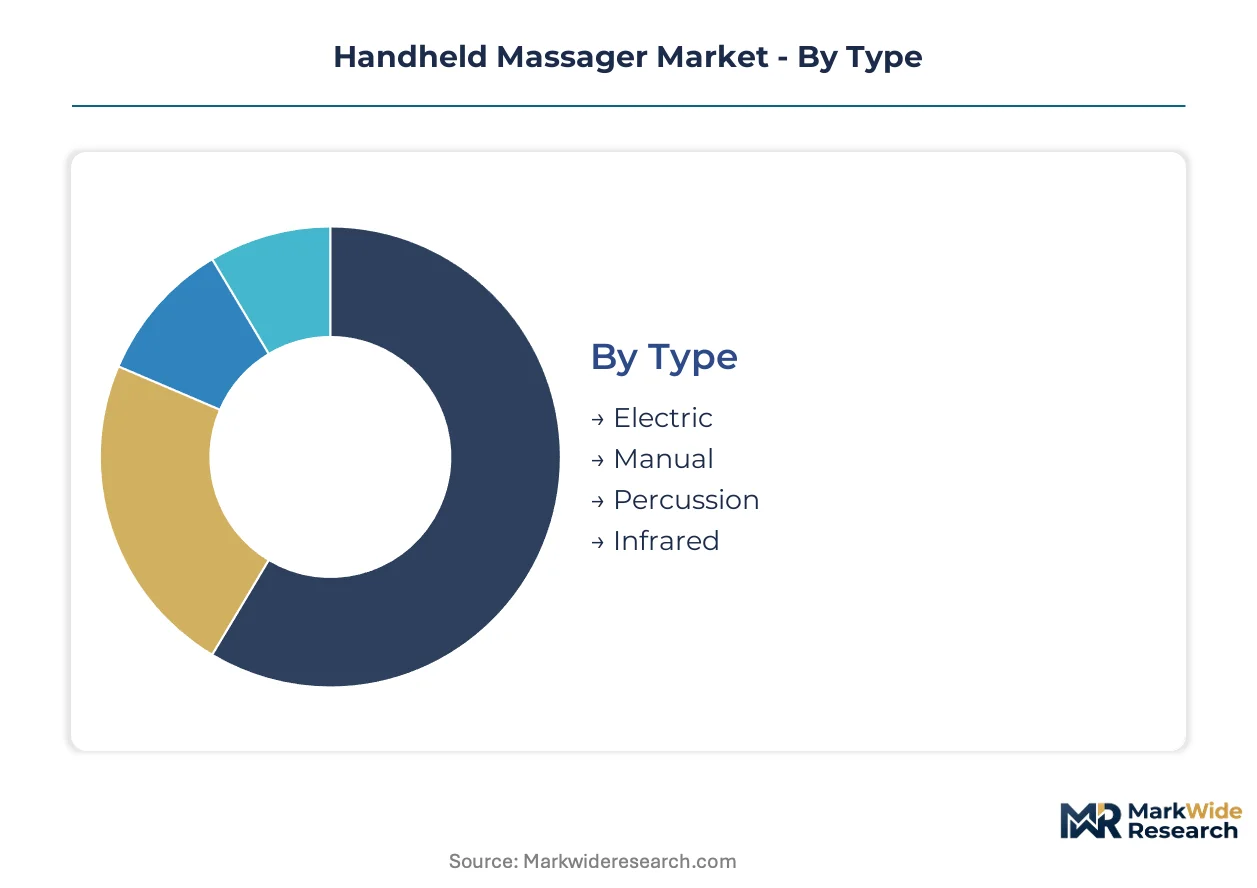
Handheld massager purchasing patterns fragment sharply across use-case intensity and mobility requirements. Manufacturers must align motor specifications and battery architectures to distinct user workflows rather than pursuing universal designs.
Type:
Domestic demand concentrates in electric and infrared variants, while percussion devices drive export volume to professional sports markets. Manual units retain strong regional production clusters serving price-sensitive local distribution.
- Electric:Corded and cordless electromechanical units deliver 20–60 Hz vibration frequencies through AC adapters or lithium-ion cells. Demand concentrates in United States suburban households seeking post-workout recovery convenience, constrained by FDA 510(k) clearance timelines for therapeutic claim positioning.
- Percussion:High-amplitude (10–16 mm stroke) devices generate rapid vertical impulses for deep tissue penetration. Export-led sales dominate to German physiotherapy practices and Japanese athletic training facilities, where EU MDR CE marking and PMDA compliance create premium pricing tiers.
- Manual:Spring-loaded or ball-bearing mechanical devices rely on user-applied pressure without electrical components. Wood and silicone construction dominates Southeast Asian domestic markets with minimal regulatory burden.
- Infrared:Thermal-emitting heads combine percussion or vibration with 600–1000 nm wavelength heat penetration. German wellness retail channels and South Korean beauty-device distributors drive order flow for heat-assisted circulation benefits.
Electric holds the largest share; momentum sits with percussion.
Intensity Level:
Cost tier differentiation separates professional-grade adjustable systems from fixed-output consumer units. High-intensity specifications command component premiums in motor torque and heat dissipation engineering.
- Adjustable:Variable-speed firmware enables 5–20 speed settings with real-time pressure feedback. Physical therapy chains in the Netherlands and Texas specify these for patient-specific dosage protocols.
- High:Fixed maximum-output motors deliver 60+ Hz for dense muscle groups. Competitive bodybuilding segments in California and Florida drive replacement cycles.
- Medium:Single-speed mid-range specifications target general wellness users without clinical requirements. Mass-market retail in France and Italy absorbs volume through pharmacy and hypermarket channels.
- Low:Gentle vibration for facial or sensitive tissue applications. Japanese cosmetic device regulations and South Korean K-beauty export standards shape compliance requirements.
Adjustable commands the highest unit economics; medium captures the widest distribution footprint.
Target User:
Application-specific ergonomics drive form factor divergence, with athletic use demanding durability and senior use prioritizing lightweight construction.
- Fitness Enthusiasts:CrossFit affiliates and boutique studio members expect 150+ minute cordless runtime with attachment modularity. California and Texas wellness markets show steepest expansion trajectory for subscription-based accessory replenishment.
- Athletes:Collegiate and professional sports medicine programs specify fleet-standardized units with unified motor-inverter platforms. German Olympic training centers and Australian Institute of Sport procurement drives bulk orders.
- Office Workers:Compact desk-side devices target cervical and lumbar tension from sedentary posture. Japanese corporate wellness programs and United Kingdom white-collar distribution channels absorb volume.
- Seniors:Lightweight (under 1 kg) units with simplified controls address arthritis and circulation management. Medicare Advantage pilot programs in Florida and Arizona test reimbursement eligibility.
Fitness enthusiasts generate the highest lifetime value; seniors represent the most underpenetrated addressable base.
Power Source:
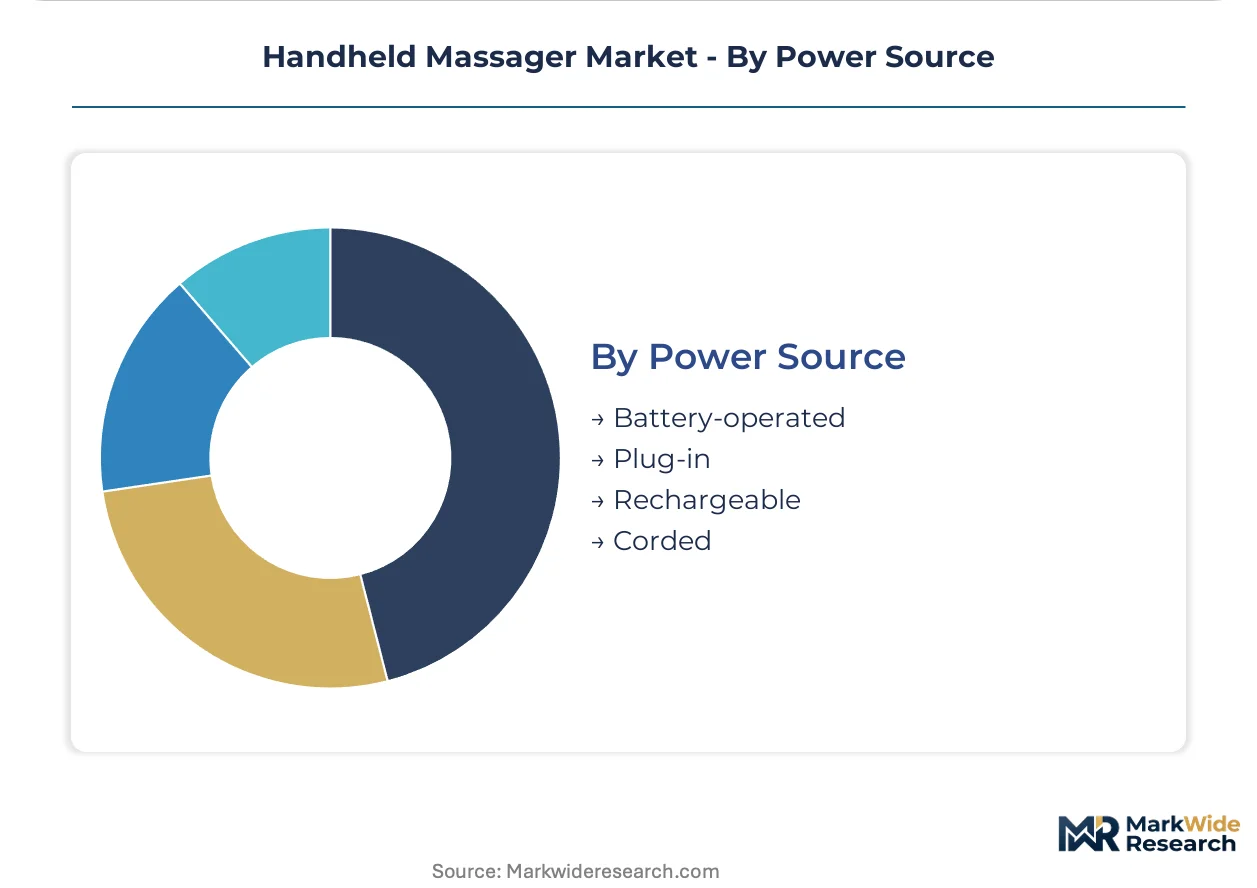
Volume leadership is rotating toward rechargeable lithium-ion as energy density improvements eliminate corded performance advantages.
- Rechargeable:Lithium-ion cells with 20% generational capacity gains enable professional-grade cordless runtime. South Korean and Japanese cell manufacturers supply Tier 1 brands with multi-year cathode agreements.
- Battery-operated:Disposable AA/AAA configurations persist in travel and emergency backup segments. IATA lithium transport restrictions disadvantage this category in cross-border e-commerce.
- Corded:AC-powered units retain price positioning in clinical settings requiring uninterrupted operation. German physiotherapy practices specify these for treatment room installations.
- Plug-in:Transformer-dependent designs with fixed voltage requirements dominate budget private-label production. Shenzhen PCB fabrication clusters supply this tier with 70%+ geographic concentration.
Rechargeable is gaining share fastest; corded defends position in institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands 40-60% premiums over Shenzhen-assembled units lacking CE marking, while California wellness markets absorb subscription-based accessory replenishment at lifetime value multiples exceeding mass-market retail.
United States
Fitness enthusiasts in California and Texas drive cordless runtime specifications above 150 minutes, with boutique studios embedding percussive therapy into membership protocols. FDA 510(k) clearance timelines stretch 12-18 months for therapeutic claims, filtering entrants without quality management systems. Direct-to-consumer brands cluster in Los Angeles and Austin, where specialty retail partnerships scale rapidly.
Germany
Physiotherapy practices specify fleet-standardized units with unified motor-inverter platforms, while statutory health insurance pilots device rental models for adjunct therapy reimbursement. EU MDR technical documentation requirements and 14-month notified body backlogs eliminate budget exporters from therapeutic channels. Industrial concentration centers on Munich and Stuttgart quality management consultancies serving CE-marking preparation.
Japan
Corporate wellness programs absorb compact desk-side devices for cervical tension management, with cosmetic device regulations shaping low-intensity facial unit specifications. PMDA compliance frameworks govern therapeutic positioning, creating premium tiers distinct from general wellness imports. Osaka-based athletic training facilities drive export demand for high-amplitude professional specifications.
South Korea
K-beauty distributors channel infrared-thermal devices through beauty-device retail networks, with MFDS standards governing heat-emitting product categories. Domestic cell manufacturers supply lithium-ion cathode materials to Tier 1 brands under multi-year agreements. Seoul metropolitan area concentrates R&D partnerships between device brands and battery engineering firms.
China
Shenzhen PCB fabrication clusters supply 70%+ of motor control boards, creating single-geography disruption exposure for assembly-heavy operators. GB standards and SAMR quality supervision shape domestic market access, while NMPA pathways remain underdeveloped for therapeutic massager categories. Pearl River Delta contract manufacturers dominate budget private-label production for export markets.
Handheld Massager Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with in-house motor engineering separating premium positioning from assembly-dependent budget tiers. The vendor base clusters around three strategic profiles: integrated R&D-platform firms with proprietary drive systems, mass-market retail anchors with North American distribution partnerships, and Shenzhen-based fabricators serving private-label export demand. Dominant competitive moves include vertical integration into battery cathode supply agreements and geographic expansion through EU MDR early-filing advantages.
Among the integrated R&D-platform specialists, Therabody and Hyperice exemplify technology-led positioning through proprietary percussive architectures, while HoMedics anchors mass-market retail presence through established North American pharmacy and hypermarket channels. These three firms occupy distinct competitive spaces—Therabody and Hyperice representing premium-tier engineering differentiation, HoMedics exemplifying volume-scale distribution leverage—without direct segment overlap.
| Leading Market Players |
|---|
| Breo |
| Naipo |
| Theragun |
| Therabody |
| Zyllion |
| Hyperice |
| RENPHO |
| Lifepro |
| HoMedics |
| Others |
Supply Flow & Price Mechanics
Lithium-ion cell chemistry substitution for nickel-cadmium and lead-acid alternatives is redrawing procurement geography toward South Korean and Japanese cathode suppliers while compressing price premiums for cordless runtime thresholds above 150 minutes. This chemistry transition simultaneously elevates working capital requirements for multi-year supply agreements and widens the spread between certified therapeutic-grade positioning and uncertified wellness imports.
Pricing Analysis
The configured-to-order premium spread separates CE-marked therapeutic devices from mass-market wellness units by 40-60 percentage points. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, EU MDR technical documentation depth, and cordless runtime specifications. Pricing pressure stems from cobalt and lithium carbonate spot volatility compressing gross margins for brands without captive cathode agreements. Budget private-label buyers exhibit acute price sensitivity, while German physiotherapy practices and Japanese athletic training facilities prioritize certification grade over unit cost.
Supply Chain Analysis
Inventory lead times for motor control boards extend 3-5 days beyond standard fulfillment due to IATA lithium battery transport restrictions requiring specialized hazmat packaging. Manufacturing concentration centers on China for PCB fabrication, South Korea for cathode materials, and Japan for precision motor components. Raw material dependencies include lithium carbonate, cobalt sulfate, and rare-earth permanent magnets. Single-geography vulnerability in Shenzhen-dominated electronics clusters threatens disruption exposure. Distribution runs through direct-to-consumer wellness brands, specialty retail partnerships, and physical therapy procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as post-workout recovery normalization splinters demand across fitness enthusiasts, clinical adjunct therapy, and senior circulation management niches. Each segment demands incompatible motor specifications and battery architectures, preventing universal design dominance.
For Market Incumbents: Compound certification advantages by accelerating EU MDR early filings ahead of 14-month German notified body backlogs. Deepen backward integration into battery cathode supply through multi-year agreements with South Korean cell manufacturers. Defend against Shenzhen-based private-label erosion by embedding subscription-based accessory replenishment into high-usage customer contracts. For New Entrants and Emerging Players: Differentiate on AI-guided pressure feedback integration with smartphone apps, bypassing patent thickets around fixed-amplitude mechanisms. Target the senior segment with sub-1 kg lightweight designs and simplified controls, the most underpenetrated addressable base. Pursue Medicare Advantage pilot program eligibility in Florida and Arizona as a reimbursement-driven go-to-market pathway. For Investors and Strategic Acquirers: The market sits at a technology consolidation phase that favors integrated R&D-platform firms with proprietary drive systems over assembly-dependent operators. Long-term viability across the projection horizon hinges on in-house motor and battery engineering capabilities. Acquisition focus should center on semiconductor firms with integrated gate driver expertise and brushless DC motor-inverter platforms. Monitor German statutory health insurance reimbursement code expansions as the critical inflection signal for clinical channel viability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Early Filing | 14-month German notified body queues eliminate late entrants from therapeutic premium tiers. |
| Battery Cathode Supply Agreement | Multi-year South Korean and Japanese cell contracts insulate margins from cobalt spot volatility. |
| AI-Guided Pressure Feedback Integration | Force sensor and smartphone app combinations differentiate premium tiers from fixed-speed alternatives. |
| Subscription Accessory Replenishment | California and Texas wellness markets demonstrate lifetime value multiples exceeding transactional retail. |
| Clinical Reimbursement Pathway Development | German and Dutch physical therapy rental models billable under statutory insurance codes expand addressable base. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with product managers at direct-to-consumer wellness brands, procurement leads at German physiotherapy chains, biomedical engineers at Japanese athletic training facilities, and category buyers at North American specialty retailers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, IATA lithium battery transport regulations, and customs trade records for motor control board imports. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Across the analysis window, forecasts model handheld massager demand by device type (electric, percussion, manual, infrared), intensity level specification, target user workflow, and power source architecture. CAGRs derive from segment-specific adoption curves weighted by regulatory clearance timelines and battery energy density improvement trajectories. Key inputs include lithium-ion cell capacity generational gains, EU MDR compliance cost pass-through elasticity, and boutique fitness chain percussive therapy protocol standardization rates.
The analysis sits within stated boundaries; outcomes outside FDA 510(k) clearance timeline stability, EU MDR notified body capacity expansion, or IATA lithium transport rule moderation would require recalibration. Forecasts reflect documented assumptions regarding cathode material supply continuity and motor control firmware talent availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Toothpaste Tablet Market
Personal Grooming Products
Insect Repellent Wipes Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
Electric Hair Brush Market
Personal Grooming Products
Foot Care Products Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Disposable Slippers Market
Personal Grooming Products
Lice Combs Market
Personal Grooming Products
Global Posture Corrector Market
Personal Grooming Products
Disposable Razor Market
Personal Grooming Products
Electric Hair Clipper and Trimmer Market
Personal Grooming Products
Electric Massagers Market
Personal Grooming Products
Shoe Care Market
Personal Grooming Products
Global Tampons Market
Personal Grooming Products
AI Toothbrush Market
Personal Grooming Products
Sexual Lubricant Market