
 Insect Repellent Wipes Market | 2026-2036
Insect Repellent Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Insect Repellent Wipes Market Insights
The capital-intensity divergence between large-format manufacturers and boutique natural-formulation brands is unwinding competitive stability in insect repellent wipes. SC Johnson leverages its integrated supply chain and household brand equity to sustain shelf dominance across mass retail channels. Aunt Fannie's specializes in plant-derived active ingredients, competing on ingredient transparency rather than unit economics. Quantum Health anchors its position through health-food store distribution, navigating narrower margins with premium positioning.
Insect repellent wipes are pre-moistened nonwoven substrates impregnated with EPA-registered active ingredients such as DEET, picaridin, or oil of lemon eucalyptus, designed for topical application to repel mosquitoes, ticks, and biting flies during outdoor exposure. The substrate typically employs spunlace or airlaid cellulose-polyester blends to achieve adequate liquid retention without residue transfer to skin or gear. Natural product formulations now lead growth velocity as consumer preference shifts away from synthetic actives, though synthetic segments still occupy the largest margin pool due to lower raw material volatility. Online retail channels represent the fastest-expanding distribution vector, particularly for subscription-based family packs targeting recurring outdoor use occasions.
The EPA oversees active ingredient registration and label claims under FIFRA, while the FDA governs cosmetic-insect repellent hybrid products through overlapping jurisdiction that complicates compliance pathways. State-level restrictions on disposable wipe materials, notably California's single-use plastics directives, are forcing substrate reformulation toward biodegradable cellulose alternatives. Stakeholders must monitor evolving state packaging mandates and active ingredient tolerance thresholds to preserve market access across fragmented regulatory terrain.
Market Dynamics
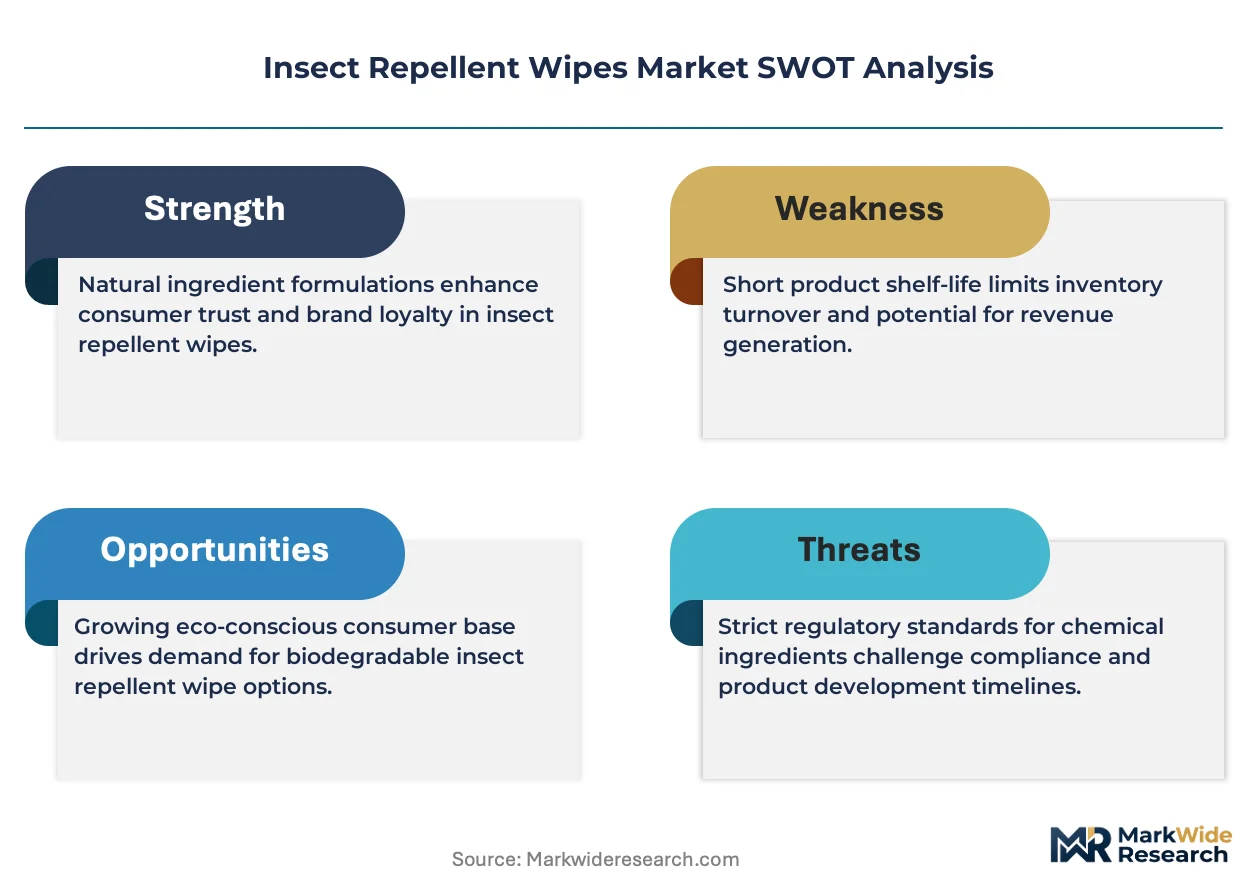
EPA registration requirements for active ingredients are compressing formulation timelines while elevating compliance costs, forcing manufacturers to consolidate testing infrastructure or exit synthetic-active segments entirely.
Growth Catalysts
- Outdoor recreation participation:Camping and adventure travel participation surges across the United States, creating recurring purchase occasions for portable repellent formats. State park visitation records drive seasonal demand spikes.
- Biodegradable substrate mandates:California's single-use plastics directives accelerate cellulose-alternative adoption, positioning early reformulators for premium shelf placement in regulated markets.
- DEET tolerance thresholds:The EPA's evolving safety benchmarks for synthetic actives push R&D investment toward picaridin and oil of lemon eucalyptus, diversifying active ingredient portfolios.
Market Restraints
- Cellulose supply concentration:Airlaid nonwoven substrate production clusters in Southeast Asian manufacturing hubs, exposing wipe producers to freight volatility and tariff exposure.
- FIFRA-FDA jurisdictional overlap:Cosmetic-repellent hybrid products face dual compliance pathways that extend time-to-market by 8-14 months versus single-jurisdiction formulations.
- Essential oil price volatility:Natural active ingredient costs fluctuate with agricultural yields in Madagascar and Indonesia, compressing margins for plant-derived formulation specialists.
Strategic Opportunities
- Subscription commerce penetration:Direct-to-consumer family pack subscriptions bypass mass retail slotting fees, capturing lifetime value from recurring outdoor households.
- Health-food channel expansion:Natural product retailers represent underpenetrated distribution for DEET-free formulations, commanding price premiums through ingredient transparency positioning.
- EU Green Deal alignment:REACH-registered biodegradable substrates qualify for preferential procurement in European outdoor retail chains, opening transatlantic export pathways.
Industry Challenges
- Toxicology specialist scarcity:EPA-compliant efficacy testing requires credentialed entomologists and dermatologists, creating recruitment bottlenecks in regional testing laboratories.
- Label claim substantiation timelines:FIFRA-mandated field trials for duration-of-protection claims extend product development cycles beyond typical consumer goods benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insect Repellent Wipes Market |
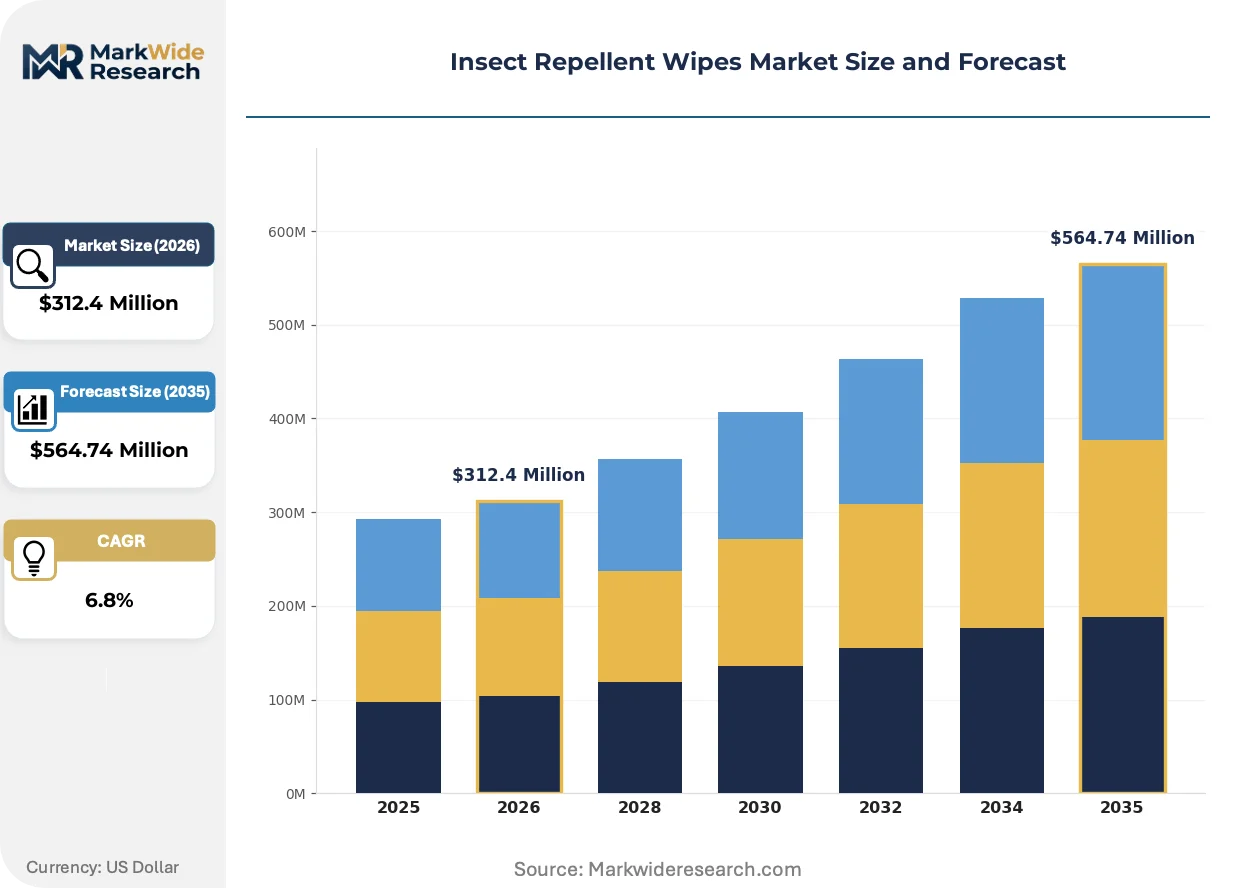
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Biochemical, Herbal Application: Outdoor Activities, Camping, Travel, Home Use Customer Type: Individuals, Families, Outdoor Enthusiasts, Travelers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | SC Johnson, Cutter, Repel, Quantum Health, La Fresh, CoreTex, STEM, Aunt Fannie's, Burt's Bees, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insect Repellent Wipes Market Trends and Innovations
Formulation chemistry and substrate engineering are converging to redefine product performance standards while regulatory fragmentation accelerates regional specialization in compliance capabilities.
Microencapsulation technology for timed-release active delivery is miniaturizing protection duration gaps between single-application wipes and repeated spray reapplication. Backpacking and thru-hiking segments adopt these formats fastest, compressing the addressable market for conventional pump sprays in weight-sensitive use cases.
REACH restrictions on persistent organic pollutants are forcing European manufacturers to abandon legacy DEET concentrations above 30%, redirecting R&D toward icaridin and PMD refinement. German and French outdoor retailers now require full substance disclosure, shifting competitive advantage toward supply chain transparency rather than efficacy claims alone.
Consumer preference for ingredient provenance is fragmenting mass-market purchasing into mission-driven segments that prioritize USDA BioPreferred certification or Leaping Bunny cruelty-free status. This certification-driven preference shift concentrates in coastal United States metropolitan markets, where health-food store penetration exceeds national averages by 3-4x.
Insect Repellent Wipes Market Segmentation
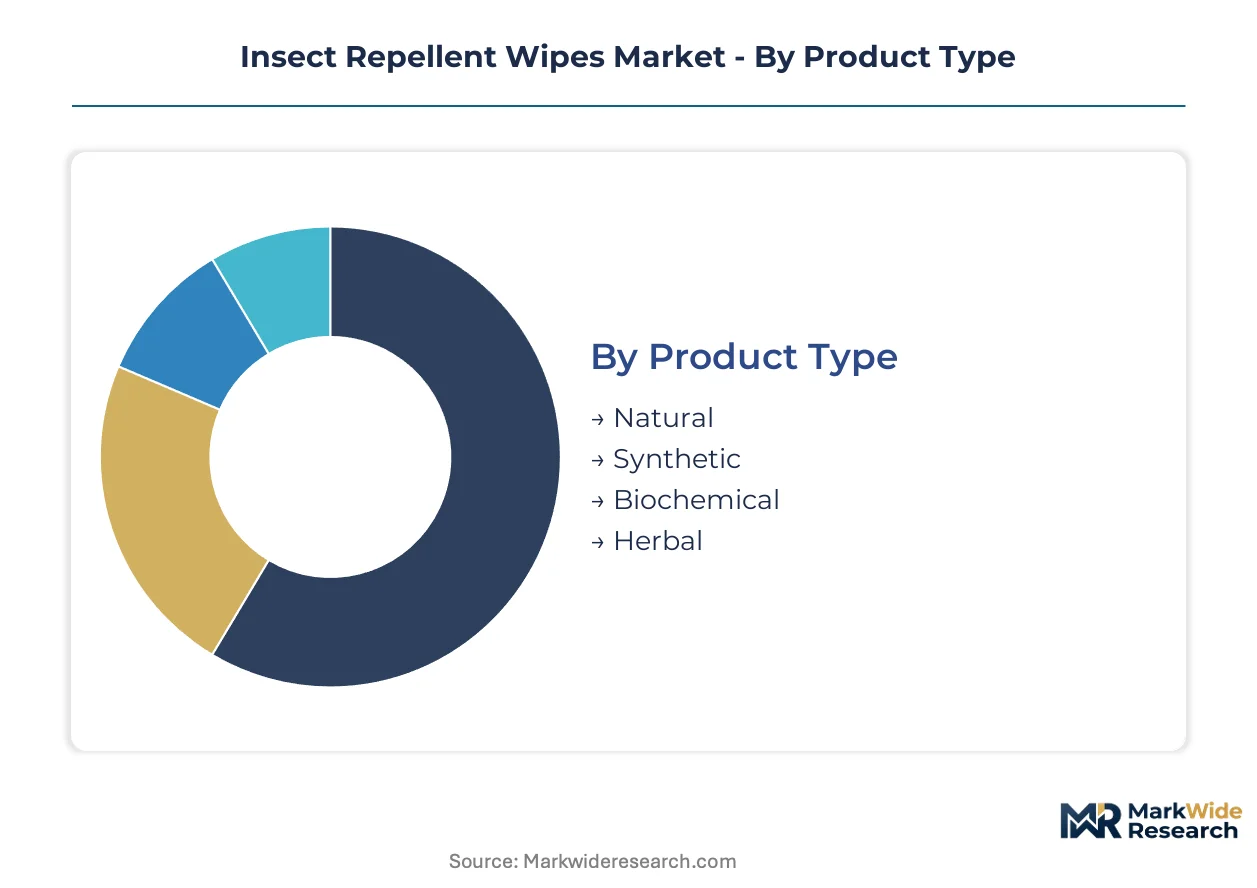
Insect repellent wipes segment along formulation chemistry, use occasion, buyer identity, and purchase location. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer portfolio strategy.
Product Type:
Natural formulations command premium shelf placement through health-food retail channels, while synthetic variants dominate mass-market volume. The channel mix bifurcates sharply between certified organic positioning and convenience-store accessibility.
- Natural:Plant-derived actives such as oil of lemon eucalyptus and citronella oil impregnate biodegradable cellulose substrates. Demand concentrates in California and Pacific Northwest metropolitan markets where single-use plastics restrictions and ingredient transparency preferences overlap.
- Synthetic:DEET and picaridin formulations deliver extended protection duration through controlled-release chemistry. Backpacking and military procurement channels absorb the majority of volume, prioritizing efficacy over substrate biodegradability.
- Biochemical:Biopesticide actives derived from bacterial fermentation occupy narrow regulatory niche between natural and synthetic classifications. EPA registration pathways remain less standardized, limiting retail distribution.
- Herbal:Essential oil blends without standardized active concentration claim aromatherapeutic positioning rather than EPA-registered repellency. Direct-to-consumer subscription channels capture most volume, sidestepping FIFRA label requirements.
Synthetic dominates installed base. Natural is where expansion concentrates.
Application:
Cost tier stratification separates commodity home-use formats from performance-optimized outdoor variants. Higher price points correlate with substrate durability requirements and active ingredient concentration.
- Outdoor Activities:Hiking, fishing, and hunting applications demand sweat-resistant substrates with 8+ hour protection claims. State park concession partnerships and outdoor retailer co-branding drive placement in Colorado, Utah, and Montana trailhead markets.
- Camping:Family pack configurations with child-safe actives target recurring seasonal purchase. KOA campground retail partnerships and REI private label programs concentrate volume in the Mountain West and Northeast corridor.
- Travel:TSA-compliant single-wipe sachets address airline carry-on restrictions and hotel amenity procurement. International departure lounge retail and boutique hotel supply chains absorb premium-priced formats.
- Home Use:Patio and backyard applications favor larger format canisters with standard DEET concentrations. Mass retail seasonal displays and hardware store garden centers move volume on price-promotion cycles.
Home Use dominates installed base. Outdoor Activities is climbing the fastest.
Customer Type:
Volume concentration varies by household composition and purchase frequency, with family units generating recurring revenue through subscription models.
- Individuals:Solo outdoor recreationists and business travelers purchase on immediate need with minimal brand loyalty. Convenience store and airport retail capture this segment through impulse placement.
- Families:Multi-person households with children drive bulk pack adoption and subscription commerce. Pediatrician recommendation and school district procurement guidelines influence brand selection in suburban markets.
- Outdoor Enthusiasts:Dedicated camping and hiking practitioners maintain baseline inventory and replace on seasonal cycle. Specialty retailer expertise and online community endorsement shape purchase decisions.
- Travelers:International and adventure travel participants prioritize compact format and broad-spectrum protection. Travel clinic recommendations and destination-specific disease risk awareness trigger purchase.
Families dominate installed base. Outdoor Enthusiasts is gaining share fastest.
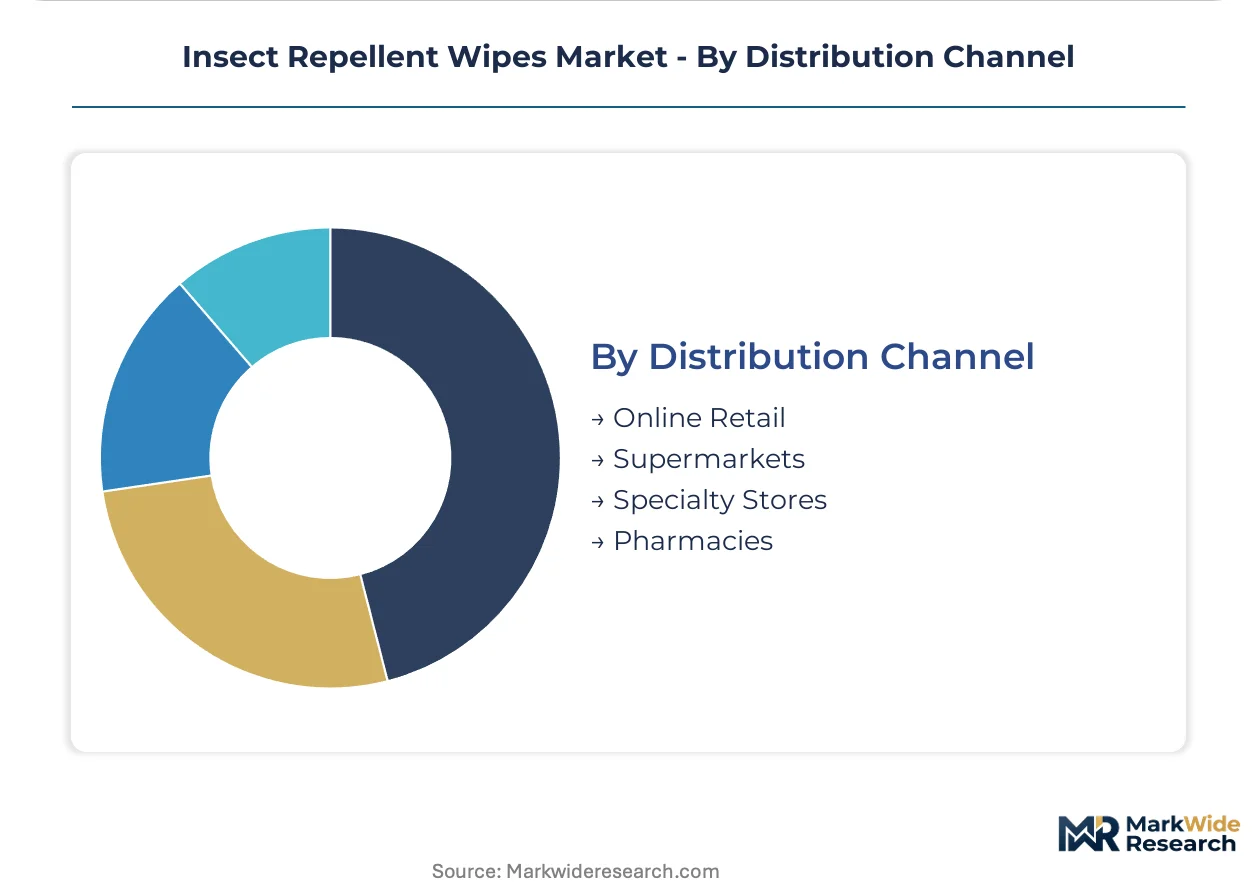
Distribution Channel:
Supply concentration in Southeast Asian substrate manufacturing creates freight cost differentials that favor online retail's inventory centralization over dispersed brick-and-mortar distribution.
- Online Retail:Direct-to-consumer platforms and marketplace sellers bypass slotting fees while capturing subscription revenue. Amazon and specialty outdoor e-commerce sites aggregate demand from fragmented geographic markets.
- Supermarkets:Mass merchandisers and grocery chains rely on seasonal end-cap displays and promotional pricing. Walmart and Target distribution networks concentrate volume in suburban and exurban trade areas.
- Specialty Stores:Outdoor equipment retailers and natural product outlets command price premiums through staff expertise and curated assortment. REI and Whole Foods Market represent anchor tenants with divergent formulation preferences.
- Pharmacies:Drug store chains emphasize travel health and pediatric safety positioning through pharmacist consultation. CVS and Walgreens seasonal programs align with vacation travel peaks and back-to-school periods.
Supermarkets dominate installed base. Online Retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland absorb premium pricing for biodegradable substrates without volume elasticity, while Indian and Brazilian consumers trade down to lower-concentration formats when essential oil costs spike.
United States
State park visitation in Colorado and Utah drives seasonal demand spikes for sweat-resistant outdoor formulations. The EPA's FIFRA registration requirements compress product development timelines while elevating compliance costs for synthetic-active manufacturers. California's single-use plastics directives force substrate reformulation toward cellulose alternatives in Los Angeles and San Francisco retail corridors.
Germany
REACH restrictions on DEET concentrations above 30% redirect R&D investment toward icaridin and PMD refinement in German outdoor retail. The EU Green Deal's biodegradable procurement standards position REACH-registered substrates for preferential shelf placement. Munich and Frankfurt anchor distribution networks for transalpine hiking and cycling segments.
China
Domestic camping participation surges in Sichuan and Yunnan provinces, creating recurring purchase occasions for portable repellent formats. The Ministry of Ecology and Environment's dual carbon goals accelerate scrutiny of synthetic active ingredient manufacturing. Guangzhou and Shenzhen manufacturing clusters dominate airlaid nonwoven substrate production for regional wipe converters.
Brazil
Amazon basin ecotourism and urban dengue awareness drive demand for DEET-free natural formulations in São Paulo and Rio de Janeiro. ANVISA's cosmetic-repellent hybrid oversight creates compliance complexity for imported products with overlapping functional claims. Southeast Asian cellulose supply exposure compresses margins for Brazilian converters during freight volatility cycles.
Australia
Ross River virus and Japanese encephalitis awareness in Queensland and New South Wales sustains year-round repellent purchase behavior. The Therapeutic Goods Administration's parallel jurisdiction with state environmental agencies fragments compliance pathways for biodegradable substrate claims. Melbourne and Sydney specialty outdoor retailers command price premiums through staff expertise and curated natural-assortment positioning.
Insect Repellent Wipes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with household chemical conglomerates leveraging supply chain scale against boutique formulators competing on ingredient transparency. The market structure rewards backward integration into substrate sourcing and EPA-compliant testing infrastructure. Three archetypes dominate: mass-market brand licensors, natural-formulation specialists, and private-label converters for outdoor retail channels. Capacity consolidation and geographic licensing agreements represent the primary competitive moves, as regulatory fragmentation raises barriers for new entrants lacking established compliance capabilities.
Among mass-market household chemical manufacturers, SC Johnson anchors the integrated leader tier through shelf dominance across Walmart and Target networks. Aunt Fannie's exemplifies the natural-formulation specialist archetype, competing on plant-derived active transparency rather than unit economics. Quantum Health occupies the health-food channel specialist position, navigating narrower margins through premium positioning in Whole Foods Market and REI distribution.
| Leading Market Players |
|---|
| SC Johnson |
| Cutter |
| Repel |
| Quantum Health |
| La Fresh |
| CoreTex |
| STEM |
| Aunt Fannie's |
| Burt's Bees |
| Others |
Pricing and Supply Chain Analysis
Cellulose-alternative substrate adoption in California and European markets simultaneously relocates manufacturing toward Southeast Asian airlaid hubs and compresses margin structures for converters unable to absorb reformulation costs. This substitution dynamic concentrates pricing power with integrated substrate producers while fragmenting downstream competition between premium biodegradable positioning and commodity synthetic formats.
Pricing Analysis
Subscription-based family pack renewals drive lifetime value capture from recurring outdoor households, with three-tier pricing structure across premium, standard, and economy levels separating certified organic formulations from mass-market DEET variants. Price differentiation hinges on EPA registration tier and biodegradable substrate certification, with natural-formulation specialists commanding shelf premiums through Whole Foods Market and REI placement. Cost compression in standard synthetic tiers is intensifying because of essential oil price volatility and freight exposure from Indonesian cellulose sourcing. Families with children exhibit lowest price sensitivity due to pediatric safety prioritization, while individual convenience purchasers show highest elasticity.
Supply Chain Analysis
Strait of Malacca transit exposure underwrites Southeast Asian airlaid nonwoven substrate flows to North American and European converters, with production gravity centering on Guangzhou, Shenzhen, and Jakarta manufacturing clusters. Raw material dependencies span Indonesian cellulose pulp, Malaysian polyester fiber, and Madagascar-sourced citronella oil for natural actives. Single-source vulnerability concentrates in Southeast Asian substrate production, where tariff exposure and freight volatility compress converter margins during logistics disruption cycles. Distribution runs through centralized Amazon fulfillment and REI private-label programs, bypassing mass retail slotting fees for direct-to-consumer penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics dynamics are reshaping competitive positioning as subscription commerce infrastructure and EPA registration databases create interoperability layers between formulation specialists and recurring-purchase households. The ecosystem shift toward direct-to-consumer family pack models concentrates customer data ownership with early platform adopters.
For Market Incumbents: Shield shelf position in Walmart and Target networks by deepening backward integration into airlaid substrate sourcing and captive EPA testing infrastructure. Natural-formulation specialists threaten mass-market volume through health-food channel expansion; counter by accelerating biodegradable substrate certification investment to neutralize premium positioning advantages.
For New Entrants and Emerging Players: Anchor in underpenetrated health-food retail corridors in coastal United States metropolitan markets, where USDA BioPreferred certification concentration exceeds national averages. The most penetrable white-space target sits in TSA-compliant travel sachet formats for boutique hotel supply chains; pursue go-to-market alignment with travel clinic recommendation networks and international departure lounge retail operators.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed natural-formulation specialists holding captive supply agreements for Madagascar citronella and Indonesian cellulose. Five-to-ten-year viability favors converters with REACH-registered substrate portfolios and established FIFRA compliance capabilities. Monitor California single-use plastics directive expansion as inflection indicator for biodegradable format acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Certification | REACH registration unlocks preferential procurement in REI and European outdoor retail chains. |
| Subscription Commerce Infrastructure | Direct-to-consumer family pack models bypass Walmart slotting fees and capture recurring revenue. |
| EPA Testing Infrastructure Investment | Captive entomology and dermatology capabilities compress FIFRA compliance timelines for synthetic actives. |
| Health-Food Channel Expansion | Whole Foods Market placement commands price premiums through ingredient transparency positioning. |
| Travel Format Development | TSA-compliant sachet configurations address airline carry-on restrictions and hotel amenity procurement. |
Research Methodology
A standing panel of EPA regulatory consultants, health-food retail category managers, outdoor equipment procurement directors, and airlaid substrate plant engineers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against EPA FIFRA registration databases, customs trade records for cellulose pulp imports, and Nielsen retail audit data for mass-market wipe categories. Bottom-up volume modeling across formulation chemistry tiers triangulated against top-down market sizing from outdoor participation surveys and state park visitation records.
Consistency checks validated volume and value outputs against external benchmarks including camping equipment sales correlations and seasonal insect-borne disease incidence patterns. The analytical framework modeled segmentation dimensions spanning formulation chemistry, use occasion intensity, buyer household composition, and distribution channel format across the projection horizon. CAGRs were derived from regression analysis of historical outdoor participation trends and regulatory compliance cost trajectories, with inputs from essential oil price indices and Southeast Asian freight rate volatility.
Underlying assumptions cover sustained outdoor recreation participation growth, stable EPA registration fee structures, and gradual California plastics directive expansion, with deviation risk concentrated in essential oil agricultural yield shocks and tariff regime shifts. Practitioners should keep alternative scenarios live as biodegradable substrate cost curves and FIFRA-FDA jurisdictional clarity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Foot Care Products Market
Personal Grooming Products
Shaving Market
Personal Grooming Products
Infant Mosquito Repellent Market
Personal Grooming Products
Global Canes and Walking Sticks Market
Personal Grooming Products
Global Away-From-Home Tissue and Hygiene Market
Personal Grooming Products
North America Mosquito Repellent Market
Personal Grooming Products
Disposable Razor Market
Personal Grooming Products
Global Consumer Use IPL Hair Removal Devices Market
Personal Grooming Products
Cotton Buds Market
Personal Grooming Products
Nose & Ear Hair Trimmers Market
Personal Grooming Products
Personal Lubricants Market
Personal Grooming Products
Global Massage Guns Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Razor Market
Personal Grooming Products
Toothpaste Tablet Market
Personal Grooming Products
Electric Tooth Polisher Market