
 Smart Body Scales Market | 2026-2036
Smart Body Scales Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Body Scales Market Insights
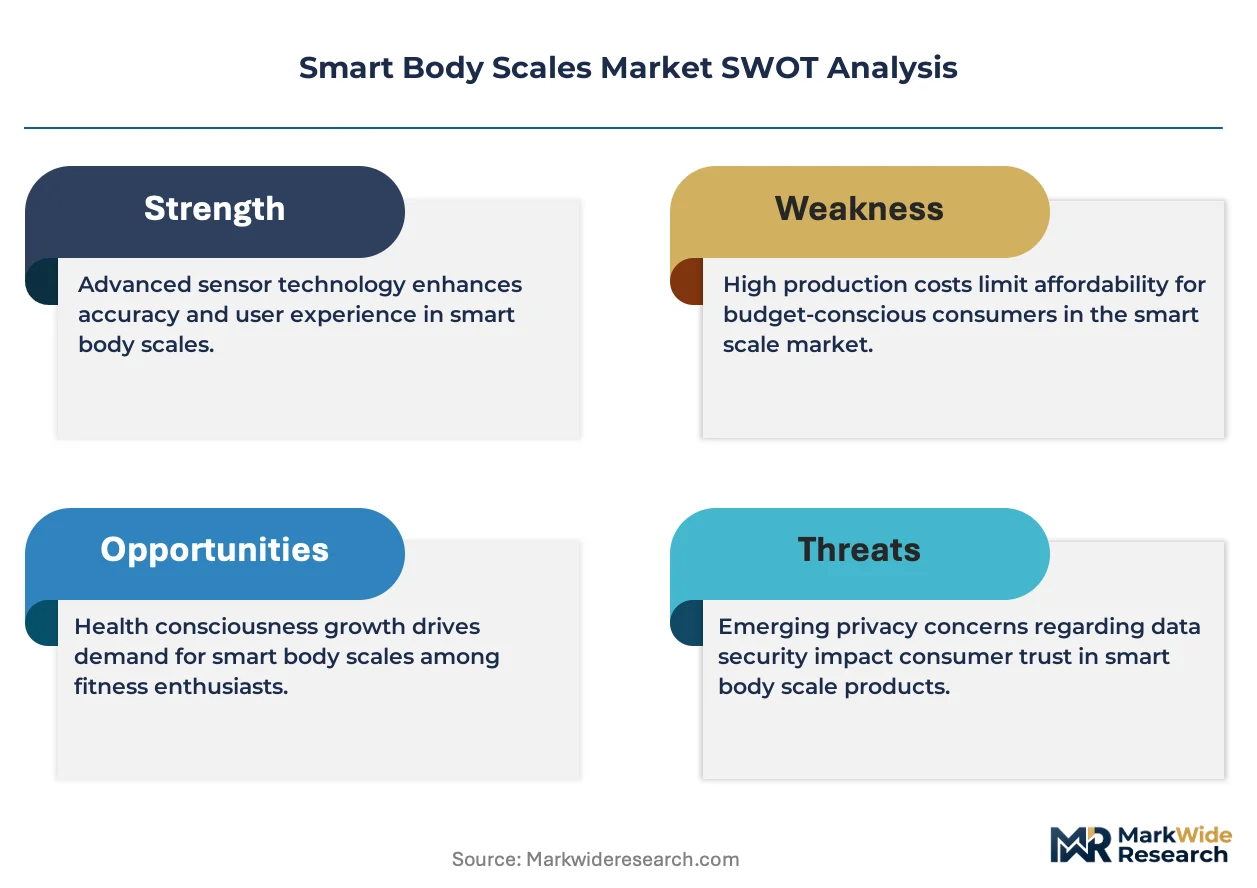
Buyer concentration across the smart body scales landscape is rebalancing from fragmented direct-to-consumer channels toward consolidated enterprise wellness procurement by gyms and healthcare providers. Withings leverages its European design heritage and clinical-grade sensor arrays to command premium positioning in institutional accounts. Renpho sustains aggressive pricing and Amazon-native distribution to dominate mass-market home use segments. Garmin anchors its wearable ecosystem strategy by extending proprietary Connect IQ compatibility into body composition hardware, creating defensible cross-device loyalty.
Smart body scales are electronic weighing instruments incorporating bioelectrical impedance analysis sensors, load cells with precision to 0.1 kilogram, and wireless chipsets for automated data transmission to mobile applications and cloud platforms. Their primary commercial purpose centers on longitudinal body composition tracking for consumer fitness, clinical monitoring, and insurance risk assessment workflows. Bluetooth-enabled scales currently occupy the highest volume tier due to minimal power requirements and universal smartphone pairing, while Wi-Fi-enabled models capture margin pools among users demanding autonomous cloud syncing without phone proximity. Healthcare providers represent the fastest-growing end user channel as reimbursement frameworks gradually incorporate remote patient monitoring metrics.
FCC certification governs radio frequency emissions for all connected scales sold in the United States, while CE marking under EU Radio Equipment Directive and REACH chemical compliance shape European market access requirements. Japan's METI enforces PSE electrical safety standards that constrain import timelines for unapproved devices. Stakeholders must monitor evolving FDA guidance on software-as-medical-device classifications for algorithms generating diagnostic insights from impedance data, as regulatory reclassification would fundamentally alter compliance costs and channel eligibility.
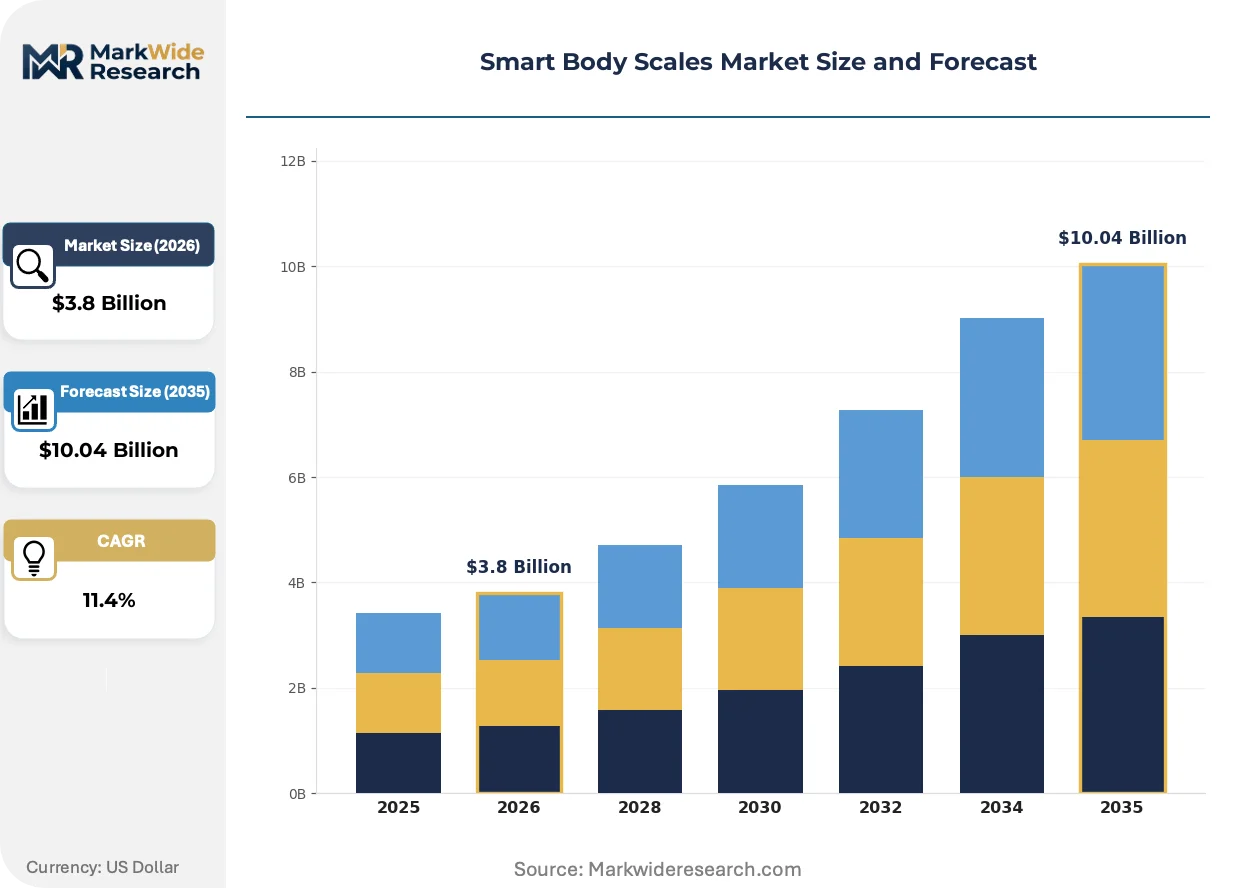
Market Dynamics
Bluetooth and Wi-Fi connectivity standards from the FCC and CE marking frameworks are reshaping product certification requirements, forcing manufacturers to redesign hardware architectures around regional radio frequency compliance before market entry.
Growth Catalysts
- Home fitness enthusiasts:Residential consumers are prioritizing integrated health data ecosystems that synchronize body composition metrics with nutrition and workout applications.
- REACH chemical compliance:European regulatory clarity on bioelectrical impedance sensor materials is accelerating product standardization across manufacturing bases.
- Remote patient monitoring:Healthcare providers are incorporating longitudinal body composition tracking into reimbursement frameworks for chronic disease management.
Market Restraints
- Load cell precision components:Supply concentration in precision sensor manufacturing creates input cost volatility and single-source dependency risks.
- Japan METI PSE standards:Electrical safety certification timelines extend import lead times for unapproved devices entering Japanese distribution channels.
- Smartphone-dependent pairing:Bluetooth-enabled models require proximity activation, limiting autonomous data capture for elderly or non-smartphone user segments.
Strategic Opportunities
- Germany's corporate wellness procurement:Enterprise buyers are consolidating vendor relationships for institutional body composition monitoring programs.
- Cloud-native Wi-Fi architectures:Autonomous data syncing without phone proximity is electrifying premium segment demand among affluent health-conscious households.
- ISO 13485 quality systems:Medical device-grade manufacturing standards are opening clinical channel eligibility for certified scale manufacturers.
Industry Challenges
- FDA software-as-medical-device reclassification:Algorithm-generated diagnostic insights from impedance data face evolving regulatory scrutiny that would alter compliance costs.
- Cross-platform API fragmentation:Health data interoperability standards vary across Apple HealthKit, Google Fit, and proprietary fitness ecosystems, complicating integration roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Body Scales Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Scales, Analog Scales, Bluetooth-enabled Scales, Wi-Fi-enabled Scales End User: Home Use, Gyms, Health Clubs, Healthcare Providers Technology: Wi-Fi Technology, Bluetooth Technology, NFC Technology, IoT Integration Application: Weight Monitoring, Body Composition Analysis, Fitness Tracking, Health Management |
| Companies Covered | Withings, Renpho, InBody, Garmin, Omron Healthcare, Anker (Eufy), Tanita, HoMedics, Arboleaf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Body Scales Market Trends and Innovations
Multi-frequency bioelectrical impedance analysis is electrifying competitive differentiation as manufacturers race to deliver clinical-grade accuracy in consumer-priced hardware.
Multi-frequency bioelectrical impedance analysis is electrifying the premium tier by enabling segmental body composition measurement rather than whole-body estimates. Hospital outpatient clinics and high-end gym chains are adopting these units at triple the pace of standard single-frequency models. This capability compression is forcing mid-tier manufacturers to license third-party sensor algorithms or exit the clinical-adjacent segment entirely.
EU MDR classification guidance for connected health devices is tightening post-market surveillance requirements for scales generating diagnostic indicators. Manufacturers must now maintain clinical evidence portfolios and periodic safety reporting that consumer electronics firms rarely possess. German and French notified bodies are processing certification backlogs extending eighteen months, advantaging incumbent medical device specialists over technology entrants.
Employer-sponsored wellness programs are consolidating vendor selection around platforms offering aggregated population health dashboards. Benefits administrators now require API-accessible body composition data feeds rather than standalone consumer applications. This purchasing pattern shift is most visible in United States Fortune 500 self-insured plans, where procurement teams favor enterprise-grade data governance over retail brand recognition.
Smart Body Scales Market Segmentation
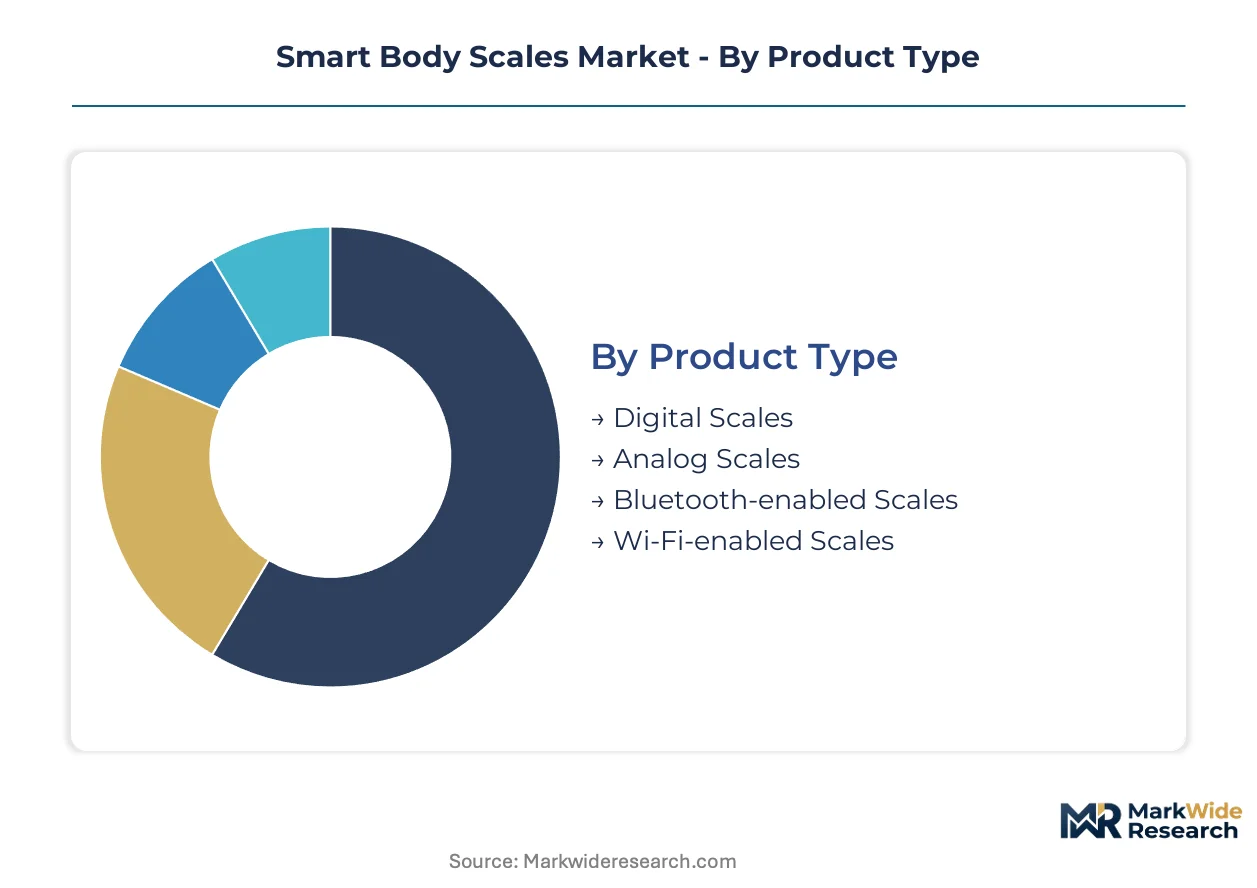
Segmentation in smart body scales reveals divergent capital requirements and margin structures across hardware architectures. Manufacturers must align R&D intensity with channel-specific certification burdens and connectivity standards.
Product Type:
Bluetooth-enabled Scales demand the heaviest upfront investment in FCC and CE radio certification, while Wi-Fi-enabled variants require cloud infrastructure and ongoing security compliance.
- Digital Scales:Load cell arrays with 0.1 kg precision and LCD displays constitute the baseline hardware configuration. Demand concentrates in Germany's mass retail channels where price sensitivity dominates household purchasing decisions.
- Analog Scales:Spring-mechanical platforms without electronic components occupy the entry price tier. These units see residual demand in China's rural distribution networks where battery replacement logistics deter digital adoption.
- Bluetooth-enabled Scales:Low-energy wireless chipsets paired with smartphone applications enable automated data logging. FCC certification timelines and radio frequency testing create capital barriers for new entrants targeting United States retail placement.
- Wi-Fi-enabled Scales:Autonomous cloud synchronization demands embedded TCP/IP stacks and recurring server infrastructure. Affluent households in the United States pay premiums for phone-independent data capture.
Most installed capacity flows through Bluetooth-enabled Scales. Expansion is steepest in Wi-Fi-enabled Scales.
End User:
Healthcare Providers extract the highest per-unit value through reimbursement-eligible remote monitoring, while Home Use channels optimize for manufacturing scale.
- Home Use:Residential consumers prioritize smartphone ecosystem compatibility and aesthetic industrial design. China's e-commerce platforms move the highest unit volumes through aggressive promotional pricing cycles.
- Gyms:Commercial durability specifications including reinforced platforms and anti-slip surfaces differentiate institutional-grade hardware. United States boutique fitness chains specify API-integrated body composition dashboards for member retention.
- Health Clubs:High-traffic environments demand calibration stability under continuous daily use. German corporate wellness procurement favors ISO 13485-certified manufacturers for population health programs.
- Healthcare Providers:Clinical-grade bioelectrical impedance analysis with segmental measurement capabilities supports chronic disease management workflows. Reimbursement frameworks in the United States are expanding coverage for remote patient monitoring data streams.
Volume concentrates in Home Use. Value capture is climbing fastest in Healthcare Providers.
Technology:
IoT Integration requires the deepest software engineering investment across firmware, cloud architecture, and third-party API maintenance.
- Wi-Fi Technology:802.11 b/g/n chipsets enable autonomous data transmission without intermediary devices. Germany's residential broadband penetration supports premium positioning for always-connected hardware.
- Bluetooth Technology:BLE 5.0 protocols minimize power consumption for battery-operated scales. Universal smartphone compatibility makes this the default specification for China's export manufacturing base.
- NFC Technology:Near-field pairing eliminates manual device discovery steps. Japan's METI PSE certification requirements extend lead times for radio-enabled hardware imports.
- IoT Integration:Embedded MQTT protocols and cloud-native architectures enable real-time health data pipelines. United States hospital systems specify these capabilities for enterprise wellness platform integration.
Bluetooth Technology carries the largest installed base. IoT Integration is gaining share fastest among institutional purchasers.
Application:
Body Composition Analysis commands the highest sensor precision and algorithm development investment, while Weight Monitoring minimizes bill-of-materials complexity.
- Weight Monitoring:Single-metric load cell measurement without impedance analysis occupies the entry hardware tier. China's domestic market sustains volume through price-competitive basic functionality.
- Body Composition Analysis:Multi-frequency bioelectrical impedance sensors estimate fat mass, muscle mass, and hydration status. United States healthcare providers are adopting these units for metabolic syndrome screening programs.
- Fitness Tracking:Longitudinal trend visualization and goal-setting features target athletic consumer segments. German gym chains bundle these capabilities into premium membership tiers.
- Health Management:Integration with chronic condition monitoring platforms and caregiver alert systems. Japan's aging population drives demand for elderly-accessible interfaces and automated clinical data sharing.
Weight Monitoring dominates unit shipments. Body Composition Analysis is expanding most quickly in clinical-adjacent channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer health data specialists concentrate in Germany's industrial clusters. Firmware engineers and sensor calibration technicians anchor development centers in Shenzhen and Silicon Valley. Clinical validation researchers populate Boston's medical technology corridor.
United States
Fortune 500 self-insured employers and hospital outpatient clinics drive enterprise procurement of connected body composition hardware. FDA software-as-medical-device guidance shapes algorithm compliance costs for diagnostic-featured scales. Greater Boston hosts clinical validation partnerships between sensor manufacturers and academic medical centers.
Germany
Corporate wellness program administrators and ISO 13485-certified manufacturers dominate institutional channel demand. EU MDR classification requirements and REACH chemical compliance govern bioelectrical impedance sensor materials. Baden-Württemberg's precision engineering cluster supplies load cell components to regional scale assemblers.
China
E-commerce platform operators and export manufacturing contractors sustain the highest global unit volumes. MIIT radio transmission standards and GB certification protocols regulate domestic connectivity specifications. Shenzhen's electronics manufacturing services corridor integrates BLE chipsets with pressure sensor arrays at scale.
Japan
Aging population caregivers and municipal health management programs seek elderly-accessible interface designs. METI PSE electrical safety certification extends import lead times for unapproved radio-enabled devices. Nagoya's industrial automation cluster adapts factory calibration systems for consumer health hardware production.
United Kingdom
National Health Service pilot programs and private gym chains test reimbursement-eligible remote monitoring deployments. MHRA guidance on wellness device claims influences marketing compliance for body composition algorithms. London's health technology venture ecosystem channels early-stage capital toward connected sensor startups.
Smart Body Scales Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price-performance segments. Consumer electronics conglomerates leverage existing supply chain infrastructure and retail distribution relationships. Dedicated health technology specialists concentrate clinical validation resources and medical channel relationships. Strategic moves center on multi-frequency sensor algorithm licensing and enterprise wellness platform API integrations.
Within the connected health specialist tier, Withings and Renpho occupy distinct positioning archetypes. Garmin anchors wearable ecosystem extension strategies. Pure-play specialists exemplify clinical-grade sensor development concentration.
| Leading Market Players |
|---|
| Withings |
| Renpho |
| InBody |
| Garmin |
| Omron Healthcare |
| Anker (Eufy) |
| Tanita |
| HoMedics |
| Arboleaf |
| Others |
Pricing and Supply Chain Analysis
Multi-frequency bioelectrical impedance sensor miniaturization is compressing production costs while concentrating precision manufacturing capabilities among ISO 13485-certified assemblers in Germany and China. This technology transition simultaneously erodes margins on single-frequency hardware and elevates pricing power for clinical-grade units with segmental measurement capabilities.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware-only transactions from subscription-tiered models incorporating cloud analytics and API access. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Price erosion runs through the economy tier as Shenzhen-based manufacturers exploit BLE chipset commoditization. Home fitness enthusiasts exhibit highest price sensitivity, while healthcare providers prioritize ISO 13485 certification over unit cost.
Supply Chain Analysis
Reverse-logistics flows for calibration drift and sensor degradation remain underdeveloped, with most units discarded rather than refurbished. Component sourcing draws from China's Shenzhen corridor for BLE chipsets, Germany's Baden-Württemberg cluster for precision load cells, and Japan's Nagoya region for factory calibration systems. Single-source vulnerability concentrates in medical-grade impedance sensor substrates. Distribution runs through Amazon-native direct-to-consumer channels for home use and enterprise procurement platforms for institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart body scales market functions as a stable compounder anchored by reimbursement expansion for remote patient monitoring data streams. Chronic disease management workflows generate recurring demand that transcends consumer electronics cyclicality.
For Market Incumbents: Acquire multi-frequency sensor algorithm portfolios to defend against clinical-grade accuracy commoditization. Backward integration into precision load cell manufacturing mitigates single-source dependency risks. ISO 13485 certification investments preserve hospital channel eligibility as FDA software-as-medical-device scrutiny intensifies.
For New Entrants and Emerging Players: The premium-economy price-point gap in Wi-Fi-enabled clinical-adjacent hardware offers white-space entry. Target Germany's corporate wellness procurement with API-integrated population health dashboards. Pursue white-label manufacturing partnerships with Shenzhen EMS providers to compress time-to-market.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play specialists lacking enterprise wellness platform integrations. Long-term viability hinges on clinical channel penetration and recurring revenue attachment rates. Monitor FDA guidance evolution on diagnostic algorithm classification as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Frequency Sensor Licensing | Clinical-grade accuracy compression enables premium tier defense against mid-market erosion. |
| Enterprise API Integration | Fortune 500 wellness procurement demands aggregated population health data feeds. |
| ISO 13485 Certification Pathway | Hospital system eligibility requires medical device-grade quality management systems. |
| Cloud-Native Wi-Fi Architecture | Autonomous data syncing captures affluent households seeking phone-independent capture. |
| Reimbursement Strategy Development | CMS remote patient monitoring expansion creates sustainable revenue anchoring. |
Research Methodology
Multiple input streams — connected health device procurement managers, biomedical engineers at hospital systems, BLE chipset sourcing directors, FCC certification consultants, and corporate wellness benefits administrators — were reconciled against secondary validation from FDA 510(k) filings, CE marking databases, CMS reimbursement bulletins, and MIIT radio transmission standards. Bottom-up unit economics modeling triangulated against top-down market sizing across connectivity standards and end-user channels.
Data-stream reconciliation anchored volume projections across the analysis window to segmentation dimensions spanning product architecture, technology protocol, application depth, and institutional versus residential purchasing patterns. CAGRs derived from longitudinal reimbursement policy trajectories and sensor cost experience curves. Forecast inputs incorporated EU MDR classification timelines and METI PSE certification throughput constraints.
Caveats apply where FDA software-as-medical-device reclassification or REACH chemical compliance revisions could materially shift the outlook. Practitioners should monitor reimbursement code expansions for body composition monitoring and notified body certification backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Underarm Sweat Pads Market
Personal Grooming Products
Electric Shavers Market
Personal Grooming Products
Global Mosquito Repellent Products Market
Personal Grooming Products
Shavers Market
Personal Grooming Products
Europe and MEA Condom Market
Personal Grooming Products
North America Hair Styling Tools Market
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
Sexual Lubricant Market
Personal Grooming Products
Hand Hygienic Product Market
Personal Grooming Products
Shaving Pen Market
Personal Grooming Products
US Percussion Massage Gun Market
Personal Grooming Products
Global Beard Balm Market
Personal Grooming Products
Handheld Massager Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
India Sexual Wellness Market