
 Shoe Insert Market | 2026-2036
Shoe Insert Market Size, Share, and Industry Trends Forecast 2026-2036
Shoe Insert Market Outlook
Buyer concentration among specialty running retailers and orthopedic clinics is recalibrating how manufacturers allocate trade marketing budgets. Bauerfeind AG leverages its medical heritage to dominate European pharmacy channels. Superfeet Worldwide, Inc. competes through biomechanical R&D partnerships with collegiate athletic programs. New Balance Athletics, Inc. extends its footwear brand equity into in-house insert lines sold through owned retail.
Shoe inserts are engineered support devices fabricated from layered composites of ethylene-vinyl acetate foam, thermoplastic polyurethane, or carbon fiber shells, manufactured through heat-molding or CNC milling to achieve prescribed durometer ratings and arch geometries for load redistribution. Orthotic-grade inserts command premium positioning due to prescription requirements and durable medical equipment billing codes, while gel-based products occupy mass-market price tiers through supermarket and online retail penetration. Athletes represent the fastest-growing end-user cohort as sports science programs institutionalize biomechanical screening protocols.
The US FDA classifies certain orthotic inserts as Class I or II medical devices under 21 CFR Part 890, requiring compliance with quality system regulations for claims involving plantar fasciitis or diabetic foot ulcer prevention. ISO 13485 certification shapes export eligibility for manufacturers targeting European healthcare procurement frameworks under the EU Medical Device Regulation. Stakeholders must monitor how evolving diabetic foot care reimbursement policies in Medicare and national European health systems redirect volume between custom orthotic laboratories and prefabricated product lines.
Market Dynamics
Biomechanical screening protocols at collegiate athletic programs are institutionalizing performance insole procurement as standard equipment, compressing replacement cycles and elevating technical specifications for shock absorption and arch geometry customization.
Growth Catalysts
- 21 CFR Part 890 Classification Clarity:The US FDA's evolving oversight of medical-grade orthotics creates defined pathways for plantar fasciitis and diabetic foot ulcer prevention claims, enabling manufacturers to pursue durable medical equipment billing codes with regulatory certainty.
- German Podiatric Reimbursement:Germany's statutory health insurance framework covers custom orthotic prescriptions, driving pharmacy channel volume and supporting premium positioning for carbon fiber and thermoplastic polyurethane shell constructions.
- EVA Foam Process Innovation:Advanced heat-molding techniques for ethylene-vinyl acetate composites enable mass-customization at scale, reducing unit economics for semi-custom products positioned between prefabricated and laboratory-fabricated tiers.
Market Restraints
- Petrochemical Input Volatility:Ethylene-vinyl acetate and thermoplastic polyurethane pricing tracks crude oil derivatives, compressing margins for manufacturers without backward integration into polymer compounding or long-term supply contracts.
- ISO 13485 Certification Burden:European Medical Device Regulation compliance requires quality management system investments that exclude smaller manufacturers from healthcare procurement frameworks, concentrating supply among certified incumbents.
- Over-the-Counter Gel Substitutes:Mass-market gel-based inserts sold through supermarket and online retail channels capture price-sensitive consumers, limiting addressable market expansion for biomechanically engineered products.
Strategic Opportunities
- Medicare Diabetic Foot Care Expansion:Evolving reimbursement policies for therapeutic shoes and inserts among Medicare beneficiaries redirect volume toward prefabricated heat-moldable products that satisfy billing code requirements at lower cost than custom laboratory fabrication.
- Sports Medicine Clinic Direct Channels:Biomechanical screening partnerships with physical therapy practices and sports medicine clinics create bypass opportunities around traditional retail markup structures, capturing margin and patient data simultaneously.
- 3D Printing Convergence with Pressure Mapping:Integration of in-store pressure plate diagnostics with additive manufacturing enables same-day custom shell production, collapsing fulfillment timelines that previously required two-week laboratory turnaround.
Industry Challenges
- Podiatric Technician Talent Scarcity:Laboratory-fabricated custom orthotics require skilled technicians for plaster casting and CNC milling operations, with training pipeline gaps constraining capacity expansion for high-margin prescription segments.
- EU MDR Transition Timelines:Recertification requirements under the Medical Device Regulation impose documentation and clinical evidence burdens that delay product launches and strain regulatory affairs staffing at mid-tier manufacturers.
- Omni-Channel Inventory Complexity:Serving specialty running retailers, orthopedic clinics, pharmacy chains, and direct-to-consumer platforms simultaneously requires segmented SKU strategies that multiply working capital requirements and obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shoe Insert Market |
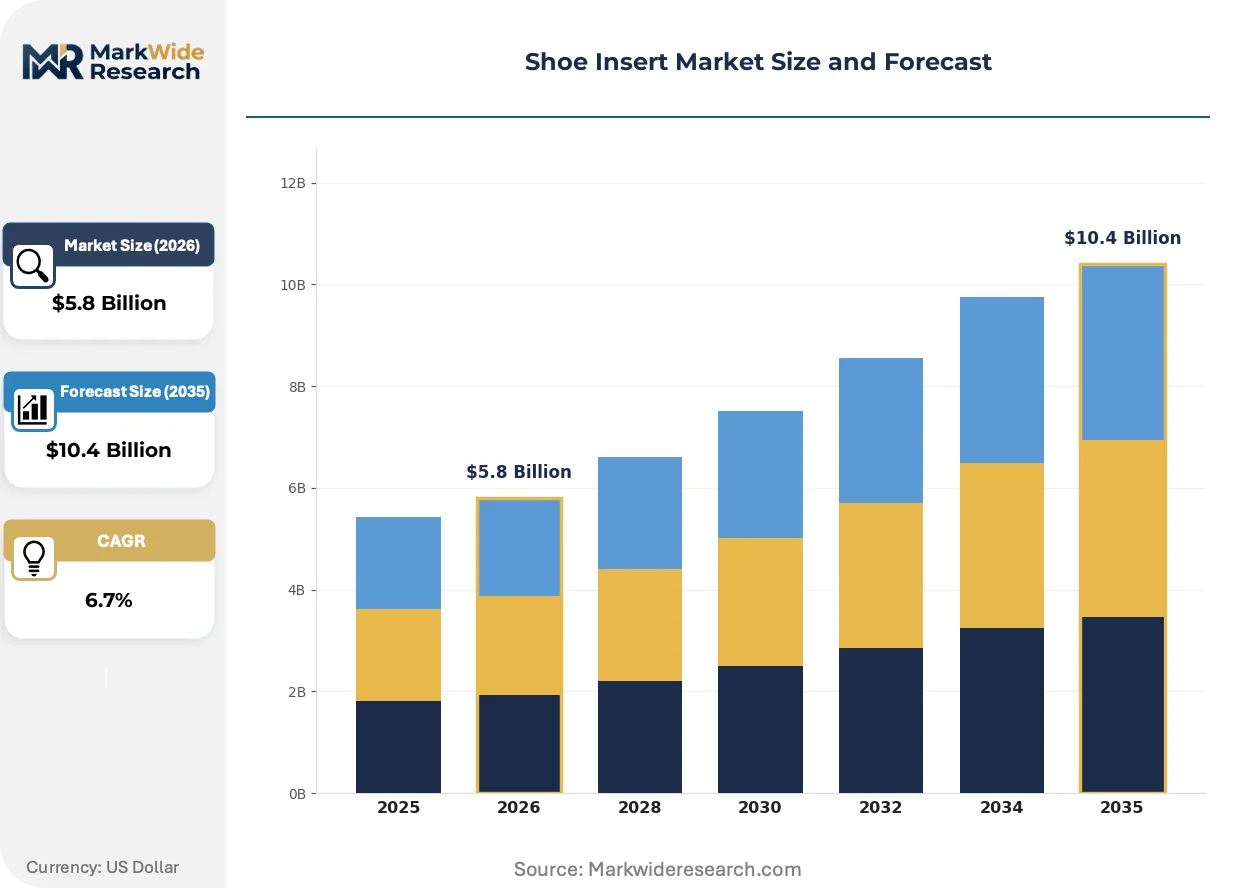
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arch Support, Cushioning, Gel, Orthotic End User: Athletes, Diabetics, Elderly, General Public Material: Foam, Rubber, Fabric, Plastic Distribution Channel: Online Retail, Pharmacies, Sports Stores, Supermarkets |
| Companies Covered | Bauerfeind AG, Superfeet Worldwide, Inc., Foot Science International, PowerStep, New Balance Athletics, Inc., Sidas, ENERTOR, Aetrex Inc., Spenco Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shoe Insert Market Strategic Shifts
Digital manufacturing workflows and regulatory classification refinements are compressing the gap between mass-market accessibility and clinical-grade performance, while procurement centralization among institutional buyers restructures channel economics.
Carbon fiber reinforced thermoplastic composites are expanding into performance insole midsole layers, delivering stiffness-to-weight ratios that satisfy collegiate athletic program specifications for energy return and torsional rigidity. NCAA Division I equipment managers now specify durometer ratings and arch height tolerances in competitive bid documents, forcing suppliers to certify batch consistency through third-party testing. This material migration is expanding into the premium prefabricated tier, enabling price positioning above standard EVA constructions without full custom laboratory costs.
The EU Medical Device Regulation's classification of certain prefabricated orthotics as Class I medical devices is requiring technical documentation and post-market surveillance systems that previously applied only to custom-fabricated products. Manufacturers targeting European healthcare procurement must now maintain vigilance systems for adverse events and periodic safety updates, elevating compliance costs across product lines. German pharmacy chains and French hospital purchasing groups are consolidating supplier lists around MDR-certified manufacturers, accelerating consolidation among mid-tier competitors.
Biomechanical screening is migrating from clinical settings to retail environments through pressure-mapping kiosk installations at specialty running stores and sporting goods chains. These systems generate arch index measurements and pressure distribution reports that guide consumer self-selection toward appropriate support levels, reducing return rates and enabling staff-assisted selling without certified pedorthist involvement. This channel evolution is most advanced in the United States and Germany, where retail labor costs and podiatrist availability ratios create favorable economics for technology-mediated fitting assistance.
Shoe Insert Market Segmentation
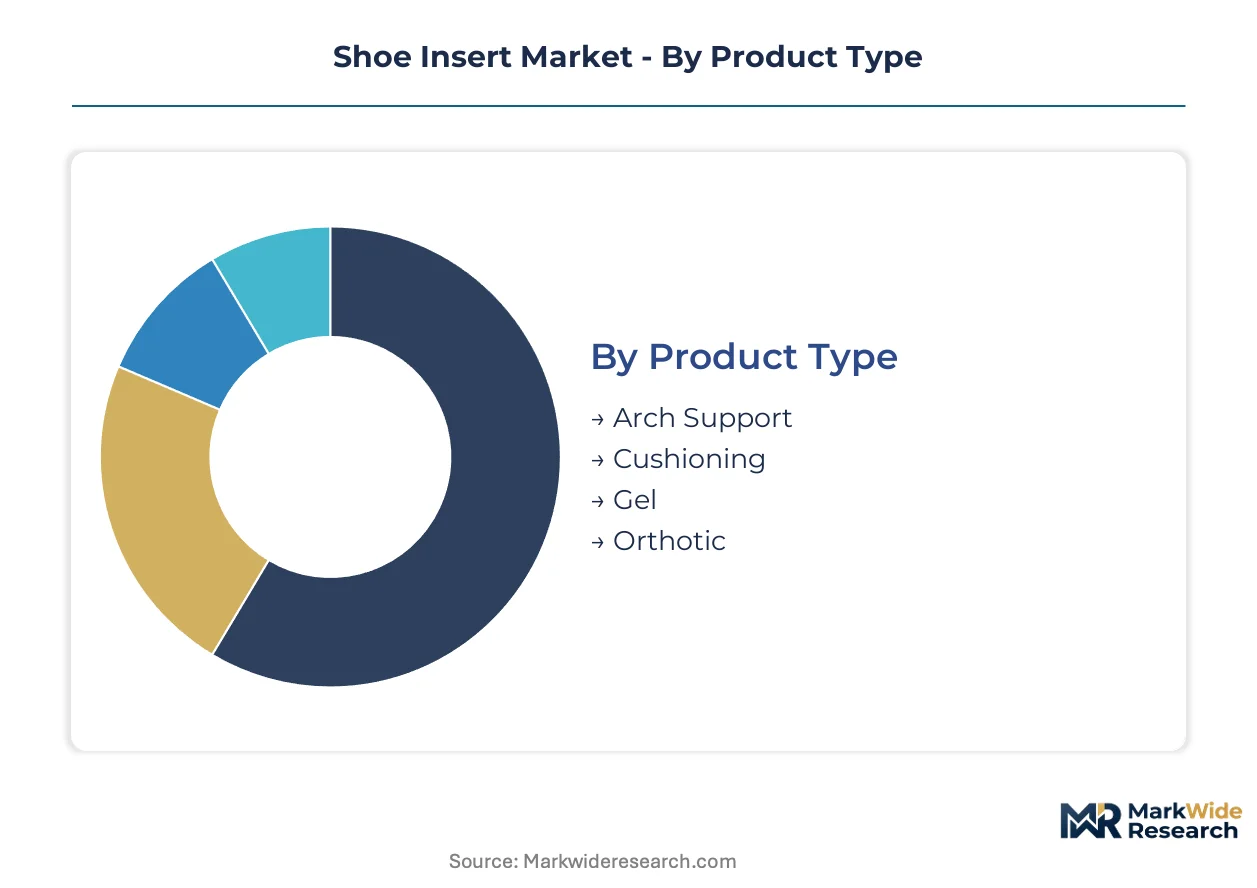
Segmentation in the shoe insert market determines pricing architecture, regulatory pathways, and channel strategy. Material composition and end-user clinical requirements create divergent margin profiles and certification burdens across product tiers.
Product Type:
Standalone orthotic devices command premium positioning through prescription requirements, while prefabricated cushioning products integrate into mass retail environments with minimal clinical oversight.
- Arch Support:Engineered with thermoplastic shells and calibrated durometer foams to redistribute plantar pressure. German statutory health insurance reimbursement drives pharmacy channel volume for prescription-grade variants with carbon fiber reinforcement.
- Cushioning:Multi-density EVA foam constructions absorb impact forces during athletic activity. NCAA Division I equipment managers specify shock attenuation thresholds in procurement contracts, compressing replacement cycles.
- Gel:Viscous silicone polymer inserts target price-sensitive consumers through supermarket and online retail penetration.
- Orthotic:Custom-laboratory or heat-moldable devices fabricated to individual biomechanical prescriptions under FDA 21 CFR Part 890 classification.
Volume placements concentrate in Cushioning; the faster expansion belongs to Orthotic.
End User:
Customer type segmentation separates clinical prescription workflows from self-directed retail purchases, with reimbursement eligibility determining addressable market boundaries.
- Athletes:Biomechanical screening protocols at collegiate and professional programs institutionalize performance insole procurement as standard equipment. Sports medicine clinics in the United States and Germany capture margin through direct-channel partnerships.
- Diabetics:Therapeutic shoe and insert coverage under Medicare billing codes redirects volume toward prefabricated heat-moldable products. FDA classification requirements for ulcer prevention claims elevate compliance costs.
- Elderly:Fall-risk reduction and pressure redistribution needs drive podiatric prescription volume in European healthcare systems.
- General Public:Self-directed purchasers select from retail assortments based on comfort preferences without clinical consultation.
Athletes generate the steepest expansion trajectory; Diabetics anchor reimbursement-dependent volume.
Material:
Raw material selection determines manufacturing process, performance specification, and exposure to petrochemical input volatility.
- Foam:Ethylene-vinyl acetate composites enable heat-molding customization at scale. Advanced processing techniques reduce unit economics for semi-custom tiers positioned between prefabricated and laboratory-fabricated products.
- Rubber:Natural and synthetic elastomer compounds deliver durability for industrial and occupational footwear applications.
- Fabric:Moisture-wicking textile topcovers enhance comfort in athletic and everyday use segments.
- Plastic:Thermoplastic polyurethane shells provide structural rigidity in orthotic-grade devices.
Foam dominates current production volume; carbon fiber-thermoplastic composites are gaining share fastest in premium tiers.
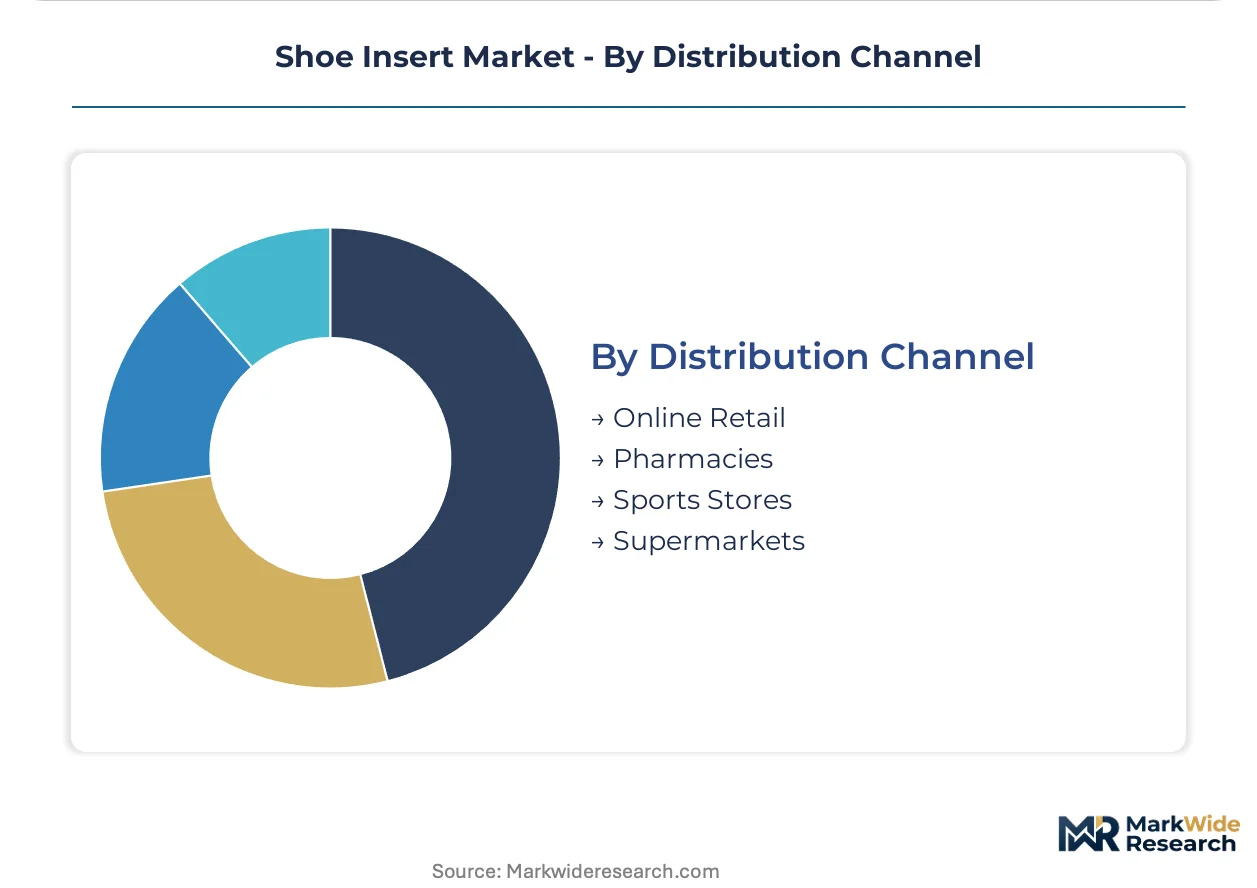
Distribution Channel:
Channel structure shapes working capital requirements, SKU complexity, and customer data capture capabilities.
- Online Retail:Direct-to-consumer platforms enable biometric data collection and algorithmic fitting recommendations. Return rate management challenges persist for products requiring physical trial.
- Pharmacies:German and French pharmacy chains consolidate supplier lists around EU MDR-certified manufacturers, accelerating certification concentration.
- Sports Stores:Specialty running retailers install pressure-mapping kiosks for technology-mediated fitting assistance without certified pedorthist involvement.
- Supermarkets:Mass-market gel and foam products occupy low-price tiers with minimal technical differentiation.
Pharmacies and Sports Stores capture premium positioning; Online Retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters in Germany, the United States, and select Asian manufacturing hubs where podiatric infrastructure and athletic program procurement intersect. Reimbursement frameworks and sports medicine adoption rates determine regional penetration depth for premium orthotic tiers.
United States
NCAA Division I equipment managers now specify durometer ratings and arch tolerances in competitive bids, compressing replacement cycles for performance insoles. FDA 21 CFR Part 890 classification creates defined pathways for plantar fasciitis and diabetic foot ulcer prevention claims, enabling durable medical equipment billing code pursuit. Boston's sports medicine corridor anchors biomechanical R&D partnerships between manufacturers and collegiate athletic programs.
Germany
Statutory health insurance reimbursement for custom orthotic prescriptions drives pharmacy channel volume for carbon fiber and thermoplastic polyurethane constructions. EU Medical Device Regulation compliance requirements concentrate supplier lists among ISO 13485-certified manufacturers, excluding smaller competitors. Bavaria's orthopedic device cluster hosts precision milling operations serving both domestic and export healthcare procurement frameworks.
Japan
Aging demographics and fall-risk reduction protocols elevate podiatric prescription volume for pressure-redistributing orthotic devices. METI industrial standards for medical device quality management shape domestic certification requirements that parallel ISO 13485 frameworks. Osaka-Kobe manufacturing belt concentrates precision foam processing for athletic and medical-grade insert production.
China
Domestic sports science program expansion and marathon participation growth drive performance insole demand among amateur and semi-professional athletes. NMPA medical device classification requirements for therapeutic claims create compliance barriers for imported premium products. Yangtze River Delta manufacturing centers supply EVA foam composites to both domestic brands and export-oriented contract producers.
United Kingdom
NHS podiatry service commissioning frameworks redirect volume toward prefabricated heat-moldable products as cost-containment measures limit custom laboratory referrals. MHRA medical device registration requirements align with EU MDR transitional provisions for continued market access. London's specialty running retail corridor deploys pressure-mapping kiosk networks for technology-mediated fitting assistance.
Shoe Insert Market Competitive Environment
German producers anchor the medical-grade tier through pharmacy channel dominance and statutory reimbursement access; US specialists hold performance athletic positioning through collegiate program partnerships and direct-to-consumer platform development. The vendor structure stratifies across three archetypes: heritage medical device manufacturers with ISO 13485 certification, athletic-focused biomechanical engineering firms, and footwear brand extenders leveraging owned retail networks. Consolidation pressure concentrates among mid-tier competitors facing EU MDR recertification burdens, while strategic partnerships between pressure-mapping technology providers and additive manufacturing services reshape fulfillment economics.
Within the heritage medical tier, Bauerfeind AG and Foot Science International exemplify European pharmacy channel anchoring through reimbursement-aligned product architectures. Superfeet Worldwide, Inc. occupies the athletic-specialist position, representing US-based biomechanical R&D integration with institutional procurement frameworks. New Balance Athletics, Inc. demonstrates footwear brand extension strategy, leveraging owned retail networks for in-house insert line distribution.
| Leading Market Players |
|---|
| Bauerfeind AG |
| Superfeet Worldwide, Inc. |
| Foot Science International |
| PowerStep |
| New Balance Athletics, Inc. |
| Sidas |
| ENERTOR |
| Aetrex Inc. |
| Spenco Medical Corporation |
| Others |
Value Chain & Pricing Dynamics
Ethylene-vinyl acetate foam pricing tracks crude oil derivatives through polymer compounding stages, translating petrochemical volatility into margin compression for manufacturers lacking backward integration or long-term supply contracts. This input cost pathway stratifies final product positioning: laboratory-fabricated custom orthotics with carbon fiber shells command premium pharmacy channel placement in Germany, while mass-market gel constructions absorb volatility through supermarket retail penetration.
Pricing Analysis
Volume placements concentrate in mass-market cushioning tiers, while margin capture clusters in prescription-grade orthotic segments. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber-reinforced laboratory products from heat-moldable semi-custom devices and supermarket gel inserts. Cost compression in the mid-tier intensifies because EVA foam process innovation enables mass-customization at scale. Price-sensitive general public consumers select from retail assortments without clinical consultation, while least-sensitive diabetic and elderly segments navigate reimbursement-dependent prescription workflows.
Supply Chain Analysis
Ocean freight and containerized shipping costs from Yangtze River Delta manufacturing centers to European pharmacy distribution hubs directly influence landed cost structures for prefabricated insert tiers. Supply concentration centers on China for EVA foam composite production, Germany for precision milling operations serving healthcare procurement, and the United States for collegiate athletic program fulfillment. Raw material dependencies draw from petrochemical feedstocks for thermoplastic polyurethane shells, carbon fiber prepregs for structural reinforcement, and viscous silicone polymers for gel constructions. Single-source vulnerability in medical-grade polymer compounding creates exposure to regulatory restriction cascades under EU MDR enforcement. Distribution runs through specialty running retailers, orthopedic clinics, pharmacy chains, and direct-to-consumer platforms simultaneously.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
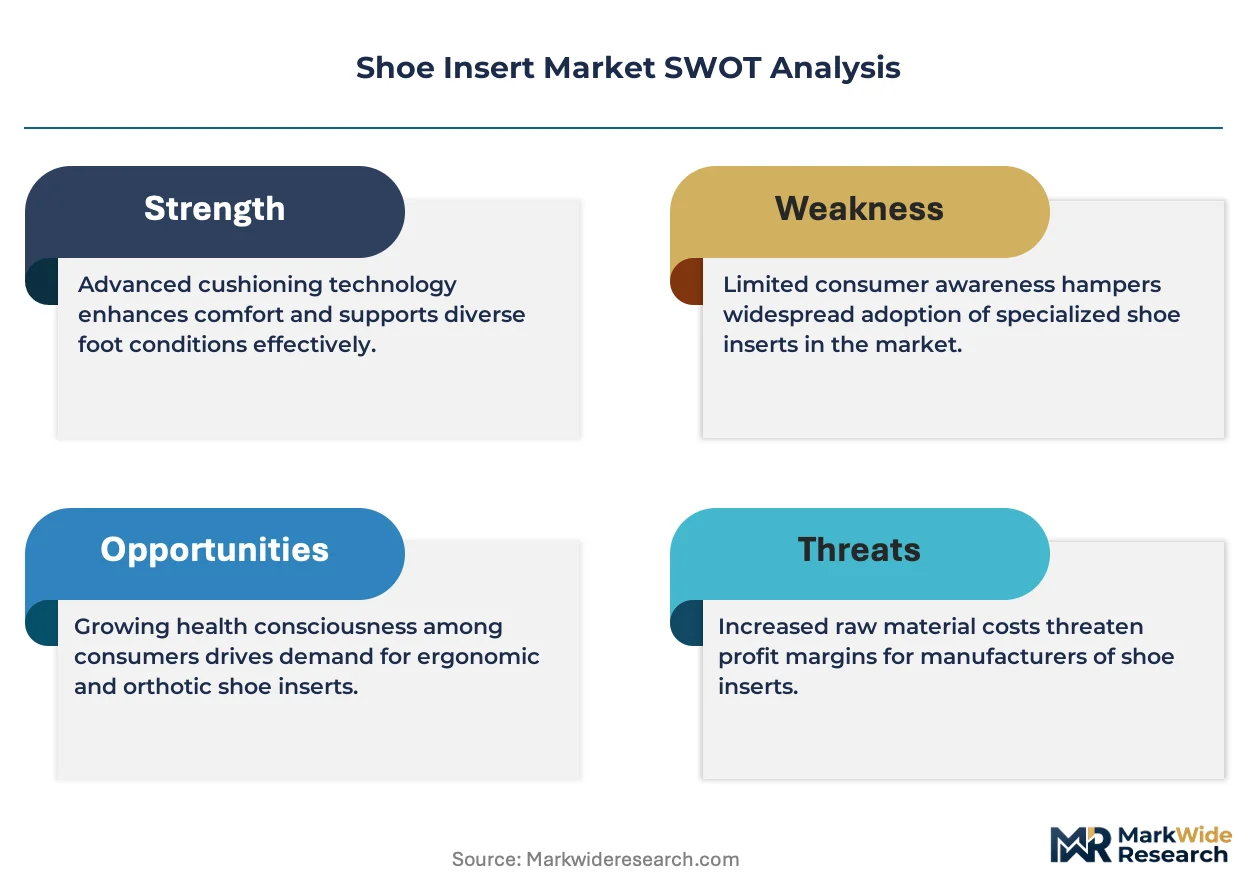
This market reads as a cost-of-compliance story where EU Medical Device Regulation recertification requirements create a barrier-to-entry moat for ISO 13485-certified incumbents while excluding smaller manufacturers from healthcare procurement frameworks.
For Market Incumbents: Cement pharmacy channel anchoring through statutory reimbursement alignment in Germany and France, while acquiring pressure-mapping kiosk networks to capture retail biomechanical data streams. Threat from 3D printing convergence with additive manufacturing services demands capacity addition in Bavaria's orthopedic device cluster to maintain laboratory-fabricated turnaround advantages. Certification investment in FDA 21 CFR Part 890 quality system regulations defends Medicare billing code access against emerging heat-moldable competitors. For New Entrants and Emerging Players: Sports medicine clinic direct channels offer the most penetrable white-space target, bypassing traditional retail markup structures through biomechanical screening partnerships with physical therapy practices. Medicare diabetic foot care reimbursement expansion redirects volume toward prefabricated heat-moldable products, creating entry opportunity at lower certification burden than custom laboratory tiers. Go-to-market angle centers on algorithmic fitting recommendations through direct-to-consumer platforms with biometric data collection capabilities. For Investors and Strategic Acquirers: Consolidation of German pharmacy supplier lists around MDR-certified manufacturers is the leading indicator that mid-tier competitors face forced exit or acquisition scenarios over the projection horizon. Long-term viability favors vertically integrated specialists with in-house polymer compounding and precision milling operations. Acquisition target archetype: athletic-focused biomechanical engineering firms with collegiate program procurement relationships but lacking ISO 13485 certification for healthcare expansion. Signal to watch: EU MDR enforcement actions triggering supply list exclusions.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | ISO 13485 quality management system deployment secures pharmacy channel access in Germany and France. |
| Pressure-Mapping Kiosk Deployment | In-store diagnostics integration with specialty running retailers reduces return rates and enables staff-assisted selling. |
| Backward Integration into Polymer Compounding | In-house EVA foam production mitigates petrochemical input volatility and compresses unit economics. |
| 3D Printing Convergence Partnership | Additive manufacturing service alliances collapse custom orthotic fulfillment timelines from laboratory turnaround. |
| Medicare Reimbursement Strategy | Durable medical equipment billing code pursuit redirects diabetic foot care volume toward prefabricated heat-moldable tiers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across podiatrists, orthopedic device procurement managers, collegiate athletic equipment directors, and pharmacy chain category buyers. FDA 21 CFR Part 890 classification databases, EU Medical Device Regulation technical documentation, German statutory health insurance reimbursement schedules, and NCAA Division I procurement bid documents supplied validation anchors. Bottom-up unit economics modeling triangulated against top-down healthcare expenditure flows.
Granularity-level framing applied product type, end user, material composition, and distribution channel dimensions at the country level for Germany, the United States, Japan, China, and the United Kingdom. CAGRs derived from segment-level volume trajectories weighted by reimbursement policy evolution and sports medicine infrastructure penetration. Industry-specific forecast inputs incorporated petrochemical price indices for EVA and TPU feedstocks, plus Medicare diabetic foot care billing code utilization trends.
Caveats apply where EU MDR recertification timeline delays, petrochemical price volatility spikes, or Medicare reimbursement policy reversals could materially shift the outlook. Forecasts reflect assumptions about collegiate athletic program procurement institutionalization and pharmacy channel consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Personal Lubricants Market
Personal Grooming Products
Disposable Electric Toothbrushes Market
Personal Grooming Products
Infant Mosquito Repellent Market
Personal Grooming Products
Mexico Beard Trimmer Market
Personal Grooming Products
Global Mosquito Repellent Products Market
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Back Massager Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
North America Mosquito Repellent Market
Personal Grooming Products
US Percussion Massage Gun Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Smart Body Scales Market
Personal Grooming Products
Shaving Market
Personal Grooming Products
Hand Hygienic Product Market