
 Massage Fascia Gun Market | 2026-2036
Massage Fascia Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Massage Fascia Gun Market Insights
The EU Green Deal's product sustainability mandates is shifting procurement criteria across European fitness equipment distributors toward repairable, low-carbon motor assemblies. Therabody leverages its clinical certification pipeline to sustain premium positioning in physical therapy channels. Hyperice anchors North American sports team supply contracts through its connected recovery ecosystem. Ekrin Athletics differentiates via direct-to-consumer pricing control and extended warranty programs that reduce lifetime replacement rates.
A massage fascia gun is a handheld percussive therapy device employing a high-torque brushless motor to deliver rapid, concentrated pressure pulses at amplitudes typically ranging from 10 to 16 millimeters and frequencies between 1,200 and 3,200 percussions per minute, designed to reduce myofascial tension and enhance localized blood flow in muscle tissue. Portable units dominate volume shipments due to lithium-ion battery energy density improvements that now sustain 4-6 hours of runtime at sub-1.5 kilogram weights. Wireless technology adoption accelerates fastest among home users seeking clutter-free recovery spaces, while premium price tier units capture the majority of margin pools through proprietary motor control algorithms and app-integrated treatment protocols.
FDA Class II medical device pathways shape entry barriers for clinical-grade fascia guns targeting physical therapist practices, while FCC electromagnetic emissions standards govern wireless connectivity modules in connected units. The EU's CE marking and MDR compliance requirements for therapeutic claims constrain marketing language and substantiation documentation across European distribution channels. Stakeholders must monitor evolving battery transportation regulations from IATA and national aviation authorities, as lithium-cell shipping restrictions increasingly constrain cross-border e-commerce fulfillment speed and cost structures.
Market Dynamics
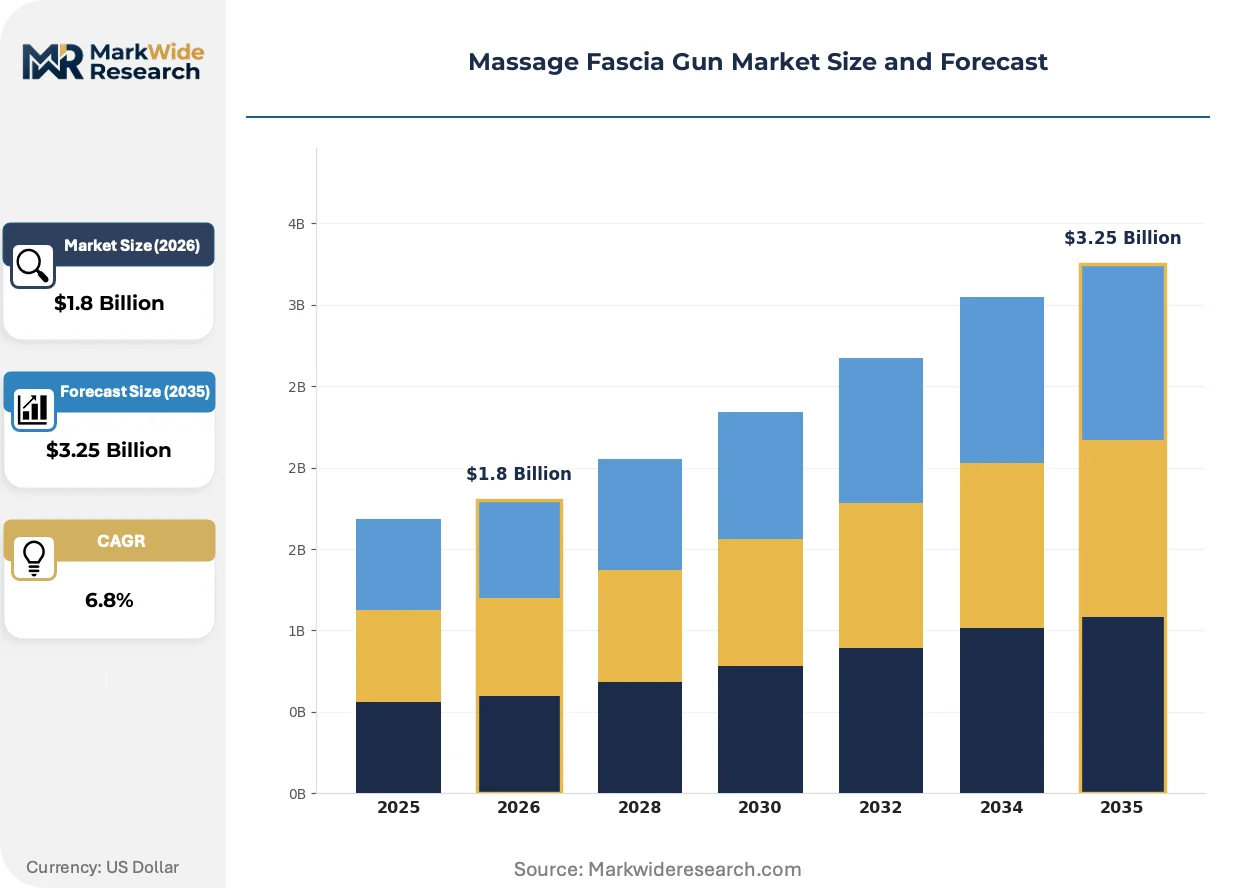
Brushless motor miniaturization and lithium-ion energy density gains are compressing device weights below 1.2 kilograms while extending runtime, fundamentally altering portability thresholds and channel economics for percussive therapy equipment.
Growth Catalysts
- FDA Class II medical device pathways:Clinical-grade certification opens physical therapy practices and sports medicine clinics as institutional buyers with recurring replacement cycles and bulk procurement authority.
- Boutique fitness studio chains:Recovery-room standardization across premium gym networks generates fleet orders for commercial-duty units with extended warranty requirements.
- Lithium-polymer battery chemistry:Higher discharge rates and reduced thermal profiles enable sustained high-torque output without motor derating, satisfying athlete demands for uninterrupted treatment sessions.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium procurement dependence on Chinese processing facilities exposes motor manufacturers to export quota volatility and price spikes.
- IATA lithium-cell shipping restrictions:Cross-border e-commerce fulfillment faces extended transit times and elevated hazmat surcharges, compressing direct-to-consumer margin structures.
- Brushless motor controller IP thickets:Proprietary field-oriented control algorithms held by incumbent suppliers create licensing barriers for new entrants seeking competitive torque precision.
Strategic Opportunities
- EU Green Deal repairability mandates:Modular motor housings and standardized battery interfaces position early adopters for preferential placement with sustainability-screening distributors.
- Telehealth-integrated recovery protocols:App-connected treatment logging enables remote physical therapist oversight, opening subscription revenue streams beyond hardware sales.
- India's PLI scheme for electronics manufacturing:Contract assembly relocation to Indian SEZs reduces landed cost for price-sensitive Asian markets while satisfying local content requirements.
Industry Challenges
- FCC Part 15 electromagnetic emissions certification:Wireless module integration for app connectivity requires pre-market testing cycles that extend product launch timelines by 4-6 months.
- Biomechanical efficacy substantiation:Peer-reviewed clinical data requirements for therapeutic claims demand longitudinal studies with institutional review board oversight, straining R&D budgets.
- Post-sales service network density:Repairable design compliance under EU regulations necessitates regional technician certification programs that fragment operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Massage Fascia Gun Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Corded, Wireless, High-Performance End User: Athletes, Fitness Enthusiasts, Physical Therapists, Home Users Technology: Pneumatic, Electric, Mechanical, Battery-Operated Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Therabody, Hyperice, TimTam, Ekrin Athletics, DMS, Rapid Release, Pleno, Lifepro, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Massage Fascia Gun Market Trends and Innovations
Percussive therapy devices are converging with digital health infrastructure and sustainable manufacturing protocols, redefining value capture beyond hardware margins toward data-enabled service relationships.
Quasi-sinusoidal amplitude control is electrifying treatment precision through real-time motor feedback loops that adjust stroke depth based on tissue resistance. Physical therapy departments at university athletic programs are piloting these units for load-managed rehabilitation protocols. The technology is compressing differentiation timelines as algorithmic performance becomes the primary purchase criterion over raw motor specifications.
EU MDR compliance requirements for therapeutic medical devices are tightening clinical evidence standards for percussive therapy claims marketed to healthcare providers. Manufacturers must now submit technical documentation including biocompatibility testing and risk management files to notified bodies before CE marking. European distributors are consolidating supplier rosters toward pre-certified vendors, accelerating consolidation among smaller brands lacking regulatory affairs capacity.
Recovery-as-a-service bundling is displacing standalone hardware transactions in corporate wellness programs and professional sports organizations. Teams and employers now lease device fleets with usage analytics and preventive maintenance included, transferring capital expenditure to operational budgets. This pattern concentrates most visibly in North American markets where sports franchises and tech sector employers compete on employee wellness amenities.
Massage Fascia Gun Market Segmentation
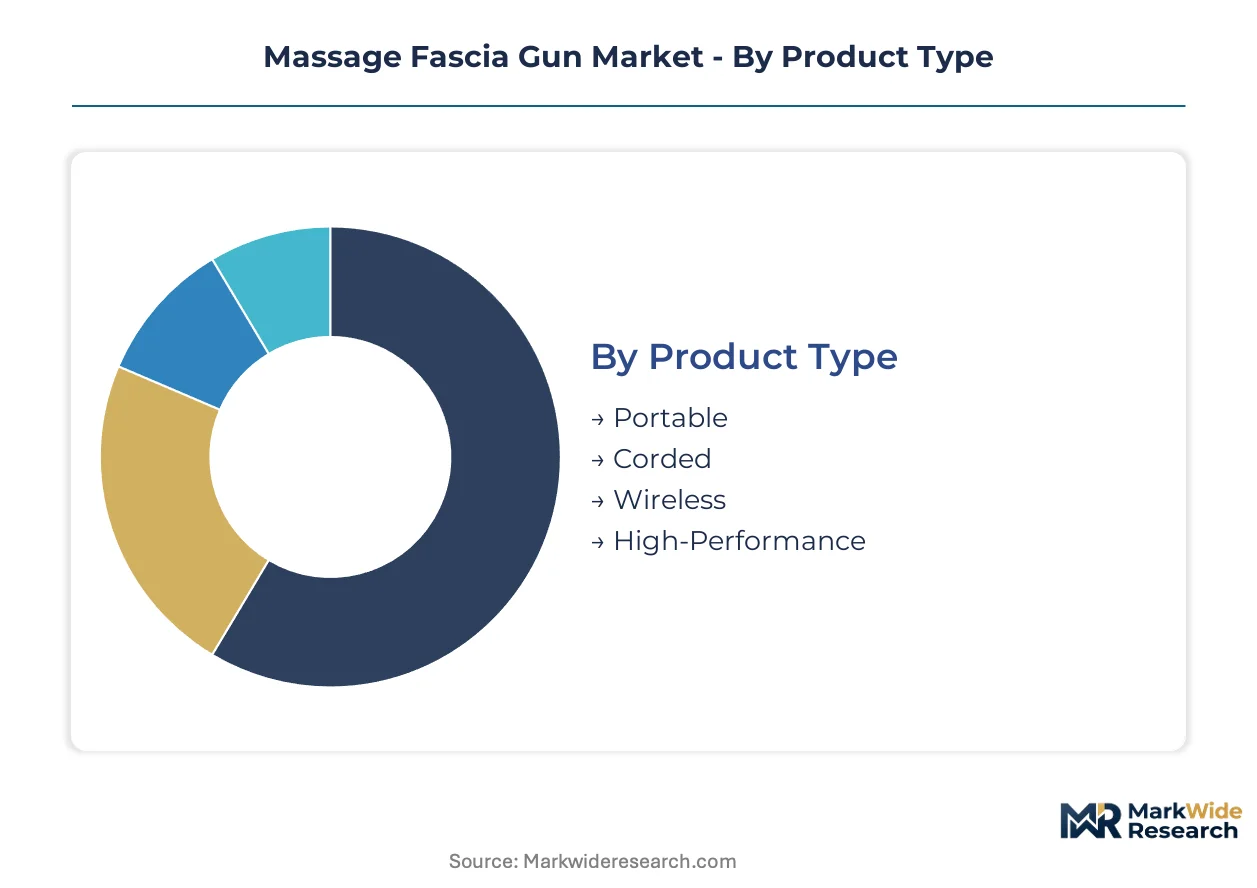
Segmentation in the massage fascia gun market reveals how upgrade cycles and replacement demand concentrate across device categories. Replacement timelines vary from 18 months for budget home units to 5+ years for clinical-grade equipment, creating distinct revenue pulses across each segment cluster.
Product Type:
Replacement cycles compress as motor miniaturization and battery chemistry improvements render older units obsolete faster.
- Portable:Lithium-polymer cells now deliver 4-6 hour runtime at sub-1.2 kilogram weights, making these the default choice for athletes traveling to competitions. Demand concentrates in United States boutique fitness chains standardizing recovery-room equipment across locations.
- Wireless:Bluetooth-enabled units with app-integrated treatment protocols command margin premiums through firmware upgradeability that extends functional lifespan. Home users in Germany and France prioritize cable-free recovery spaces, driving fastest adoption in EU markets subject to Ecodesign repairability mandates.
- Corded:Continuous power delivery suits clinical settings where uninterrupted treatment sessions matter more than mobility.
- High-Performance:Brushless motors with 16mm amplitude and 60-pound stall force target professional sports medicine clinics requiring durability under intensive use.
Portable units sit at the top of the volume ranking, with Wireless climbing the fastest.
End User:
Customer lifetime value diverges sharply based on procurement authority and usage intensity patterns.
- Physical Therapists:Institutional buyers with recurring replacement budgets and bulk procurement power. FDA Class II medical device certification requirements create switching costs that lock practices into validated suppliers. United States rehabilitation clinics drive premium-tier demand.
- Athletes:Individual purchasers prioritize amplitude range and noise suppression for locker-room use. NCAA Division I programs and professional team training facilities in Texas and California generate fleet orders with 3-year replacement cycles.
- Fitness Enthusiasts:Price-sensitive segment where direct-to-consumer brands compete on warranty length and social proof.
- Home Users:Occasional-use buyers selecting based on weight and storage footprint rather than performance specifications.
Physical Therapists generate the highest per-customer revenue, with Athletes expanding most quickly as sports science departments professionalize recovery protocols.
Technology:
Power delivery mechanisms determine maintenance requirements and total cost of ownership across use environments.
- Battery-Operated:Lithium-ion energy density gains enable sustained high-torque output without thermal derating. IATA shipping restrictions on lithium cells complicate cross-border fulfillment for direct-to-consumer brands targeting Australian and Canadian markets.
- Electric:Brushless motor controllers with field-oriented control algorithms deliver precise amplitude modulation. Japanese and South Korean manufacturers hold proprietary IP that creates licensing barriers for new entrants.
- Pneumatic:Compressed air systems in commercial gym installations reduce per-unit maintenance through centralized compressor redundancy.
- Mechanical:Spring-driven mechanisms persist in budget segments where electronic complexity adds failure modes.
Battery-Operated technology dominates shipment volumes, with Electric systems gaining share fastest as algorithmic performance becomes the primary purchase criterion.
Price Tier:
Margin structures stratify based on certification grade, connected features, and warranty depth rather than raw motor specifications alone.
- Premium:FDA-registered units with clinical validation studies and app ecosystems. Physical therapy practices in the United States and university athletic programs absorb price premiums for liability protection and treatment documentation capabilities.
- Mid-Range:Spec-competitive devices targeting fitness enthusiasts who research amplitude and frequency specifications. Ekrin Athletics and similar direct-to-consumer brands control pricing through owned-channel distribution.
- Budget:Unbranded or white-label units sold through Amazon and Alibaba with minimal warranty support and no therapeutic claims.
- Luxury:Design-forward units with materials like carbon fiber housings and concierge support services targeting gift markets and executive wellness programs.
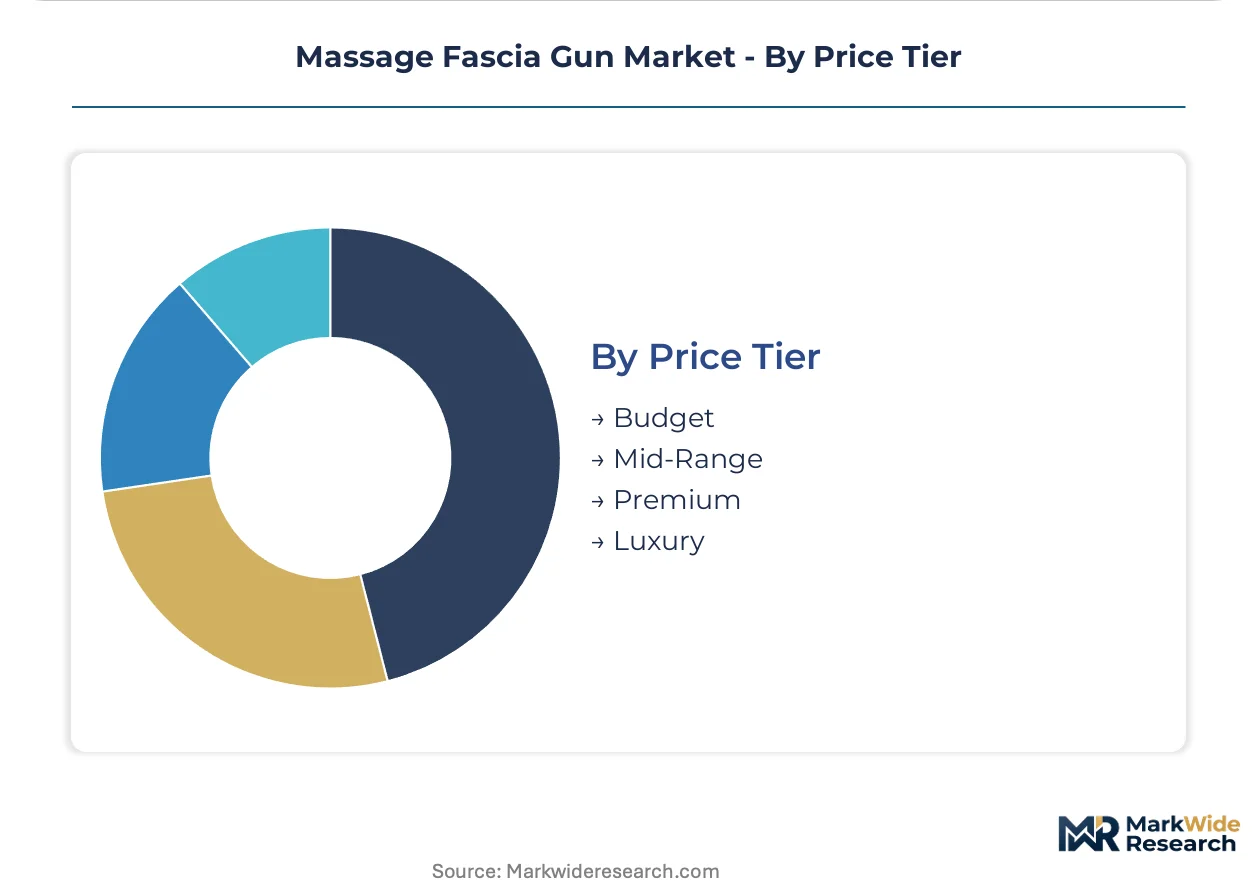
Premium tier captures the majority of profit pools, with Mid-Range expanding most quickly as specification transparency erodes brand premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Percussive therapy devices originated in United States sports medicine clinics during the early 2000s, with commercial scaling accelerating through boutique fitness chain standardization. Today, procurement patterns diverge sharply across regulatory environments and recovery infrastructure maturity.
United States
NCAA Division I athletic programs and professional sports franchises in Texas and California drive fleet procurement of clinical-grade units with 3-year replacement cycles. FDA Class II medical device registration requirements create switching costs that lock physical therapy practices into validated supplier relationships. Dallas-Fort Worth and Los Angeles metropolitan areas concentrate the highest density of sports medicine clinics integrating percussive therapy into standard rehabilitation protocols.
Germany
Fitness enthusiasts in Berlin and Munich prioritize cable-free recovery spaces, accelerating wireless unit adoption faster than any other EU market. EU MDR compliance requirements for therapeutic claims constrain marketing language and substantiation documentation across German distribution channels. The Bavarian industrial corridor around Munich hosts specialized motor controller manufacturers supplying brushless drive systems to device assemblers.
China
Domestic brands dominate price-sensitive consumer segments through direct-to-consumer e-commerce channels on Alibaba and JD.com. NMPA medical device registration pathways for therapeutic claims remain underdeveloped, limiting clinical-grade market penetration. The Pearl River Delta manufacturing cluster around Shenzhen and Dongguan supplies brushless motors and lithium-polymer cells to global device brands.
Japan
Corporate wellness programs in Tokyo and Osaka lease device fleets with usage analytics, transferring capital expenditure to operational budgets. METI energy efficiency standards shape motor design requirements for products targeting the domestic market. The Kanto region around Tokyo concentrates rehabilitation equipment distributors serving aging demographics with home-recovery solutions.
Australia
IATA lithium-cell shipping restrictions complicate cross-border fulfillment from Asian manufacturing hubs, compressing direct-to-consumer margin structures. TGA medical device registration requirements for therapeutic claims create entry barriers for unvalidated suppliers. Melbourne and Sydney host the highest concentration of boutique fitness studios standardizing recovery-room equipment across location networks.
Massage Fascia Gun Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and connected feature depth. The vendor base stratifies into three tiers: FDA-registered clinical specialists, direct-to-consumer specification competitors, and unbranded white-label assemblers. Two dominant competitive moves define current positioning: clinical certification pipeline investments that lock institutional buyers into recurring replacement cycles, and owned-channel distribution construction that bypasses retail margin extraction.
Among United States-based recovery technology developers, Therabody, Hyperice, and Ekrin Athletics occupy distinct archetype positions. Therabody exemplifies the clinical-certification path with FDA-registered units targeting physical therapy practices. Hyperice anchors the connected-ecosystem archetype through sports team supply relationships and app-integrated treatment logging. Ekrin Athletics represents the direct-to-consumer specification competitor, controlling pricing through owned-channel distribution and extended warranty programs that reduce lifetime replacement rates.
| Leading Market Players |
|---|
| Therabody |
| Hyperice |
| TimTam |
| Ekrin Athletics |
| DMS |
| Rapid Release |
| Pleno |
| Lifepro |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
Brushless motor miniaturization and lithium-polymer battery chemistry maturation are compressing bill-of-materials costs while concentrating manufacturing expertise in Shenzhen and Dongguan, simultaneously enabling premium-tier margin capture and supply-side consolidation among vertically integrated assemblers.
Pricing Analysis
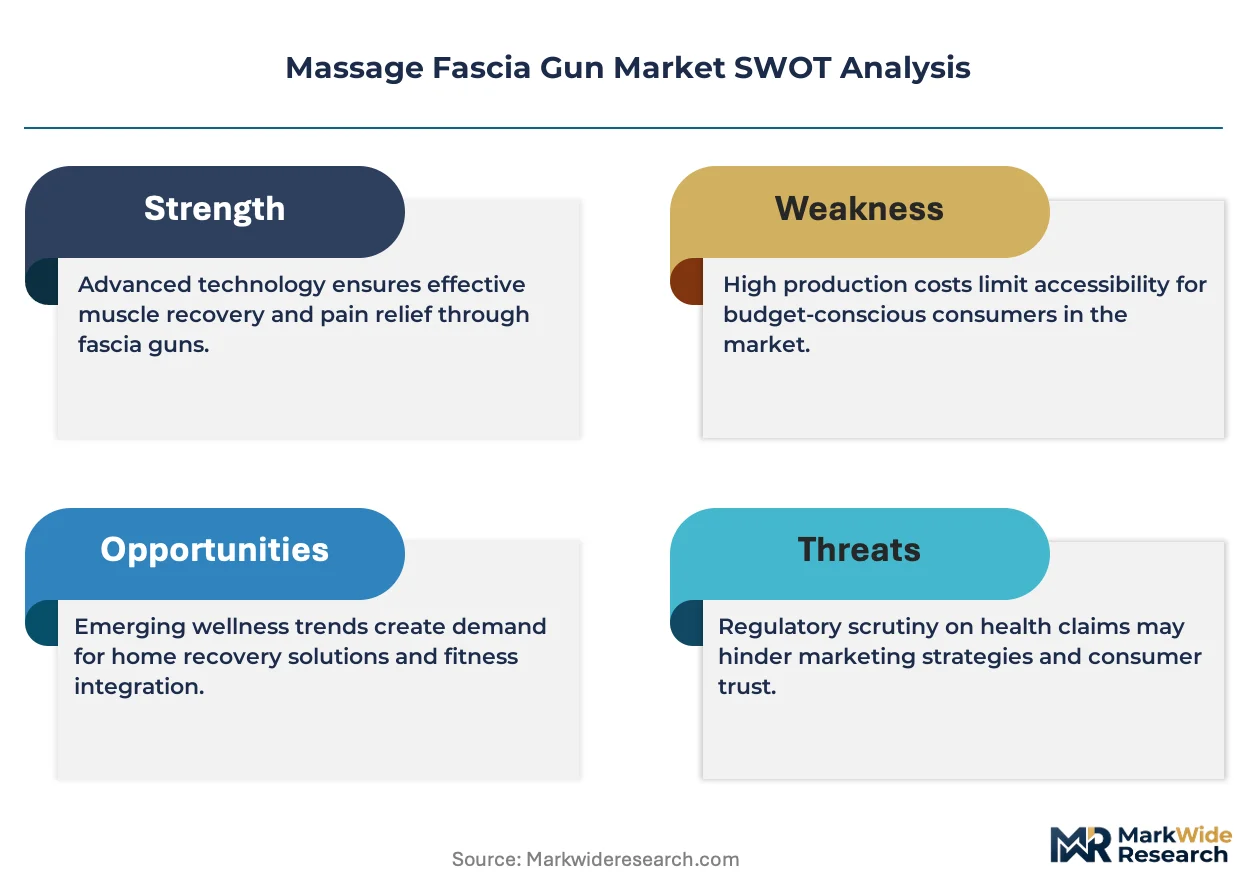
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and connected-feature depth. FDA Class II medical device registration and app-integrated treatment protocols command 3-4x multiples over unbranded budget units. Cost compression in the mid-range tier is intensifying because direct-to-consumer brands bypass retail margin extraction. Fitness enthusiasts exhibit highest price sensitivity, while physical therapy practices absorb premiums for liability protection.
Supply Chain Analysis
Hazmat surcharges on lithium-cell air freight are restructuring cross-border fulfillment economics toward ocean-bulk and regional assembly hubs. Neodymium magnet processing draws from Chinese facilities, while brushless motor controllers source from Japanese and South Korean IP holders. Single-source vulnerability in rare-earth magnet supply exposes assemblers to export quota volatility. Distribution runs through boutique fitness studio chains and sports medicine clinics for fleet orders, with Amazon and direct-to-consumer channels serving individual purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on algorithmic performance differentiation and repairable-design compliance that extends replacement cycles and unlocks subscription revenue streams.
For Market Incumbents: Lock in clinical certification pipelines to create switching costs that bind physical therapy practices and NCAA athletic programs to validated suppliers. Deepen upstream control over brushless motor controller IP through licensing negotiations with Japanese and South Korean patent holders. Defend against emerging direct-to-consumer specification competitors by accelerating app-ecosystem development for treatment logging and remote therapist oversight.
For New Entrants and Emerging Players: Quasi-sinusoidal amplitude control algorithms offer a technology-first wedge into university athletic programs piloting load-managed rehabilitation protocols. Target Germany's wireless-priority home user segment where EU Ecodesign repairability mandates favor modular, serviceable designs over sealed disposable units. Pursue white-label partnerships with European fitness equipment distributors screening for sustainability compliance.
For Investors and Strategic Acquirers: Valuations sit cheapest among direct-to-consumer brands with owned-channel distribution infrastructure and extended warranty programs that reduce lifetime replacement rates. Long-term viability over a 5-10 year window favors assemblers with Indian PLI scheme manufacturing footprints and pre-certified EU MDR regulatory affairs capacity. Monitor FDA Class II medical device registration timelines as inflection indicators for institutional buyer consolidation toward validated suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Certification Pipeline Investment | FDA Class II pathways lock physical therapy practices into recurring replacement cycles with validated suppliers. |
| App-Integrated Treatment Ecosystem Development | Bluetooth-enabled firmware upgradeability extends functional lifespan and commands margin premiums from home users. |
| EU MDR Pre-Certification Compliance | CE marking and technical documentation submission accelerates supplier roster consolidation among European distributors. |
| Modular Repairable Design Adoption | Standardized battery interfaces and motor housings satisfy EU Green Deal mandates and reduce warranty service costs. |
| Indian PLI Manufacturing Relocation | Contract assembly in Indian SEZs reduces landed cost for price-sensitive Asian markets while satisfying local content requirements. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and Australia, with primary inputs from each regional cluster. The research combines structured interviews with physical therapy practice owners, sports medicine clinic procurement managers, boutique fitness studio chain operators, brushless motor controller engineers, and lithium-polymer cell suppliers. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation databases, IATA lithium-cell shipping guidelines, and SEC filings of publicly traded recovery technology developers. Bottom-up shipment estimates by price tier and end-user segment triangulate against top-down market sizing derived from distributor revenue disclosures.
Granularity-level modeling disaggregates volume and value across the projection horizon by product type, end user, technology, and price tier, with additional cross-tabulation by regional regulatory cluster and channel structure. CAGRs derive from logistic growth curve fitting to historical replacement cycle data and institutional procurement pattern analysis. Industry-specific forecast inputs include NCAA athletic program equipment refresh schedules, EU Ecodesign implementation timelines, and IATA lithium-cell restriction evolution scenarios.
The model holds under stable regulatory certification pathways and continued brushless motor cost-down curves; deviation in rare-earth export quotas or accelerated EU repairability enforcement would shift volume concentration toward pre-certified, modular-design suppliers. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Europe and MEA Condom Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
Shaving Market
Personal Grooming Products
360 Degree Toothbrush Market
Personal Grooming Products
Infant Mosquito Repellent Market
Personal Grooming Products
Europe Hair Styling Tools Market
Personal Grooming Products
Global Consumer Use IPL Hair Removal Devices Market
Personal Grooming Products
Facial Hair Care Wipes Market
Personal Grooming Products
Razor Blade Market
Personal Grooming Products
Personal Lubricants Market
Personal Grooming Products
Smart Hairbrush Market
Personal Grooming Products
Mexico Beard Trimmer Market
Personal Grooming Products
Disposable Shower Caps Market
Personal Grooming Products
Disposable Razor Market