
 North America Hair Styling Tools Market | 2026-2036
North America Hair Styling Tools Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hair Styling Tools Market Analytics
Mexican manufacturing capacity for ceramic heating elements is hardening as a critical supply node for North American brands. Conair Corporation leverages its vertically integrated production network across the U.S. Southeast to sustain margin control on flat iron assemblies. Helen of Troy Limited anchors its competitive stance through concentrated R&D spending on ionic technology platforms. Dyson Ltd. differentiates via patented airflow engineering that commands premium positioning in professional channels.
Hair styling tools encompass electrically powered devices engineered to apply controlled thermal energy to hair fibers, typically operating at temperatures between 250°F and 450°F through resistive heating elements coated in ceramic or tourmaline composites, with the primary commercial purpose of enabling temporary structural modification to keratin strands for aesthetic or professional styling outcomes. Professional salons dominate volume demand for premium-tier flat irons and curling wands, while home users drive replacement frequency in the budget and mid-range hair dryer categories. Ionic technology captures expanding share as consumers prioritize frizz reduction claims, though infrared platforms remain niche due to higher unit costs and limited stylist familiarity.
The U.S. Consumer Product Safety Commission enforces electrical safety standards that mandate UL certification for corded appliances, while Health Canada requires CSA Group testing for products entering Canadian distribution channels. The U.S. FDA maintains oversight of claims related to hair damage reduction or scalp health benefits, constraining marketing language for ceramic and tourmaline technologies. Stakeholders must monitor evolving state-level energy efficiency mandates in California and New York, as these jurisdictions typically prefigure broader North American regulatory trajectories for small appliance power consumption limits.
Market Dynamics
Professional salons across the United States and Canada are compressing tool refresh cycles as stylists prioritize ceramic and tourmaline heating technologies, while Mexican manufacturing capacity for ceramic heating elements hardens as a critical supply node for North American brands.
Growth Catalysts
- UL Certification Mandate:The U.S. Consumer Product Safety Commission enforces electrical safety standards that mandate UL certification for corded appliances, pressuring manufacturers toward compliance investments that elevate category quality floors.
- California and New York Metro Demand:Dense salon networks and premium beauty retail in these metropolitan areas drive premium-tier uptake, concentrating volume demand for professional-grade flat irons and curling wands.
- Ionic Technology Platforms:Concentrated R&D spending on ionic technology captures expanding share as consumers prioritize frizz reduction claims, displacing conventional heating element specifications in mid-range and premium segments.
Market Restraints
- Ceramic Heating Element Supply Concentration:Mexican manufacturing capacity hardens as a critical supply node, creating geographic concentration risk for North American brands dependent on cross-border component flows.
- Infrared Platform Cost Barriers:Higher unit costs and limited stylist familiarity constrain infrared platform penetration, relegating this technology to niche professional applications despite superior thermal efficiency claims.
- FDA Marketing Constraints:The U.S. FDA maintains oversight of claims related to hair damage reduction or scalp health benefits, constraining marketing language for ceramic and tourmaline technologies and limiting differentiation vectors.
Strategic Opportunities
- State-Level Energy Efficiency Prefiguration:California and New York energy efficiency mandates for small appliance power consumption limits typically prefigure broader North American regulatory trajectories, creating first-mover advantage for compliant product lines.
- Home User Replacement Frequency:Home users drive replacement frequency in budget and mid-range hair dryer categories, representing volume expansion potential through channel diversification into mass retail and direct-to-consumer platforms.
- CSA Group Testing Alignment:Health Canada requirements for CSA Group testing create parallel certification pathways that, when synchronized with UL processes, enable streamlined North American market access.
Industry Challenges
- Dual Certification Timeline Compression:Simultaneous UL and CSA Group certification requirements create extended compliance timelines, delaying product launches and compressing effective sales windows for seasonal styling tool introductions.
- Tourmaline Composite Sourcing Complexity:Securing consistent tourmaline composite supply for resistive heating element coating requires qualification of alternative suppliers, adding procurement friction and quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hair Styling Tools Market |
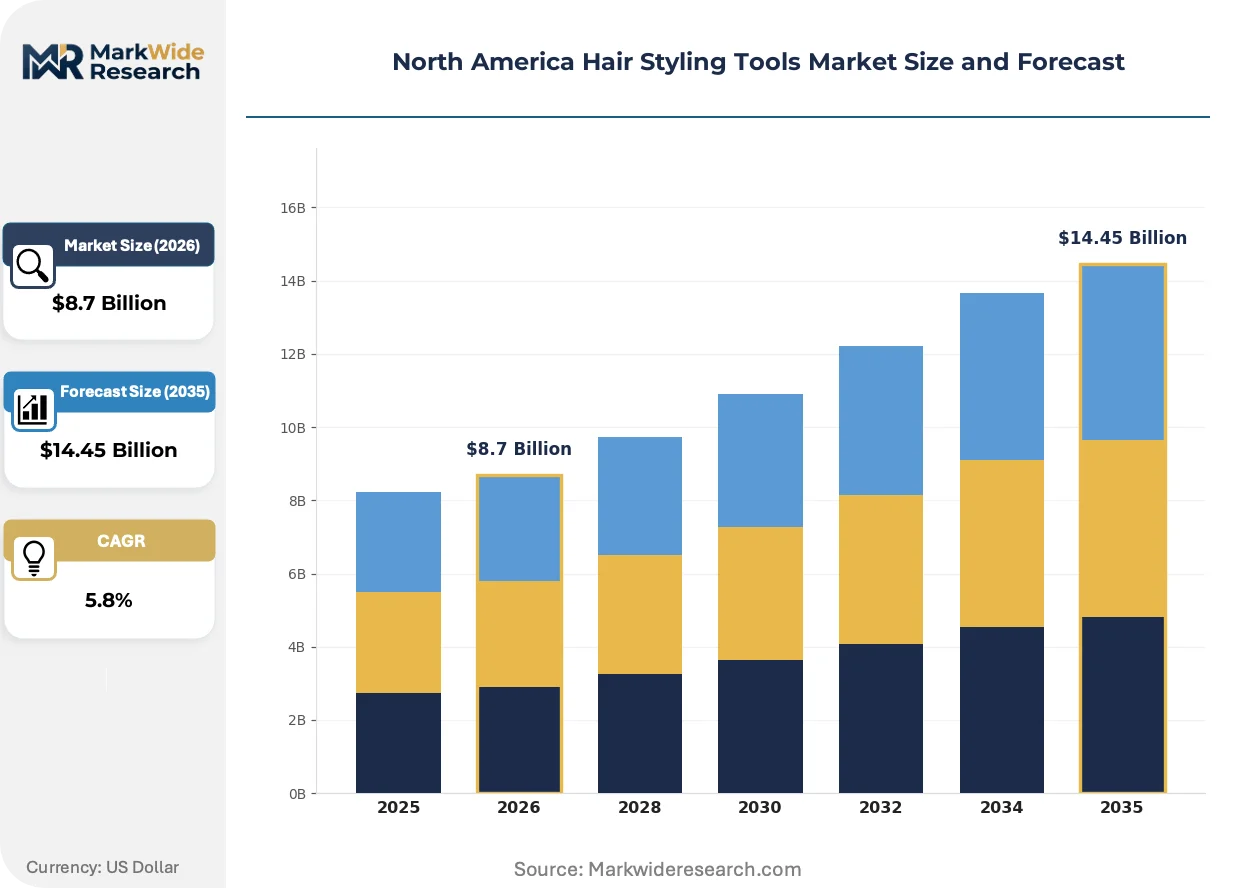
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Dryers, Flat Irons, Curling Wands, Hot Rollers End User: Professional Salons, Home Users, Cosmetology Schools, Beauty Enthusiasts Technology: Ionic, Infrared, Ceramic, Tourmaline Price Tier: Premium, Mid-range, Budget, Value |
| Companies Covered | Conair Corporation, Helen of Troy Limited, Spectrum Brands, Inc., Andis Company, Revlon, Koninklijke Philips N.V., Panasonic Corporation, Wahl Clipper Corporation, Dyson Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hair Styling Tools Market Evolving Landscape
Patented airflow engineering and ionic technology platforms are actively reshaping competitive positioning in professional channels, while regulatory pressure on power consumption and safety certification elevates technical barriers to market entry.
Ceramic-tourmaline composite heating elements are unifying thermal distribution performance with frizz-reduction claims in professional-grade flat irons. Premium salons in California and New York metropolitan areas are adopting these hybrid platforms at accelerated refresh cycles. This convergence is unifying previously separate product categories—pure ceramic and pure tourmaline tools—into single SKUs that command price premiums while reducing inventory complexity for distributors.
The U.S. Consumer Product Safety Commission maintains active oversight of electrical appliance safety standards with escalating enforcement attention on corded appliance thermal runaway risks. Manufacturers are responding with redundant thermostat engineering and enhanced cord strain relief designs that extend development cycles. Professional-grade flat irons and curling wands face the steepest compliance burden, as these categories operate at the upper temperature boundaries of consumer electrical safety thresholds.
Salon procurement patterns are fragmenting across direct brand relationships, professional beauty distributors, and e-commerce platforms, compressing traditional channel margins. Independent stylists in Texas and Florida metropolitan clusters are bypassing legacy professional distributors for manufacturer-direct purchasing with volume discount structures. This disintermediation is most visible in mid-range hair dryer categories, where home user price sensitivity and professional durability requirements create hybrid specification demands.
North America Hair Styling Tools Market Segmentation
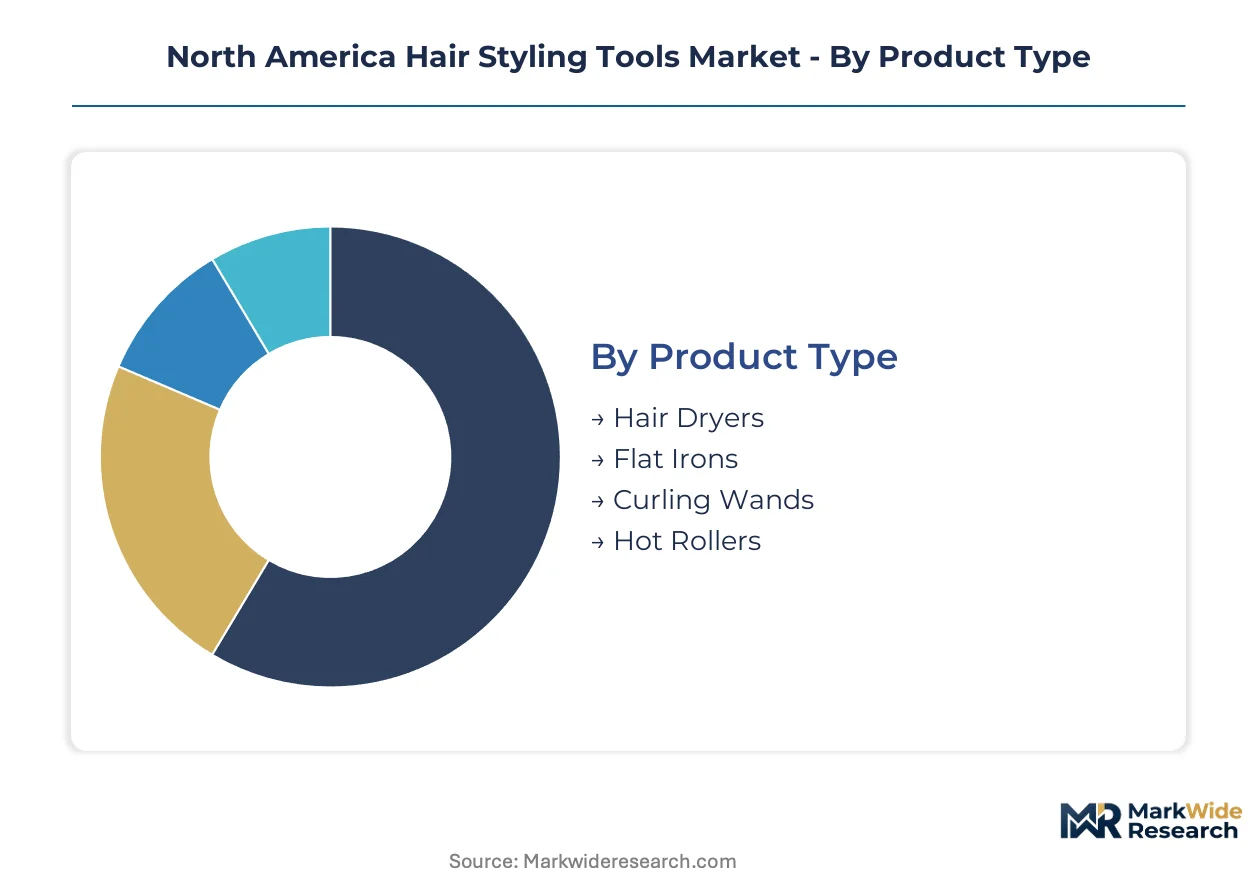
Segmentation in hair styling tools reveals how thermal engineering specifications, end-use durability requirements, and channel economics fragment demand across distinct purchasing behaviors. Professional salons prioritize temperature precision and component longevity, while home users trade thermal performance for accessibility and price points.
Product Type:
Ceramic and tourmaline heating specifications differentiate commercial performance across device categories, with thermal distribution uniformity and frizz reduction claims driving specification divergence.
- Hair Dryers:Resistive heating elements combined with fan assemblies generate airflow temperatures between 140°F and 180°F. Home users in California and New York metropolitan areas drive replacement cycles for mid-range units with ionic technology integration.
- Flat Irons:Ceramic-tourmaline composite plates apply direct thermal contact at 250°F to 450°F operating ranges. Professional salons in Texas and Florida bypass distributors for manufacturer-direct procurement of premium-tier units with redundant thermostat engineering.
- Curling Wands:Barrel-shaped heating elements enable temporary structural modification through controlled thermal exposure. Budget-tier units concentrate in mass retail channels serving home user price sensitivity.
- Hot Rollers:Resistive heating cores within cylindrical forms deliver gradual thermal conditioning for volume styling. Limited stylist familiarity constrains penetration outside cosmetology school training environments.
Hair dryers lead on scale; flat irons lead on momentum.
End User:
Purchasing authority and durability requirements segment demand across institutional procurement patterns and individual consumption behaviors.
- Professional Salons:Commercial operators prioritize UL-certified equipment with extended duty cycles and component serviceability. Dense salon networks in California and New York drive premium-tier flat iron and curling wand uptake.
- Home Users:Individual consumers prioritize price accessibility and compact storage dimensions over thermal precision specifications. Replacement frequency concentrates in budget and mid-range hair dryer categories through mass retail and direct-to-consumer channels.
- Cosmetology Schools:Training institutions procure standardized equipment portfolios for curriculum consistency across multiple student users.
- Beauty Enthusiasts:Hobbyist segment exhibits hybrid specification demands bridging professional performance claims with home user price thresholds.
Professional salons command margin; home users command volume.
Technology:
Heating element composition and supplemental emission properties define functional differentiation and marketing claim substantiation boundaries.
- Ionic:Negative ion emission systems reduce static charge accumulation on keratin strands. Expanding consumer prioritization of frizz reduction claims is displacing conventional heating specifications in mid-range and premium segments.
- Ceramic:Aluminum oxide-based resistive coatings distribute thermal energy with reduced hot spot formation. Mexican manufacturing capacity for ceramic heating elements hardens as critical supply infrastructure for North American assembly operations.
- Infrared:Far-infrared emission claims superior thermal efficiency through deeper strand penetration. Higher unit costs and limited stylist familiarity relegate this platform to niche professional applications.
- Tourmaline:Crystalline boron silicate mineral coatings combine ionic emission with ceramic thermal distribution. FDA oversight of hair damage reduction claims constrains marketing language differentiation for this composite technology.
Ceramic leads on scale; ionic leads on momentum.
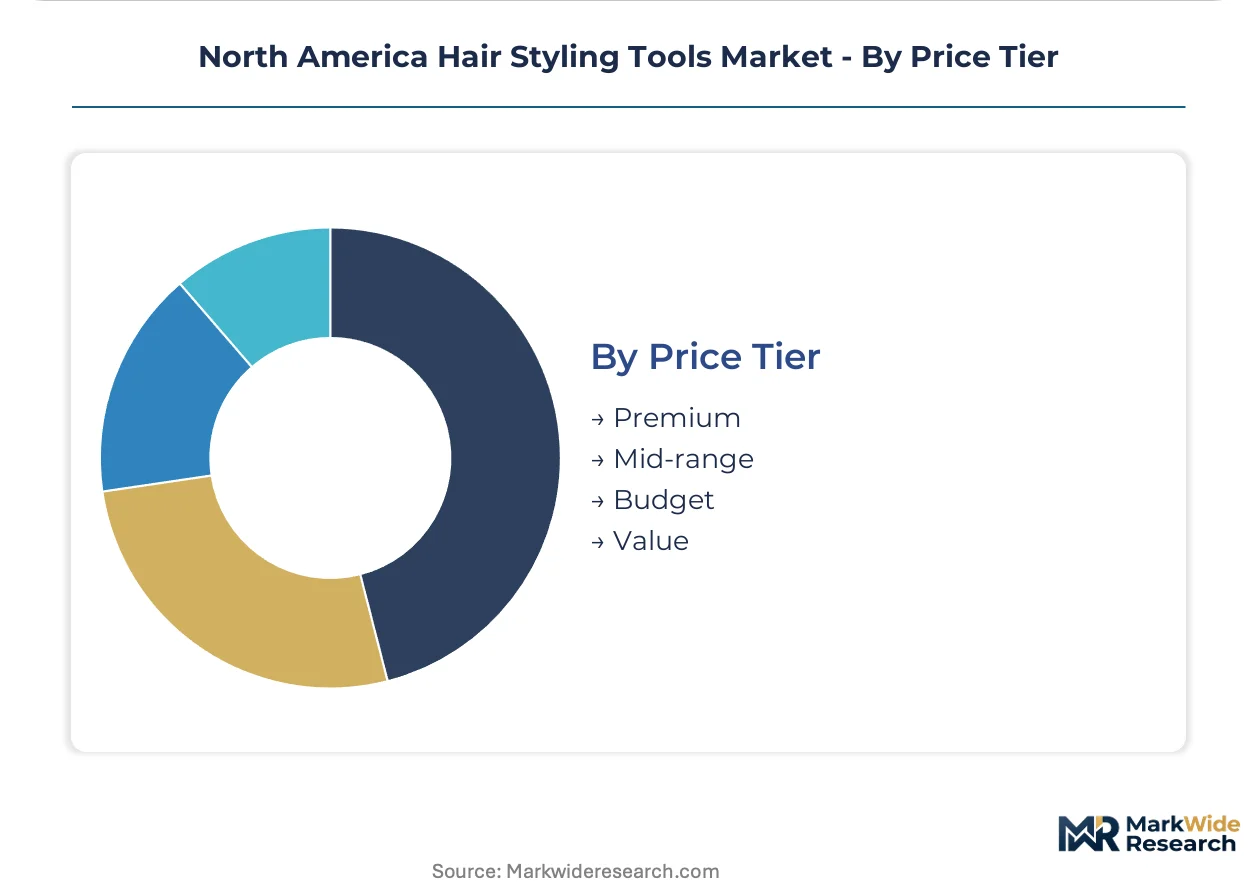
Price Tier:
Certification grade, component sourcing, and channel margin structures stratify accessible price positions.
- Premium:Patented airflow engineering and hybrid ceramic-tourmaline specifications command professional channel positioning. Dyson and Helen of Troy R&D investments anchor this tier through concentrated technology platform development.
- Mid-range:Ionic technology integration at accessible price points captures expanding home user demand. Conair vertically integrated production networks sustain margin control across this volume-heavy segment.
- Budget:Basic resistive heating without supplemental emission technologies serves mass retail price floors. Replacement frequency concentrates here for home user hair dryer categories.
- Value:Entry-tier positioning with minimal feature differentiation targets first-time purchasers and temporary use scenarios.
Mid-range leads on scale; premium leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers exploit regulatory-arbitrage gaps between jurisdictions, migrating component production toward lower-compliance-cost zones while maintaining UL certification for finished goods assembly in higher-margin markets. This geographic stratification concentrates ceramic heating element fabrication in Mexican industrial corridors while final-tool assembly and safety testing anchor in the United States and Canada.
United States
California and New York metropolitan areas concentrate dense salon networks and premium beauty retail, driving professional-grade flat iron and curling wand procurement. The U.S. Consumer Product Safety Commission enforces escalating UL certification mandates for corded appliances with thermal runaway protections. Texas and Florida stylist clusters increasingly bypass legacy distributors for manufacturer-direct purchasing with volume discount structures.
Canada
Health Canada requires CSA Group testing for all electrical appliances entering Canadian distribution, creating parallel certification pathways that synchronize with UL processes. Ontario and Quebec host concentrated professional salon networks importing premium-tier equipment through cross-border professional beauty distributors. Toronto and Vancouver anchor procurement hubs serving Pacific Northwest and Great Lakes stylist populations.
Mexico
Mexican manufacturing capacity for ceramic heating elements hardens as critical supply infrastructure for North American assembly operations. The Secretariat of Economy oversees maquiladora programs that attract component fabrication investment from U.S. and Canadian brands seeking tariff-advantaged production. Baja California and Chihuahua industrial corridors host heating element coating facilities serving cross-border just-in-time delivery schedules.
California
State-level energy efficiency mandates for small appliance power consumption limits prefigure broader North American regulatory trajectories, pressuring manufacturers toward compliant product line development. Los Angeles and San Francisco metropolitan salon density drives premium-tier ionic technology uptake. The California Energy Commission maintains active rulemaking on standby power limits for corded styling devices.
New York
Manhattan and Brooklyn professional salon clusters exhibit accelerated tool refresh cycles prioritizing ceramic-tourmaline composite specifications. The New York State Department of State enforces consumer protection standards that complement federal UL requirements. Upstate distribution centers serve as consolidation points for professional beauty supply chains reaching New England and Mid-Atlantic markets.
North America Hair Styling Tools Market Competitive Landscape
U.S. producers anchor the premium tier through concentrated R&D investment; Mexican and Asian fabricators hold component supply and mid-range assembly. The vendor base stratifies across three tiers: multinational appliance conglomerates with diversified personal care portfolios, vertically integrated specialists controlling heating element supply chains, and contract manufacturers serving private-label retail programs. Competitive moves concentrate on backward integration into ceramic component production and strategic partnerships with professional salon distributors to secure specification lock-in.
Within the multinational conglomerate tier, Koninklijke Philips N.V. and Panasonic Corporation exemplify diversified appliance portfolios spanning professional and consumer channels. Among vertically integrated specialists, Conair Corporation occupies a position representing captive production network control, while Dyson Ltd. anchors premium-tier positioning through patented engineering differentiation. Helen of Troy Limited exemplifies concentrated R&D investment in ionic technology platforms. These archetypes represent distinct strategic postures: scale-driven manufacturing efficiency, technology-driven premium pricing, and brand-driven channel penetration.
| Leading Market Players |
|---|
| Conair Corporation |
| Helen of Troy Limited |
| Spectrum Brands, Inc. |
| Andis Company |
| Revlon |
| Koninklijke Philips N.V. |
| Panasonic Corporation |
| Wahl Clipper Corporation |
| Dyson Ltd. |
| Others |
Value Network & Pricing Analysis
Professional salon procurement clusters in California and New York metropolitan areas anchor North American pricing power, compressing channel margins as stylists bypass legacy distributors for manufacturer-direct volume structures. This buyer concentration forces three-tier pricing stratification across premium ceramic-tourmaline specifications, mid-range ionic platforms, and basic resistive heating units.
Pricing Analysis
Distributor margin compression in legacy professional beauty supply chains is accelerating price erosion across mid-range hair dryer categories, while direct-to-salon discount structures protect premium flat iron pricing. Certification grade and volume scale separate premium UL-certified professional equipment from budget mass retail offerings. Cost compression in budget tiers intensifies because Mexican component sourcing faces cross-border logistics friction. Home users in mass retail channels exhibit highest price sensitivity; professional salons demonstrate lowest sensitivity due to durability requirements and specification lock-in.
Supply Chain Analysis
Regional distribution centers in Texas and Florida operate as hub-and-spoke consolidation points for professional beauty supply chains reaching stylist clusters across the Southeast and Southwest. Ceramic heating element fabrication concentrates in Mexico, with final assembly and UL certification testing anchoring in the United States and Canada. Raw material dependencies include aluminum oxide ceramic coatings, tourmaline composite minerals, and copper resistive wiring. Single-source vulnerability in Mexican ceramic component supply creates geographic concentration risk. Distribution runs through professional beauty distributors, mass retail chains, and manufacturer-direct e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
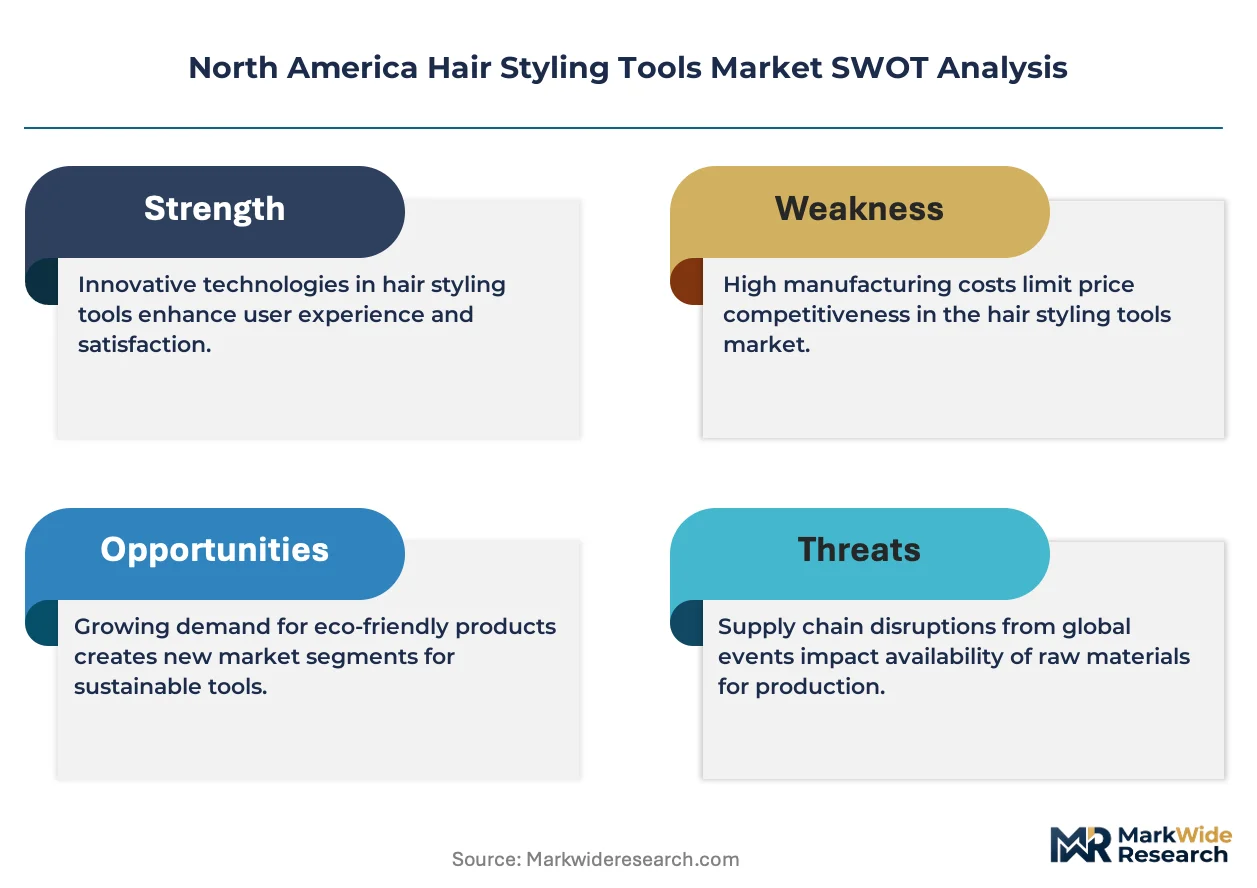
North American hair styling tools constitute a late-cycle quality story as professional salon refresh cycles accelerate toward ceramic-tourmaline hybrid specifications. This specification upgrade trajectory elevates technical barriers and consolidates procurement authority among R&D-capable incumbents.
For Market Incumbents: Lock in ceramic heating element supply through captive production or long-term offtake agreements with Mexican fabricators, insulating against cross-border tariff exposure and component scarcity. Extend redundant thermostat engineering capabilities to meet escalating UL thermal runaway standards, converting compliance burden into specification lock-in against emerging competitors lacking certification infrastructure. For New Entrants and Emerging Players: Begin with infrared platform specialization targeting niche professional applications in Texas and Florida metropolitan clusters, where stylist familiarity gaps create white-space opportunity despite higher unit costs. Pursue direct-to-stylist e-commerce positioning with volume discount structures that bypass legacy distributor margin extraction, capturing independent stylist procurement fragmentation. For Investors and Strategic Acquirers: Vertically integrated personal care conglomerates represent the most active acquirer category in this space, seeking ceramic component supply chain control and professional channel specification authority. Acquisition targets should exhibit captive Mexican heating element production and established UL certification pathways. Watch California Energy Commission standby power rulemaking as inflection signal for regulatory-driven product line obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Component Backward Integration | Mexican maquiladora production control secures margin and supply continuity against tariff volatility. |
| Dual UL-CSA Certification Synchronization | Parallel testing alignment accelerates North American market access and compresses launch timelines. |
| Direct-to-Stylist E-Commerce Launch | Volume discount structures capture Texas and Florida procurement fragmentation bypassing distributors. |
| Ionic Technology Platform Extension | Frizz reduction claims displace conventional specifications in mid-range and premium segments. |
| Energy Efficiency Compliance Prepositioning | California standby power standards prefigure broader regulatory trajectories requiring product redesign. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with salon owners, professional beauty distributor procurement managers, ceramic heating element plant engineers, and UL certification compliance officers with secondary validation. Trade data from U.S. Customs and Border Protection, FDA marketing claim filings, California Energy Commission rulemaking dockets, and professional beauty industry association reports anchored volume estimates. Bottom-up salon equipment procurement surveys and top-down appliance manufacturing output triangulation verified segment sizing.
Historical reference periods spanning pre-pandemic baseline through post-recovery normalization anchored the projection horizon across the analysis window. Segmentation dimensions modeled include product type, end user category, heating technology platform, and price tier. CAGRs derived from regression analysis against macroeconomic indicators and industry-specific demand drivers including salon network expansion rates, tool refresh cycle compression, and regulatory compliance cost trajectories.
Several conditions sit outside the modeled scope, including abrupt tariff regime changes affecting Mexican component flows, breakthrough heating technologies displacing ceramic-tourmaline platforms, and salon industry consolidation altering procurement authority structures. Forecasts reflect documented assumptions about regulatory trajectory continuity and supply chain geographic stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Self-Tanning Products Market
Personal Grooming Products
Back Massager Market
Personal Grooming Products
Gel Socks Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Organic and Natural Tampons Market
Personal Grooming Products
Heated Razor Starter Kit Market
Personal Grooming Products
Asia Pacific Hair Styling Tools Market
Personal Grooming Products
Disposable Razor Blades Market
Personal Grooming Products
Disposable Slippers Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
North America Mosquito Repellent Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
Insoles Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Smart Electric Toothbrush Market