
 Motor Gear Unit Market | 2026-2036
Motor Gear Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Gear Unit Market Foresight
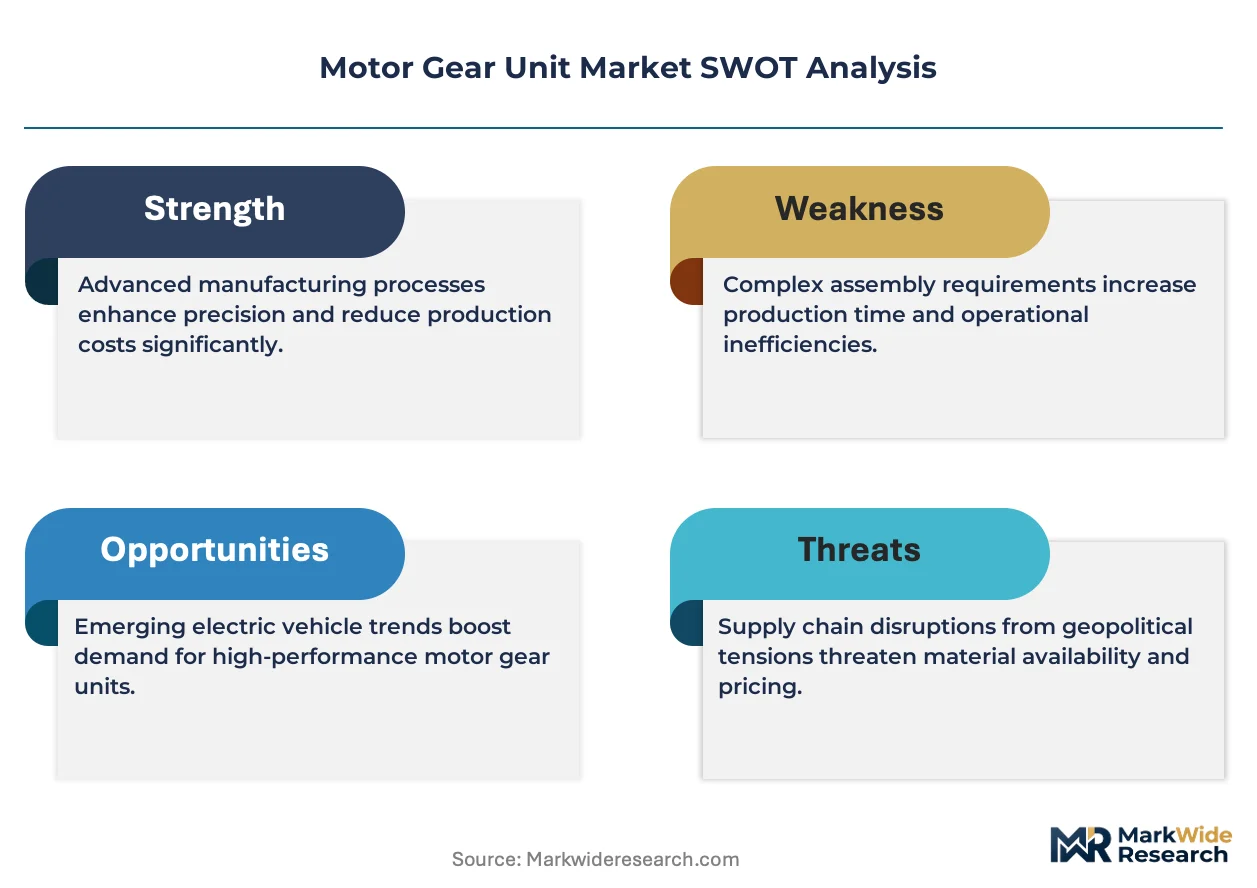
Multi-source procurement for precision gear components is decoupling from the single-supplier models that historically dominated industrial drivetrain sourcing. SEW-Eurodrive leverages its integrated manufacturing footprint in Germany to control quality across helical and bevel gear lines. Nidec anchors its position through high-R&D intensity in compact electric gear motor architectures for robotics and conveyor applications. Bonfiglioli differentiates via specialized marine and wind energy gear systems that sustain premium positioning in renewable energy installations.
A motor gear unit combines an electric motor with a speed-reduction gearbox to deliver controlled torque and rotational speed to driven machinery, typically achieving ratios from 5:1 to over 10,000:1 depending on gear stage configuration. Helical gear arrangements dominate industrial equipment applications due to their high load capacity and smooth meshing characteristics that reduce noise and vibration in continuous-duty environments. Worm gear configurations retain strong positions in conveyor systems and material handling where high reduction ratios in compact footprints justify lower mechanical efficiency. Electric technology leads the technology segmentation as plant electrification displaces hydraulic power transmission in manufacturing and aerospace ground support equipment.
The EU F-Gas Regulation and REACH compliance frameworks shape material selection and lubricant chemistry for gear units sold into European manufacturing and marine end uses. ISO 6336 and AGMA 2001 standards govern load capacity calculations and safety factors that determine product certification for industrial gear drives. China's GB standards and MIIT efficiency mandates impose minimum performance thresholds on gear motor assemblies imported or manufactured domestically. Stakeholders must monitor how carbon border adjustment mechanisms and regional content requirements recalibrate sourcing decisions for multinational industrial equipment supply chains.
Market Dynamics
Warehouse automation and electrification mandates are restructuring motor gear unit procurement, compressing supplier lead times while expanding performance certification requirements across industrial drivetrain specifications.
Growth Catalysts
- EU F-Gas Regulation:Industrial efficiency codes tighten energy performance thresholds for electromechanical power transmission equipment, forcing plant upgrades across German manufacturing clusters.
- Helical gear architectures:High load capacity and smooth meshing characteristics reduce noise in continuous-duty environments, accelerating replacement cycles in automotive OEM supply chains.
- China:GB standards and MIIT efficiency mandates impose minimum performance thresholds on gear motor assemblies, stimulating domestic production capacity expansion.
Market Restraints
- Specialized alloy supply:Concentration in rare earth magnet processing creates input cost volatility for compact electric gear motor architectures.
- Worm gear efficiency ceiling:Lower mechanical efficiency versus helical alternatives caps penetration in energy-intensive continuous-duty applications.
- REACH compliance friction:Lubricant chemistry restrictions extend product development timelines for European marine and manufacturing end uses.
Strategic Opportunities
- India:PLI scheme incentives for domestic manufacturing equipment create procurement windows for precision gear component suppliers.
- Robotics integration:Compact electric gear motor demand from collaborative robot arm manufacturers outpaces existing supplier capacity.
- Outcome-based maintenance contracts:Sensor-enabled predictive service models displace traditional break-fix arrangements in German automotive assembly plants.
Industry Challenges
- ISO 6336 certification backlog:Third-party load capacity testing capacity constraints delay product launches for industrial gear drive manufacturers.
- Legacy hydraulic system integration:Retrofit complexity with existing plant infrastructure extends sales cycles for electrification projects.
- Gear cutting specialist scarcity:Precision machining workforce gaps constrain output expansion at mid-tier European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Gear Unit Market |
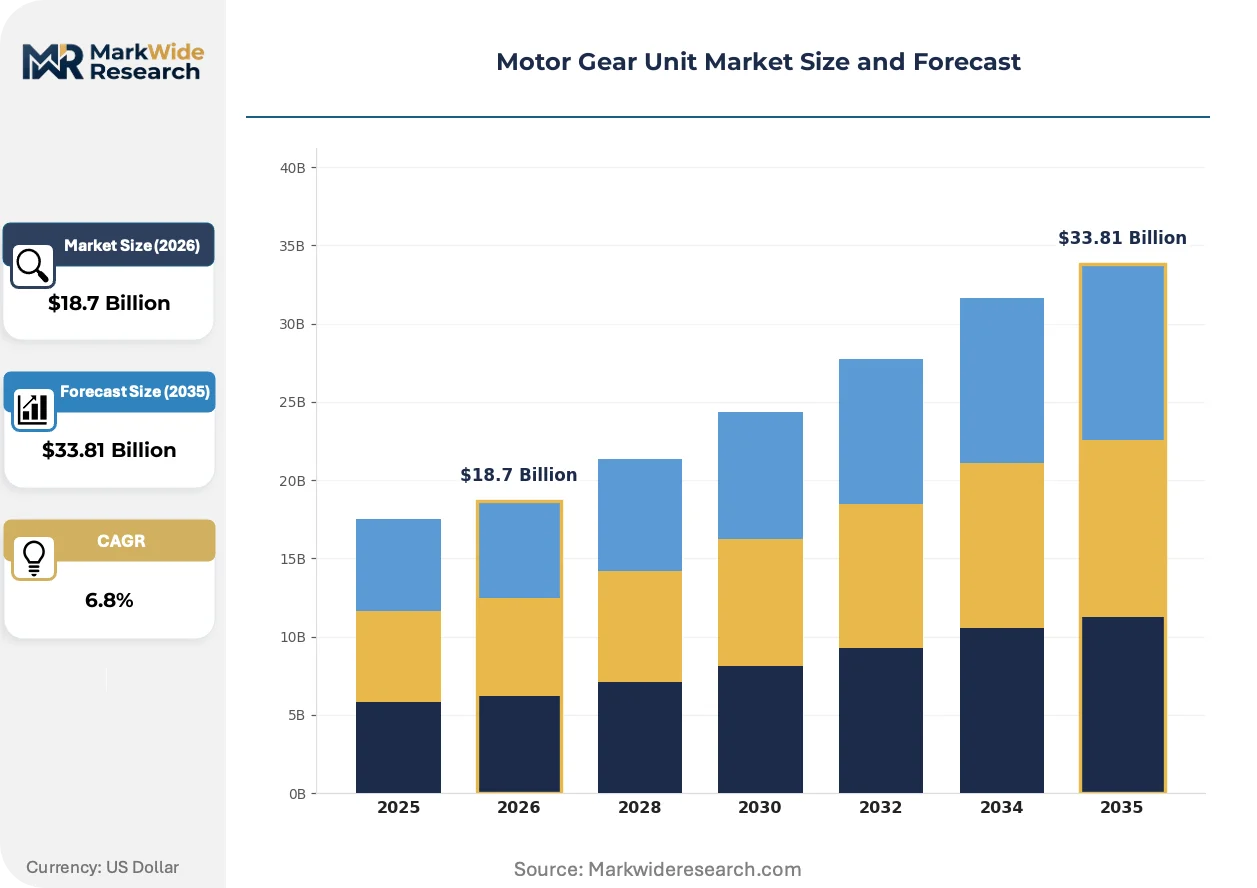
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bevel Gear, Helical Gear, Worm Gear, Spur Gear Application: Automotive, Robotics, Conveyor Systems, Industrial Equipment End User: Manufacturing, Aerospace, Marine, Renewable Energy Technology: Electric, Hydraulic, Pneumatic, Mechanical |
| Companies Covered | Regal Rexnord, Nidec, SEW-Eurodrive, Dana Industrial, Nord Drivesystems, Sumitomo Heavy Industries, Bonfiglioli, Elecon Engineering, Flender, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Gear Unit Market Shifts & Advancements
Digitalization of condition monitoring and servomotor integration are compressing traditional gearbox-motor boundaries, while regulatory pressure on lubricant chemistry accelerates material science investment.
Integrated sensor arrays embedded in gear housings enable real-time vibration and temperature monitoring, transmitting data to plant control systems via industrial Ethernet protocols. Food processing and pharmaceutical manufacturers adopt these configurations fastest, driven by zero-downtime requirements and batch traceability mandates. The technology is integrating predictive maintenance workflows directly into OEM service offerings, compressing aftermarket revenue pools for independent repair providers.
REACH restrictions on mineral oil-based lubricants force reformulation toward synthetic esters and polyalkylene glycols with superior biodegradability profiles. Gear unit manufacturers serving European marine and wind energy installations face extended validation cycles for new lubricant chemistries. German precision manufacturers are responding by qualifying multiple lubricant suppliers per product line to mitigate approval timeline risk.
Modular servo-gearmotor platforms allow torque and speed reconfiguration through software parameter changes rather than mechanical ratio swaps. Machine tool builders and packaging OEMs in Japan and Germany leverage this flexibility to reduce spare inventory holdings and accelerate line changeovers. The shift is most visible in high-mix, low-volume production environments where batch sizes compress below traditional gearbox economic order quantities.
Motor Gear Unit Market Segmentation
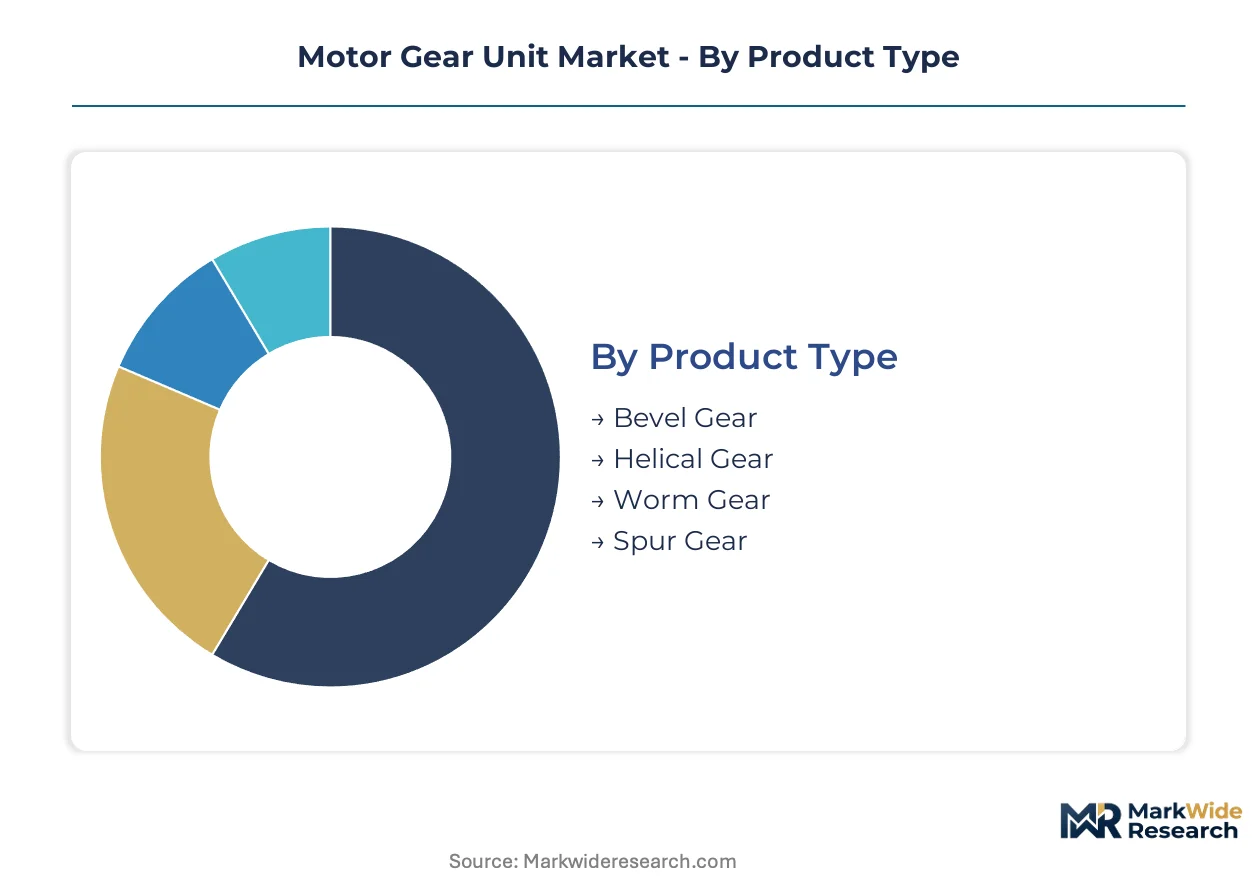
Motor gear unit procurement patterns diverge sharply across product architectures and end-use applications. Supply chain configuration and certification requirements create distinct competitive dynamics within each segment category.
Product Type:
Supply concentration for precision gear cutting capacity shapes competitive positioning across gear architectures.
- Helical Gear:Angled tooth geometry enables gradual tooth engagement that distributes load across multiple teeth simultaneously. German automotive OEM supply chains and continuous-duty manufacturing lines in Stuttgart and Wolfsburg anchor procurement volumes, driven by noise reduction mandates under EU machinery directives.
- Worm Gear:Screw-and-wheel mechanism achieves high reduction ratios in compact axial dimensions, trading mechanical efficiency for space economy. Warehouse automation clusters in the Ruhr Valley and conveyor system integrators sustain demand despite efficiency ceilings.
- Bevel Gear:Conical tooth geometry transmits power between intersecting shafts, serving right-angle drive configurations in packaging machinery.
- Spur Gear:Parallel-axis cylindrical teeth offer simplest manufacturing geometry for low-speed, high-torque applications in basic material handling.
Helical gear architectures absorb the bulk of installed capacity; worm gear configurations are expanding most quickly in e-commerce fulfillment automation.
Application:
End-use equipment specifications determine torque density requirements and certification complexity for gear unit suppliers.
- Conveyor Systems:Continuous-duty belt and roller drives demand high reliability with minimal maintenance intervals. German logistics hubs and automated distribution centers across Bavaria and North Rhine-Westphalia drive replacement cycles, pressured by F-Gas Regulation efficiency thresholds.
- Industrial Equipment:Machine tools, presses, and process machinery require precise speed-torque matching across variable load profiles. Tool builders in Japan's Aichi Prefecture and Germany's Baden-Württemberg cluster specify compact servo-integrated units.
- Automotive:Assembly line positioning systems and paint shop conveyors use standardized gear motor platforms with rapid spare parts availability.
- Robotics:Collaborative robot joints and linear actuators demand ultra-compact harmonic and planetary gear reductions with zero backlash.
Industrial equipment applications command the highest specification density; robotics integration is climbing the fastest as cobot deployment accelerates.
End User:
Customer procurement sophistication varies from commodity replacement purchasing to engineered system integration.
- Manufacturing:Discrete and process industries operate the largest installed base of gear motor assets. German automotive and machinery sectors dominate premium procurement, with REACH compliance and ISO 6336 certification as baseline requirements.
- Renewable Energy:Wind turbine pitch and yaw drives require extreme reliability under variable loading. North Sea offshore installations and Baltic coast projects specify marine-grade sealing and synthetic lubricant compatibility.
- Aerospace:Ground support equipment and manufacturing tooling demand lightweight, high-torque density units with traceable material certification.
- Marine:Propulsion auxiliaries and deck machinery face salt corrosion and vibration challenges, driving specialized housing designs.
Manufacturing absorbs dominant procurement volumes; renewable energy installations are gaining share fastest as wind capacity expands.
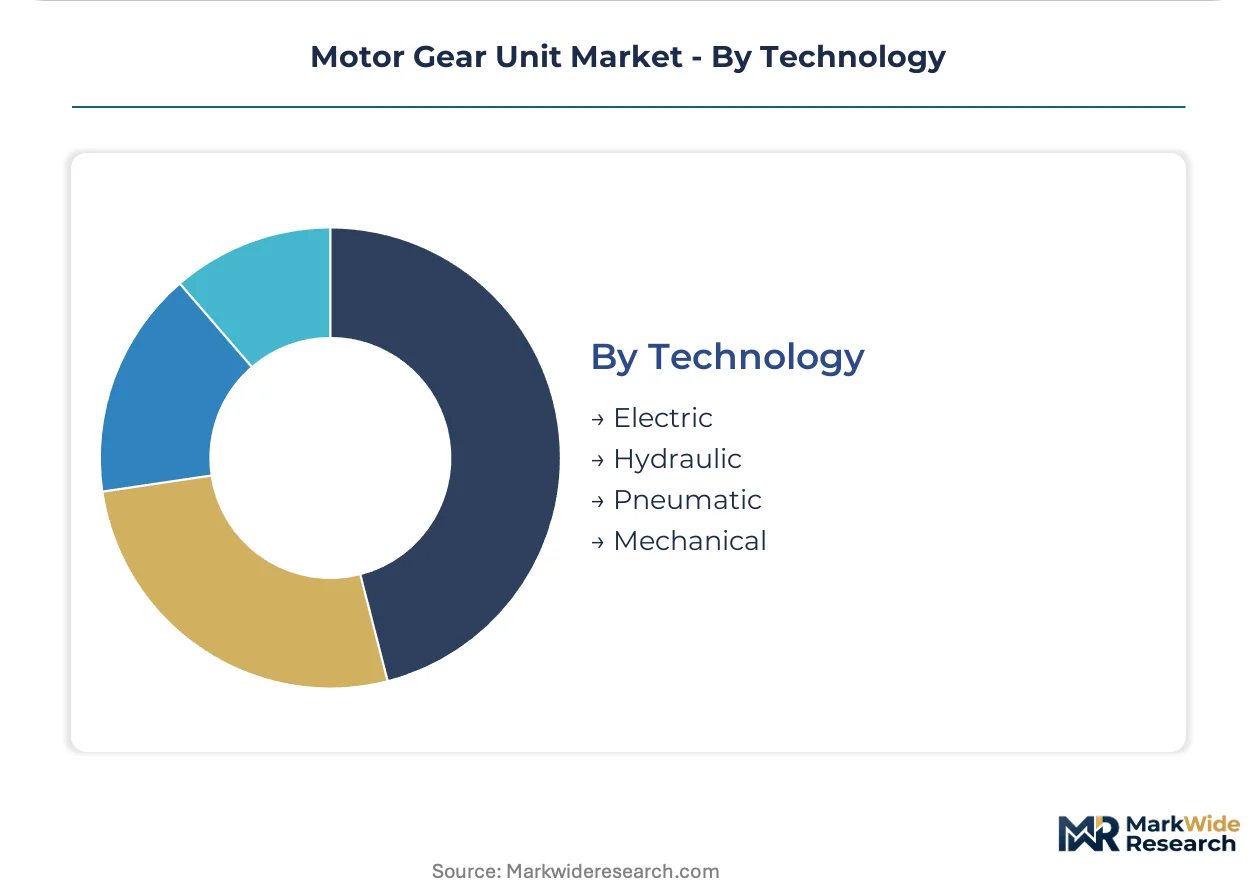
Technology:
Power transmission modality selection reflects plant electrification trajectories and legacy infrastructure constraints.
- Electric:AC induction and permanent magnet motor-gearbox combinations displace fluid power in most new installations. German plant electrification mandates and China's MIIT efficiency standards accelerate displacement of hydraulic alternatives in injection molding and metal forming.
- Hydraulic:High-force density fluid power retains position in heavy pressing and lifting applications where electric torque density remains insufficient.
- Pneumatic:Compressed air drives persist in explosive atmospheres and food-grade washdown environments where electric motor sealing costs escalate.
- Mechanical:Direct shaft coupling and belt reduction survive only in lowest-cost, fixed-speed applications with minimal precision requirements.
Electric technology commands overwhelming share of new procurement; hydraulic systems are contracting except in specialized heavy-force niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing clusters in China's Inner Mongolia and Jiangxi provinces anchor upstream supply for compact electric gear motor architectures. This feedstock concentration shapes procurement geography across downstream assembly operations.
Germany
Automotive OEM supply chains and precision manufacturing clusters in Stuttgart and Wolfsburg drive helical gear procurement volumes. The EU F-Gas Regulation mandates efficiency upgrades across electromechanical power transmission equipment. SEW-Eurodrive's integrated manufacturing footprint in Bruchsal controls quality across helical and bevel gear lines serving regional automotive assembly plants.
China
GB standards and MIIT efficiency mandates impose minimum performance thresholds on gear motor assemblies for domestic manufacturing. Warehouse automation in the Yangtze River Delta and Pearl River Delta sustains conveyor system demand. Domestic production capacity expansion accelerates as local suppliers capture procurement from multinational industrial equipment supply chains.
United States
Food processing and pharmaceutical manufacturers in the Midwest and Southeast adopt sensor-integrated gear units fastest. OSHA machinery safety requirements and FDA batch traceability mandates drive zero-downtime specifications. Automated distribution centers across Texas and Georgia compress supplier lead times while expanding performance certification requirements.
Japan
Machine tool builders in Aichi Prefecture specify compact servo-integrated units for precise speed-torque matching. METI industrial efficiency guidelines and JIS standards govern product certification for robotics and packaging OEMs. Modular servo-gearmotor platforms from Nagoya-area suppliers enable torque reconfiguration through software parameter changes.
India
PLI scheme incentives for domestic manufacturing equipment create procurement windows for precision gear component suppliers. Gujarat and Maharashtra industrial corridors attract gear motor assembly investments. Elecon Engineering anchors domestic production capacity serving material handling and power transmission applications across western Indian manufacturing clusters.
Motor Gear Unit Market Competitive Landscape
Global majors compete with regional champions across integrated manufacturing versus specialized component supply. The vendor base stratifies into three tiers: German precision manufacturers with captive gear cutting capacity, Japanese servo-motor integrators, and emerging Asian scale players. Strategic archetypes include full-line system suppliers, niche application specialists, and component-focused fabricators. M&A activity concentrates on sensor technology acquisitions and geographic expansion into Indian and Southeast Asian assembly markets.
Among German-based integrated manufacturers, SEW-Eurodrive and Flender exemplify the full-line system supplier archetype with captive production of helical and bevel gear architectures. Nidec occupies a position within the compact electric gear motor tier, representing high-R&D intensity specialization for robotics and conveyor applications. These three anchors illustrate how geographic origin and company structure correlate with strategic positioning across precision manufacturing, servo integration, and scale-driven supply.
| Leading Market Players |
|---|
| Regal Rexnord |
| Nidec |
| SEW-Eurodrive |
| Dana Industrial |
| Nord Drivesystems |
| Sumitomo Heavy Industries |
| Bonfiglioli |
| Elecon Engineering |
| Flender |
| Others |
Supply & Pricing Matrix
Captive gear cutting capacity in Germany anchors premium pricing power for helical and bevel architectures serving Stuttgart automotive clusters. SEW-Eurodrive's Bruchsal manufacturing footprint controls quality across precision lines, insulating against commodity price erosion while forcing mid-tier competitors toward unbundled service models.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium German suppliers from economy-tier Asian competitors. Three-tier pricing structure across premium, standard, and economy levels tracks certification density: ISO 6336-validated units command substantial premiums over uncertified alternatives. Pricing pressure stems from Chinese domestic capacity expansion under MIIT efficiency mandates. Small and mid-tier European manufacturers exhibit highest price sensitivity as rare earth magnet cost volatility compresses margins.
Supply Chain Analysis
Remanufacturing flows for industrial gear units concentrate in Germany and Japan, extending asset life for high-value helical configurations. Upstream rare earth processing draws from China's Inner Mongolia and Jiangxi provinces, creating single-source vulnerability for compact electric architectures. Specialized alloy dependencies include neodymium-iron-boron magnets, case-hardened steel forgings, and synthetic ester lubricants. Distribution runs through OEM-direct channels for automotive supply chains and industrial distributors for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The motor gear unit sector sits in a pronounced technology-transition phase as permanent magnet electric architectures displace hydraulic power transmission in metal forming and injection molding.
For Market Incumbents: Anticipate margin compression from Chinese scale players by qualifying multiple lubricant suppliers per product line to mitigate REACH validation timeline risk. Deepen backward integration into rare earth magnet sourcing through offtake agreements with Jiangxi processors. Sensor-enabled predictive maintenance contracts represent the critical defensive lever against independent aftermarket providers.
For New Entrants and Emerging Players: Capture procurement windows in India's PLI scheme corridors by targeting Gujarat and Maharashtra material handling clusters with compact servo-integrated units. Robotics integration for collaborative robot arm manufacturers offers the most penetrable white space, with existing supplier capacity lagging demand. A component-specialist go-to-market angle—precision gear cutting without full motor integration—sidesteps capital intensity barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in sensor technology acquisitions and geographic expansion into Indian assembly markets. Long-term viability favors vertically integrated manufacturers with captive gear cutting capacity over component fabricators exposed to commodity cycles. Watch F-Gas Regulation enforcement intensity across German manufacturing clusters as inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive magnet sourcing insulates against Jiangxi processing concentration and price volatility. |
| Sensor-Enabled Predictive Maintenance Platform | Outcome-based contracts displace break-fix aftermarket revenue pools in automotive plants. |
| Modular Servo-Gearmotor Platform Launch | Software torque reconfiguration reduces spare inventory for Japanese machine tool builders. |
| REACH-Compliant Lubricant Qualification | Multiple supplier validation mitigates extended approval timelines for marine installations. |
| Indian Assembly Footprint Expansion | PLI scheme access captures western corridor material handling procurement growth. |
Research Methodology
Independent corroboration across plant engineer interviews, OEM procurement director discussions, and aftermarket service head consultations underwrites the qualitative findings. Primary fieldwork engaged maintenance directors at German automotive assembly plants, technical R&D leads at precision gear manufacturers, and channel partners serving warehouse automation integrators. Secondary validation drew from EU F-Gas Regulation filings, MIIT efficiency mandate documentation, SEC 10-K disclosures from listed industrial equipment suppliers, and ISO 6336 certification registries. Bottom-up unit demand modeling triangulated against top-down manufacturing value-added estimates.
Rate-of-change decomposition across the projection horizon separates volume growth from mix shift toward higher-efficiency electric architectures. Segmentation dimensions modeled include gear architecture type, end-use application intensity, technology modality, and regional regulatory cluster. CAGRs derived from regression analysis of historical replacement cycles against electrification mandate timelines. Forecast inputs incorporated F-Gas Regulation compliance cost curves and MIIT domestic production incentive trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth export restriction severity and carbon border adjustment mechanism implementation timing. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology substitution elasticities. Practitioners should monitor Inner Mongolia rare earth processing quota announcements and EU machinery directive amendment drafts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive Seat Motor Market
Electric Motor
Electric Drives Market
Electric Motor
Automotive Heater Fan Motor Market
Electric Motor
Vibrator Motor Market
Electric Motor
Electric Motorcycle Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Automotive Wiper Motor Market
Electric Motor
Electric Vehicle Flat Wire Motor Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Traction Motor Core Market
Electric Motor
Automotive Sunroof Motor Market
Electric Motor
E-Bike Motor Market