
 Power Tool Lithium Battery Market | 2026-2036
Power Tool Lithium Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Power Tool Lithium Battery Market Insights
The EU Battery Regulation is decoupling cost structures from legacy chemistries by imposing strict recycled lithium and cobalt thresholds on cell producers. Samsung SDI leverages its Korean cathode supply chain to preempt compliance costs. CATL anchors its European expansion with dedicated recycling partnerships in Hungary.
Power tool lithium batteries are rechargeable electrochemical cells, typically lithium-ion or lithium-polymer configurations rated between 18V and 40V, engineered to deliver high discharge rates for brushless motor drives in portable equipment. Their primary purpose is replacing corded power sources on job sites where mobility and runtime directly determine labor productivity. Cordless drills occupy the largest volume share among product types due to universal adoption across trade categories. Fast charge technology commands premium positioning as contractors prioritize minimizing downtime between cycles. The 6Ah capacity tier captures outsized margin attention from professional users balancing weight against extended runtime demands.
The EU Battery Regulation, EPA hazardous waste rules, and China's GB standards collectively tighten material traceability and end-of-life accountability across the value chain. These frameworks elevate compliance costs for smaller pack assemblers while favoring vertically integrated cell manufacturers with certified recycling streams. Stakeholders must weigh chemistry selection against emerging carbon border adjustments and regional content requirements before committing to capacity expansion.
Market Dynamics
Professional construction crews in Germany's industrial corridor are accelerating cordless drill adoption, forcing pack assemblers to reconcile fast-charge performance demands with the EU Battery Regulation's recycled content mandates.
Growth Catalysts
- Brushless motor diffusion:High-efficiency brushless drives in professional-grade equipment reduce energy loss, extending effective runtime per charge cycle and justifying premium battery investments.
- EU Battery Regulation thresholds:Mandatory recycled lithium and cobalt minimums are compressing legacy chemistry margins while rewarding producers with certified recycling infrastructure.
- Construction labor mobility:German trade contractors prioritize cordless platforms to eliminate generator dependency and reduce setup time on multi-site projects.
Market Restraints
- Cathode material concentration:Korean and Chinese cathode supply chains dominate precursor sourcing, exposing European pack assemblers to geographic single-point failure risks.
- Fast-charge thermal management:High C-rate charging generates cell degradation trade-offs that limit cycle life warranties and inflate replacement cost projections.
- EPA hazardous waste classification:End-of-life battery handling rules in the US impose reverse logistics burdens on distributors without dedicated recycling partnerships.
Strategic Opportunities
- Secondary life stationary storage:Retired power tool cells with degraded capacity retain value for residential energy storage applications in off-grid construction sites.
- Direct-to-contractor digital channels:Equipment rental platforms and manufacturer-direct portals are disintermediating traditional industrial distribution for professional user segments.
- Carbon border adjustment positioning:Early compliance with embedded carbon tracking requirements creates preferential access to EU public procurement tenders for infrastructure projects.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell characterization and battery management system firmware development expertise concentrates among a limited pool of specialists with automotive sector experience.
- Multi-certification timeline compression:Simultaneous pursuit of CE marking, UL listing, and GB standard compliance extends product launch cycles and strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Tool Lithium Battery Market |
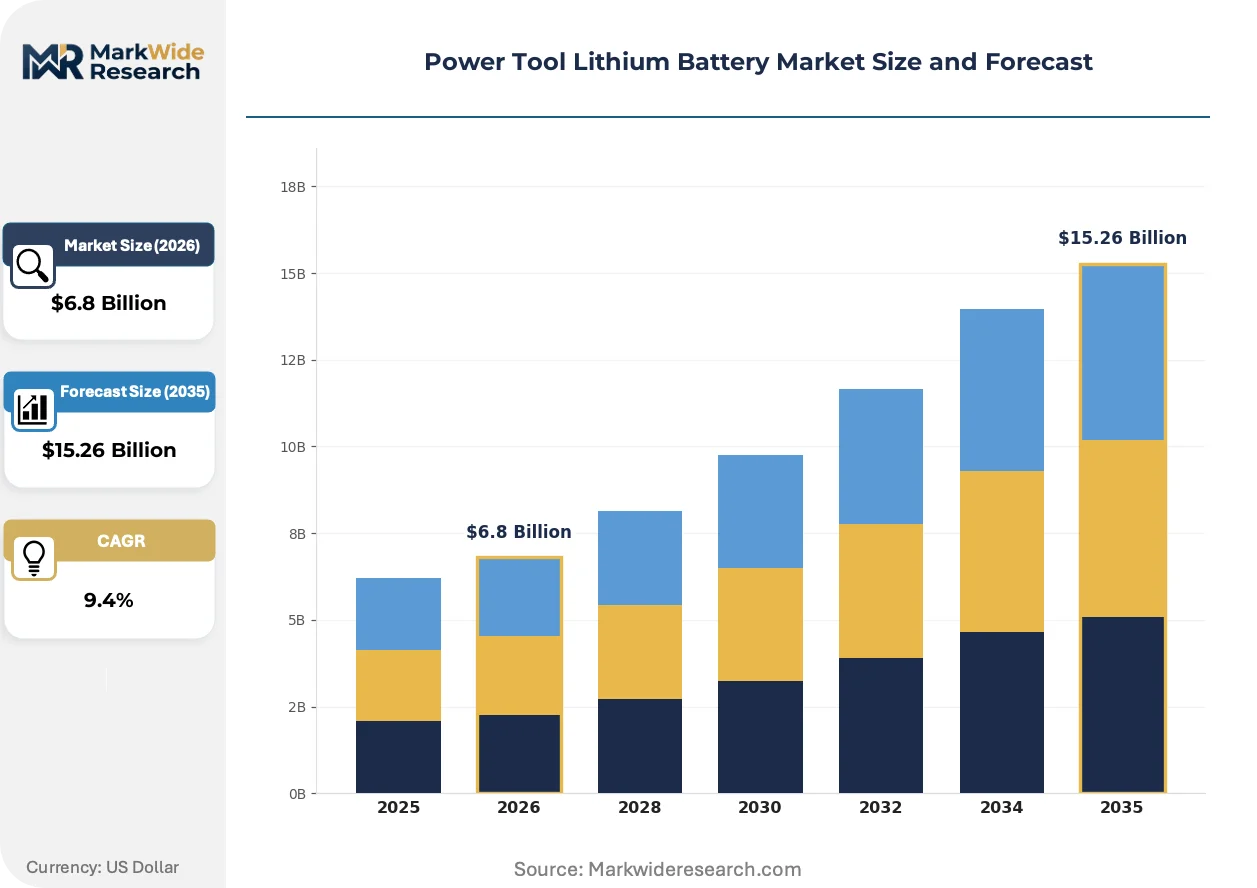
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cordless Drills, Circular Saws, Reciprocating Saws, Impact Wrenches End User: Construction, Manufacturing, Automotive, DIY Enthusiasts Battery Capacity: 2Ah, 4Ah, 6Ah, 8Ah Charge Technology: Fast Charge, Standard Charge, Smart Charge, Wireless Charge |
| Companies Covered | Stanley Black & Decker, Techtronic Industries, Makita Corporation, Robert Bosch, Hilti Corporation, Samsung SDI, Panasonic Corporation, LG Energy Solution, CATL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Tool Lithium Battery Market Trends and Innovations
Solid-state and silicon-anode chemistries are absorbing development investment as producers seek to satisfy professional runtime demands without violating weight constraints or thermal limits.
Silicon-anode blends are absorbing incremental capacity gains in high-discharge cells by replacing graphite with silicon composites that store more lithium ions per unit volume. German power tool manufacturers are qualifying these cells for 40V platform extensions targeting masonry and metalworking applications. The technology is absorbing margin pressure from cobalt reduction mandates by delivering performance differentiation without premium chemistry costs.
REACH substance restrictions and the EU Battery Regulation's carbon footprint declaration requirements are forcing cell producers to document supply chain emissions across mining, refining, and assembly stages. Industrial pack assemblers face compliance cost inflation that favors vertically integrated manufacturers with captive material traceability systems. Professional-grade product lines bear the heaviest documentation burden as they target EU public works contracts with mandatory sustainable procurement clauses.
Certification-driven procurement is compressing supplier qualification timelines as German construction consortia centralize purchasing through approved vendor lists. Rental equipment fleets are displacing individual contractor ownership for high-voltage platforms, shifting volume concentration toward national equipment lessors with standardized battery compatibility requirements. This concentration is most visible in Bavaria and North Rhine-Westphalia where infrastructure investment density supports fleet-scale deployment economics.
Power Tool Lithium Battery Market Segmentation
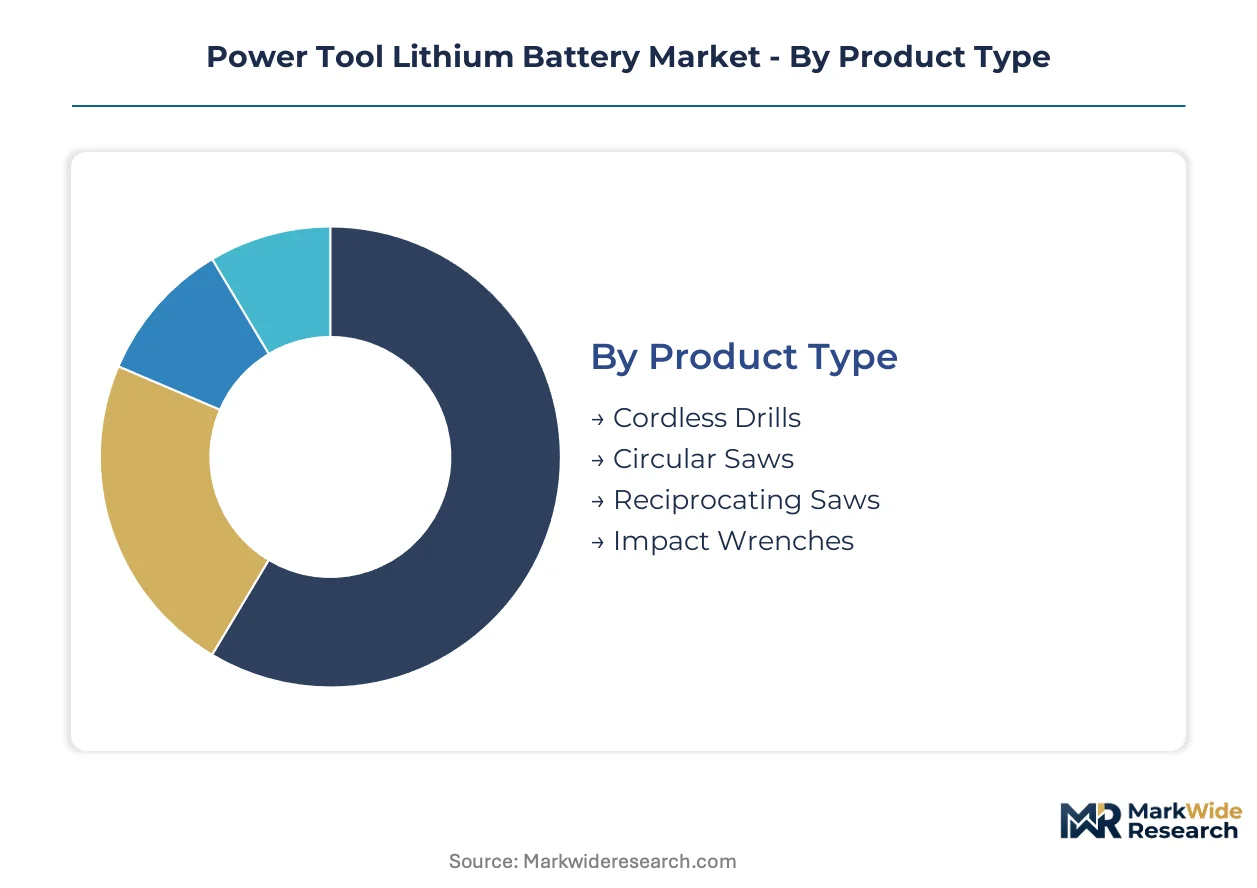
Segmentation in power tool lithium batteries reveals how professional contractors prioritize runtime density over upfront cost, while regulatory pressure on recycled content splits supplier qualification tiers. Understanding these divides exposes where margin concentrates and which technology investments align with procurement evolution.
Product Type:
Buyers differentiate by torque demands and job site mobility requirements, with trade contractors selecting platforms based on motor efficiency and battery interchangeability across tool families.
- Cordless Drills:Universal brushless motor configurations in 18V-20V platforms dominate professional tool belts. German construction consortia in Bavaria and North Rhine-Westphalia are standardizing on these systems to eliminate generator dependency across multi-site masonry contracts.
- Circular Saws:High-torque 40V configurations with silicon-anode cells address metal framing and decking applications. Demand concentrates among industrial manufacturing facilities in Germany's Ruhr corridor where extended runtime justifies premium platform investments.
- Reciprocating Saws:Compact 18V variants serve demolition crews requiring one-handed operation in confined mechanical spaces.
- Impact Wrenches:Heavy-duty 40V systems target automotive assembly and heavy equipment maintenance with burst discharge requirements.
Cordless drills lead volumes today; circular saws are climbing the fastest as 40V platform extensions penetrate metalworking trades.
End User:
Procurement scale and compliance burden separate professional segments from consumer tiers, with certified recycling documentation becoming a gatekeeping requirement for public works eligibility.
- Construction:Trade contractors purchasing through equipment rental platforms and approved vendor lists. EU Battery Regulation mandates are compressing supplier pools to vertically integrated manufacturers with traceable recycling streams.
- Manufacturing:Industrial maintenance departments specifying battery interchangeability across cordless platforms to minimize spare inventory. REACH substance restrictions and carbon footprint declarations impose heaviest documentation burdens on this segment targeting sustainable procurement clauses.
- Automotive:Assembly line tool cribs prioritizing fast-charge throughput to maintain takt time without workstation bottlenecks.
- DIY Enthusiasts:Price-sensitive retail purchasers with minimal compliance exposure but growing preference for battery compatibility across home improvement tool ecosystems.
Construction commands the largest procurement volumes; manufacturing is expanding most quickly as carbon border adjustment positioning drives fleet standardization.
Battery Capacity:
Weight-runtime trade-offs fragment user preferences, with professional crews optimizing for shift-length coverage without ergonomic fatigue.
- 6Ah:The professional sweet spot balancing cell count against tool weight. German contractors specify this tier for eight-hour masonry shifts where generator elimination drives productivity gains.
- 4Ah:Compact configurations for overhead and confined-space applications where tool maneuverability outweighs runtime extension.
- 2Ah:Entry-level packs for intermittent DIY use and backup redundancy in professional kits.
- 8Ah:Extended runtime for high-draw applications with thermal management penalties limiting fast-charge compatibility.
6Ah configurations dominate professional procurement today; 8Ah variants are gaining share fastest as silicon-anode technology reduces weight penalties.
Charge Technology:
Downtime sensitivity and infrastructure investment separate premium positioning from cost-optimized tiers, with thermal management capabilities determining warranty terms.
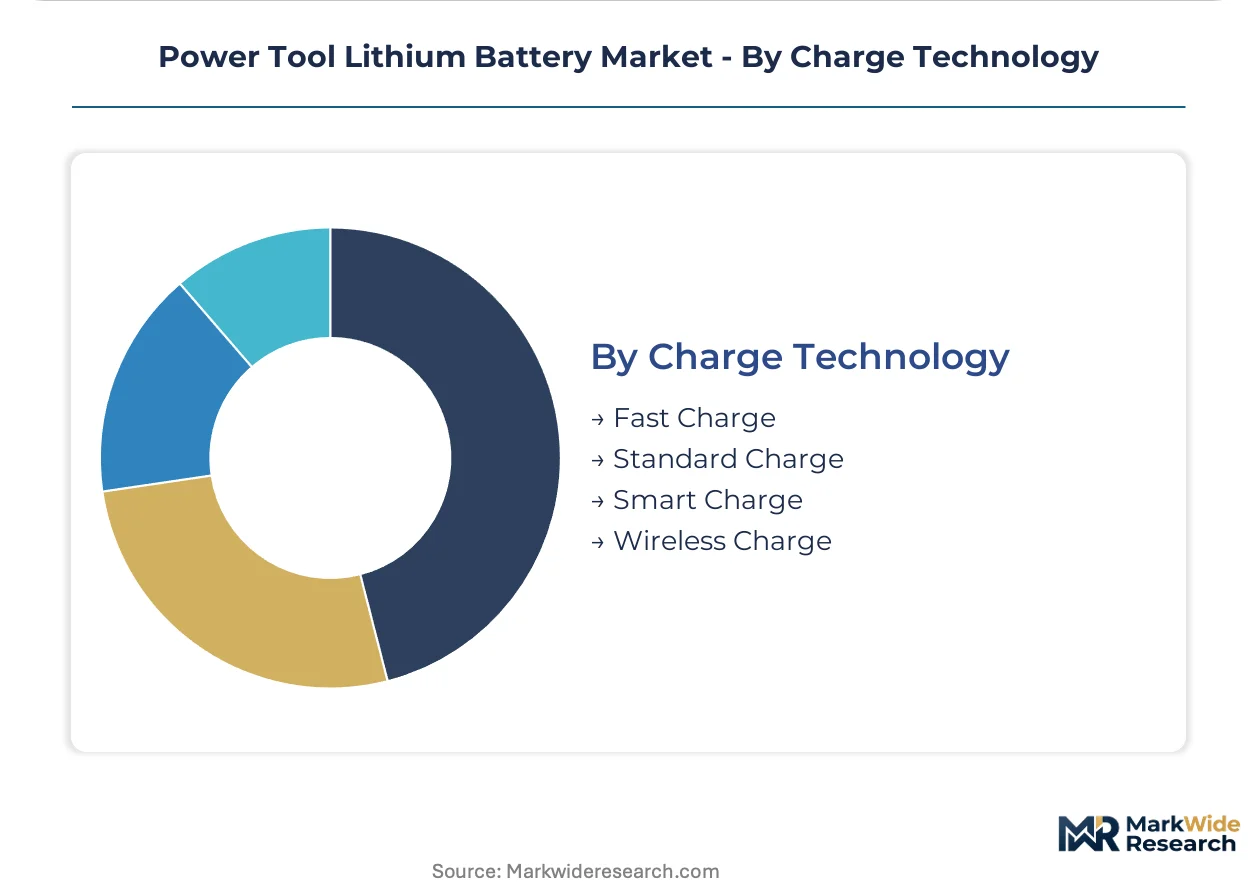
- Fast Charge:High C-rate systems reducing cycle downtime to 15-35 minutes. Professional crews in Germany's industrial corridor prioritize these systems despite cell degradation trade-offs that compress warranty periods.
- Smart Charge:Battery management system integration optimizing charge curves for cycle life extension. Manufacturing maintenance departments favor this tier for capital equipment with multi-year depreciation horizons.
- Standard Charge:Cost-optimized overnight charging for non-time-critical applications and backup inventory rotation.
- Wireless Charge:Inductive systems for cleanroom and hazardous environment applications where connector wear poses contamination or spark risks.
Fast charge leads professional adoption today; smart charge is expanding most quickly as total cost of ownership calculations incorporate replacement cycle economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered lithium-ion cell commercialization for consumer electronics in the early 1990s, establishing the foundational manufacturing protocols that power tool battery architectures later adopted. This technical lineage continues to shape regional specialization patterns across major producing economies.
United States
Professional construction crews in Texas and Florida are standardizing on cordless platforms for hurricane-resistant housing builds. EPA hazardous waste classification rules tighten end-of-life handling requirements for distributors. The Southeast manufacturing corridor from Atlanta to Charlotte hosts expanding pack assembly operations serving regional equipment lessors.
Germany
Bavarian masonry contractors and North Rhine-Westphalia metalworking shops drive 40V platform adoption for generator-free job sites. The EU Battery Regulation's recycled content mandates compress supplier pools to certified recycling stream operators. Industrial manufacturing clusters in the Ruhr corridor concentrate demand for high-discharge silicon-anode configurations.
China
Domestic construction mechanization and export-oriented power tool manufacturing absorb the majority of regional cell output. GB standards on lithium battery safety and traceability align with tightening EU import requirements. The Yangtze River Delta hosts integrated cathode precursor and cell finishing capacity serving global OEM supply chains.
South Korea
Automotive cell expertise migrates into power tool applications as producers leverage shared cathode supply chain investments. MFDS battery safety certifications and carbon footprint disclosure rules align with EU market entry requirements. Seoul Capital Area R&D centers concentrate electrochemical engineering talent for next-generation silicon-anode development.
Power Tool Lithium Battery Market Competitive Landscape
The competitive structure tilts toward vertically integrated cell manufacturers with captive recycling infrastructure. Tiered supplier qualification is compressing the vendor base as EU Battery Regulation compliance costs exclude smaller pack assemblers. Three archetypes dominate: Korean and Chinese cathode-integrated cell producers, European industrial tool OEMs with backward battery integration, and Japanese electronics conglomerates with legacy lithium expertise. Capacity expansion in Hungary and strategic recycling partnerships represent the dominant competitive vectors.
Within the cell producer tier, Samsung SDI and LG Energy Solution anchor Korean supply chain positioning, while CATL exemplifies Chinese scale-driven expansion into European pack assembly. Stanley Black & Decker and Robert Bosch occupy positions as tool OEMs with integrated battery platform strategies. These five entities represent the structural poles around which second-tier specialists and regional assemblers orbit.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Techtronic Industries |
| Makita Corporation |
| Robert Bosch |
| Hilti Corporation |
| Samsung SDI |
| Panasonic Corporation |
| LG Energy Solution |
| CATL |
| Others |
Pricing and Supply Chain Analysis
Cathode precursor costs originating in Korean and Chinese refining operations cascade through cell production tiers, compressing margins for European pack assemblers lacking backward integration into nickel-cobalt processing while rewarding manufacturers with captive cathode supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified recycling-stream operators from uncertified assemblers and gray-market imports. Price differentiation hinges on EU Battery Regulation compliance documentation and fast-charge thermal management warranties. Cost compression in the standard tier is intensifying because Korean cathode supply chain concentration exposes European buyers to freight and duty volatility. DIY enthusiasts exhibit highest price sensitivity; German construction consortia purchasing through approved vendor lists show lowest elasticity due to procurement compliance mandates.
Supply Chain Analysis
Domestic-content thresholds embedded in EU public procurement rules and China's GB standards are forcing cell producers to reconfigure cathode sourcing away from single-country dependencies. Manufacturing gravity centers on China, South Korea, and Japan for precursor refining and cell finishing. The value chain draws from Australian lithium spodumene, Indonesian nickel laterite, and DRC cobalt hydroxide. Single-source vulnerability in Korean cathode precursor supply exposes European pack assemblers to geographic concentration risk. Distribution runs through national equipment lessors and manufacturer-direct portals disintermediating traditional industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU Battery Regulation compliance costs in Europe and scale manufacturing economics in Asia creates margin expansion opportunities for producers with transnational production footprints.
For Market Incumbents: Lock in cathode supply agreements with Korean refiners before carbon border adjustments tighten import economics. Secure dedicated recycling partnerships in Hungary to preempt EU Battery Regulation recycled content mandates. Defensive consolidation of cell characterization talent pools offsets electrochemical engineering scarcity threatening R&D timelines. For New Entrants and Emerging Players: Silicon-anode qualification for 40V platform extensions offers technology-first entry into German metalworking trades underserved by legacy graphite-cell incumbents. Target secondary-life stationary storage applications for retired power tool cells in off-grid construction segments. Direct-to-contractor digital channels bypass equipment rental platform gatekeepers controlling Bavarian and North Rhine-Westphalia procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where EU Battery Regulation compliance costs exceed smaller pack assemblers' capital reserves. Long-term viability favors vertically integrated cell manufacturers with certified recycling infrastructure and captive cathode supply. Acquisition target archetype: mid-cap European pack assemblers with approved vendor list status but lacking recycling partnerships. Watch silicon-anode qualification timelines at German tool OEMs as inflection indicator for next-generation chemistry adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Recycling Partnership Formation | CATL's Hungarian facility secures EU Battery Regulation compliance for European expansion. |
| Silicon-Anode Cell Qualification | German manufacturers extend 40V platforms into masonry without cobalt premium chemistry. |
| Direct-to-Contractor Channel Buildout | Equipment rental platforms disintermediate legacy industrial distribution in Bavaria. |
| Cathode Supply Backward Integration | Samsung SDI leverages Korean precursor investments to compress compliance costs. |
| Carbon Footprint Documentation Investment | Industrial pack assemblers meet REACH and EU Green Deal procurement clause requirements. |
Research Methodology
Bottom-up contractor equipment procurement modeling reconciled against top-down cell production capacity tracking forms the analytical core. Primary interviews with battery management system firmware engineers, equipment rental platform procurement directors, German construction consortium purchasing managers, and cathode precursor supply planners combined with secondary validation from EU Battery Regulation implementation documents, ECHA REACH substance restriction updates, Korean MFDS safety certification filings, and customs trade flow data. Triangulation across these sources calibrates volume and value estimates.
Historical trendline analysis of cordless drill adoption rates and fast-charge technology penetration established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, battery capacity tier, charge technology, and regional regulatory cluster. CAGRs derive from fitted growth curves adjusted for EU Battery Regulation implementation pace and silicon-anode commercialization timelines. Industry-specific forecast inputs incorporate brushless motor diffusion rates and construction labor mobility indices.
The model holds under stable cathode supply chain configurations and consistent regulatory enforcement timelines; deviation in Korean precursor export restrictions, EU carbon border adjustment scope expansion, or silicon-anode thermal management breakthroughs would shift trajectory. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
GCC Electric Motor Market
Electric Motor
Motor Gear Unit Market
Electric Motor
Traction Motor Core Market
Electric Motor
Electric Drives Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
Global Automotive Onboard Charger Market
Electric Motor
China E-Bike (Pedelec Bikes) Hub Motor Market
Electric Motor
UAE Electric Motor Market
Electric Motor
Electric Vehicle (EV) Traction Motor Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Car Charger Market
Electric Motor
Electric Motors for IC Engine Vehicle Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
Global Motor Management Market
Electric Motor
Automotive ABS Motor Market