
 Qatar Gas Hobs Market | 2026-2036
Qatar Gas Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Gas Hobs Market Analytics
After-sales maintenance contracts and extended warranty packages is pivoting vendor revenue models away from one-time appliance sales. Bosch leverages its service network density to lock in repeat engagement across Qatar's premium residential towers. Samsung competes on smart-home integration, embedding Wi-Fi diagnostics into its hob lines. La Germania anchors its position through specialized high-BTU commercial units aimed at Qatar's expanding restaurant sector.
Gas hobs are cooking appliances employing open-flame burners fueled by natural gas, propane, or butane, typically delivering heat outputs from 3.5 kW to 5 kW per burner through cast iron or brass burner caps. These units serve residential kitchens, commercial foodservice operations, and hospitality facilities requiring precise temperature control and rapid thermal response. Built-in installation dominates Qatar's new construction pipeline, while freestanding units retain traction in renovation projects and mid-market housing. Natural gas fuel type leads volume given Qatar's domestic gas abundance and KAHRAMAA pipeline infrastructure, though hybrid hobs combining gas and electric elements are gaining share among design-conscious buyers in West Bay luxury developments.
KAHRAMAA sets minimum efficiency thresholds for gas-burning appliances sold in Qatar, directly influencing burner design and ignition system specifications. The country's national standardization body, in coordination with Gulf Standardization Organization (GSO) requirements, mandates safety certifications for imported cooking equipment, creating compliance barriers for uncertified manufacturers. Stakeholders must monitor evolving energy-labeling rules and building code updates in Lusail and Msheireb districts, where green building certifications are becoming procurement gatekeepers for developer contracts.
Market Dynamics
KAHRAMAA efficiency mandates are compressing traditional burner architectures while Lusail City's green building procurement rules privilege certified appliance vendors. This dual regulatory pressure is restructuring vendor eligibility and accelerating technology turnover across Qatar's construction pipeline.
Growth Catalysts
- Lusail Smart City mandates:Green building certifications in this district require high-efficiency gas appliances, creating procurement pull for compliant hobs in residential towers.
- Cast brass burner caps:Superior thermal conductivity and corrosion resistance in Qatar's humid coastal environment extends equipment lifespan and reduces service calls.
- KAHRAMAA pipeline expansion:Natural gas infrastructure densification into West Bay and Pearl-Qatar developments eliminates propane dependency for new installations.
Market Restraints
- Copper and brass input volatility:Burner component costs fluctuate with global metal commodity markets, compressing margin predictability for manufacturers.
- Import certification timelines:Gulf Standardization Organization conformity assessment procedures create 8-14 week entry delays for non-established suppliers.
- Induction cooktop substitution:Electric alternatives gain share in premium West Bay renovations where full-kitchen electrification aligns with developer sustainability branding.
Strategic Opportunities
- Msheireb Downtown Doha:Heritage district restoration projects specify traditional-look gas hobs for boutique hospitality kitchens, creating niche demand.
- Wi-Fi diagnostic convergence:Smart home integration partnerships with building management systems in Lusail's connected towers enable predictive maintenance revenue streams.
- Extended warranty channel innovation:Developer bulk procurement contracts now bundle 5-year service packages, shifting vendor economics toward recurring revenue.
Industry Challenges
- Certified technician scarcity:KAHRAMAA-authorized gas appliance installers remain concentrated in Doha, creating service bottlenecks for Al Wakrah and Al Khor deployments.
- Legacy kitchen footprint constraints:Existing countertop cutout dimensions in renovation projects limit retrofit options to specific hob sizes, fragmenting inventory requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Gas Hobs Market |
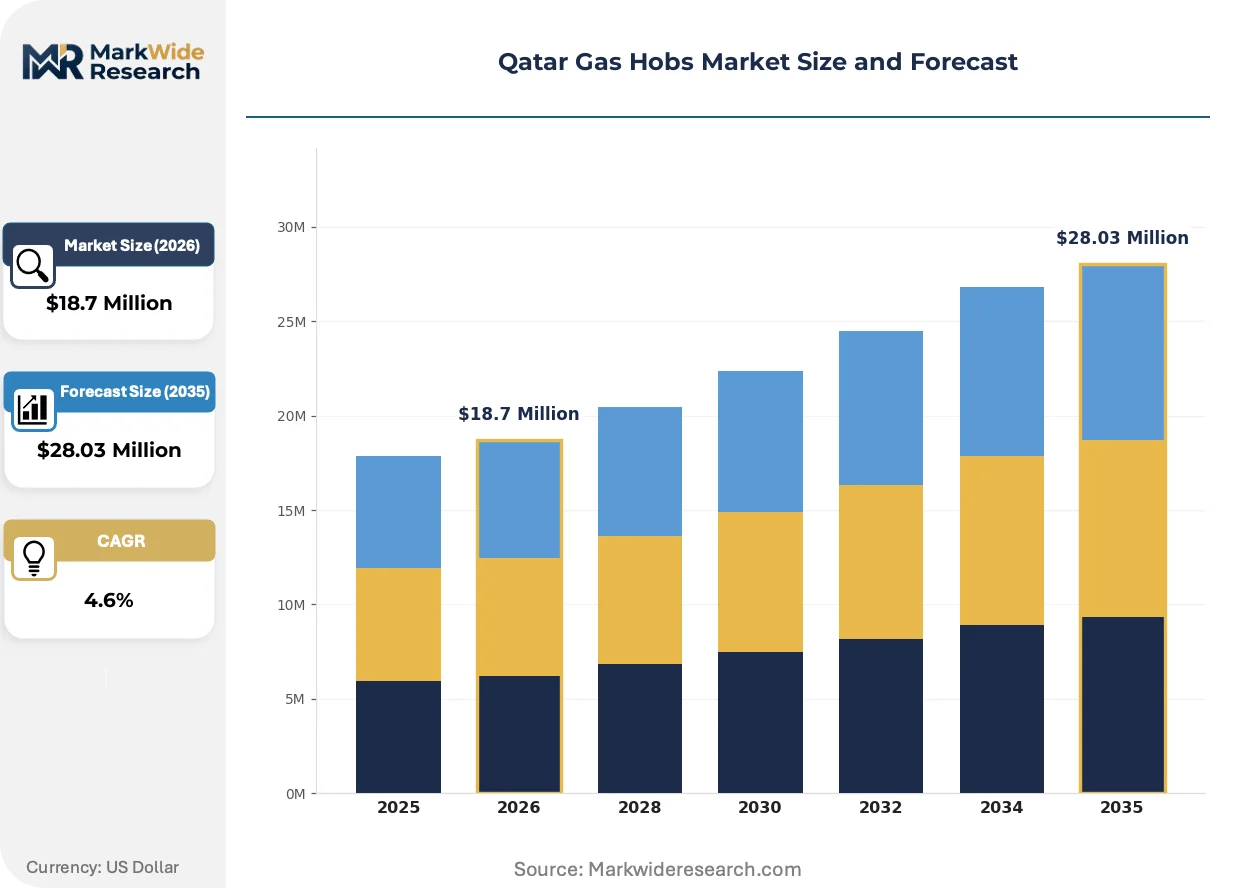
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $28.03 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction Hobs, Gas Hobs, Electric Hobs, Hybrid Hobs Installation Type: Built-in, Freestanding, Countertop, Portable Fuel Type: Natural Gas, Propane, Butane, Electricity End User: Residential, Commercial, Hospitality, Industrial |
| Companies Covered | Bosch, Whirlpool, Beko, La Germania, Lofra, Fisher & Paykel, Siemens, Samsung, Electrolux, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Gas Hobs Market Evolving Landscape
Flame modulation technology and connected diagnostics are redefining performance benchmarks in Qatar's premium residential segment. Regulatory pressure on thermal efficiency is simultaneously compressing traditional burner designs and opening white space for hybrid fuel configurations.
Triple-ring burner architectures with independently controlled flame zones are decentralizing heat distribution control in high-end residential kitchens. West Bay luxury developers specify these units for penthouse installations where precise temperature gradation supports diverse cooking techniques. The technology is decentralizing purchasing authority from general contractors to chef consultants engaged by individual unit buyers.
KAHRAMAA's phased efficiency threshold escalations are mandating electronic ignition systems and flame failure devices on all new installations. Appliance distributors must now maintain compliance documentation archives for warranty validation. Commercial foodservice operators in Doha's hotel district face the steepest retrofit obligations as existing stock ages out of service eligibility.
Buyer engagement patterns are compressing specification cycles as developers pre-select appliance packages for entire towers. Individual purchasers in Lusail's resale market encounter limited hob substitution options within fitted kitchens. This concentration is most pronounced in the hospitality-to-residential conversion segment where original equipment specifications lock in maintenance ecosystems for decade-long horizons.
Qatar Gas Hobs Market Segmentation
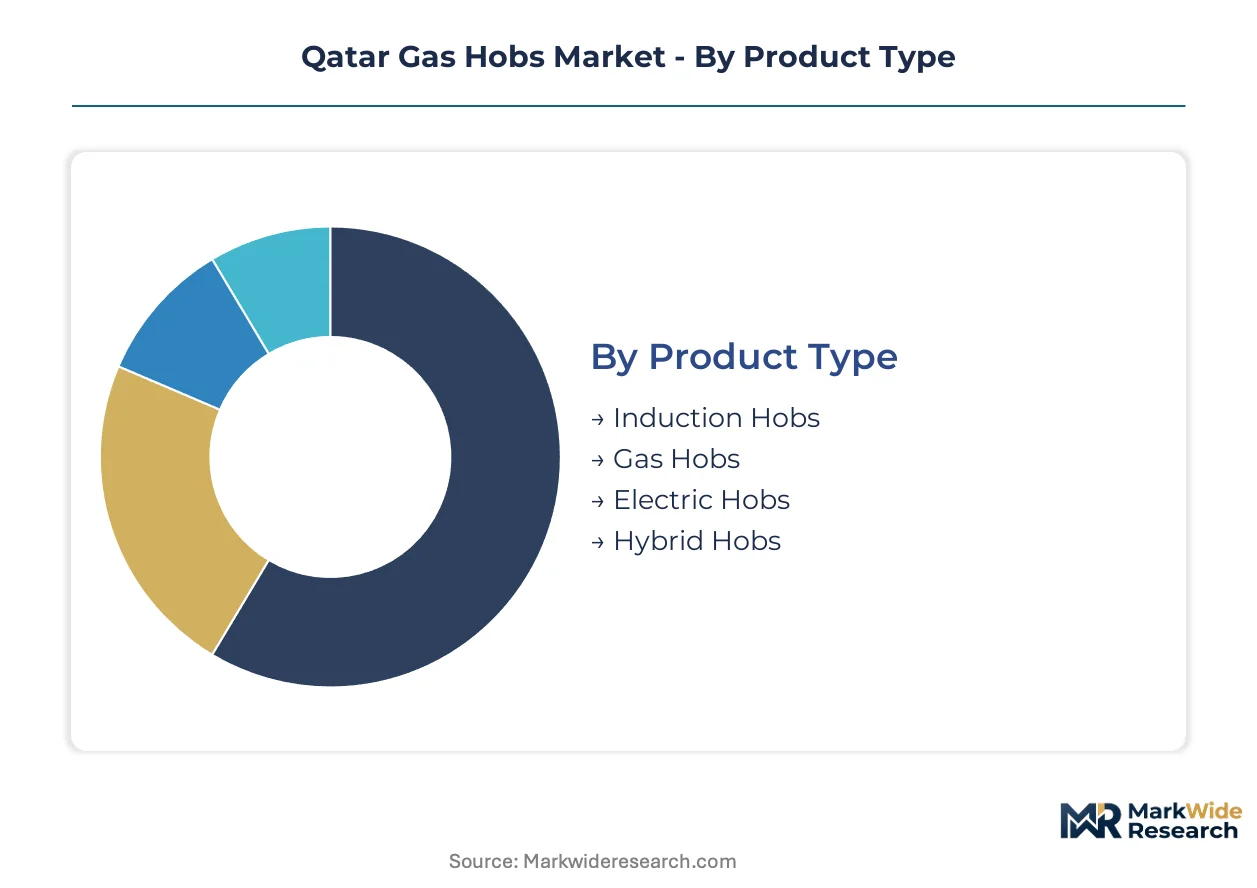
Qatar's gas hobs market fragments across four critical dimensions that determine procurement patterns, installation logistics, and vendor positioning. Product technology and fuel infrastructure compatibility dominate specification decisions in Doha's construction pipeline.
Product Type:
Gas hobs command volume leadership through KAHRAMAA pipeline penetration, while premium segments concentrate where electrification and smart-home integration reshape kitchen specifications.
- Gas Hobs:Open-flame burners fueled by natural gas or LPG deliver 3.5-5 kW outputs through cast iron or brass caps. Demand clusters in Lusail City's residential towers where KAHRAMAA infrastructure eliminates fuel logistics complexity and developer bulk procurement locks in specifications.
- Hybrid Hobs:Dual-fuel configurations combining gas burners with electric induction zones address diverse cooking techniques in West Bay luxury developments. Penthouse buyers specify these units for temperature precision, while developers leverage the technology for green building certification points.
- Induction Hobs:Fully electric cooking surfaces gain share in Pearl-Qatar renovations aligned with sustainability branding.
- Electric Hobs:Coil and ceramic radiant elements retain niche presence in budget residential conversions.
Mature deployment sits with gas hobs. Newer deployment is concentrated in hybrid configurations.
Installation Type:
Construction method determines specification authority—developer-driven new builds favor permanent integration while renovation activity sustains flexible formats.
- Built-in:Flush countertop integration dominates Qatar's new construction pipeline. West Bay and Lusail developers specify these units during tower fit-out, locking maintenance ecosystems and limiting end-user substitution.
- Freestanding:Self-contained units with integrated ovens serve renovation projects and mid-market housing in Al Wakrah where existing kitchen footprints constrain built-in retrofits.
- Countertop:Surface-mounted hobs address temporary hospitality installations and catering operations.
- Portable:Compact single-burner units serve outdoor catering and emergency kitchen backup.
Volume concentration tracks built-in specifications. Freestanding formats expand most quickly in renovation corridors.
Fuel Type:
Domestic energy abundance shapes fuel economics, with pipeline infrastructure creating decisive cost and convenience advantages for natural gas.
- Natural Gas:KAHRAMAA pipeline delivery dominates new installations across Doha, Lusail, and Al Rayyan. The fuel's cost stability and continuous supply eliminate cylinder logistics, making it mandatory for developer procurement in connected districts.
- Propane:LPG cylinder dependency persists in Al Khor and peripheral zones awaiting pipeline extension, creating service bottlenecks and higher operating costs for restaurants.
- Butane:Portable cylinder fuel serves outdoor catering and temporary foodservice operations.
- Electricity:Grid-powered cooking gains share where full-kitchen electrification aligns with district cooling integration.
Established infrastructure anchors natural gas deployment. Electrification represents the steepest expansion trajectory in premium West Bay renovations.
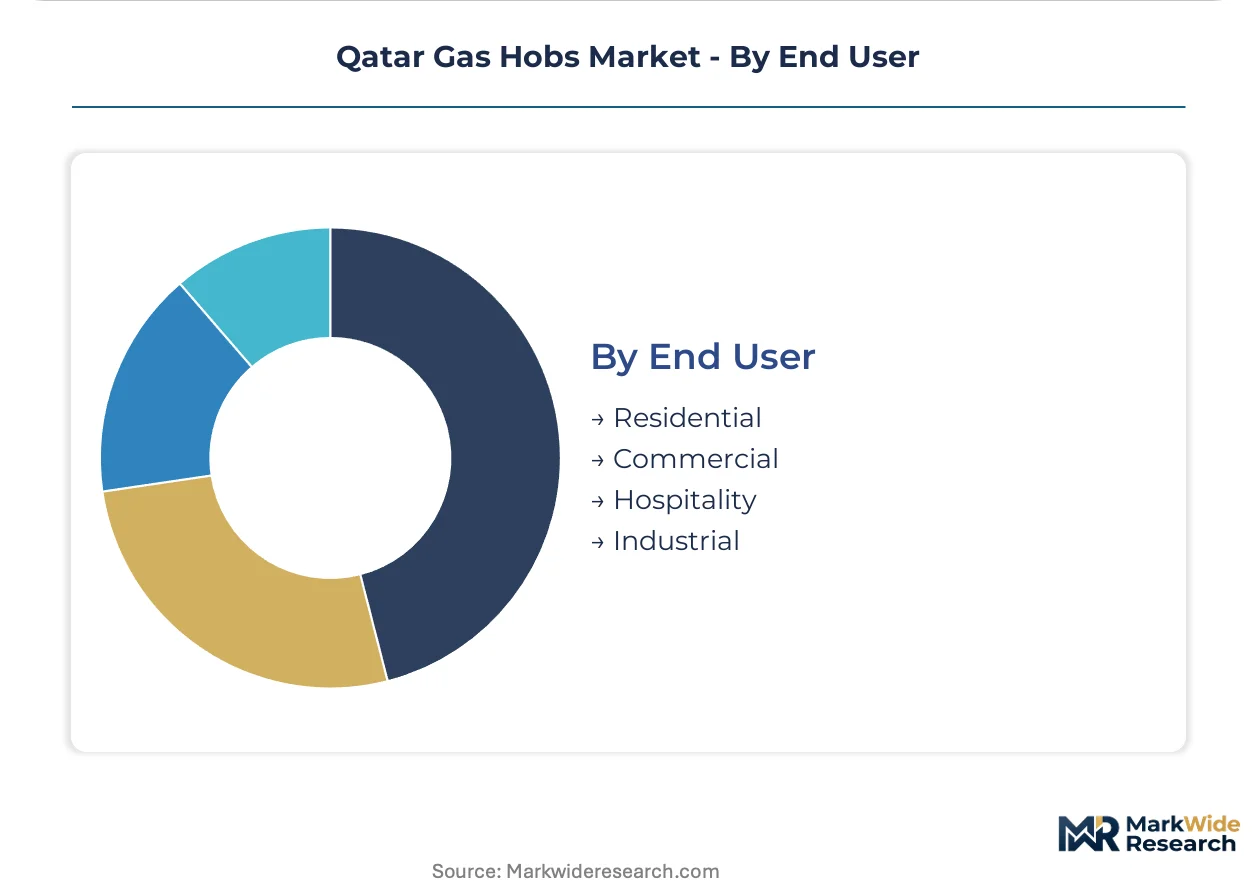
End User:
Buyer type determines specification complexity, maintenance contract structures, and burner performance requirements.
- Residential:Individual households and investor-owned apartments in Doha's high-rise towers drive volume demand. Purchasers prioritize aesthetic integration and KAHRAMAA compliance documentation for warranty validation.
- Hospitality:Hotels and serviced apartments in West Bay and Msheireb specify high-BTU commercial-grade burners. Chef consultants increasingly influence penthouse specifications, decentralizing authority from general contractors.
- Commercial:Independent restaurants and cloud kitchens in Lusail's food districts demand rapid thermal response and durability under continuous operation.
- Industrial:Central kitchen facilities and catering commissaries require heavy-duty configurations for volume food production.
Residential specifications dominate unit volumes. Hospitality procurement commands premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
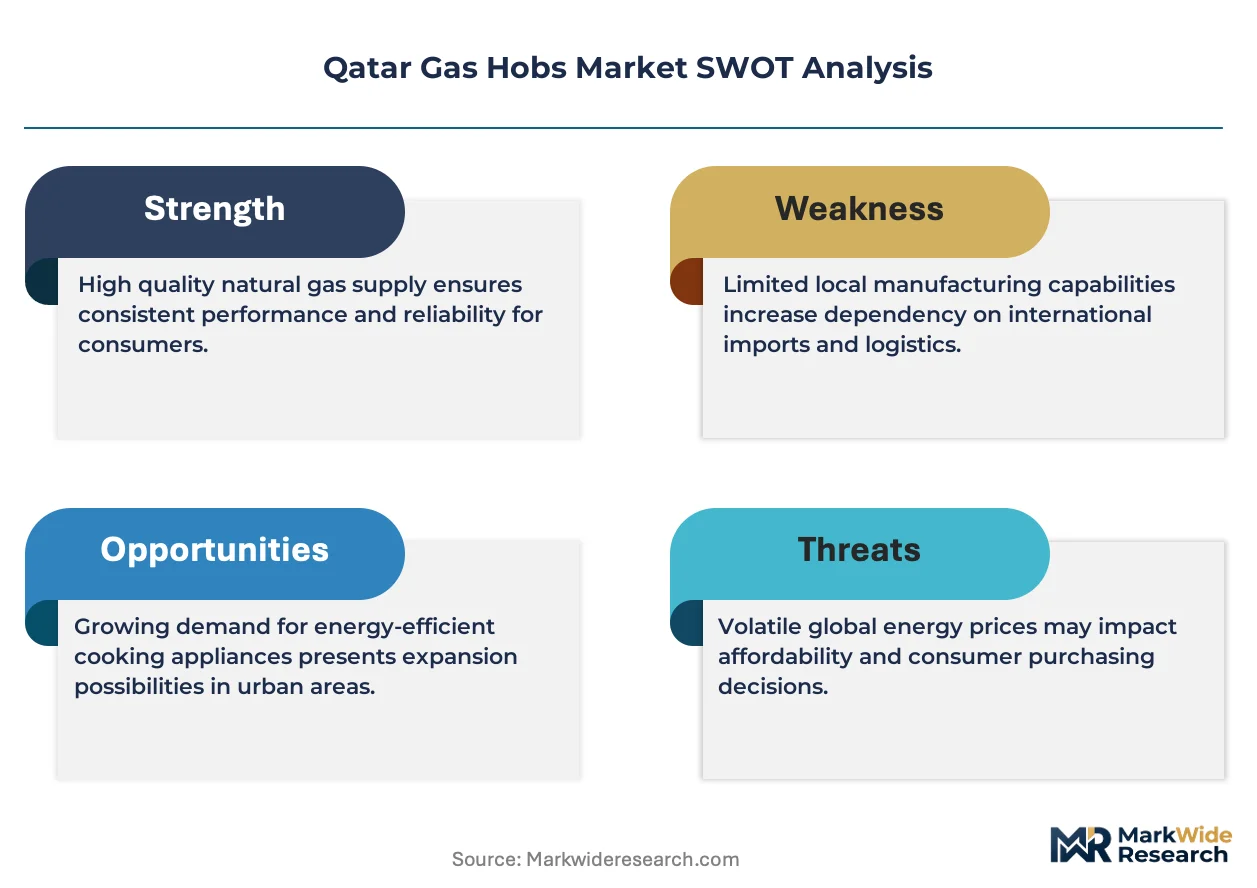
Qatar's gas hobs consumption outstrips domestic manufacturing capacity, creating import dependency for finished appliances and burner components. The market draws supply from European, Asian, and regional fabrication centers. Sub-regional demand clusters concentrate where KAHRAMAA infrastructure expansion and construction activity overlap.
Doha Metropolitan Area
West Bay's luxury residential towers and Msheireb's heritage hospitality projects drive premium hob specifications. KAHRAMAA efficiency mandates enforce electronic ignition and flame failure device compliance across all new installations. Developer bulk procurement in Lusail City locks in built-in gas hob specifications for entire tower portfolios.
Al Wakrah
Mid-market housing developments and renovation corridors sustain freestanding unit demand where existing kitchen footprints resist built-in retrofit. Pipeline infrastructure gaps in peripheral zones maintain propane cylinder dependency for restaurants. Service bottlenecks emerge from technician scarcity relative to installation volume.
Al Khor
Industrial zone expansion and worker accommodation projects generate standardized appliance demand at volume price points. Awaiting KAHRAMAA pipeline extension, commercial kitchens operate on LPG logistics with higher operating costs. New residential compounds pre-specify natural gas readiness for future infrastructure connection.
Lusail City
Smart city mandates require green building certification for all residential towers, privileging high-efficiency gas appliances in developer procurement. Connected building management systems enable predictive maintenance partnerships with appliance vendors. Hybrid hob configurations gain share among penthouse buyers seeking certification points and cooking flexibility.
Pearl-Qatar
Renovation activity in established residential units drives appliance replacement cycles with sustainability-aligned electrification trends. Full-kitchen electrification projects substitute induction for gas in premium repositioning strategies. Original built-in specifications from 2000s construction create legacy footprint constraints for retrofit options.
Qatar Gas Hobs Market Competitive Landscape
Top-tier vendors anchor premium residential and hospitality specifications, while mid-market specialists compete on price-accessible renovation segments. The vendor base stratifies across three tiers: global appliance conglomerates with service network density, regional distributors with import certification expertise, and niche commercial specialists. Competitive moves concentrate on extended warranty bundling and smart-home integration partnerships.
Within the European-origin tier, Bosch, Siemens, and Electrolux occupy positions defined by compliance documentation archives and KAHRAMAA-authorized service infrastructure. These manufacturers exemplify the archetype of vendors leveraging certification depth to lock in developer bulk procurement contracts. Samsung represents the electronics-origin competitor embedding connectivity features that align with Lusail's smart building requirements.
| Leading Market Players |
|---|
| Bosch |
| Whirlpool |
| Beko |
| La Germania |
| Lofra |
| Fisher & Paykel |
| Siemens |
| Samsung |
| Electrolux |
| Others |
Value Network & Pricing Analysis
Brass and copper burner component costs transmit directly from global metal commodity exchanges through to landed appliance pricing in Doha, with KAHRAMAA certification requirements layering compliance premiums atop raw material volatility. European-origin manufacturers leverage authorized service infrastructure to command price premiums in West Bay luxury towers, while Asian fabricators compete on accessible price points for Al Wakrah mid-market housing.
Pricing Analysis
Margin tightening in the premium tier reflects KAHRAMAA-authorized service network scarcity, as Bosch and Siemens capture developer bulk contracts through compliance documentation depth. Three-tier pricing structure across European premium, Asian standard, and regional economy levels separates buyers by certification grade and after-sales bundling. Cost-down pressure on mid-market SKUs accelerates because Lusail developer procurement centralizes specification authority and compresses substitution options. Residential investors in Pearl-Qatar resale units exhibit highest price sensitivity, while hospitality procurement in Msheireb demonstrates lowest sensitivity due to chef consultant specification authority.
Supply Chain Analysis
Single-source vulnerability sits with Italian and German burner component suppliers for brass casting and electronic ignition systems. Finished appliance supply concentrates in Italy, Turkey, and China, with component sourcing drawing from Indian brass foundries and Southeast Asian control module fabricators. Raw material dependencies rest on copper cathode, brass alloy, and tempered glass cooktop panels. Tariff exposure through Gulf Standardization Organization conformity assessment procedures creates 8-14 week entry delays. Distribution runs through Doha-based authorized distributors holding KAHRAMAA compliance archives for warranty validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's gas hobs market sits at a technology-transition phase as electronic ignition systems and flame failure devices displace standing pilot configurations under KAHRAMAA efficiency mandates. Hybrid fuel configurations combining gas and electric elements represent the ascendant specification in Lusail penthouse developments.
For Market Incumbents: Acquire KAHRAMAA-authorized service technician capacity to defend installed base maintenance revenue against Samsung's Wi-Fi diagnostic encroachment. Deepen backward integration into brass burner casting to offset copper price volatility compressing component margins. Lock in Lusail developer procurement through 5-year extended warranty bundling that shifts economics toward recurring service contracts. For New Entrants and Emerging Players: Launch via direct developer engagement in Al Wakrah renovation corridors where freestanding unit demand escapes incumbent bulk contract capture. Target Msheireb heritage hospitality kitchens specifying traditional-look gas hobs for boutique fit-outs, a niche underserved by smart-home-focused competitors. Penetrate through specialized high-BTU commercial configurations for Lusail's expanding restaurant sector. For Investors and Strategic Acquirers: KAHRAMAA pipeline extension announcements into Al Khor and peripheral zones are the leading indicator that natural gas-ready appliance demand will outstrip certified installer capacity, creating service infrastructure acquisition opportunities. Long-term viability hinges on regulatory compliance depth rather than manufacturing scale, privileging targets with established GSO certification expertise and archived warranty documentation systems. Monitor Lusail smart building management system integration partnerships as the signal for predictive maintenance revenue model viability.| Strategic Initiative | Industry Significance |
|---|---|
| KAHRAMAA Certification Investment | Compliance documentation archives unlock developer bulk procurement contracts in Lusail City towers. |
| Extended Warranty Channel Innovation | 5-year service bundling shifts vendor economics from transactional sales to recurring revenue streams. |
| Smart Home Integration Partnership | Wi-Fi diagnostic convergence with Lusail building management systems enables predictive maintenance offerings. |
| Brass Component Backward Integration | In-house burner casting capacity insulates margins from copper commodity volatility on global exchanges. |
| Al Wakrah Service Network Expansion | Technician deployment into renovation corridors captures freestanding unit demand outside incumbent strongholds. |
Research Methodology
Independent corroboration across distributor sales data, KAHRAMAA compliance filings, and developer procurement specifications underwrites the qualitative findings. Primary interviews with appliance distributor principals, KAHRAMAA-authorized installation contractors, Lusail developer procurement officers, and West Bay hospitality chef consultants combined with secondary validation from GSO conformity assessment records, Qatar Chamber of Commerce import statistics, and construction project databases. Bottom-up unit shipment estimates triangulated against top-down construction pipeline valuations across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, installation format, fuel infrastructure, and end-user segmentation dimensions. CAGRs derive from fitted trend extrapolation moderated by regulatory phase-in schedules and infrastructure buildout timelines. Forecast inputs incorporate KAHRAMAA pipeline extension announcements, Lusail green building certification adoption curves, and brass alloy price volatility indices.
The model assumes a particular technology adoption path; alternative pathways for full-kitchen electrification in Pearl-Qatar renovations would alter the outlook. Forecasts reflect assumptions about KAHRAMAA efficiency threshold enforcement consistency and GSO certification processing durations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Faucets Market
Household Items
Air Purifier Market
Household Items
Knife Set Market
Household Items
Drain Cleaners Market
Household Items
Porcelain Tableware Market
Household Items
Toilet Rim Blocks Market
Household Items
Hangers Market
Household Items
Deodorizer Bag Market
Household Items
Toilet Brush Market
Household Items
Leaf Blower Market
Household Items
Europe Ice/Cooler Box Market
Household Items
Water Purifier Bottle Market
Household Items
Sorting Hampers Market
Household Items
Global Electric Scissors Market
Household Items
Desktop Air Purifier Market
Household Items
Washing Capsules Market