
 Portable Stick Market | 2026-2036
Portable Stick Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Stick Market Analytics
Travel enthusiasts is bifurcating from casual photographers as the dominant buyer archetype in portable stick demand. Amazon leverages its marketplace infrastructure to control distribution breadth across multiple product variants. Xiaomi specializes in lightweight carbon fiber designs that anchor its position in Asia-Pacific supply chains. Google competes through ecosystem integration, extending software-hardware compatibility into the portable accessory space.
A portable stick is a handheld, telescoping support device typically constructed from aluminum or carbon fiber tubing with locking mechanisms, designed to stabilize cameras, smartphones, or fishing equipment during outdoor activities. Carbon fiber variants achieve weight reductions below 200 grams while maintaining load capacities exceeding 5 kilograms, enabling extended use in backpacking and alpine environments. The material dimension shows aluminum occupying the volume-dominant tier due to cost accessibility, while carbon fiber captures the fastest-growing segment driven by gram-conscious trekkers and professional photographers. Selfie sticks lead product type revenue pools, though hiking poles are gaining share as trail tourism participation rises across mountain regions.
FDA guidelines for electronic components in smart-enabled sticks, combined with ISO 9001 quality management standards and China's GB national standards for sporting equipment, collectively shape product certification requirements and market access conditions. REACH compliance in Europe restricts certain polymer additives used in grip manufacturing, forcing reformulation of plastic-based handles. Stakeholders must monitor evolving material regulations and smart connectivity integrations to anticipate which specification thresholds will define next-generation procurement criteria.
Market Dynamics
Carbon fiber manufacturing consolidation in China's Zhejiang and Guangdong provinces is compressing material costs and redrawing competitive boundaries for lightweight portable stick producers worldwide.
Growth Catalysts
- Trail Tourism Expansion:Alpine hiking participation in Switzerland, Austria, and Nepal is generating sustained demand for collapsible trekking poles with gram-optimized designs.
- REACH Reformulation Mandates:ECHA restrictions on phthalate-based grip polymers are accelerating bio-based thermoplastic elastomer adoption across European manufacturing lines.
- Smart Device Integration:Bluetooth-enabled selfie sticks with remote shutter functionality are capturing content creator segments on TikTok and Instagram Reels.
Market Restraints
- Carbon Fiber Supply Concentration:Toray Industries, Mitsubishi Chemical, and SGL Carbon control 70% of aerospace-grade precursor supply, creating input bottlenecks for sporting goods tiers.
- Aluminum Price Volatility:LME aluminum contract fluctuations between 2022 and 2024 compressed margins for mid-market manufacturers locked into fixed retail pricing.
- ISO 9001 Certification Burden:Small-batch artisans in Italy's Dolomites region face six-month compliance timelines that delay EU market entry for handcrafted hiking poles.
Strategic Opportunities
- African Safari Tourism:Kenya and Tanzania's lodge-to-trail infrastructure investments are creating first-mover openings for collapsible monopod suppliers serving wildlife photographers.
- India's PLI Scheme:Production-linked incentives for advanced materials manufacturing are attracting carbon fiber composite investments in Gujarat's special economic zones.
- Drone Photography Convergence:Dual-purpose sticks with integrated landing gear extensions are opening adjacent revenue pools among DJI Mavic operators.
Industry Challenges
- Composite Engineering Talent Scarcity:Layup optimization expertise for tapered carbon fiber tubing remains concentrated in Japan's Osaka-Kobe industrial corridor, limiting replication elsewhere.
- Multi-Standard Certification Overlap:Products requiring simultaneous GB, CE, and FCC markings for smart connectivity face conflicting electromagnetic compatibility test protocols.
- Retailer Consolidation Pressure:Amazon's private-label expansion into Basics-branded selfie sticks is compressing shelf access for independent brands without vertical manufacturing control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Stick Market |
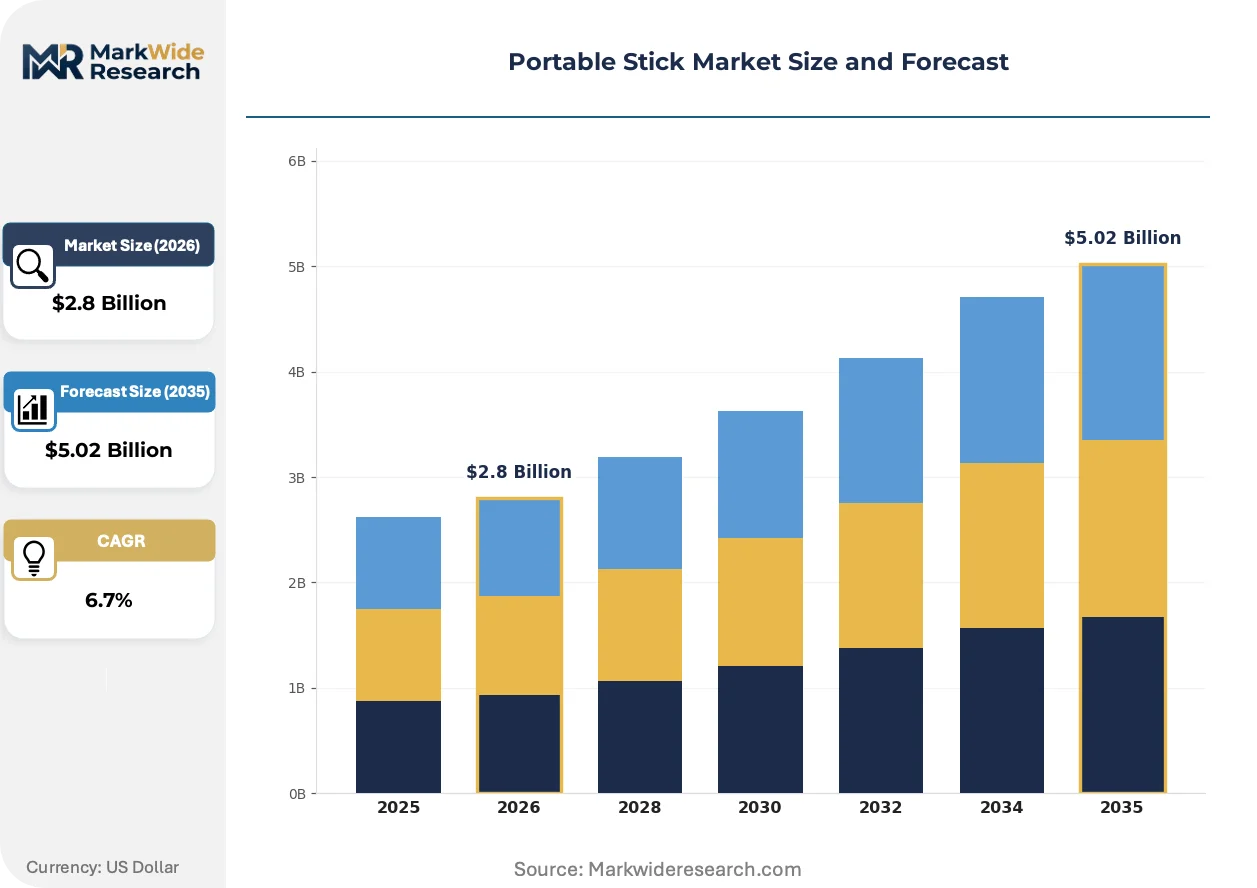
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selfie Stick, Fishing Rod Holder, Hiking Pole, Tripod Stick Material: Aluminum, Carbon Fiber, Plastic, Wood End User: Travel Enthusiasts, Photographers, Campers, Athletes Feature: Extendable, Lightweight, Waterproof, Compact |
| Companies Covered | Amazon, Roku, Google, Apple, Xiaomi, Tencent, Alibaba, Hisense, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Stick Market Evolving Landscape
Material science breakthroughs and regulatory chemistry restrictions are simultaneously enabling performance leaps and forcing formulation overhauls across portable stick manufacturing.
Telescoping carbon fiber tubing with variable wall thickness is decomposing the traditional trade-off between weight minimization and torsional rigidity. Gram-conscious trekkers in the Pacific Northwest and Scottish Highlands are adopting these structures for multi-day traverses. The technology is decomposing aluminum's historical dominance in premium segments where every ounce determines packability ratings.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber grips are compelling European manufacturers to source FSC-certified cork and bio-PU alternatives. ECHA's 2023 update to SVHC candidate lists forced immediate supply chain audits across grip molding facilities in Portugal and Romania. Hiking pole brands targeting German and Austrian retailers now lead compliance documentation as a competitive differentiator.
Direct-to-consumer subscription models with seasonal equipment swaps are disrupting traditional retail cycles for adventure travel gear. Specialty operators like Cairn and Nomadik are bundling carbon fiber trekking poles with curated trail maps and permits. This pattern concentrates in the US Mountain West and British Columbia where annual national park pass holders seek equipment flexibility without ownership burden.
Portable Stick Market Segmentation
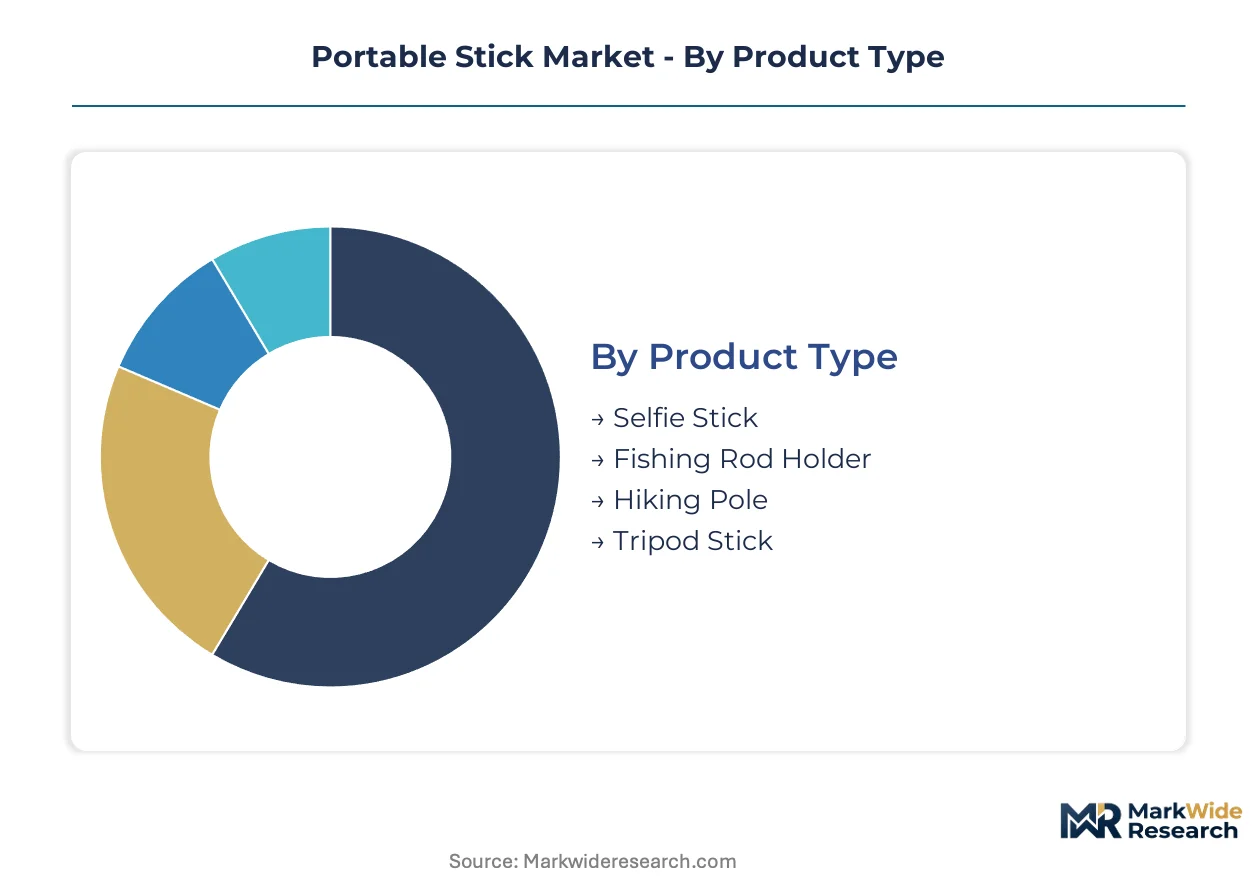
Portable stick procurement patterns diverge sharply across use-case intensity and environmental exposure requirements. Regulatory frameworks for material composition and electronic integration create compliance thresholds that reshape segment prioritization for manufacturers and distributors.
Product Type:
REACH Annex XVII restrictions on grip polymers and China's GB standards for sporting equipment create divergent certification burdens across functional categories, with electronic-enabled variants facing FCC electromagnetic compatibility overlays.
- Selfie Stick:Bluetooth-enabled variants with remote shutter functionality integrate lithium-polymer cells requiring UN 38.3 transport certification and FDA oversight for RF emission thresholds. Demand concentrates among content creators in Shenzhen and Los Angeles, where TikTok and Instagram Reels production volumes drive replacement cycles. Established volume favors Selfie Stick; emerging adoption favors Hiking Pole.
- Hiking Pole:Collapsible trekking poles with twist-lock or lever-lock mechanisms must withstand ISO 9001 load-testing protocols for alpine use. Gram-optimized carbon fiber designs dominate procurement from REI and Decathlon for Pacific Northwest trail systems. Established volume favors Selfie Stick; emerging adoption favors Hiking Pole.
- Fishing Rod Holder:Marine-grade aluminum and carbon fiber composites resist saltwater corrosion per ASTM B117 standards.
- Tripod Stick:Hybrid designs with three-point stabilization target vloggers requiring hands-free positioning.
Established volume favors Selfie Stick; emerging adoption favors Hiking Pole.
Material:
Cost tier stratification separates aerospace-grade carbon fiber from commodity aluminum, with plastic and wood occupying niche sustainability and artisan positioning.
- Aluminum:6061-T6 and 7075 alloys deliver tensile strength above 270 MPa at price points accessible to mass-market retailers. Volume dominance persists in Walmart and Amazon Basics supply chains serving casual photographers and weekend hikers. Established volume favors Aluminum; emerging adoption favors Carbon Fiber.
- Carbon Fiber:T700 and T800 modulus prepregs achieve sub-200 gram weights with 5+ kilogram load ratings, commanding premium positioning at specialty retailers like Backcountry and Bergfreunde. Toray Industries precursor supply constraints limit expansion for mid-tier brands. Established volume favors Aluminum; emerging adoption favors Carbon Fiber.
- Plastic:Glass-filled nylon and ABS variants serve disposable price tiers with limited durability expectations.
- Wood:FSC-certified cork grips and bamboo shafts target European sustainability mandates and Japanese artisan aesthetics.
Established volume favors Aluminum; emerging adoption favors Carbon Fiber.
End User:
Application intensity determines specification thresholds, with professional photographers demanding load-bearing precision and campers prioritizing packability over gram optimization.
- Travel Enthusiasts:Multi-destination content creators require collapsible designs satisfying airline carry-on dimensional restrictions. Procurement concentrates through direct-to-consumer subscription services like Cairn and Nomadik serving annual national park pass holders. Established volume favors Travel Enthusiasts; emerging adoption favors Athletes.
- Photographers:DSLR and mirrorless operators specify Arca-Swiss compatible mounting plates and vibration-dampening carbon fiber layups. Studio and wildlife segments diverge on weight versus stability trade-offs. Established volume favors Travel Enthusiasts; emerging adoption favors Athletes.
- Campers:Overlanding and vanlife participants prioritize multi-function tools combining stick utility with tent pole or awning support.
- Athletes:Trail runners and ski mountaineers drive demand for fixed-length carbon fiber poles below 100 grams per unit.
Established volume favors Travel Enthusiasts; emerging adoption favors Athletes.
Feature:
Customer type bifurcation between gram-conscious thru-hikers and durability-focused family campers shapes feature prioritization in retail assortment planning.
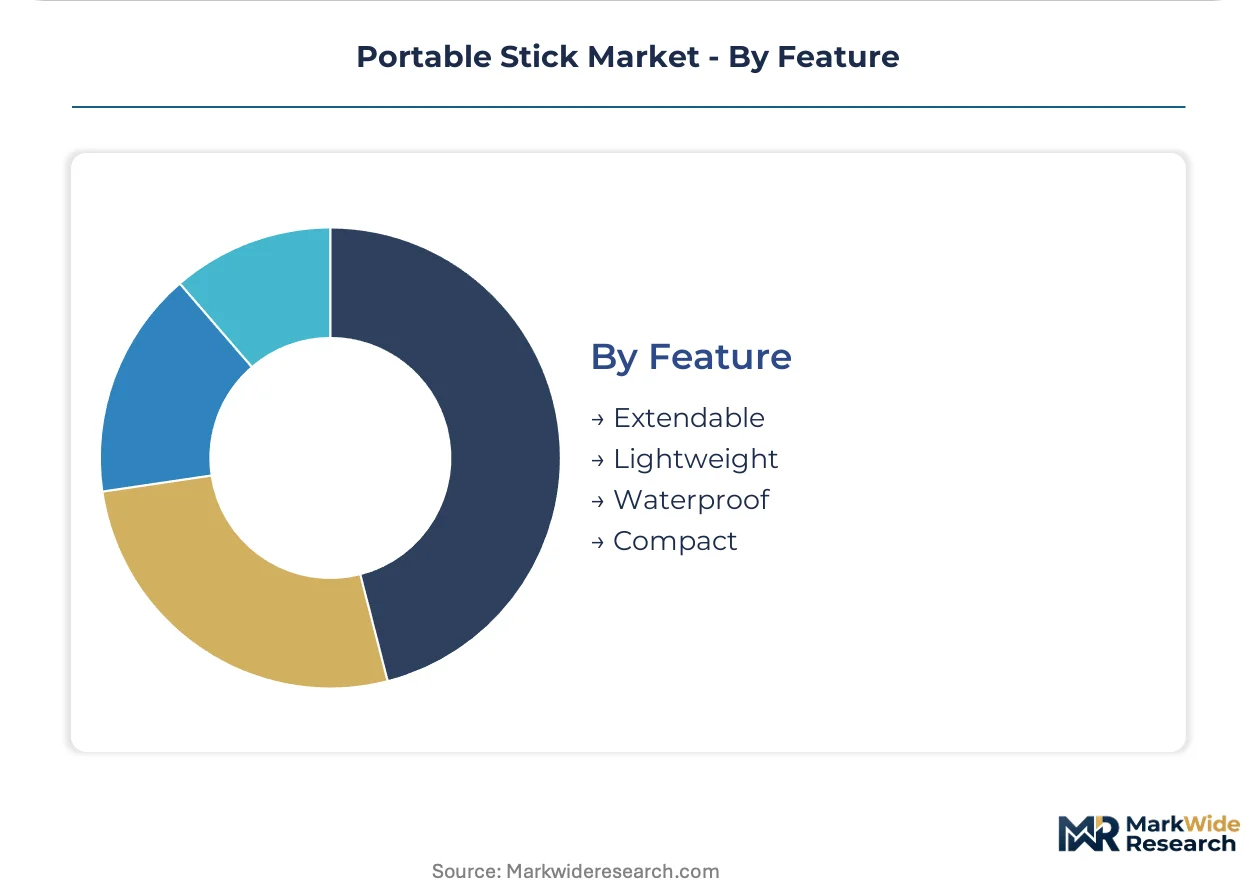
- Extendable:Telescoping mechanisms with twist-lock or flip-lock actuation span 20-150 centimeter ranges, accommodating seated and standing positions. Zhejiang manufacturing clusters specialize in anodized aluminum tube production for OEM supply to European sporting goods brands. Established volume favors Extendable; emerging adoption favors Lightweight.
- Lightweight:Sub-150 gram specifications require tapered carbon fiber tubing with variable wall thickness engineering. Layup optimization expertise concentrates in Japan's Osaka-Kobe corridor, limiting supplier diversification. Established volume favors Extendable; emerging adoption favors Lightweight.
- Waterproof:IPX7-rated electronic integration enables stream-crossing and marine deployment without corrosion failure.
- Compact:30-centimeter collapsed lengths target ultralight backpackers with sub-40 liter pack volumes.
Established volume favors Extendable; emerging adoption favors Lightweight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Travel enthusiasts in China drive the dominant share of portable stick procurement, with domestic manufacturing clusters feeding both local e-commerce channels and export markets across multiple continents.
China
Zhejiang and Guangdong provinces concentrate carbon fiber tubing fabrication for telescoping selfie sticks and hiking poles. GB standards for sporting equipment and MIIT regulations for Bluetooth-enabled variants shape product certification requirements. Shenzhen's electronics ecosystem integrates smart connectivity features for content creator segments.
United States
Pacific Northwest trail systems and national park pass holders generate sustained demand for gram-optimized trekking poles. FCC electromagnetic compatibility protocols govern RF-emitting selfie sticks with remote shutter functionality. Colorado's outdoor retail corridors specialize in subscription-based equipment swaps for adventure travelers.
Germany
Alpine hiking participation in Bavaria drives procurement of collapsible poles with twist-lock mechanisms. ECHA REACH Annex XVII restrictions on phthalate-based grip polymers accelerate bio-based thermoplastic elastomer adoption. Baden-Württemberg's sporting goods distributors lead compliance documentation as competitive differentiation.
Japan
Osaka-Kobe industrial corridor retains concentrated expertise in carbon fiber layup optimization for tapered tubing. METI standards and JIS quality protocols regulate load-bearing specifications for alpine equipment. Tokyo's content creator economy sustains replacement cycles for smartphone stabilization accessories.
India
Gujarat's special economic zones attract carbon fiber composite investments under PLI scheme incentives for advanced materials manufacturing. BIS certification requirements and DGFT export protocols shape market access conditions. Maharashtra's e-commerce logistics hubs facilitate direct-to-consumer distribution for domestic trekking communities.
Portable Stick Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with ecosystem integration capabilities, creating a tiered structure where consumer electronics platforms compete alongside specialized outdoor equipment fabricators. Three archetypes dominate: platform operators leveraging marketplace infrastructure, carbon fiber specialists anchoring premium lightweight segments, and smartphone ecosystem integrators extending hardware compatibility. Competitive moves concentrate on backward integration into carbon fiber precursor supply and geographic expansion through direct-to-consumer subscription channels.
Within the platform operator tier, Amazon exemplifies marketplace-driven distribution breadth across multiple product variants. Xiaomi occupies a position representing lightweight carbon fiber design specialization within Asia-Pacific supply chains. Google anchors the ecosystem integration archetype, extending software-hardware compatibility into portable accessory categories.
| Leading Market Players |
|---|
| Amazon |
| Roku |
| Apple |
| Xiaomi |
| Tencent |
| Alibaba |
| Hisense |
| Sony |
| Others |
Value Network & Pricing Analysis
Carbon fiber precursor economies in Zhejiang and Guangdong provinces compress unit economics for lightweight stick producers while anchoring price floors for aluminum alternatives. Scale concentration in China's manufacturing corridors concentrates bargaining power among Toray Industries and Mitsubishi Chemical feedstock suppliers, forcing mid-tier brands into indexed contract structures that transmit aerospace-grade material premiums downstream.
Pricing Analysis
LME-linked aluminum contracts with quarterly price adjustment clauses dominate procurement for mass-market selfie sticks, while carbon fiber variants operate on fixed-price annual offtakes with aerospace scrap surcharge pass-throughs. Price differentiation rests on certification tier—ISO 9001-compliant hiking poles command shelf space premiums at REI and Decathlon versus uncertified e-commerce imports. Pricing pressure stems from Amazon Basics private-label expansion compressing independent brand margins. Casual photographers exhibit highest price sensitivity, while alpine trekkers prioritize gram optimization over unit cost.
Supply Chain Analysis
Container availability constraints on Shanghai-to-Long Beach lanes elevated inbound logistics costs for US-bound carbon fiber tubing shipments through 2024. Manufacturing gravity centers on China, Japan, and Taiwan, with Osaka-Kobe retaining layup optimization expertise and Taichung hosting precision locking mechanism fabrication. Raw material dependencies include Toray T700 precursor, 6061-T6 aluminum billet, and FSC-certified cork grip stock. Single-source vulnerability concentrates in aerospace-grade carbon fiber supply. Distribution runs through Amazon marketplace infrastructure and specialty outdoor retail networks including Backcountry and Bergfreunde.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retailer consolidation around Amazon's marketplace infrastructure shifted buyer power toward platform operators, fragmenting independent brand pricing autonomy. Three stakeholder archetypes require differentiated positioning responses.
For Market Incumbents: Compound certification investments in ISO 9001 and REACH-compliant grip formulations to defend shelf access against Amazon Basics encroachment. Establish captive carbon fiber precursor relationships through Toray Industries allocation agreements. Prioritize direct-to-consumer subscription channels like Cairn and Nomadik to bypass platform commission structures eroding margin recovery. For New Entrants and Emerging Players: Anchor in India's Gujarat special economic zones to capture PLI scheme incentives for advanced materials manufacturing. Target African safari tourism corridors in Kenya and Tanzania where collapsible monopod demand outpaces established supplier presence. Deploy wildlife photography influencer partnerships as primary go-to-market mechanism. For Investors and Strategic Acquirers: Carbon fiber composite specialists with layup optimization capabilities in Japan's Osaka-Kobe corridor represent priority acquisition targets. Long-term viability hinges on backward integration into precursor supply or downstream subscription channel ownership. Monitor ECHA SVHC candidate list updates as regulatory inflection signals requiring portfolio compliance audits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Toray Industries allocation agreements secure aerospace-grade carbon fiber feedstock against supply bottlenecks. |
| Direct-to-Consumer Subscription Launch | Cairn and Nomadik partnerships bypass Amazon commission structures while capturing national park pass holder loyalty. |
| REACH-Compliant Grip Reformulation | Bio-based thermoplastic elastomer adoption satisfies ECHA Annex XVII restrictions for German and Austrian retail access. |
| Smart Connectivity Integration | Bluetooth-enabled remote shutter functionality captures TikTok and Instagram Reels content creator replacement cycles. |
| African Distribution Partnership | Kenya and Tanzania lodge-to-trail infrastructure investments create first-mover positioning for wildlife photography segments. |
Research Methodology
Desk research of customs trade databases, SEC 10-K filings, and ECHA regulatory updates preceded structured interviews with carbon fiber plant managers, outdoor retail category buyers, sporting goods procurement leads, and trail tourism operators across the analysis window. Primary fieldwork combined with secondary validation from MIIT certification records and ISO audit registries. Bottom-up unit economics modeling triangulated against top-down market sizing from e-commerce transaction data.
Variance decomposition across product type, material grade, end-use intensity, and feature configuration anchored the analytical framework throughout the projection horizon. CAGRs derived from segment-level adoption curves weighted by airline carry-on restriction changes and alpine trail infrastructure investments. Carbon fiber precursor supply constraints and REACH reformulation timelines served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable aerospace-grade material allocation and ECHA regulatory enforcement assumptions; material deviation would warrant model refresh. Forecasts reflect documented base cases without contingency for Toray Industries supply disruption or GB standards revision. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
US Refurbished and Used Mobile Phones Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Smart TV Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Middle East and Africa Refurbished and Used Mobile Phones Market
Consumer Electronics
Portable Laptop Stands Market
Consumer Electronics
Consumer Electronic Accessories Market
Consumer Electronics
Consumer Electronics Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Action Camera Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
North America Smartphone Accessories Market
Consumer Electronics
Gaming Phone Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
FMCG Market