
 FMCG Market | 2026-2036
FMCG Market Size, Share, and Industry Trends Forecast 2026-2036
FMCG Market Analysis
Capital-intensity divergence between multinational conglomerates and regional challengers is rotating competitive dynamics across the FMCG landscape. Procter & Gamble leverages its manufacturing scale to sustain margin advantages in personal care formulations. Nestlé S.A. anchors its position through backward integration into agricultural sourcing networks. Unilever plc competes via channel control in emerging market traditional trade.
Fast-moving consumer goods encompass low-cost, high-velocity products with shelf lives typically under one year, manufactured through continuous batch processing and distributed via multi-tier logistics networks designed for rapid inventory turnover. Food and beverage categories dominate value pools due to non-discretionary purchase frequency, while personal care segments command premium pricing through dermatological certification standards. E-commerce distribution channels represent the fastest-growing structural segment as direct-to-consumer fulfillment reshapes last-mile economics.
The US FDA governs food additive safety and labeling requirements, while the EU Green Deal mandates packaging recyclability thresholds that reshape product design specifications across export-oriented manufacturers. India's FSSAI enforces fortification standards that alter formulation requirements for nutrition-focused SKUs. Stakeholders must monitor how fragmented regulatory timelines across jurisdictions will force parallel compliance investments rather than sequential market entry strategies.
Market Dynamics
Urban millennial household formation is compressing purchase cycles and forcing SKU proliferation across metropolitan retail corridors, while India's PLI scheme for food processing redirects manufacturing investment toward domestic production bases.
Growth Catalysts
- India's PLI scheme for food processing:Production-linked incentives attract capital toward domestic manufacturing facilities, reducing import dependency for packaged food categories.
- Southeast Asian metropolitan corridors:Concentrated demand pools in Jakarta, Bangkok, and Ho Chi Minh City create scale economies for regional distribution networks.
- Fortification mandates:India's FSSAI enforces micronutrient standards that expand addressable market for nutrition-enhanced product lines.
Market Restraints
- Palm oil price volatility:Input cost swings in edible oil formulations compress margin buffers for mass-market food manufacturers.
- EU Green Deal packaging thresholds:Recyclability mandates force parallel R&D investments across export-oriented producers regardless of primary market.
- Traditional trade channel fragmentation:Kirana store density in South Asia inflates last-mile logistics costs relative to modern retail benchmarks.
Strategic Opportunities
- Vietnam's underpenetrated rural hinterland:Provincial distribution gaps offer first-mover advantages for organized FMCG networks beyond Hanoi and Ho Chi Minh City.
- Dermatological certification convergence:Personal care segments command premium positioning through clinical validation standards that mass brands cannot replicate.
- Direct-to-consumer fulfillment:E-commerce platforms reshape inventory economics by collapsing wholesale tiers and enabling micro-segmentation.
Industry Challenges
- Cold chain infrastructure gaps:Temperature-controlled logistics scarcity in tier-2 Indian cities limits perishable SKU expansion.
- FSSAI fortification compliance timelines:Parallel formulation redevelopment strains R&D bandwidth across nutrition-focused portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FMCG Market |
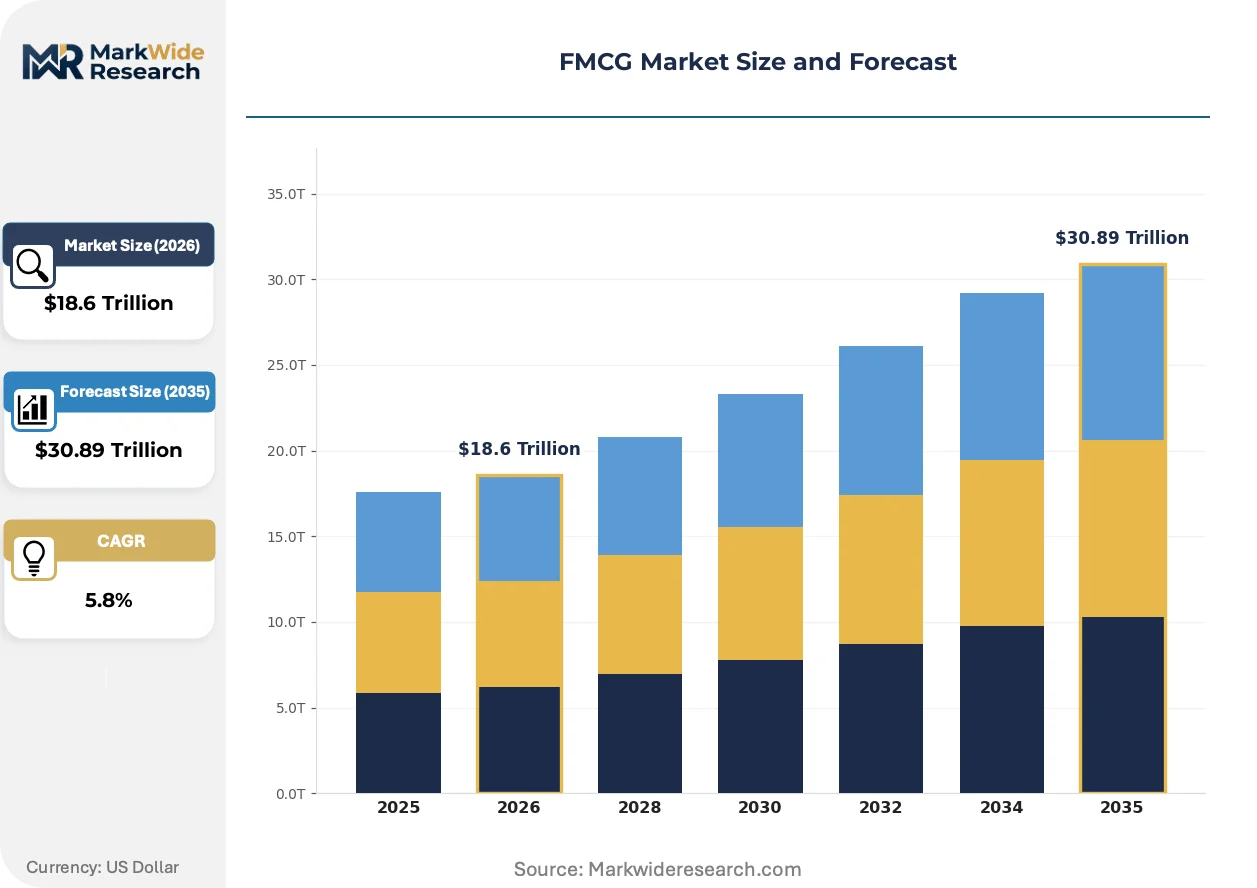
| Market Size in 2026 | $18.6 Trillion |
| Market Size in 2035 | $30.89 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food & Beverage, Personal Care, Household Products, Health Supplements Distribution Channel: Supermarkets, Convenience Stores, E-commerce, Wholesale Price Tier: Premium, Mid-range, Economy, Discount Customer Type: General Consumers, Retailers, E-commerce Platforms, Distributors |
| Companies Covered | PepsiCo, Inc., Mondelez International, Nestlé S.A., Danone, L'Oréal, Procter & Gamble, Unilever plc, General Mills, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FMCG Market Emerging Trajectories
Continuous batch processing is giving way to modular manufacturing architectures that enable rapid SKU rotation and localized formulation adjustments.
Biodegradable packaging polymers are decomposing conventional plastic supply chains. Personal care manufacturers in Germany and France accelerate adoption to preempt EU Green Deal enforcement. This material transition is decomposing established converter relationships and forcing direct partnerships with agricultural feedstock suppliers.
REACH chemical safety registrations are tightening formulation disclosure requirements for cosmetic and household cleaning categories. European manufacturers face elevated compliance costs that disadvantage smaller export-oriented competitors. Personal care segments with complex surfactant chemistries are consolidating supplier bases to reduce documentation burden.
Urban Indian consumers are compressing repurchase cycles for premium personal care through subscription-based replenishment models. Direct-to-consumer platforms bypass traditional wholesale markups in Mumbai and Bangalore metropolitan zones. Beauty and grooming verticals show the fastest channel shift velocity among all FMCG categories.
FMCG Market Segmentation
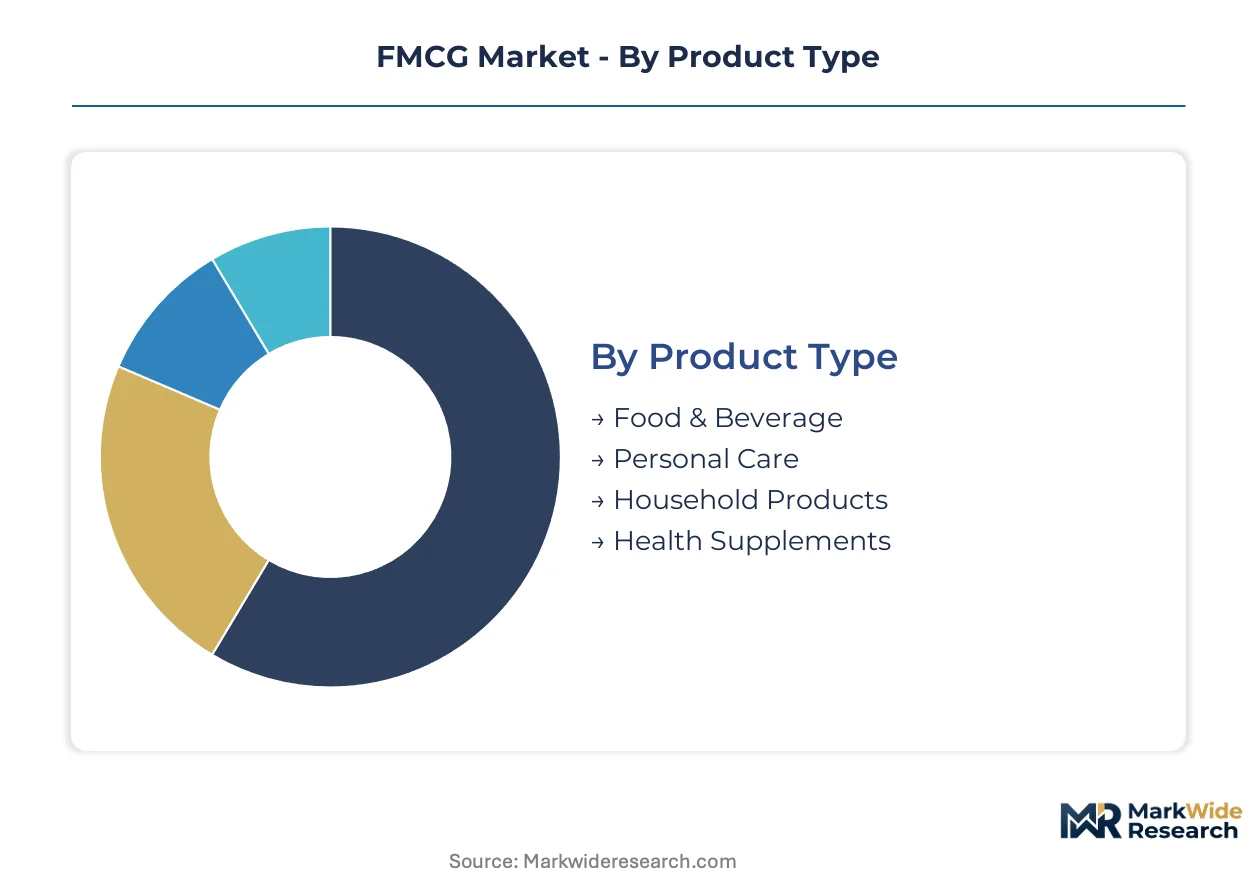
FMCG segmentation determines which products command shelf space in modern trade versus traditional kirana networks. Channel economics vary dramatically across price tiers and customer types, forcing portfolio diversification strategies.
Product Type:
Food and beverage formulations flow through high-frequency traditional trade channels, while personal care SKUs concentrate in modern retail and e-commerce platforms with higher margin capture.
- Food & Beverage:Packaged edibles and beverages with shelf lives under twelve months dominate purchase frequency metrics. Urban Indian households and Southeast Asian metropolitan corridors drive volume concentration, with India's PLI scheme redirecting capital toward domestic manufacturing bases.
- Personal Care:Dermatologically certified formulations command premium positioning through clinical validation standards. Demand clusters in subscription-based direct-to-consumer models across Mumbai and Bangalore metropolitan zones, compressing repurchase cycles among urban millennials.
- Household Products:Surface cleaners and laundry formulations with REACH-registered surfactant chemistries face elevated European compliance costs.
- Health Supplements:Micronutrient-fortified SKUs respond to India's FSSAI fortification mandates, expanding addressable markets for nutrition-enhanced lines.
By volume, Food & Beverage leads. By growth pace, Personal Care is climbing the fastest.
Distribution Channel:
Cost tier determines channel selection—premium SKUs bypass wholesale markups through direct fulfillment, while economy products depend on fragmented traditional trade density.
- Supermarkets:Modern retail formats with controlled temperature zones enable perishable SKU expansion. Concentrated demand in Jakarta, Bangkok, and Ho Chi Minh City metropolitan corridors creates scale economies for regional distribution networks.
- Convenience Stores:High-frequency neighborhood touchpoints with limited SKU breadth prioritize velocity over margin. Cold chain infrastructure gaps in tier-2 Indian cities constrain frozen and chilled product penetration.
- E-commerce:Direct-to-consumer fulfillment platforms collapse wholesale tiers and enable micro-segmentation.
- Wholesale:Bulk distribution to kirana networks and institutional buyers maintains relevance in underpenetrated provincial hinterlands.
Supermarkets capture the highest basket values. E-commerce platforms are expanding most quickly.
Price Tier:
Application context shapes tier selection—daily-use staples concentrate in economy and mid-range bands, while occasion-based and gift-oriented purchases migrate toward premium positioning.
- Premium:Dermatologically certified personal care and fortified nutrition products with clinical validation standards. EU Green Deal packaging recyclability thresholds force parallel R&D investments regardless of primary market.
- Mid-range:Mass-market formulations balancing quality perception with accessibility for urban millennial household formation.
- Economy:High-velocity essentials with compressed margins vulnerable to palm oil price volatility in edible oil formulations.
- Discount:Value-positioned SKUs for price-sensitive rural consumers in Vietnam's underpenetrated provincial distribution gaps.
Economy tiers move the highest unit volumes. Premium segments deliver the steepest margin expansion.
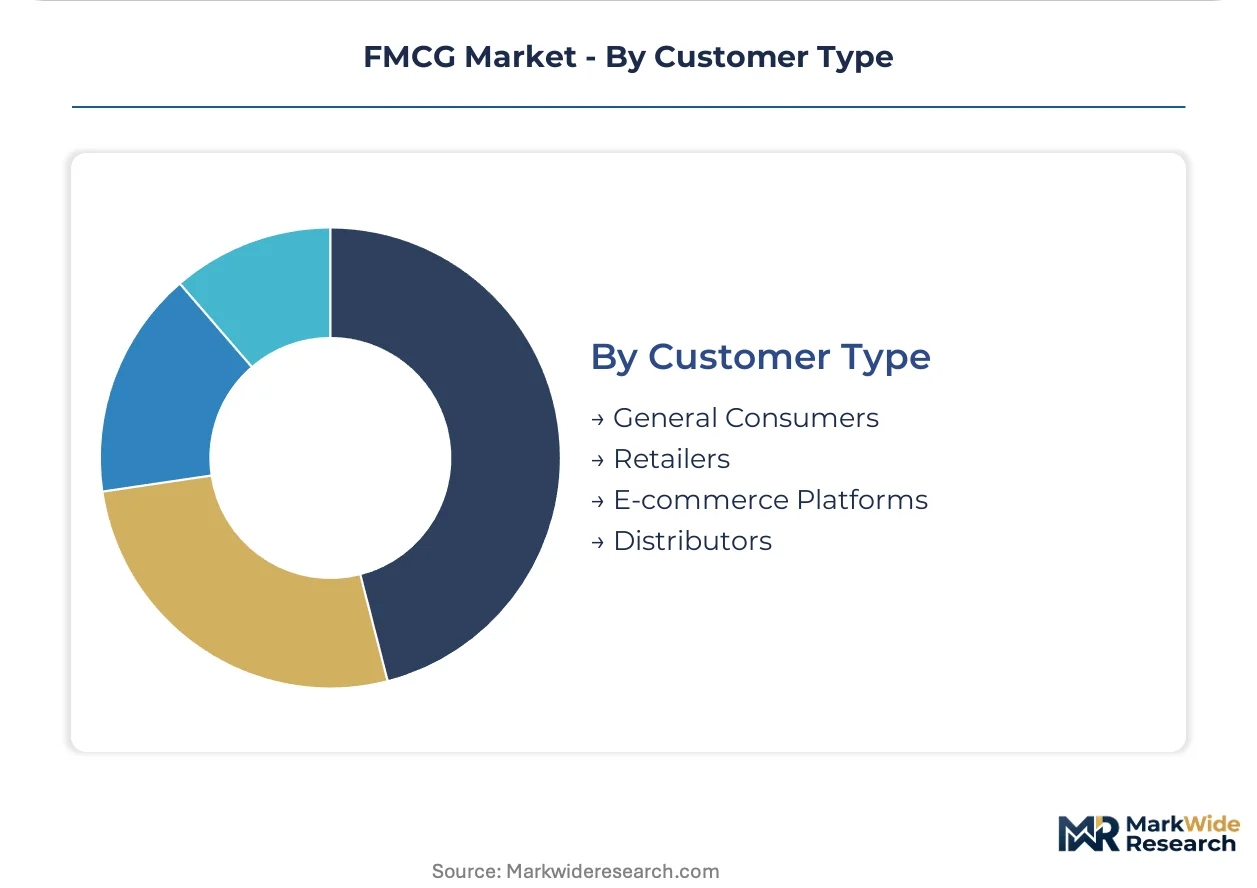
Customer Type:
Volume scale separates customer segments—e-commerce platforms and large-format retailers negotiate centralized procurement terms, while fragmented distributor networks inflate last-mile logistics costs.
- General Consumers:End-users purchasing through retail or digital touchpoints with compressed repurchase cycles in subscription-based replenishment models.
- Retailers:Kirana store operators in South Asia and modern trade buyers in Southeast Asian metropolitan corridors with divergent payment terms and inventory turnover requirements.
- E-commerce Platforms:Direct-to-consumer fulfillment operators reshaping inventory economics by collapsing wholesale tiers.
- Distributors:Multi-tier logistics intermediaries serving traditional trade fragmentation with elevated working capital intensity.
Retailers handle the broadest SKU assortment. E-commerce platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian consumers exhibit the highest price elasticity in rural hinterlands, while German and US buyers absorb premium positioning with minimal volume contraction. Southeast Asian metropolitan corridors display bifurcated demand—mass-market essentials in traditional trade alongside subscription-based personal care in digital channels.
India
Urban millennial household formation compresses repurchase cycles for beauty and grooming SKUs in Mumbai and Bangalore. The FSSAI fortification mandate forces parallel formulation redevelopment across nutrition-focused portfolios. Cold chain infrastructure gaps in tier-2 cities constrain perishable expansion beyond Delhi-NCR and Maharashtra industrial corridors.
United States
Subscription-based replenishment models reshape inventory economics for dermatologically certified personal care. The FDA governs food additive safety and labeling requirements with strict enforcement timelines. E-commerce fulfillment platforms in New York and Los Angeles metropolitan zones collapse wholesale tiers fastest among all regional markets.
Germany
REACH chemical safety registrations tighten formulation disclosure requirements for household cleaning surfactants. The EU Green Deal packaging recyclability thresholds force R&D investment regardless of primary market destination. Biodegradable polymer adoption accelerates in Frankfurt and Munich manufacturing clusters to preempt enforcement.
Vietnam
Underpenetrated provincial distribution gaps beyond Hanoi and Ho Chi Minh City offer first-mover scale advantages. The country's national food safety authority enforces evolving fortification standards that alter import requirements. Organized FMCG networks concentrate capital in Mekong Delta agricultural processing zones to capture backward integration efficiencies.
Brazil
Mass-market food manufacturers face margin compression from edible oil input volatility across São Paulo state production bases. ANVISA regulates cosmetic and food contact material safety with documentation burdens that disadvantage smaller exporters. Modern retail expansion in Rio de Janeiro and Minas Gerais creates channel conflict with entrenched traditional trade density.
FMCG Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the FMCG structure. Multinational conglomerates leverage manufacturing scale and captive agricultural sourcing networks to defend margin positions. Regional challengers compete through channel control in fragmented traditional trade and localized formulation agility. Dominant competitive moves include backward integration into feedstock supply and direct-to-consumer platform development that collapses wholesale intermediaries.
Within the integrated multinational tier, Nestlé S.A. and Unilever plc exemplify divergent strategic postures—one anchoring position through upstream agricultural control, the other through emerging market distribution density. Procter & Gamble occupies a position at the scale-driven end of personal care manufacturing. These three entities represent the archetype of capital-intensity advantages that smaller regional competitors cannot replicate without parallel compliance investment across FDA, EFSA, and FSSAI jurisdictions.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| Mondelez International |
| Nestlé S.A. |
| Danone |
| L'Oréal |
| Procter & Gamble |
| Unilever plc |
| General Mills |
| The Coca-Cola Company |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for palm oil derivatives directly tether margin buffers to Southeast Asian sourcing concentration, compressing pricing power for mass-market edible oil manufacturers while premium personal care formulations escape this cost structure through dermatological certification premiums.
Pricing Analysis
After-sales subscription revenue for beauty and grooming SKUs now drives lifetime value compression in Mumbai and Bangalore metropolitan zones. Three-tier pricing structure across premium, standard, and economy levels stratifies by FSSAI fortification compliance grade and REACH chemical safety registration status. Pricing pressure stems from palm oil price volatility in economy-tier food formulations. Rural Indian households exhibit highest price sensitivity; German consumers absorb premium positioning with minimal volume contraction.
Supply Chain Analysis
Indonesia and Malaysia anchor global palm oil feedstock production, while India and Vietnam concentrate packaged food manufacturing and agricultural processing capacity. Raw material dependencies rest on palm oil derivatives, biodegradable polymer feedstocks, and REACH-registered surfactant chemistries. Single-source vulnerability in Southeast Asian edible oil supply creates margin exposure for mass-market manufacturers. Distribution runs through multi-tier logistics networks serving kirana store density in South Asia alongside direct-to-consumer fulfillment platforms in metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of cold chain infrastructure in tier-2 Indian cities limits perishable SKU expansion, creating capability gaps that favor capital-rich players with parallel compliance investments across FDA, EFSA, and FSSAI jurisdictions.
For Market Incumbents: Consolidate backward integration into agricultural sourcing networks to defend margin positions against regional challengers. Expand captive palm oil refining capacity in Indonesia and Malaysia to neutralize input cost volatility. Prioritize FSSAI fortification compliance investments ahead of enforcement timelines to lock out smaller competitors lacking R&D bandwidth.
For New Entrants and Emerging Players: Direct-to-consumer fulfillment gaps in Vietnam's provincial hinterlands beyond Hanoi and Ho Chi Minh City offer white-space entry points. Subscription-based replenishment models for premium personal care in tier-2 Indian cities remain under-penetrated. Launch through e-commerce platforms with micro-segmented SKU portfolios to bypass entrenched wholesale tier markups.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because capital-intensity divergence between multinational conglomerates and regional challengers is accelerating competitive exits. Target mid-tier personal care manufacturers with dermatological certification capabilities and established FSSAI compliance infrastructure. Watch cold chain infrastructure buildout in Indian tier-2 cities as the inflection signal for perishable SKU expansion viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Sourcing | Captive palm oil supply from Indonesia and Malaysia neutralizes input cost volatility for mass-market formulations. |
| Direct-to-Consumer Platform Launch | Subscription models in Mumbai and Bangalore collapse wholesale markups and compress repurchase cycles for beauty SKUs. |
| Biodegradable Packaging Transition | EU Green Deal compliance in German manufacturing clusters preempts recyclability enforcement and secures export access. |
| FSSAI Fortification Compliance Investment | Parallel formulation redevelopment ahead of enforcement timelines locks out smaller competitors lacking R&D scale. |
| Provincial Distribution Network Expansion | First-mover scale advantages in Vietnam's Mekong Delta agricultural processing zones capture backward integration efficiencies. |
Methodological Framework
Desk research of trade flow databases, customs records, and regulatory filing repositories preceded structured interviews with brand managers, category buyers at modern retail chains, channel sales heads, and supply planners across India, Southeast Asia, and European manufacturing clusters. Primary fieldwork with FMCG distribution partners and cold chain logistics operators validated secondary data on inventory turnover metrics and last-mile cost structures. Bottom-up SKU-level volume estimates triangulated against top-down macroeconomic consumption indicators.
Variance decomposition across product type, distribution channel, price tier, and customer type segmentation dimensions anchored the analytical framework over the projection horizon. CAGRs derived from trend extrapolation of historical volume trajectories adjusted for PLI scheme capital injection effects and EU Green Deal compliance cost pass-through assumptions. Forecast inputs incorporated palm oil price volatility bands and FSSAI fortification mandate implementation timelines.
Underlying assumptions cover sustained urban millennial household formation rates and stable regulatory enforcement timelines across jurisdictions, with deviation risk concentrated in palm oil commodity price spikes and cold chain infrastructure buildout delays. Recalibration cycles align with material shifts in PLI scheme disbursement patterns and EU packaging recyclability threshold enforcement dates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Dive Computer Market
Consumer Electronics
Wrist Watch Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Europe Gaming Headset Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Europe Cigarette Lighter Market
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
Mobile Accessories Market
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Smart Headphones Market
Consumer Electronics
Baby Monitor Market
Consumer Electronics
Smart Connected TV Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Smart Television and Set-Top Box Market
Consumer Electronics
Gaming Laptop Market
Consumer Electronics
Asia-Pacific Refurbished and Used Mobile Phones Market