
 Consumer Electronic Accessories Market | 2026-2036
Consumer Electronic Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Electronic Accessories Market Analysis
Remote workforce adoption is expanding across enterprise and educational segments, pulling procurement volume toward noise-canceling headphones and multi-device charging hubs. Apple Inc. leverages its proprietary connector ecosystem to sustain premium pricing power and repeat purchase cycles. Samsung Electronics Co. Ltd. anchors its accessories portfolio through deep integration with Galaxy device ecosystems and retail shelf dominance. Anker Innovations Limited specializes in gallium nitride charging technology, competing aggressively on wattage density and thermal efficiency.
Consumer electronic accessories comprise peripheral devices and supplementary components that extend, protect, or enhance the functionality of primary electronic hardware, typically incorporating polymers, lithium-ion cells, copper windings, and semiconductor controllers manufactured through injection molding, PCB assembly, and acoustic tuning processes. Their commercial purpose centers on improving user experience, device longevity, and interoperability across fragmented hardware platforms. Headphones and chargers capture the largest margin pools, with Bluetooth-enabled wireless variants outpacing wired alternatives in revenue contribution. Cases and screen protectors operate as high-volume, low-margin categories where online retail channels dominate replenishment purchases.
The FCC enforces electromagnetic interference standards for wireless accessories sold in the United States, while the EU Green Deal and RoHS directives restrict hazardous substances in cables and batteries, compelling suppliers to reformulate solder compositions and eliminate PVC jacketing. India's BIS certification mandates safety testing for chargers and power adapters, creating compliance barriers for unbranded imports. Stakeholders must monitor evolving right-to-repair regulations and interoperability mandates that could force ecosystem openness and erode proprietary connector advantages.
Market Dynamics
Wireless charging interoperability mandates from the Wireless Power Consortium are forcing ecosystem consolidation across charger manufacturers, while India's PLI scheme for domestic electronics assembly is redrawing regional supply footprints.
Growth Catalysts
- Hybrid learning stabilization:Educational institutions in North America and Europe are standardizing device-per-student policies, pulling procurement volume toward protective cases and charging carts.
- RoHS directive reformulation:The EU's restriction on hazardous substances in cables is accelerating halogen-free jacketing adoption, creating first-mover advantages for compliant suppliers.
- Gallium nitride maturation:Thermal efficiency gains in GaN semiconductors are enabling 100W+ chargers in palm-sized form factors, unlocking premium positioning in mobile workstation accessories.
Market Restraints
- Lithium-ion cell concentration:Cathode active material supply chains concentrate in East Asian chemical processors, exposing margin compression from input volatility.
- BIS certification timelines:India's mandatory safety testing for power adapters creates 12-16 week approval bottlenecks, freezing inventory turns for unbranded imports.
- Copper winding cost exposure:Magnet wire for inductive charging coils tracks LME copper pricing with limited hedging instruments available to mid-tier assemblers.
Strategic Opportunities
- Right-to-repair momentum:Draft EU legislation mandating standardized fasteners and battery accessibility is creating aftermarket parts ecosystems for out-of-warranty devices.
- Enterprise noise-canceling deployment:Open-plan office retrofits in Germany and the United Kingdom are pulling bulk orders for ANC headsets with unified communications certification.
- Qi2 magnetic alignment:The Wireless Power Consortium's updated standard integrating MagSafe-style positioning is converging accessory design across Android and iOS ecosystems.
Industry Challenges
- Acoustic engineering talent scarcity:Active noise cancellation algorithm development requires specialized DSP firmware expertise concentrated in Scandinavian and Taiwanese audio houses.
- Multi-jurisdiction certification stacking:Simultaneous FCC, CE, and BIS testing for global charger SKUs extends product launch timelines and fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Electronic Accessories Market |
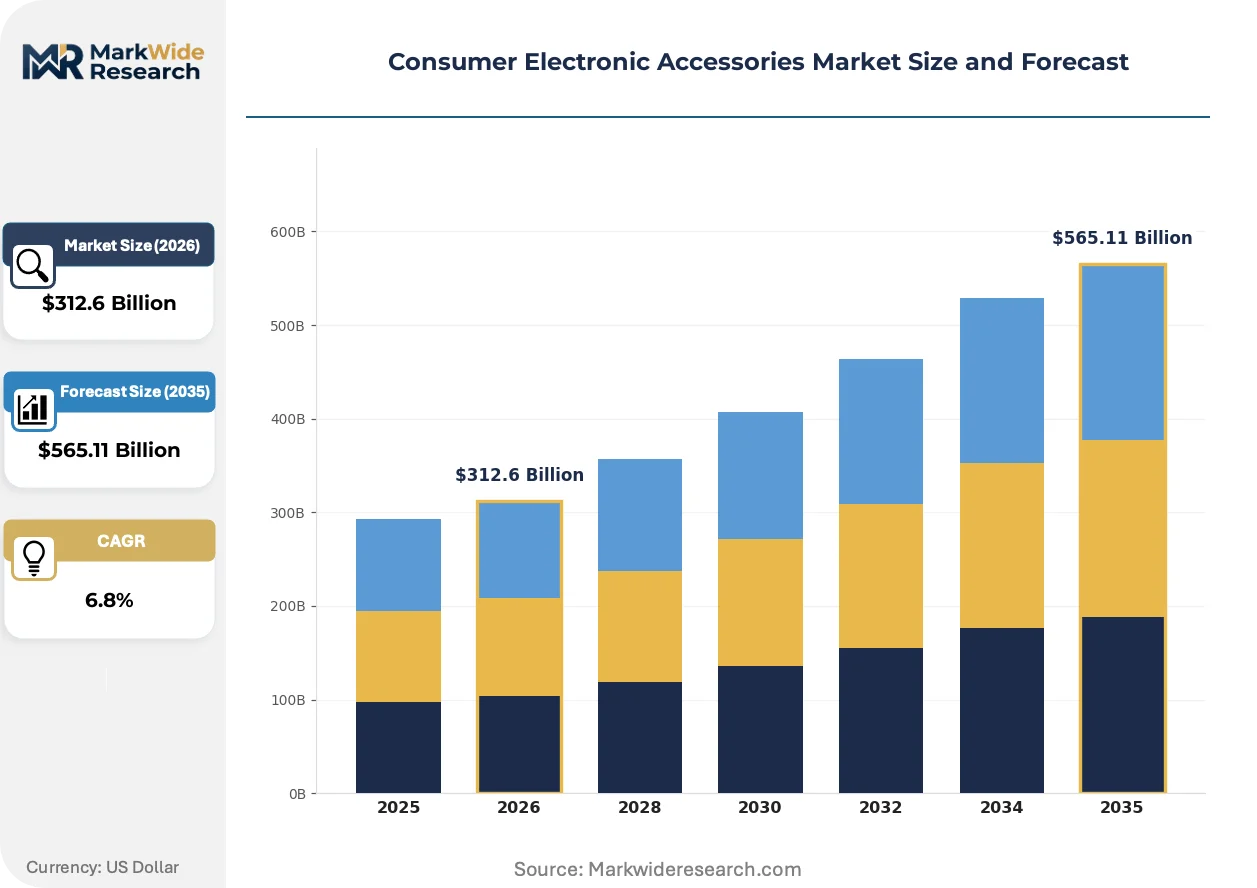
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chargers, Cases, Screen Protectors, Headphones Technology: Bluetooth, Wired, Wireless, NFC End User: Consumers, Businesses, Educational Institutions, Retailers Distribution Channel: Online Retail, Physical Stores, Wholesale, Direct Sales |
| Companies Covered | LG Electronics Inc., Bose Corporation, Apple Inc., Xiaomi Corporation, Panasonic Corporation, Samsung Electronics Co. Ltd., Logitech International S.A., Anker Innovations Limited, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Electronic Accessories Market Emerging Trajectories
Three converging forces are restructuring competitive positioning: semiconductor material transitions in power electronics, regulatory pressure on circular design, and enterprise procurement centralization around sustainability credentials.
Gallium nitride power ICs are electrifying the charger category by collapsing thermal management footprints while sustaining wattage density. Mobile workstation users and creative professionals are adopting 140W GaN adapters within 18-month replacement cycles. This semiconductor transition is compressing incumbent silicon-based supply chains and enabling wall-wart designs previously impossible at equivalent power levels.
The EU Green Deal's ecodesign requirements for smartphones are mandating USB-C universal charging ports and standardized battery replacement protocols by 2027. Accessory manufacturers must redesign dock connectors and power delivery controllers to accommodate the harmonized voltage profiles. German and French retailers are already delisting non-compliant SKUs ahead of enforcement deadlines, accelerating inventory obsolescence for proprietary connector ecosystems.
Enterprise IT departments are consolidating peripheral procurement around carbon disclosure ratings and modular repairability scores. Dell and HP device fleets now specify TCO Certified and EPEAT Gold accessories in RFP criteria, displacing consumer-grade SKUs from corporate channels. This specification tightening is most visible in Nordic public sector tenders, where lifecycle assessment documentation carries mandatory weighting in award decisions.
Consumer Electronic Accessories Market Segmentation
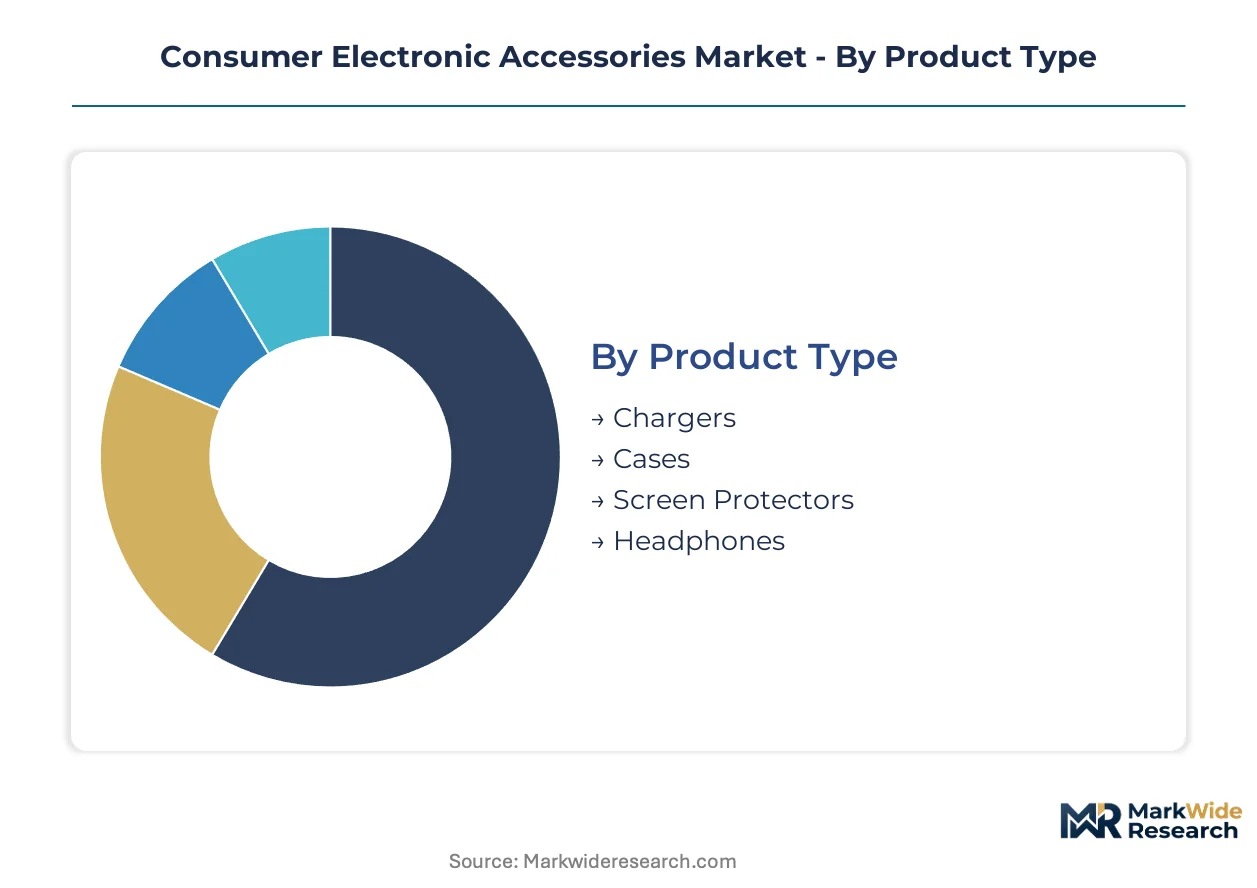
Consumer electronic accessories fragment across four structural dimensions that determine margin capture and channel strategy. Product type and technology layers define hardware interoperability requirements, while end-user and distribution splits govern pricing architecture and replenishment velocity.
Product Type:
Integration depth varies sharply: chargers and headphones operate as standalone peripherals with independent replacement cycles, while cases and screen protectors embed directly onto host devices as protective layers.
- Chargers:Gallium nitride semiconductors enable 100W+ output in compact form factors. Demand concentrates among mobile workstation users in Germany and the United States, pulled by thermal efficiency gains and USB-C harmonization mandates.
- Headphones:Active noise cancellation algorithms require specialized DSP firmware from Scandinavian and Taiwanese engineering houses. Enterprise procurement in the United Kingdom and Germany is standardizing ANC headsets with unified communications certification for open-plan deployments.
- Cases:Injection-molded polymer shells with antimicrobial coatings dominate educational bulk orders. Volume placements concentrate in India where domestic manufacturing incentives accelerate local assembly.
- Screen Protectors:Tempered glass and TPU film variants compete on hardness ratings and optical clarity. Online retail channels capture the majority of replenishment purchases due to low price points and standardized sizing.
Volume placements concentrate in chargers; the faster expansion belongs to headphones.
Technology:
Cost tier stratification separates premium wireless implementations from commodity wired alternatives, with semiconductor content and certification complexity driving the wedge.
- Bluetooth:Low-energy protocols enable multi-device pairing and extended battery life in audio accessories. Premium positioning in the United States and Germany reflects codec support for lossless streaming and gaming latency reduction.
- Wireless:Qi and Qi2 inductive charging standards from the Wireless Power Consortium are converging accessory design across Android and iOS ecosystems. India's BIS certification creates 12-16 week approval bottlenecks for unbranded imports.
- Wired:USB-C and Lightning connectors retain share in cost-sensitive segments and latency-critical gaming peripherals. EU Green Deal mandates for universal charging ports are accelerating obsolescence of proprietary connector ecosystems.
- NFC:Near-field communication enables tap-to-pair functionality and authentication in premium audio accessories. Limited deployment reflects higher bill-of-materials costs and fragmented Android implementation.
Volume placements concentrate in wired technology; the steepest expansion trajectory belongs to wireless charging standards.
End User:
Customer type determines specification tightening, with enterprise and educational procurement centralizing around sustainability credentials and modular repairability scores.
- Consumers:Individual purchasers drive replacement cycles in cases and screen protectors through online impulse buying. Price sensitivity dominates, with private-label SKUs capturing significant share in India and Southeast Asian markets.
- Businesses:Enterprise IT departments specify TCO Certified and EPEAT Gold accessories in RFP criteria for Dell and HP device fleets. Nordic public sector tenders mandate lifecycle assessment documentation with mandatory weighting in award decisions.
- Educational Institutions:Device-per-student policies in North American and European schools pull procurement volume toward protective cases and charging carts. Hybrid learning stabilization has standardized bulk purchasing rhythms.
- Retailers:Private-label accessories and licensed character merchandising target gift and impulse segments. Shelf placement negotiations with Apple and Samsung retail partners determine visibility and margin splits.
Volume placements concentrate in consumer segments; the fastest share gain belongs to educational institutions.
Distribution Channel:
Supply concentration in East Asian manufacturing clusters shapes channel economics, with direct import relationships favoring wholesale and direct sales over intermediated retail.
- Online Retail:Amazon and specialized electronics marketplaces dominate case and screen protector replenishment. Algorithmic search placement and review velocity determine SKU visibility and conversion rates.
- Physical Stores:Carrier stores and electronics chains anchor charger and headphone discovery through tactile demonstration. Staff commission structures favor higher-margin wireless and noise-canceling variants.
- Wholesale:Distributors aggregate unbranded and white-label accessories for regional retail chains. India's PLI scheme for domestic electronics assembly is redrawing regional supply footprints toward local assembly hubs.
- Direct Sales:Manufacturer-owned channels capture premium positioning through ecosystem bundling and warranty integration. Apple's proprietary connector ecosystem sustains repeat purchase cycles through forced compatibility.
Volume placements concentrate in online retail; the fastest channel expansion belongs to direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme for electronics assembly has concentrated charger and audio accessory manufacturing in Noida and Sri City special economic zones, pulling component suppliers from Shenzhen and Taipei into domestic joint ventures.
United States
Enterprise IT refresh cycles in Austin and Seattle metro areas are standardizing USB-C charging infrastructure for hybrid workforces. The FCC enforces electromagnetic interference standards that extend product launch timelines for unbranded imports. Manufacturing concentrates in Texas and California for final assembly of premium audio accessories serving corporate procurement channels.
Germany
Open-plan office retrofits in Berlin and Hamburg are pulling bulk orders for ANC headsets with unified communications certification. The EU Green Deal's ecodesign requirements mandate USB-C universal charging ports by 2027, accelerating obsolescence of proprietary connector ecosystems. Industrial clusters in Bavaria specialize in acoustic engineering for automotive-grade noise cancellation algorithms.
India
Domestic manufacturing incentives under the PLI scheme are accelerating local assembly of chargers and audio accessories in Noida and Sri City. BIS certification mandates 12-16 week safety testing approval timelines for power adapters, freezing inventory turns for unbranded imports. Tamil Nadu and Karnataka host expanding electronics manufacturing clusters supplying educational institution procurement.
China
Shenzhen and Dongguan manufacturing hubs dominate magnet wire winding and PCB assembly for inductive charging coils. MIIT standards harmonization with Qi2 magnetic alignment protocols is converging accessory design specifications. Yangtze River Delta clusters specialize in gallium nitride semiconductor packaging for compact high-wattage chargers.
United Kingdom
Educational device-per-student policies in London and Manchester are standardizing protective case and charging cart procurement rhythms. CE marking requirements under EU-UK trade continuity agreements maintain RoHS directive compliance for halogen-free cable jacketing. Scottish enterprise zones are attracting acoustic engineering talent for DSP firmware development.
Consumer Electronic Accessories Market Vendor Landscape
Top-tier vendors anchor ecosystem-integrated premium positioning, while mid-tier specialists compete on semiconductor efficiency and certification agility. The vendor base stratifies across proprietary connector ecosystems, gallium nitride charging technology, and acoustic engineering houses. Three archetypes dominate: ecosystem-locked incumbents leveraging forced compatibility, semiconductor-focused power specialists, and audio houses with DSP firmware concentration. Competitive moves center on backward integration into GaN semiconductor supply and geographic expansion into India's PLI-subsidized manufacturing zones.
Within the ecosystem-locked tier, Apple Inc. and Samsung Electronics Co. Ltd. exemplify proprietary connector strategies that sustain repeat purchase cycles through forced compatibility requirements. Anker Innovations Limited occupies a position among power specialists competing on thermal efficiency and wattage density. These three anchors represent divergent strategic postures: closed-ecosystem premium capture, retail shelf dominance through device bundling, and component-level semiconductor differentiation.
| Leading Market Players |
|---|
| LG Electronics Inc. |
| Bose Corporation |
| Apple Inc. |
| Xiaomi Corporation |
| Panasonic Corporation |
| Samsung Electronics Co. Ltd. |
| Logitech International S.A. |
| Anker Innovations Limited |
| Sony Corporation |
| Others |
Supply Flow & Price Mechanics
Enterprise IT procurement departments in Germany and the United States anchor pricing power for TCO Certified and EPEAT Gold accessories, compressing margin capture for non-compliant suppliers through specification tightening in RFP criteria.
Pricing Analysis
Short lead-time premiums for gallium nitride chargers with BIS certification in India command substantial markups over spot inventory from unbranded Shenzhen suppliers. Three-tier pricing structure across premium, standard, and economy levels separates ecosystem-locked Apple and Samsung SKUs from white-label alternatives, with certification grade and thermal wattage density as primary price differentiation drivers. Cost compression in mid-tier silicon-based chargers is intensifying because GaN semiconductor transitions displace legacy thermal management designs. Educational institutions in North America exhibit highest price sensitivity due to bulk procurement volumes, while enterprise buyers in Nordic markets show least sensitivity given mandatory sustainability documentation weighting.
Supply Chain Analysis
Reverse-logistics flows for out-of-warranty device refurbishment are emerging through EU right-to-repair mandates, creating aftermarket parts ecosystems that compete with original manufacturer replenishment cycles. Manufacturing concentration spans China for magnet wire winding and PCB assembly, India for PLI-subsidized charger and audio accessory assembly, and Taiwan for gallium nitride semiconductor packaging. Raw material dependencies draw from lithium-ion cells for battery packs, copper windings for inductive charging coils, and halogen-free polymers for RoHS-compliant cable jacketing. Single-source vulnerability in East Asian cathode active material processors exposes margin compression from input volatility. Distribution runs through Amazon and specialized electronics marketplaces for case and screen protector replenishment, with carrier stores anchoring charger and headphone discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around semiconductor material transitions and certification agility, with gallium nitride specialization and BIS compliance timelines forcing weaker assemblers into white-label absorption or exit.
For Market Incumbents: Lock in backward integration into gallium nitride semiconductor supply through joint ventures with Yangtze River Delta packaging houses, insulating thermal efficiency advantages from spot-market silicon displacement. Deepen channel control through direct sales ecosystem bundling that forces repeat purchase cycles via proprietary connector compatibility, defending against Qi2 magnetic alignment standardization that erodes ecosystem lock-in. For New Entrants and Emerging Players: The price-point gap between premium ANC headsets with unified communications certification and economy wired alternatives presents white-space capture opportunity in mid-tier Bluetooth audio for hybrid workforce segments. India's PLI-subsidized manufacturing zones offer the most penetrable geography given 12-16 week BIS bottlenecks freezing unbranded import competition. Pursue white-label partnerships with educational procurement channels standardizing device-per-student protective case and charging cart deployments. For Investors and Strategic Acquirers: The window for entry favors acoustic engineering houses with concentrated DSP firmware talent in Scandinavian and Taiwanese clusters, positioned for enterprise noise-canceling deployment acceleration. Long-term viability hinges on acquisition targets with captive gallium nitride semiconductor relationships and modular repairability scores aligned with EU ecodesign trajectories. Monitor Wireless Power Consortium Qi2 adoption velocity across Android OEMs as inflection indicator for proprietary connector ecosystem erosion.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Backward Integration | Captures thermal efficiency advantages from Yangtze River Delta packaging specialization. |
| BIS Certification Pre-Positioning | Accelerates market access ahead of 12-16 week approval bottlenecks freezing unbranded imports. |
| Qi2 Magnetic Alignment Adoption | Converges accessory design specifications across Android and iOS ecosystem fragmentation. |
| Enterprise Sustainability Certification | Unlocks Nordic public sector tenders mandating TCO Certified and EPEAT Gold documentation. |
| Educational Channel Direct Sales | Captures bulk procurement rhythms from standardized device-per-student policy implementation. |
Methodological Framework
Trade databases, customs records, and SEC filings from accessory manufacturers formed the secondary backbone, triangulated against primary interviews with procurement officers at Dell and HP device fleets, category buyers at Amazon and carrier retail channels, acoustic engineering directors at Scandinavian audio houses, and PLI scheme administrators in Tamil Nadu and Karnataka. Bottom-up SKU-level analysis of charger wattage tiers, headphone ANC certification status, and case antimicrobial coating specifications was cross-validated against top-down expenditure flows from educational institution bulk purchasing and enterprise IT refresh cycles.
Bottom-up modeling aggregated unit economics across gallium nitride and silicon-based charger architectures, Bluetooth codec tier stratification, and polymer injection-molding cost curves, while top-down validation tracked regional procurement expenditure patterns across the analysis window. Segmentation dimensions spanned product type integration depth, technology cost tier stratification, end-user specification tightening, and distribution channel concentration. CAGRs were derived from replacement cycle compression in mobile workstation power adapters and hybrid learning stabilization in educational protective case procurement.
Inputs from BIS certification databases and Wireless Power Consortium standardization timelines were available through the study window; gaps in real-time lithium-ion cell spot pricing and copper LME forward curves introduce uncertainty bands around margin projections. Forecasts reflect assumptions around PLI scheme continuation, RoHS directive enforcement sequencing, and right-to-repair legislative passage. Practitioners should monitor Qi2 OEM adoption rates, GaN semiconductor capacity expansion announcements, and Nordic tender sustainability documentation weighting adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Japan Gaming Peripherals Market
Consumer Electronics
Consumer Electronics Retail Market
Consumer Electronics
Screen Privacy Protectors Market
Consumer Electronics
Watch Market
Consumer Electronics
Adult Sex Dolls Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
Home Entertainment Devices Market
Consumer Electronics
Earbuds Market
Consumer Electronics
Gaming Mouse & Keyboards Market
Consumer Electronics
Armenia Consumer Goods Market
Consumer Electronics
Smartphone Screen Protector Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Nail Art Printer Market