
 North America Smartphone Accessories Market | 2026-2036
North America Smartphone Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smartphone Accessories Market Intelligence
Unbundling of charger and cable from smartphone retail packaging is hardening across North America, pressuring aftermarket suppliers to capture replacement cycles. Apple Inc. leverages its proprietary connector ecosystem to sustain captive demand for first-party adapters and cables. Belkin International competes through broad retail distribution, while Otter Products LLC anchors its position in protective cases through military-grade drop-test certification programs.
North America smartphone accessories encompass protective enclosures, power delivery devices, audio peripherals, and display films engineered to extend device functionality, durability, and user experience; wireless charging pads operate at 5W to 15W output under Qi protocol specifications, while screen protectors utilize chemically strengthened aluminosilicate glass rated to 9H hardness. Cases in silicone and hybrid plastic formulations lead volume shipments, though wireless earbuds command the fastest expansion trajectory as Bluetooth audio codecs improve latency performance. Distribution through online retail channels captures the dominant revenue share, yet specialty shops retain margin concentration in premium leather and metal-finish segments.
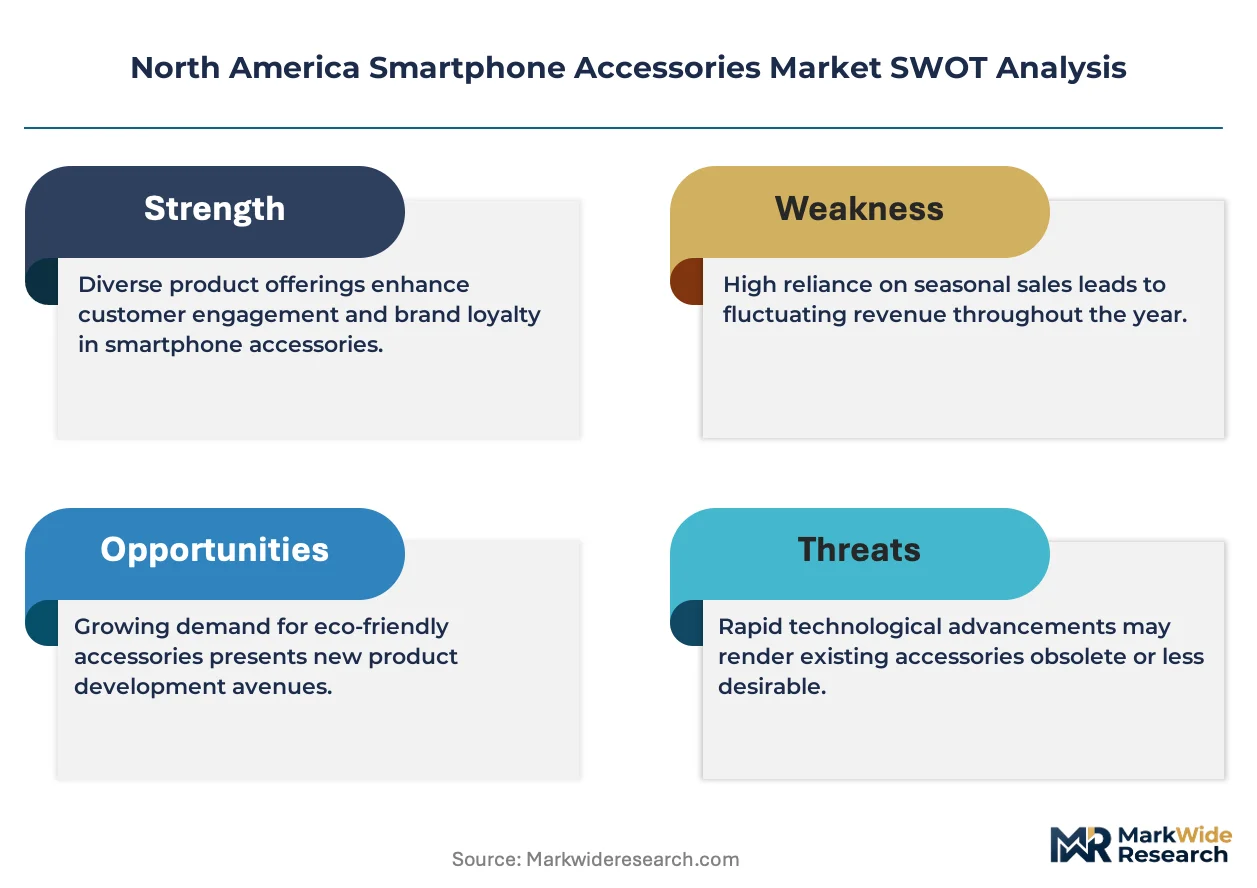
The FCC enforces Part 15 rules governing unintentional radiators and intentional emitters, compelling accessory manufacturers to secure equipment authorization before US market entry; California's SB 244 right-to-repair legislation further shapes design standards by mandating parts availability and diagnostic tool access. Health Canada and the PMRA coordinate with US agencies on cross-border electromagnetic compatibility standards, reducing testing duplication for vendors serving both markets. Stakeholders must monitor evolving state-level repair mandates and interoperability requirements that will determine which product architectures secure shelf space.
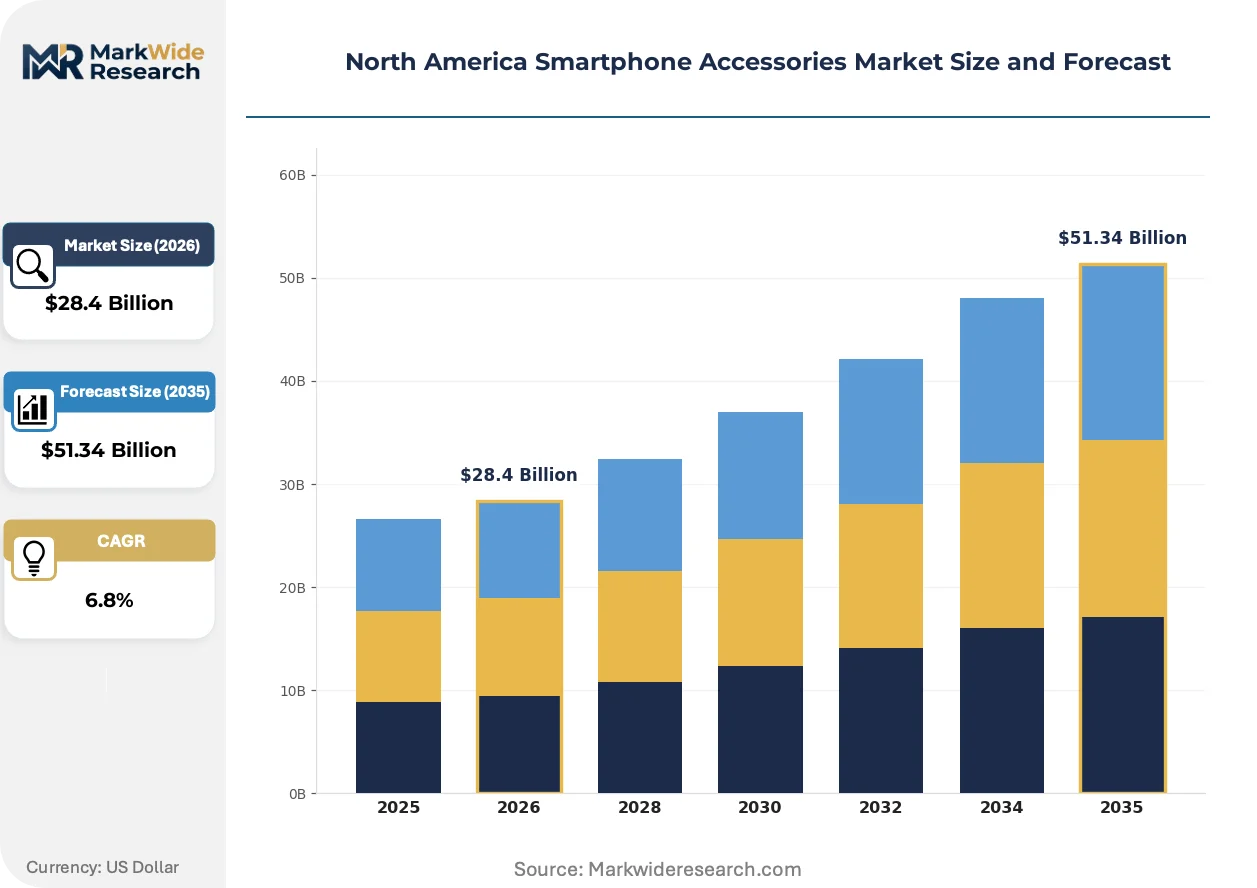
Market Dynamics
Unbundling of chargers from smartphone retail packaging across the United States and Canada is redirecting replacement demand toward aftermarket channels, forcing suppliers to rebuild go-to-market architectures around independent accessory purchases rather than bundled hardware sales.
Growth Catalysts
- FCC Part 15 Equipment Authorization:Tightened thresholds for RF-emitting accessories are accelerating design standardization among importers, reducing market fragmentation and concentrating shelf space with compliant vendors.
- California SB 244 Right-to-Repair Mandate:Parts availability requirements for diagnostic tools and replacement components are extending accessory lifecycles and expanding the addressable market for repair-compatible peripherals.
- Bluetooth Audio Codec Advancement:Latency improvements in wireless transmission protocols are displacing wired earphone inventory across enterprise procurement channels serving distributed workforces.
Market Restraints
- Proprietary Connector Lock-In:Apple's Lightning and USB-C ecosystem control captures first-party adapter demand, constraining aftermarket margin extraction for power delivery accessories.
- Aluminosilicate Glass Input Concentration:Chemically strengthened substrate supply concentrates among Asian specialty glass manufacturers, exposing screen protector vendors to freight cost volatility and tariff exposure.
- Qi Protocol Output Ceiling:Wireless charging pad performance caps at 15W under current specifications, limiting differentiation against wired fast-charging alternatives in power-user segments.
Strategic Opportunities
- Enterprise Charging Station Deployment:Distributed workforce normalization across Canadian and US metropolitan corridors is opening bulk procurement contracts for multi-device docking hardware.
- Leather and Metal-Finish Premiumization:Specialty retail channels in California's tech corridor retain margin concentration for artisanal case materials underserved by mass-market e-commerce.
- Health Canada-PMRA Cross-Border Harmonization:Coordinated electromagnetic compatibility standards with US agencies reduce testing duplication for vendors serving both markets, lowering regulatory entry costs.
Industry Challenges
- RF Engineering Talent Scarcity:FCC intentional emitter certification requires specialized electromagnetic compatibility expertise that concentrates among a narrow pool of US-based testing laboratories, extending product launch timelines.
- Drop-Test Certification Capex:Military-grade protective case validation demands capital-intensive impact simulation equipment that mid-tier manufacturers struggle to amortize across fragmented SKU portfolios.
- State-Level Repair Mandate Fragmentation:Divergent right-to-repair legislation across California, New York, and pending jurisdictions forces multi-standard inventory planning and compliance documentation redundancy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smartphone Accessories Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cases, Screen Protectors, Chargers, Wireless Earbuds Material: Plastic, Silicone, Leather, Metal Distribution Channel: Online Retail, Electronics Stores, Supermarkets, Specialty Shops Customer Type: Individual Consumers, Businesses, Educational Institutions, Professionals |
| Companies Covered | Apple Inc., Samsung Electronics Co. Ltd., Bose Corporation, Otter Products LLC, Belkin International, Sony Corporation, Plantronics Inc., JVC Kenwood Corporation, Sennheiser electronic GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smartphone Accessories Market Strategic Shifts & Innovations
Magnetic alignment systems and GaN semiconductor architectures are compressing form factors while elevating power density, reshaping competitive differentiation around thermal management and spatial efficiency rather than raw output metrics.
GaN-based power adapters are overtaking silicon-based charging bricks in premium tier positioning. Enterprise IT procurement teams across Toronto and Austin metropolitan zones are specifying gallium nitride architectures for workstation deployments. This semiconductor transition is enabling 65W+ output from palm-sized enclosures, collapsing the physical footprint advantage that previously separated wall-wart from desktop charging categories.
California's SB 244 right-to-repair framework is mandating parts availability timelines and diagnostic tool accessibility for smartphone peripherals. Accessory manufacturers must now engineer modular architectures compatible with third-party servicing infrastructure. Protective case vendors serving the California market are responding by standardizing adhesive formulations and clip mechanisms that independent repair technicians can replicate without factory tooling.
Direct-to-consumer subscription models for recurring accessory replacement are displacing transactional e-commerce patterns among urban millennial demographics. Specialty audio brands are bundling wireless earbuds with annual case and tip refresh programs through proprietary mobile applications. This behavioral shift concentrates most visibly in Seattle and Vancouver tech corridors where device turnover cycles compress below twenty-four months.
North America Smartphone Accessories Market Segmentation
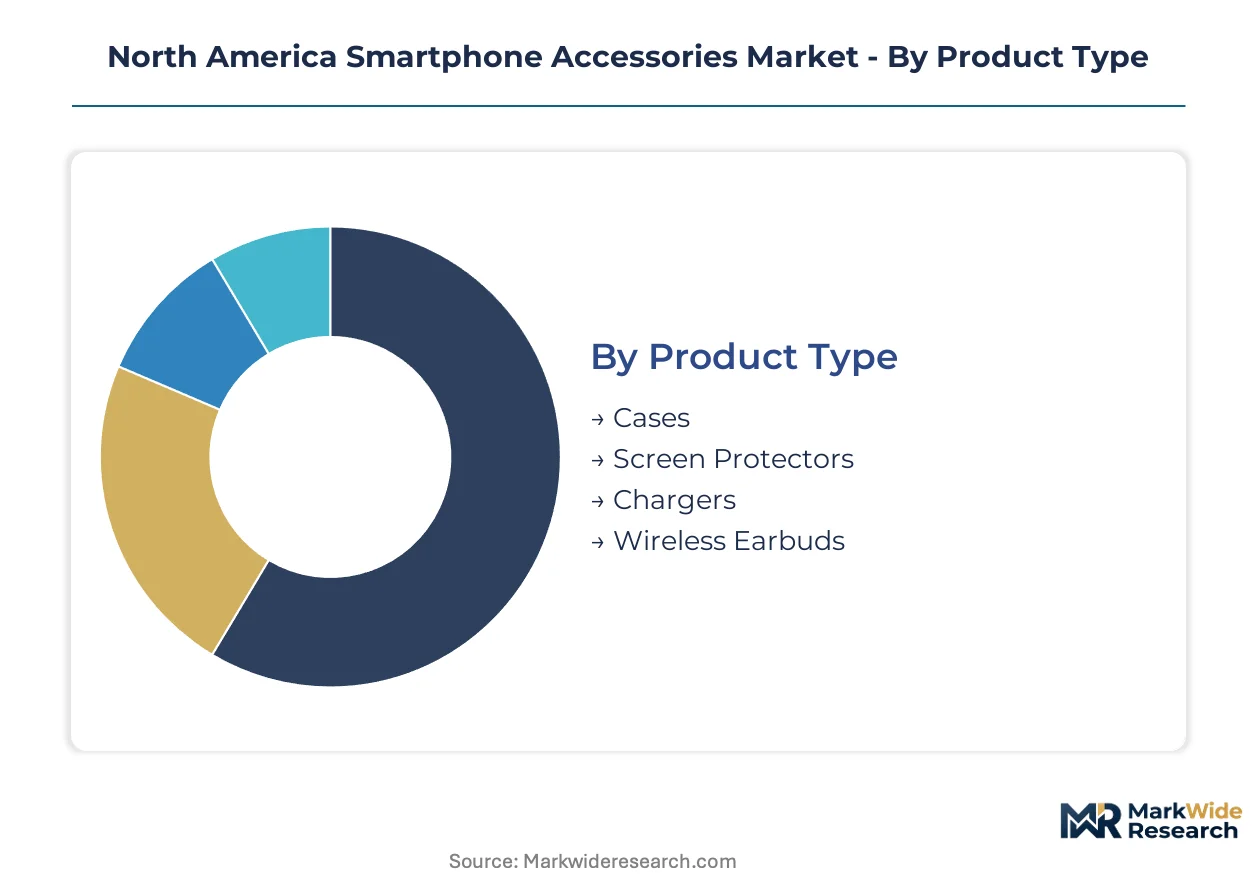
Accessory procurement patterns in North America diverge sharply across use cases, with enterprise buyers prioritizing interoperability and durability while individual consumers chase form-factor innovation. Material selection and channel strategy determine margin capture more than volume scale in this replacement-driven market.
Product Type:
Supply concentration in injection-molded enclosures and Qi-certified charging modules tilts manufacturing capacity toward protective and power-delivery categories.
- Cases:Silicone and hybrid plastic formulations dominate volume shipments, with military-grade drop-test certification programs anchoring Otter Products LLC's position. California's tech corridor absorbs disproportionate demand for premium protective enclosures as device turnover cycles compress below twenty-four months.
- Wireless Earbuds:Bluetooth audio codec improvements in latency performance are displacing wired inventory across enterprise procurement channels serving distributed workforces. Toronto and Austin metropolitan zones specify these for workstation deployments.
- Screen Protectors:Chemically strengthened aluminosilicate glass rated to 9H hardness concentrates supply among Asian specialty manufacturers.
- Chargers:GaN semiconductor architectures enable 65W+ output from palm-sized enclosures, collapsing wall-wart versus desktop charging distinctions.
Cases absorb the bulk of installed capacity; wireless earbuds are expanding most quickly.
Material:
Cost tier stratification separates mass-market synthetic volumes from artisanal premium positioning in specialty retail.
- Plastic:Polycarbonate and TPU blends anchor economy-tier case production with standardized tooling amortizable across fragmented SKU portfolios.
- Silicone:Liquid silicone rubber injection molding scales efficiently for mid-tier protective enclosures distributed through online retail channels.
- Leather:Vegetable-tanned and full-grain finishes command margin concentration in California specialty shops underserved by mass-market e-commerce.
- Metal:Aluminum unibody and stainless-steel accent architectures target professional demographics seeking thermal dissipation and electromagnetic shielding properties.
Plastic and silicone capture the volume base; leather climbs the fastest as premiumization accelerates.
Distribution Channel:
Volume gravity centers on digital fulfillment infrastructure, though margin extraction favors physical touchpoints for experiential categories.
- Online Retail:Direct-to-consumer subscription models for recurring accessory replacement concentrate in Seattle and Vancouver tech corridors.
- Electronics Stores:Big-box chains like Best Buy anchor charger and cable replacement cycles following unbundling from smartphone retail packaging.
- Supermarkets:Impulse-display economics capture economy-tier case and screen protector demand with minimal sales associate interaction.
- Specialty Shops:Artisanal leather and metal-finish segments retain margin concentration through tactile merchandising and repair service bundling.
Online retail handles the volume majority; specialty shops deliver the steepest margin expansion.
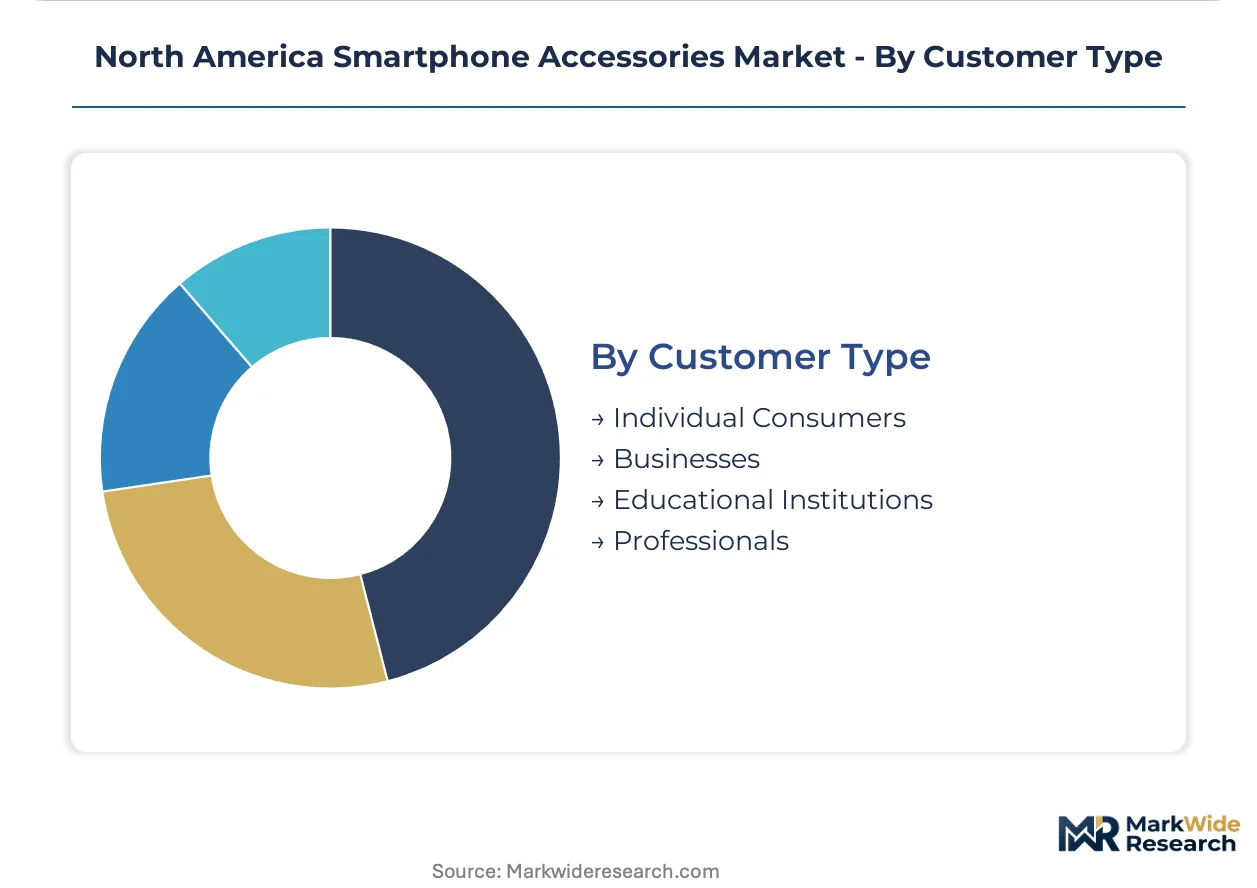
Customer Type:
Procurement authority fragmentation across IT departments, procurement offices, and individual buyers necessitates divergent go-to-market architectures.
- Individual Consumers:Replacement-cycle acceleration in urban millennial demographics drives direct-to-consumer subscription adoption for recurring tip and case refresh programs.
- Businesses:Enterprise charging station deployment for distributed workforces opens bulk procurement contracts across Canadian and US metropolitan corridors.
- Educational Institutions:K-12 and university IT departments specify ruggedized protective enclosures with standardized diagnostic tool compatibility under California SB 244 mandates.
- Professionals:Creative and technical workers prioritize GaN-based power adapters and low-latency wireless audio for mobile workstation configurations.
Individual consumers represent the installed base anchor; businesses are gaining share fastest through enterprise standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American consumption of smartphone accessories outpaces domestic manufacturing capacity, with assembly operations concentrated in Mexican border states while design and distribution headquarters cluster in US coastal technology corridors. Canada supplies specialized electromagnetic testing infrastructure that serves cross-border certification requirements.
United States
California's SB 244 right-to-repair legislation mandates parts availability timelines that reshape accessory design standards nationwide. The FCC enforces Part 15 equipment authorization rules that concentrate compliant vendor shelf space. Silicon Valley and Austin metropolitan zones anchor enterprise procurement of GaN-based charging hardware for distributed workforce deployments.
Canada
Health Canada and the PMRA coordinate electromagnetic compatibility standards with US agencies to reduce testing duplication for cross-border vendors. Toronto's financial district drives bulk procurement contracts for multi-device docking stations. Vancouver's tech corridor concentrates direct-to-consumer subscription adoption for recurring earbud replacement programs.
Mexico
Manufacturing assembly of protective cases and charging cables concentrates in Baja California and Chihuahua border states serving US retail replenishment. Mexican labor costs attract injection-molding operations for silicone and hybrid plastic enclosures. Monterrey's industrial parks host quality-control facilities for military-grade drop-test certification programs.
North America Smartphone Accessories Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the North American smartphone accessories market. Consumer electronics conglomerates leverage proprietary connector ecosystems and retail distribution scale to defend positions in power delivery and audio peripherals. Pure-play accessory specialists anchor market presence through military-grade certification programs and premium material differentiation. M&A activity concentrates on acquiring drop-test validation capabilities and GaN semiconductor engineering talent. Strategic partnerships between case manufacturers and independent repair networks expand under California's right-to-repair compliance requirements.
Among diversified technology conglomerates, Apple Inc. and Samsung Electronics Co. Ltd. exemplify ecosystem-lock strategies that capture first-party adapter demand through proprietary connector control. Otter Products LLC anchors the specialist tier through protective case positioning tied to military-grade certification programs. Belkin International occupies a position bridging mass-market retail distribution with enterprise procurement channels for power delivery accessories.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co. Ltd. |
| Bose Corporation |
| Otter Products LLC |
| Belkin International |
| Sony Corporation |
| Plantronics Inc. |
| JVC Kenwood Corporation |
| Sennheiser electronic GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Enterprise IT procurement teams across Toronto and Austin anchor contract-based long-term offtake for GaN-based charging hardware, compressing spot-market premiums and forcing aftermarket vendors toward subscription-tiered pricing models to retain margin capture.
Pricing Analysis
Margin tightening in mass-market power delivery accessories reflects unbundling of chargers from smartphone retail packaging across the United States and Canada. Three-tier pricing structure across premium, standard, and economy levels separates military-grade drop-test certified enclosures from injection-molded economy cases and artisanal leather finishes. Price differentiation traces to certification grade and after-sales service bundling rather than raw material cost. Individual consumers in Seattle and Vancouver exhibit highest price sensitivity through direct-to-consumer subscription adoption, while enterprise buyers in California's tech corridor prioritize interoperability over unit cost.
Supply Chain Analysis
Aluminosilicate glass substrate supply rests on Japanese and South Korean specialty manufacturers, exposing screen protector vendors to freight cost volatility. Chemically strengthened substrate, GaN semiconductor wafers, and liquid silicone rubber feed North American assembly operations concentrated in Mexican border states. Tariff exposure on Asian-sourced critical components constitutes the dominant structural risk. Distribution runs through online retail channels for volume majority, with specialty shops capturing premium margin concentration in California and Vancouver corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN semiconductor architectures are displacing silicon-based charging bricks across enterprise procurement channels, compressing legacy power adapter margins and opening white-space for thermal-management specialists.
For Market Incumbents: To counter proprietary connector lock-in by Apple Inc. and Samsung Electronics Co. Ltd., accessory specialists must deepen backward integration into GaN semiconductor sourcing and secure military-grade drop-test certification programs that big-box retailers mandate for shelf placement. Channel control through direct-to-consumer subscription platforms offers defensive moat against e-commerce price erosion. For New Entrants and Emerging Players: The gap between premium artisanal leather cases and economy-tier plastic enclosures offers entry path for mid-tier hybrid material specialists targeting California's SB 244 repair-compatible design mandates. Enterprise charging station deployment for distributed workforces represents most penetrable segment, with bulk procurement contracts in Toronto and Austin accessible through interoperability certification rather than brand equity. Go-to-market angle should emphasize Health Canada-PMRA cross-border electromagnetic compatibility pre-certification to reduce US market entry friction. For Investors and Strategic Acquirers: The window for entry favors GaN semiconductor engineering talent pools and drop-test validation capabilities concentrated among narrow US-based testing laboratories. Long-term viability hinges on modular architectures compatible with evolving state-level right-to-repair mandates across California, New York, and pending jurisdictions. Signal to watch is FCC Part 15 equipment authorization threshold tightening that will consolidate compliant vendor shelf space.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Talent Acquisition | Captures 65W+ power density engineering capability ahead of silicon displacement. |
| Military-Grade Drop-Test Certification | Secures big-box retail shelf placement against uncertified economy-tier competitors. |
| Direct-to-Consumer Subscription Launch | Locks recurring revenue from Seattle and Vancouver millennial demographics. |
| Cross-Border EMC Pre-Certification | Reduces Health Canada-PMRA and FCC testing duplication for dual-market vendors. |
| Modular Repair-Compatible Design | Ensures California SB 244 compliance and extends accessory lifecycle addressability. |
Research Approach
Independent corroboration across accessory manufacturing executives, FCC compliance consultants, and enterprise IT procurement officers underwrites the qualitative findings. Primary fieldwork with silicone injection-molding plant managers, big-box category buyers, and independent repair network operators combined with secondary validation from FCC equipment authorization databases, SEC 10-K filings of listed consumer electronics conglomerates, and customs/trade data on aluminosilicate glass imports. Bottom-up SKU-level volume builds and top-down category spend estimates triangulate to segment-level outputs.
Rate-of-change decomposition across the projection horizon isolates volume drivers by product type, material tier, distribution channel, and customer archetype. Analytical framework models protective enclosure, power delivery, audio peripheral, and display film segments with granularity on Qi protocol certification status and GaN versus silicon semiconductor architecture. CAGRs derive from replacement cycle compression trends, enterprise procurement standardization patterns, and regulatory compliance threshold evolution. Forecast inputs include Bluetooth audio codec latency improvement trajectories and state-level right-to-repair mandate propagation timelines.
Underlying measurement precision varies by segment; wireless earbuds and GaN-based chargers carry tighter precision than artisanal leather cases where artisan production obscures volume tracking. Forecasts reflect documented assumptions on enterprise distributed workforce normalization and FCC Part 15 enforcement intensity. Supply chain disruption from Asian specialty glass manufacturer concentration and tariff regime volatility warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
China Massage Equipment Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Camera Case Market
Consumer Electronics
Global Speaker Market
Consumer Electronics
United States Soundbar Market
Consumer Electronics
Air Tube Headset Market
Consumer Electronics
Gaming Phone Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
North America Gaming Accessories Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Mechanical Keyboard Market
Consumer Electronics
Refurbished Computer and Laptop Market
Consumer Electronics
Smart Connected Speaker Market
Consumer Electronics
Advanced Baby Monitors Market