
 Popover Pan Market | 2026-2036
Popover Pan Market Size, Share, and Industry Trends Forecast 2026-2036
Popover Pan Market Analytics
The split between premium and commodity tiers in bakeware is shifting toward material certification and heat-conductivity performance rather than brand heritage alone. Chicago Metallic leverages its commercial-grade aluminum construction to sustain institutional buyer loyalty. Nordic Ware differentiates through proprietary non-stick coatings and domestic manufacturing scale. USA Pans anchors its position with aluminized steel formulations and channel control through specialty kitchenware retailers.
A popover pan is a deep, narrow-cup baking vessel engineered with steep walls and minimal taper to maximize steam-driven lift of egg-rich batter, typically constructed from aluminized steel, heavy-gauge aluminum, or cast iron with temperature thresholds exceeding 450°F for optimal crown formation. The product type segment shows non-stick and cast iron variants capturing margin pools from home chefs seeking reduced-fat recipes and thermal retention, while aluminum dominates volume through restaurant procurement. Distribution through online retail and specialty stores is outpacing supermarket channels as enthusiast bakers prioritize detailed specifications and verified reviews over impulse purchases.
The FDA regulates food-contact surfaces under 21 CFR 175.300 for resinous and polymeric coatings, while California's Proposition 65 mandates disclosure of trace heavy metals in ceramic and enameled finishes, pressuring manufacturers toward third-party testing. The EU's REACH restrictions on perfluorinated compounds in non-stick formulations are reshaping export-compliant product lines for cross-border sellers. Stakeholders must monitor evolving state-level chemical disclosure laws and oven-safe certification standards to align R&D investment with compliance-bound demand.
Market Dynamics
California's Proposition 65 disclosure mandates and FDA food-contact regulations are compressing product development timelines while forcing material substitutions across the popover pan supply base. Manufacturers now face certification bottlenecks that reshape competitive positioning before products reach retail shelves.
Growth Catalysts
- Specialty retail channel expansion:Enthusiast bakers are migrating toward direct-to-consumer platforms that provide detailed specifications and verified performance data, bypassing traditional supermarket distribution.
- REACH-compliant coating innovation:EU restrictions on perfluorinated compounds are accelerating adoption of ceramic and silicone-based non-stick alternatives that meet cross-border export standards.
- Home baking participation surge:Post-pandemic retention of bread-making and pastry hobbies sustains demand for purpose-built vessels with thermal precision.
Market Restraints
- Aluminum price volatility:Primary metal input costs fluctuate with energy-intensive smelting economics, compressing margin stability for mid-tier producers.
- Cast iron supply concentration:Foundry capacity clusters in specific industrial regions, creating geographic vulnerability for brands dependent on domestic heavy-gauge production.
- Substitution by multi-function bakeware:Muffin tins and standard cake pans with adapter inserts capture price-sensitive buyers seeking versatility over specialization.
Strategic Opportunities
- Underpenetrated European enthusiast segment:Germany and France show latent demand for premium aluminized steel constructions with metric calibration markings.
- Smart kitchen integration potential:Temperature-responsive coatings that signal optimal doneness through color change align with connected appliance ecosystems.
- Subscription-based replenishment models:Direct-to-consumer brands can capture recurring revenue through consumable accessory pairings and seasonal limited editions.
Industry Challenges
- Third-party testing backlog:FDA-compliant food-contact certification timelines extend six to nine months, delaying product launches past peak baking seasons.
- Skilled tool-and-die scarcity:Precision stamping expertise for steep-wall cup geometries concentrates among aging workforce cohorts in Midwest manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Popover Pan Market |
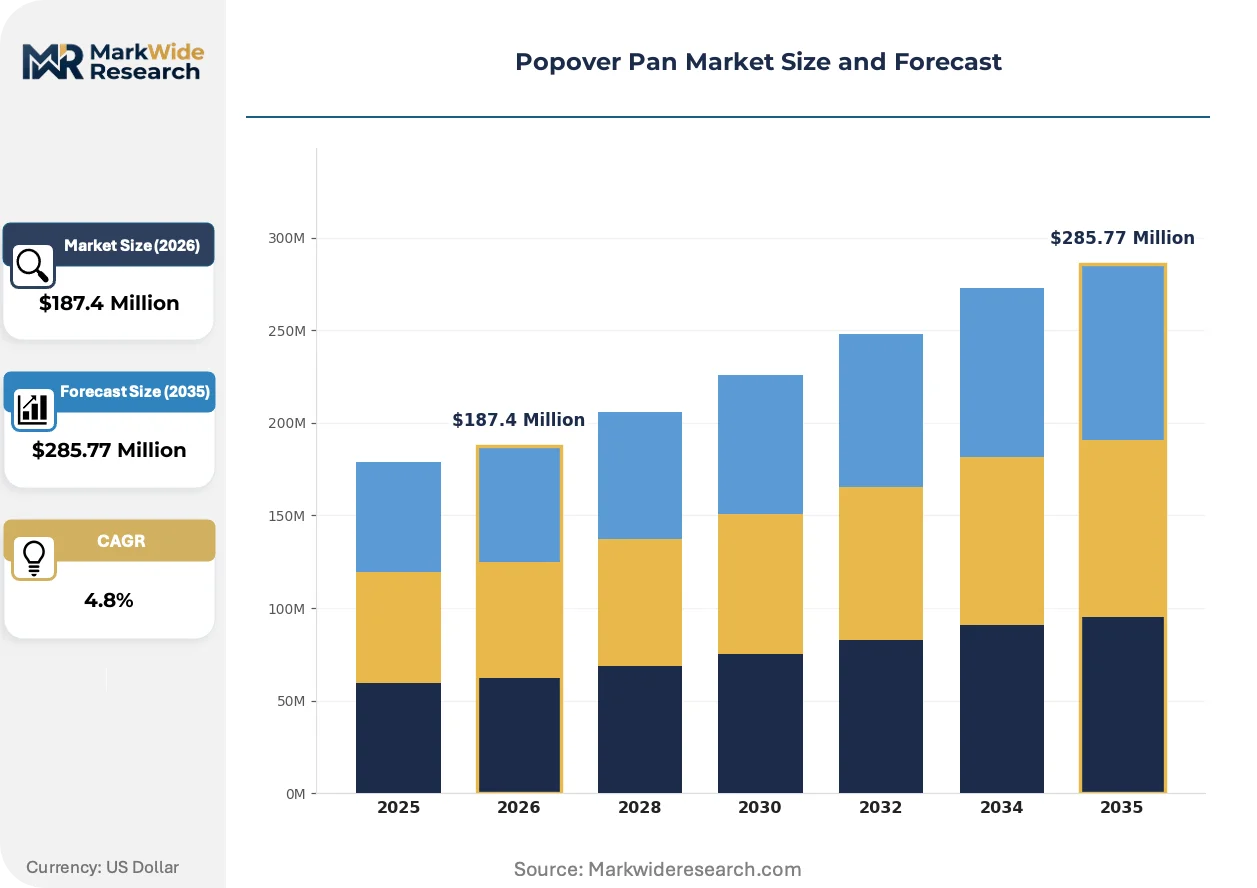
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Non-Stick, Cast Iron, Silicone End User: Home Chefs, Professional Bakers, Restaurants, Culinary Schools Size: Mini, Standard, Jumbo, Extra Large Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Kitchenware Outlets |
| Companies Covered | Chicago Metallic, Nordic Ware, Norpro, Shellwei, USA Pans, Fox Run, CHEFMADE, Bellemain, Norpro Nonstick Mini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Popover Pan Market Evolving Landscape
Material science advances and regulatory pressure are converging to transform how popover pans are engineered, certified, and sold. The competitive frontier now sits at the intersection of thermal performance verification and chemical transparency.
Aluminized steel construction with proprietary silicone-based ceramic coatings is modularizing product architectures across premium tiers. Home bakers seeking reduced-fat recipes adopt these variants for release properties without perfluorinated compounds. The technology is modularizing how manufacturers segment their lines, enabling rapid SKU expansion through interchangeable cup configurations and handle attachments.
REACH restrictions on perfluorinated substances are forcing reformulation of legacy non-stick portfolios for EU export compliance. Manufacturers must maintain parallel inventory streams or absorb R&D costs for universal coating platforms. Specialty retailers in Germany and the Netherlands now demand batch-level testing documentation before stocking imported bakeware.
Enthusiast buyers are prioritizing verified thermal performance data over brand heritage in purchase decisions. Online specialty channels displace supermarket impulse buys with specification-rich product pages and video demonstration content. This behavior concentrates most visibly in United States direct-to-consumer platforms serving dedicated home bakers.
Popover Pan Market Segmentation
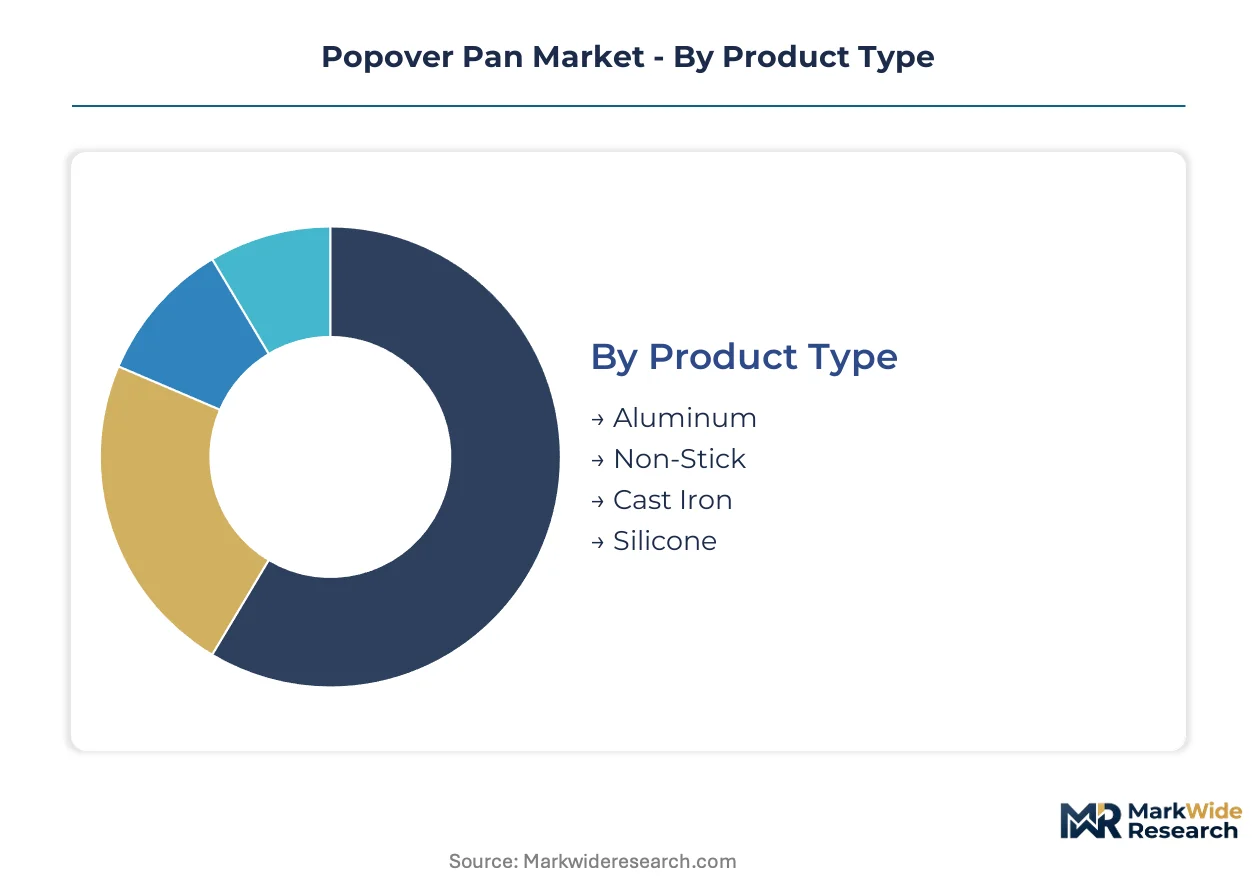
Popover pan segmentation reflects divergent thermal performance requirements across user sophistication levels and distribution channel transparency. Material composition and cup geometry determine heat transfer efficiency, crown formation reliability, and regulatory compliance pathways for manufacturers.
Product Type:
Aluminum construction dominates commercial procurement through superior thermal conductivity and rapid heat response in professional ovens.
- Aluminum:Heavy-gauge stamped aluminum with temperature thresholds exceeding 450°F delivers rapid, even heat distribution for consistent crown formation. Restaurant procurement in the United States concentrates here due to durability requirements and NSF certification alignment, though primary metal price volatility compresses margin stability for mid-tier producers.
- Non-Stick:Ceramic and silicone-based coatings replace perfluorinated formulations under REACH restrictions, enabling reduced-fat recipe execution. Home chefs in direct-to-consumer online channels drive specification-rich purchasing decisions here, prioritizing verified batch-level testing documentation over brand heritage.
- Cast Iron:Pre-seasoned heavy-gauge iron provides exceptional thermal retention for slow, even baking in residential ovens.
- Silicone:Flexible, collapsible molds target space-constrained kitchens and travel baking applications with lower temperature ceilings.
Mature deployment sits with aluminum. Newer deployment is concentrated in non-stick ceramic formulations.
End User:
User sophistication tiers separate specification-driven enthusiasts from price-sensitive generalists across channel and material preferences.
- Home Chefs:Enthusiast bakers with retained post-pandemic bread-making habits seek purpose-built vessels with thermal precision and detailed performance data. Specialty cookware retailers in the United States capture this segment through specification-rich product pages and video demonstration content.
- Professional Bakers:Commercial operations demand NSF-certified aluminum constructions with rapid batch turnover capability and institutional durability standards. Volume procurement runs through restaurant supply distributors with stringent food-contact documentation requirements under FDA 21 CFR 175.300.
- Restaurants:Front-of-house service programs leverage popover presentations for menu differentiation in casual and fine-dining segments.
- Culinary Schools:Training programs standardize on specific cup geometries for curriculum consistency and student technique development.
Volume concentrates with professional bakers. Margin expansion is climbing the fastest among home chef enthusiasts.
Size:
Cup dimensions directly govern batter-to-surface ratios and final crown geometry for specific presentation contexts.
- Standard:Six-cup configurations with 2.5-inch diameter cups accommodate traditional Yorkshire pudding and American popover recipes. Home kitchen ovens in the United States standardize around this footprint for residential baking sheet compatibility.
- Mini:Twelve-cup formats enable appetizer and tasting-menu applications with reduced baking time requirements.
- Jumbo:Oversized cups target dramatic tableside presentations in steakhouse and hospitality settings.
- Extra Large:Single-cup or limited-cup pans accommodate specialty batters and extended rise profiles.
Standard sizing anchors replacement demand. Jumbo formats are gaining share fastest in hospitality procurement.
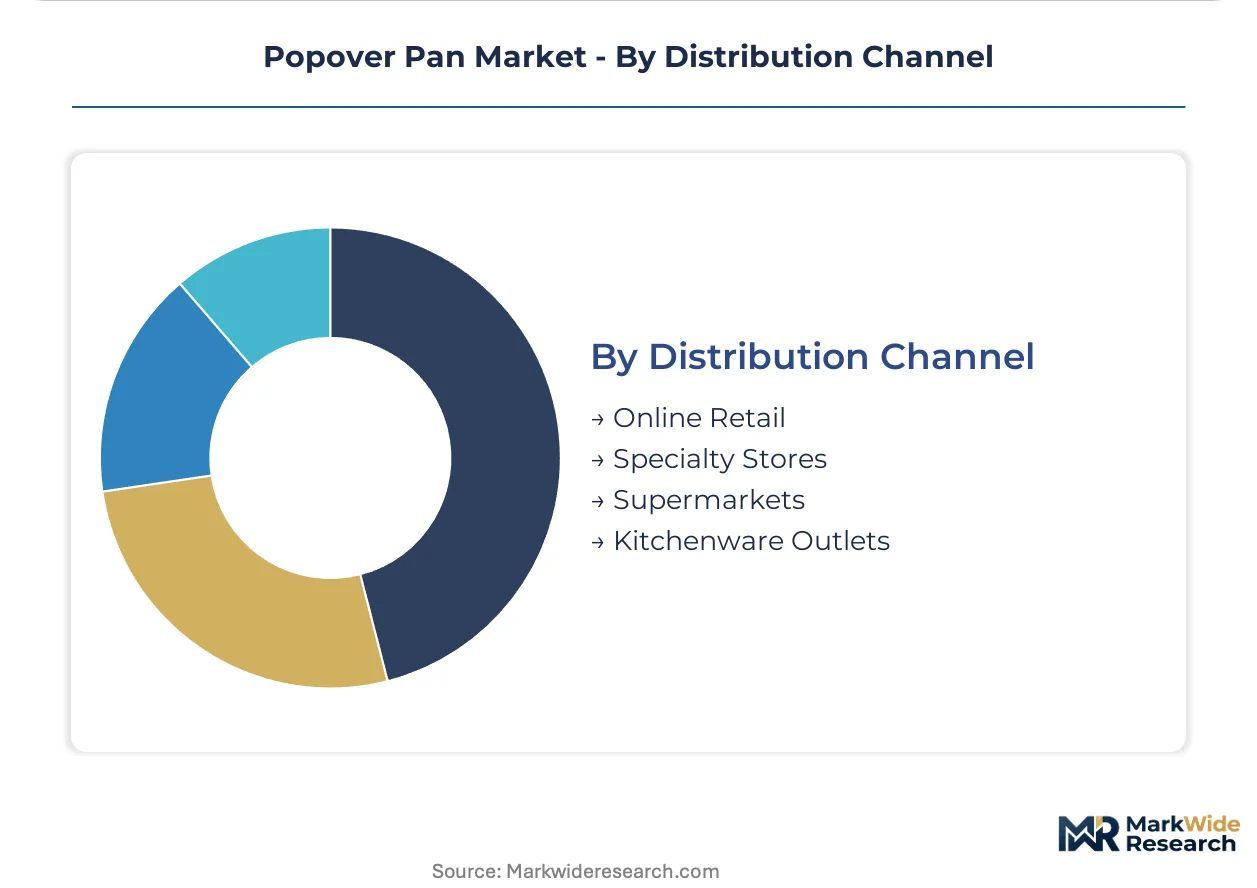
Distribution Channel:
Channel selection determines specification transparency, impulse versus planned purchasing, and regulatory documentation access.
- Online Retail:Direct-to-consumer platforms provide verified performance data, batch-level testing documentation, and enthusiast community reviews. United States specialty kitchenware e-commerce displaces supermarket impulse purchases for dedicated home bakers prioritizing chemical transparency.
- Specialty Stores:Sur La Table and Williams Sonoma locations enable tactile evaluation of weight, gauge, and coating quality with trained staff consultation.
- Supermarkets:Mass-market retail captures price-sensitive buyers seeking basic aluminum constructions without specialized coating requirements.
- Kitchenware Outlets:Discount channels move excess inventory and prior-season designs to value-oriented generalist cooks.
Supermarket distribution retains the largest volume base. Online retail represents the steepest expansion trajectory for premium tier penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sheboygan, Wisconsin anchors North American popover pan manufacturing through Nordic Ware's domestic stamping operations and aluminized steel sourcing corridors serving specialty kitchenware distributors.
United States
Direct-to-consumer platforms capture enthusiast home chefs seeking batch-level testing documentation under FDA 21 CFR 175.300 food-contact regulations. California's Proposition 65 disclosure mandates for trace heavy metals reshape coating specifications across domestic supply chains. Chicago Metallic leverages commercial-grade aluminum construction from its Illinois manufacturing base to sustain institutional buyer loyalty in restaurant procurement channels.
Germany
REACH restrictions on perfluorinated compounds accelerate ceramic and silicone-based non-stick adoption among metric-calibrated bakeware enthusiasts. ECHA chemical safety protocols demand reformulation of legacy coating portfolios for cross-border compliance. Specialty retailers in Stuttgart and Munich now require third-party batch documentation before stocking imported aluminized steel constructions.
France
Latent demand for premium Yorkshire pudding vessels concentrates in Paris and Lyon culinary supply corridors serving trained pastry professionals. ANSM food-contact material oversight aligns with EU-wide polymer coating standards under MDR-adjacent safety frameworks. Auvergne-Rhône-Alpes industrial clusters host precision stamping subcontractors supplying steep-wall cup geometries to pan assemblers.
United Kingdom
Post-Brexit divergence from EU chemical regulations creates parallel certification requirements for non-stick coating imports through Port of Felixstowe logistics hubs. London specialty kitchenware boutiques drive specification-rich purchasing among retained home baking hobbyists. Midlands manufacturing zones maintain legacy tool-and-die capacity for heavy-gauge aluminum stamping operations.
Japan
METI consumer product safety standards govern thermal threshold labeling for cast iron and aluminum bakeware entering Tokyo and Osaka retail channels. Compact residential oven footprints favor six-cup standard configurations with metric calibration markings. Nagoya industrial corridors supply precision metal forming equipment to domestic pan fabricators serving department store kitchenware floors.
Popover Pan Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and thermal performance verification dimensions rather than brand heritage alone. The vendor base separates into three strategic tiers: commercial-grade aluminum specialists serving institutional procurement, proprietary coating innovators capturing enthusiast direct-to-consumer demand, and value-positioned generalists competing through supermarket distribution. Dominant competitive moves include REACH-compliant coating reformulation for EU market access and vertical integration into aluminized steel sourcing to buffer primary metal price volatility.
Within the domestic manufacturing tier, Nordic Ware and Chicago Metallic exemplify divergent archetypes—Nordic Ware through proprietary coating scale and Chicago Metallic through commercial-grade construction standards. USA Pans occupies a position bridging specialty retail channel control with aluminized steel formulation expertise. Fox Run and Bellemain sit within value-oriented distribution through mass-market retail penetration. CHEFMADE represents Asian manufacturing scale serving export-compliant product lines.
| Leading Market Players |
|---|
| Chicago Metallic |
| Nordic Ware |
| Norpro |
| Shellwei |
| USA Pans |
| Fox Run |
| CHEFMADE |
| Bellemain |
| Norpro Nonstick Mini |
| Others |
Value Network & Pricing Analysis
Captive aluminized steel sourcing from Sheboygan-area stamping clusters anchors both supply security and pricing power for domestic manufacturers serving FDA-regulated food-contact markets. This upstream control buffers primary aluminum volatility while enabling premium tier positioning through verified batch documentation.
Pricing Analysis
Throughput-based pricing anchors commercial procurement contracts, with restaurant supply distributors paying per-batch premiums for NSF-certified aluminum constructions with rapid crown formation reliability. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant ceramic-coated SKUs from commodity aluminum and value-positioned stamped variants. Pricing pressure stems from energy-intensive smelting economics compressing mid-tier producer margins. Home chef enthusiasts in direct-to-consumer channels show lowest price sensitivity, prioritizing verified thermal performance data over cost.
Supply Chain Analysis
Direct-to-specialty-retail channels handle enthusiast buyer demand with specification-rich documentation requirements, while mass-market distribution runs through supermarket and kitchenware outlet networks serving price-sensitive generalists. Manufacturing concentrates in the United States, Germany, and China, with heavy-gauge aluminum drawing from Midwest stamping corridors and ceramic-coated variants sourcing from REACH-compliant EU coating facilities. Raw material dependencies span primary aluminum ingot, aluminized steel substrate, and silicone-based ceramic formulations. Single-source vulnerability sits with aging tool-and-die expertise concentrated in Midwest manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as FDA certification timelines and REACH-compliant coating R&D costs force sub-scale competitors toward exit or acquisition.
For Market Incumbents: Deploy proprietary coating scale as the defensive lever. Nordic Ware's domestic manufacturing footprint and Chicago Metallic's institutional buyer relationships create moats against emerging Asian exporters. Incumbents should deepen backward integration into aluminized steel sourcing to buffer primary metal volatility, while accelerating REACH-compliant reformulation to maintain EU market access against substitution by multi-function bakeware. For New Entrants and Emerging Players: Capture the underpenetrated German and French enthusiast segments through metric-calibrated premium constructions with batch-level testing documentation. White-space opportunity concentrates in temperature-responsive coating innovation and subscription-based accessory replenishment models serving retained post-pandemic home baking habits. Go-to-market positioning should leverage direct-to-consumer video demonstration content over traditional retail shelf placement. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified kitchenware portfolios seeking REACH-compliant coating capabilities and domestic stamping assets. Long-term viability favors targets with captive aluminized steel supply and established specialty retail channel control. The signal to watch is ECHA regulatory expansion beyond perfluorinated compounds into broader polymer coating restrictions, which would accelerate consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | ECHA restrictions on perfluorinated compounds force R&D investment for EU market retention. |
| Backward Integration into Aluminized Steel | Captive substrate sourcing buffers primary aluminum price volatility from energy-intensive smelting. |
| Direct-to-Consumer Platform Launch | Specialty kitchenware e-commerce displaces supermarket impulse purchases among enthusiast bakers. |
| Metric Calibration Marking Introduction | German and French culinary supply corridors demand precision measurement standards for trained professionals. |
| Temperature-Responsive Coating Development | Color-change doneness indicators align with connected appliance ecosystem integration potential. |
Research Methodology
Trade association publications, customs import records, and FDA food-contact substance filings formed the secondary backbone, cross-referenced with primary interviews across cookware brand managers, specialty retail category buyers, restaurant supply procurement leads, and coating formulation chemists. Bottom-up SKU-level data triangulated against top-down aluminum and steel consumption trends to establish market sizing boundaries.
Historical trendline analysis of specialty bakeware shipment volumes informed projection modeling across material type, end-user sophistication tier, cup geometry configuration, and distribution channel transparency. CAGRs were derived from segmented growth rate reconciliation with macroeconomic baking participation indicators and regulatory compliance cost trajectories. Forecast inputs incorporated REACH regulatory expansion timelines and primary metal price elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA chemical restriction scope expansion and skilled tool-and-die workforce attrition. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
United Arab Emirates Kitchen Furniture Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Kuwait Kitchen Hoods Market
Kitchen and Dining
UK Ceramic Tableware Market
Kitchen and Dining
Kitchen Countertop Market
Kitchen and Dining
Quartz Sink Market
Kitchen and Dining
Brightwood Tray Market
Kitchen and Dining
US Tableware Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
Outdoor Kitchen Market
Kitchen and Dining
Global Kitchenware Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Housewares (Tabletopware) Market