
 POP Display Market | 2026-2036
POP Display Market Size, Share, and Industry Trends Forecast 2026-2036
POP Display Market Outlook
Structural packaging engineering talent is reorganizing how POP display programs scale across retail chains. DS Smith PLC leverages its corrugated design studios across Europe to sustain complex retail-ready formats. WestRock Company anchors North American grocery and club channel programs through integrated paperboard supply. Smurfit Kappa Group PLC dominates Latin American retail expansion with localized converting operations.
A point-of-purchase display constitutes a temporary or semi-permanent retail fixture engineered from corrugated fiberboard, rigid plastics, or composite substrates to merchandise consumer products at the decision-making zone near checkout or aisle endcaps. These structures typically specify load-bearing thresholds, print resolution for brand graphics, and modularity for seasonal turnover. Cardboard displays lead volume due to cost efficiency and printability, while digital display segments capture margin pools through embedded LCD screens and sensor-triggered content. Interactive display adoption accelerates fastest as retailers deploy QR-enabled and NFC-integrated units to bridge physical and mobile commerce.
The EPA regulates volatile organic compound emissions from display coatings and adhesives under Clean Air Act provisions, while FDA guidelines govern food-contact-safe materials for grocery and convenience store deployments. REACH compliance across the European Union restricts certain plasticizers and flame retardants in permanent fixture substrates. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate traceability requirements that will determine supplier qualification and program economics.
Market Dynamics
Retail fixture specifications are tightening under the EU F-Gas Regulation and parallel state-level refrigerant restrictions, forcing substrate transitions toward recyclable corrugated fiberboard and bio-based rigid plastics that meet extended producer responsibility frameworks.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal and F-Gas Regulation compel retailers to replace permanent plastic fixtures with recyclable corrugated alternatives, accelerating material substitution programs across German and French supermarket chains.
- Interactive sensor integration:NFC-enabled and QR-code displays bridge physical retail with mobile commerce, driving adoption in United States grocery and convenience channels seeking measurable engagement metrics.
- Supermarket digital transformation:Major retailers in China deploy LCD-embedded endcap units to capture decision-zone attention, creating pull-through demand for semi-permanent digital display formats.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs fluctuate with Chinese import quotas and domestic mill capacity, compressing margins for display converters dependent on recycled fiber supply.
- Permanent fixture substitution:Metal and acrylic permanent displays in club retail resist seasonal replacement cycles, limiting addressable market for temporary cardboard programs in warehouse formats.
- REACH compliance burden:ECHA restrictions on plasticizers and flame retardants in permanent substrates force reformulation of composite materials, extending qualification timelines for European deployments.
Strategic Opportunities
- India retail modernization:Organized retail penetration in Indian metropolitan corridors creates first-mover advantage for corrugated retail-ready packaging formats adapted to ambient supply chain conditions.
- Food-contact certification expansion:FDA guidelines for food-safe display materials open grocery perimeter deployments previously restricted to non-food categories, expanding addressable shelf space.
- Sensor-analytics convergence:Integration of footfall sensors with inventory management systems enables outcome-based display performance models, shifting procurement from unit-cost to engagement-value metrics.
Industry Challenges
- Structural packaging engineering scarcity:Specialized talent capable of optimizing load-bearing thresholds and print resolution for retail-ready formats concentrates in European design studios, constraining program scaling.
- Multi-jurisdiction certification complexity:Simultaneous EPA VOC, FDA food-contact, and REACH compliance requirements create timeline friction for multinational retail rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | POP Display Market |
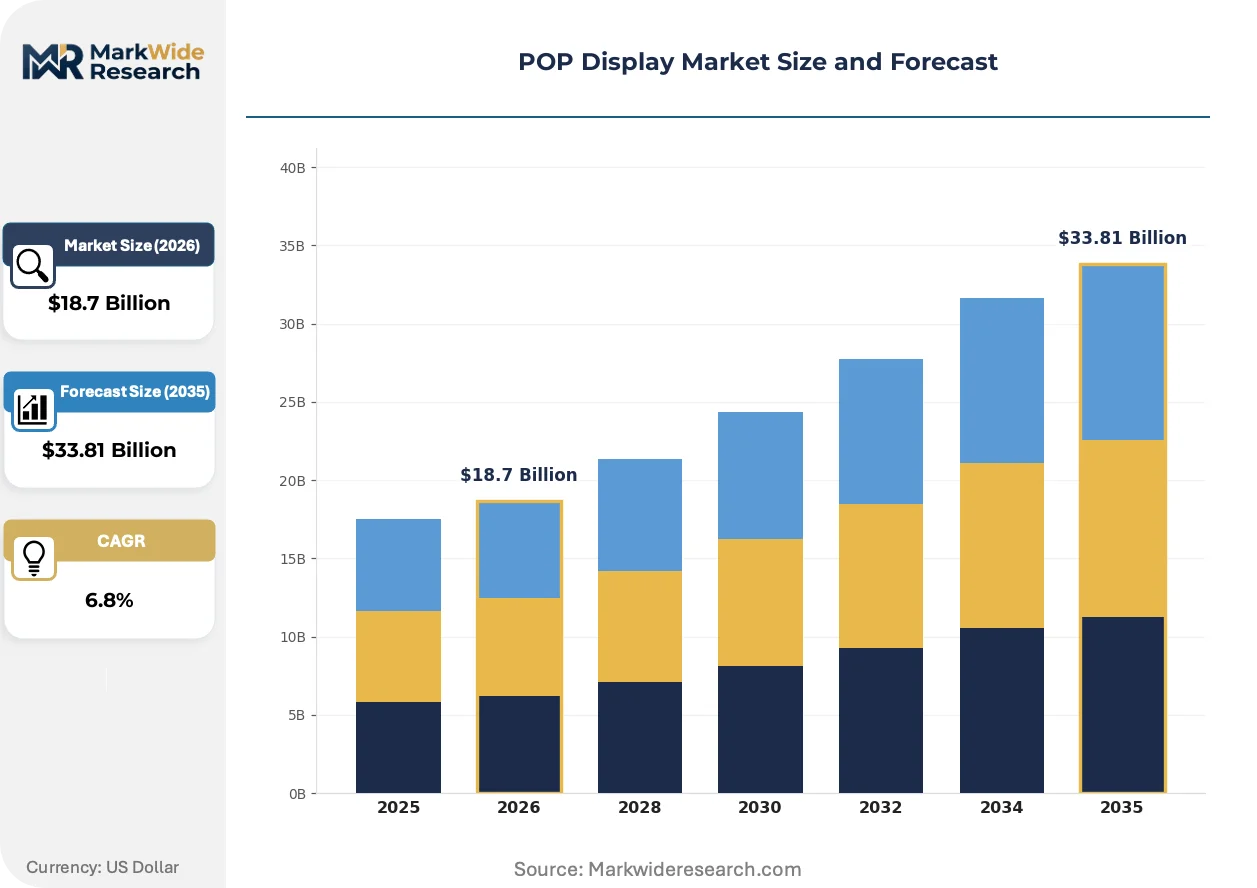
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Standard Display, Digital Display, Interactive Display, Temporary Display Material: Cardboard, Plastic, Metal, Wood End User: Retail Stores, Supermarkets, Trade Shows, Exhibitions Design Style: Minimalistic, Bold, Thematic, Eco-friendly |
| Companies Covered | DS Smith PLC, WestRock Company, Smurfit Kappa Group PLC, International Paper Company, Stora Enso Oyj, Sonoco Products Company, Georgia-Pacific LLC, Menasha Packaging, Pratt Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
POP Display Market Strategic Shifts
Display technology is fragmenting along a digital-physical fault line as retailers test sensor-enabled engagement against cost-engineered cardboard efficiency, with regulatory pressure on material provenance accelerating both tracks simultaneously.
Corrugated fiberboard engineering is bifurcating between high-volume commodity displays and precision-engineered retail-ready formats with integrated handles, tear-open features, and shelf-ready stacking geometries. German supermarket chains demand the latter for automated replenishment systems. The structural consequence is compressing mid-tier converter margins while rewarding studios with dedicated structural design capabilities.
REACH restrictions on halogenated flame retardants and phthalate plasticizers are forcing permanent fixture manufacturers toward bio-based polyesters and mineral-filled polypropylene. Industrial consequence includes reformulation costs passed through supply chains. Permanent display segments in France and Benelux respond fastest due to national extended producer responsibility implementation ahead of EU-wide harmonization.
Retail procurement patterns are compressing display program development cycles from seasonal to campaign-based turnover. Quick-service restaurant and convenience store channels in the United States lead this shift, replacing six-month fixtures with four-week promotional units. The geographic concentration of demand rotation centers on Texas and Florida metropolitan corridors with high promotional intensity.
POP Display Market Segmentation
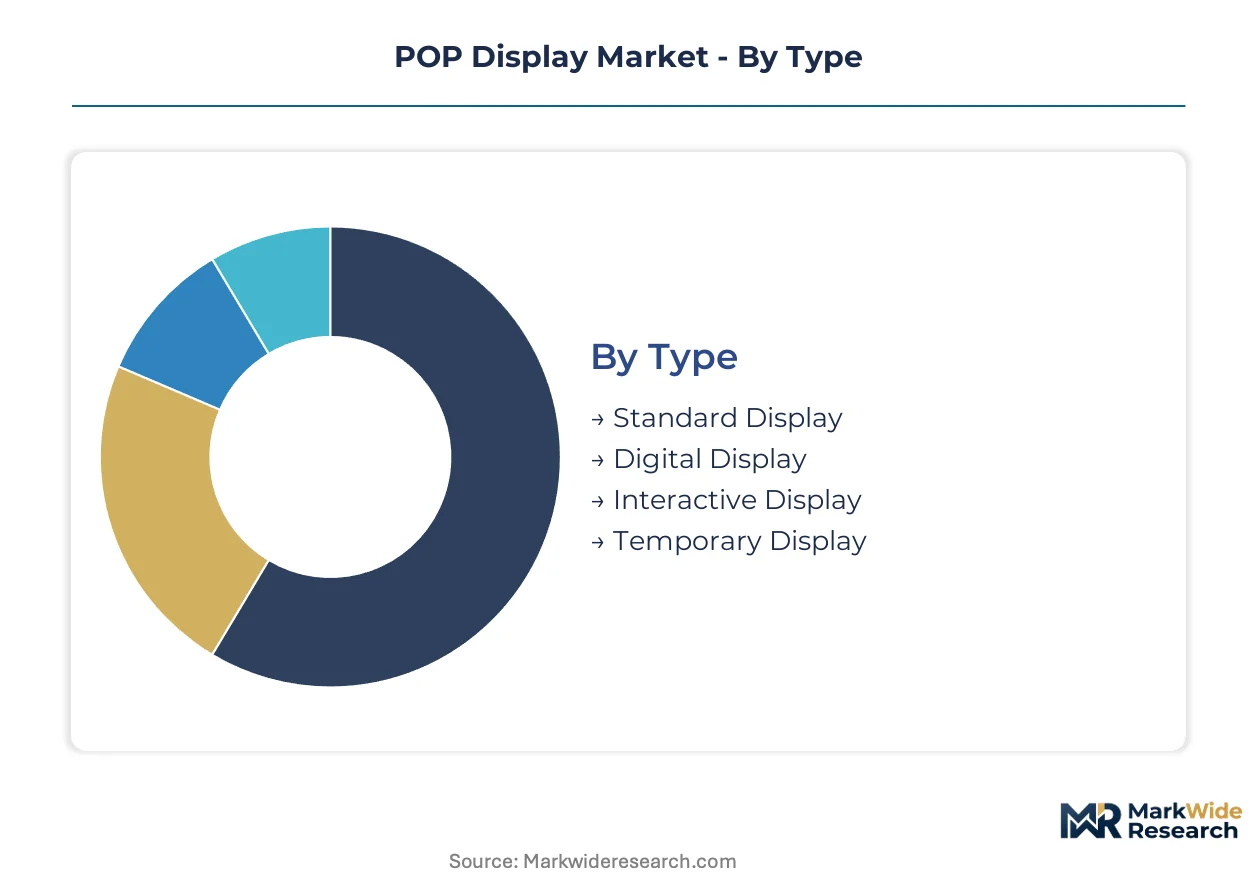
POP display procurement splits sharply between cost-engineered temporary units and sensor-enabled interactive formats, with material choices increasingly governed by extended producer responsibility frameworks rather than pure unit economics.
Type:
Interactive and digital formats face the most acute substitution pressure from permanent fixture programs in club retail, while standard cardboard displays confront margin compression from OCC feedstock volatility.
- Standard Display:Corrugated fiberboard structures engineered for seasonal promotional cycles specify load-bearing thresholds and print resolution for brand graphics. German supermarket chains deploy these for automated replenishment systems, though OCC price swings compress converter margins.
- Interactive Display:NFC-enabled and QR-code integrated units bridge physical retail with mobile commerce, capturing engagement metrics for outcome-based procurement models. United States grocery and convenience channels drive adoption fastest as retailers seek measurable shopper interaction data.
- Digital Display:LCD-embedded endcap units deliver dynamic content at decision zones. Chinese retailers deploy these for semi-permanent installations where traffic density justifies hardware investment.
- Temporary Display:Short-lifecycle corrugated units designed for four-to-six week promotional windows dominate quick-service restaurant and convenience store channels in Texas and Florida metropolitan corridors.
Standard Display anchors the volume base while Interactive Display gains share at the steepest rate.
Material:
Cost tiers separate commodity corrugated from certified food-contact and bio-based alternatives, with regulatory compliance costs widening the spread between entry-level and premium substrate specifications.
- Cardboard:Recycled corrugated fiberboard dominates volume due to printability and cost efficiency, with engineering bifurcating between commodity displays and precision retail-ready formats with integrated handles and tear-open features. REACH compliance on coatings and adhesives extends qualification timelines for European deployments.
- Plastic:Rigid plastics and bio-based polyesters serve permanent fixture applications where durability requirements exceed corrugated capabilities. ECHA restrictions on halogenated flame retardants and phthalate plasticizers force reformulation in France and Benelux ahead of EU-wide harmonization.
- Metal:Steel and aluminum frameworks anchor club retail permanent displays that resist seasonal replacement cycles, limiting addressable market for temporary programs in warehouse formats.
- Wood:Hardwood and engineered timber substrates serve premium brand activations and trade show environments where tactile aesthetics justify material cost premiums.
Cardboard commands the highest shipment volumes while Plastic faces the steepest regulatory-driven substitution pressure.
End User:
Application requirements diverge between high-frequency replenishment environments and episodic event-based deployment, with certification complexity scaling alongside food-contact proximity.
- Supermarkets:Automated replenishment systems and perimeter grocery deployments demand FDA food-contact certification for displays adjacent to fresh categories. EPA VOC regulations on coatings add compliance layers for United States rollout programs.
- Retail Stores:General merchandise and apparel channels prioritize quick-turn promotional cycles, with procurement shifting from seasonal to campaign-based turnover in four-week windows.
- Trade Shows:Episodic deployment models favor lightweight collapsible structures with rapid assembly specifications for convention center logistics.
- Exhibitions:Museum and gallery environments emphasize aesthetic integration over commercial messaging, with extended installation timelines justifying premium material selections.
Supermarkets anchor the volume base while Trade Shows expand most quickly as event-based marketing rebounds.
Design Style:
Customer type stratification separates sustainability-mandated corporate procurement from performance-driven promotional budgets, with eco-friendly specifications increasingly written into retailer supplier qualification requirements.
- Eco-friendly:Recyclable corrugated and bio-based substrates align with EU Green Deal mandates and extended producer responsibility frameworks. German and French supermarket chains now require recyclable alternatives to permanent plastic fixtures.
- Minimalistic:Reduced-ink and structural-only designs serve cost-optimized programs where brand recognition relies on product visibility rather than graphic density.
- Bold:High-contrast graphics and saturated color palettes maximize shelf impact in high-traffic decision zones.
- Thematic:Seasonal and licensed-property integrations require rapid design-to-delivery cycles for holiday and entertainment tie-in windows.
Eco-friendly specifications are climbing the fastest as retailer sustainability mandates harden into procurement requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA anchors the dominant geography through Clean Air Act enforcement on display coatings and adhesives, while the EU Green Deal and F-Gas Regulation reshape material specifications across German and French retail chains. Demand concentrates in the United States, Germany, and China.
United States
Quick-service restaurant and convenience store channels in Texas and Florida metropolitan corridors drive four-week promotional display cycles. The EPA regulates volatile organic compound emissions from coatings under Clean Air Act provisions. Atlanta anchors integrated paperboard supply for grocery and club channel programs.
Germany
Supermarket chains deploy precision-engineered retail-ready formats with integrated handles for automated replenishment systems. The EU F-Gas Regulation and extended producer responsibility frameworks compel recyclable substrate transitions. Bavaria and Baden-Württemberg host corrugated design studios sustaining complex format engineering.
China
Major retailers deploy LCD-embedded endcap units to capture decision-zone attention in high-traffic locations. The Ministry of Ecology and Environment enforces dual carbon goals affecting material sourcing. Yangtze River Delta manufacturing clusters produce semi-permanent digital display hardware for domestic deployment.
France
Benelux-adjacent retail networks respond fastest to REACH restrictions on halogenated flame retardants in permanent fixtures. ECHA compliance requirements force bio-based polyester reformulation ahead of EU-wide harmonization. Île-de-France hosts premium brand activation studios serving trade show and exhibition channels.
India
Organized retail penetration in metropolitan corridors creates first-mover opportunity for corrugated retail-ready packaging adapted to ambient supply chain conditions. FSSAI guidelines govern food-contact safety for grocery perimeter deployments. Maharashtra and Gujarat industrial zones concentrate converting operations for domestic retail modernization.
POP Display Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with corrugated design capabilities and geographic footprint determining competitive position. The structure rewards studios with dedicated structural engineering talent and penalizes mid-tier converters lacking retail-ready format expertise. Three archetypes dominate: integrated paperboard suppliers with captive fiber supply, corrugated specialists with design studio networks, and diversified packaging conglomerates with display divisions. Competitive moves center on geographic expansion into emerging retail markets and portfolio diversification toward interactive and digital formats.
Among European-integrated leaders, DS Smith PLC exemplifies the design-studio archetype through corrugated engineering capabilities, while WestRock Company anchors North American scale. Smurfit Kappa Group PLC occupies a position bridging European expertise with Latin American retail expansion. These three represent the tier where structural packaging talent and geographic coverage converge.
| Leading Market Players |
|---|
| DS Smith PLC |
| WestRock Company |
| Smurfit Kappa Group PLC |
| International Paper Company |
| Stora Enso Oyj |
| Sonoco Products Company |
| Georgia-Pacific LLC |
| Menasha Packaging |
| Pratt Industries |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between major supermarket chains and integrated paperboard suppliers lock in corrugated fiberboard supply access while stabilizing unit cost visibility across volatile OCC feedstock cycles. These arrangements concentrate pricing power with converters possessing captive recycled fiber supply and structural design capabilities in Germany and the United States.
Pricing Analysis
Geographic price spreads widen between European precision-engineered retail-ready formats and North American commodity corrugated displays, reflecting divergent labor and certification cost structures. Three-tier pricing separates food-contact certified displays from standard promotional units and economy-grade temporary fixtures, with REACH compliance costs widening the premium-to-economy spread. Pricing pressure stems from OCC price volatility linked to Chinese import quota fluctuations, compressing margins for converters lacking backward integration into recycled fiber supply. Quick-service restaurant channels in Texas and Florida exhibit highest price sensitivity due to four-week promotional turnover cycles, while German supermarket chains prioritize specification compliance over unit cost.
Supply Chain Analysis
Inventory strategy bifurcates between German supermarket chains demanding just-in-time replenishment for automated systems and North American retailers maintaining strategic stockpiles of seasonal promotional units. Supply concentrates in Germany, the United States, and China, with corrugated design studios anchoring European engineering expertise and Yangtze River Delta clusters producing digital display hardware. Raw material dependencies center on OCC feedstock, bio-based polyester resins, and LCD panel components. Single-source vulnerability runs through Chinese LCD supply for digital display segments. Distribution runs through retail procurement departments, brand marketing agencies, and corrugated converter direct sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
POP display demand sits in early-cycle expansion as interactive sensor integration penetrates grocery and convenience channels, with NFC-enabled formats capturing measurable engagement metrics that justify premium procurement.
For Market Incumbents: Consolidate structural packaging engineering talent through acquisition of specialized design studios in Bavaria and Baden-Württemberg to defend against margin compression from commodity converter competition. Deepen backward integration into OCC feedstock supply to offset price volatility from Chinese import quota shifts. Prioritize certification investment for FDA food-contact and REACH-compliant coating formulations to maintain supplier qualification with German and French supermarket chains. For New Entrants and Emerging Players: Differentiate on sensor-analytics convergence by integrating footfall detection with inventory management systems, targeting quick-service restaurant channels in Texas and Florida metropolitan corridors with outcome-based performance models. Penetrate India's organized retail modernization through corrugated retail-ready formats adapted to ambient supply chain conditions in Maharashtra and Gujarat. Deploy direct sales forces to bypass incumbent distributor relationships in emerging markets. For Investors and Strategic Acquirers: Capital is best deployed toward corrugated specialists with established design studio networks and geographic footprint in Latin American retail expansion. Long-term viability favors converters bridging physical and digital display capabilities over pure commodity cardboard producers. Monitor LCD panel cost trajectories as inflection indicator for digital display segment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Design Studio Acquisition | Structural engineering talent concentration in Germany limits scalable program execution without dedicated capabilities. |
| Sensor-Analytics Integration | NFC and footfall sensor deployment enables outcome-based procurement models shifting buyer metrics from cost to engagement. |
| Bio-Based Material Reformulation | REACH restrictions on halogenated flame retardants force polyester substitution ahead of EU-wide harmonization timelines. |
| India Market Entry | Organized retail penetration in metropolitan corridors creates first-mover positioning for retail-ready corrugated formats. |
| Food-Contact Certification Expansion | FDA guidelines open grocery perimeter deployments previously restricted to non-food categories, expanding addressable shelf space. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with display procurement managers at supermarket chains, structural packaging engineers at corrugated converters, brand marketing directors, and retail fixture specification consultants; alongside secondary validation through EPA Clean Air Act filings, ECHA REACH substance restrictions, customs trade data on OCC imports, and SEC disclosures from integrated paperboard suppliers. Bottom-up demand modeling triangulated against top-down market sizing across corrugated fiberboard consumption patterns.
Across the analysis window, the forecasting framework modeled volume and value trajectories by display type, material substrate, end-user channel, and design style segmentation. CAGRs were derived from regression analysis against retail square footage expansion, promotional intensity indices, and regulatory compliance cost curves. Industry-specific inputs included supermarket automated replenishment adoption rates and digital display hardware cost decline curves.
The analysis sits within stated boundaries; outcomes outside sustained retail modernization in emerging markets or accelerated EU Green Deal implementation timelines would require recalibration. Forecasts reflect assumptions on OCC price stabilization and REACH harmonization progression. Revision becomes warranted when interactive display cost parity with standard cardboard units crosses adoption threshold thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Sheeted Labels Market
Packaging
Electron High Barrier Packaging Film Market
Packaging
Luxury Boxes Market
Packaging
Custom Packaging Market
Packaging
Container Liner Market
Packaging
Europe Contract Packaging Market
Packaging
Canada Plastic Packaging Market
Packaging
Automatic Powder Filling Machines Market
Packaging
Form-Fill-Seal (FFS) Packaging Machine Market
Packaging
Sterilization Tape Market
Packaging
Raffia Tapes Market
Packaging
Metal Drums Market
Packaging
Middle East and Africa Plastic Packaging Films Market
Packaging
Egypt Container Glass Market
Packaging
Global Flexible Packaging Market
Packaging
Thermal Transfer Roll Market