
 Packaging Inspection Systems Market | 2026-2036
Packaging Inspection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Inspection Systems Market Analytics
Aftermarket service revenue is narrowing toward software updates and predictive maintenance contracts as hardware margins compress. Cognex leverages its deep learning vision tools to sustain premium positioning in pharmaceutical serialization. Omron anchors its presence through integrated control systems that merge inspection with line automation. METTLER TOLEDO competes via precision checkweighing and metal detection combinations that occupy critical points in food processing lines.
Packaging inspection systems comprise automated hardware and software platforms that detect defects, contaminants, and labeling errors using machine vision, X-ray, or electromagnetic sensing technologies operating at throughputs exceeding 600 units per minute. These systems enforce lot traceability, seal integrity, and foreign-object exclusion across high-speed filling and sealing operations. Vision systems dominate current installed bases due to their versatility in label verification and dimensional checking, while AI-based solutions represent the fastest-expanding technology segment as neural networks reduce false-reject rates in complex packaging formats. X-ray inspection commands the highest per-unit pricing among product types, reflecting its specialized use in dense or metallized container applications where optical methods fail.
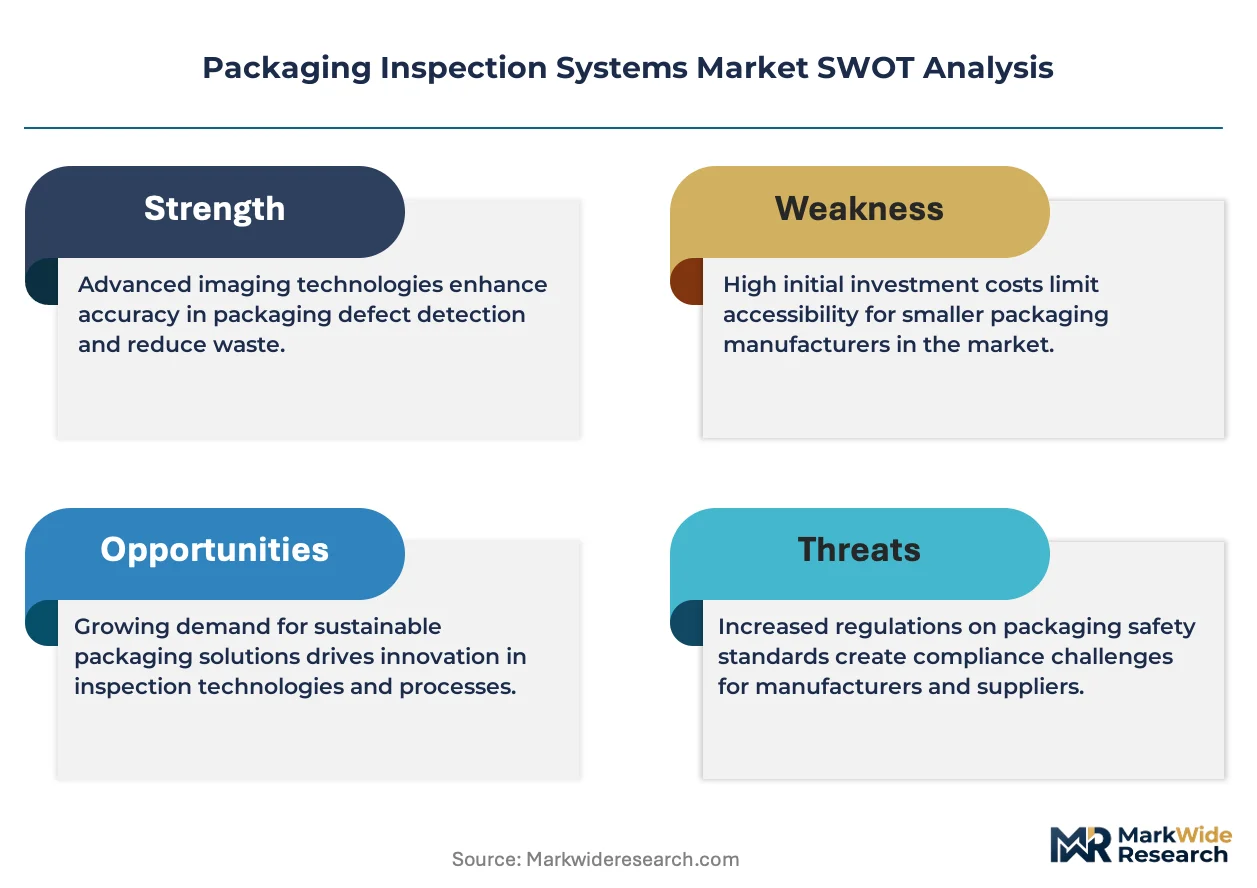
FDA enforcement of the Drug Supply Chain Security Act and EMA alignment with EU Good Manufacturing Practice Annex 1 revisions are mandating validated inspection protocols across pharmaceutical packaging operations. ISO 9001 and BRCGS certification requirements further compel food manufacturers to deploy documented, auditable inspection systems. Stakeholders must weigh capital deployment between incremental line upgrades and greenfield AI-native installations as regulatory validation timelines lengthen.
Market Dynamics
AI-native machine vision architectures are compressing validation cycles for pharmaceutical serialization, forcing incumbents to restructure R&D roadmaps around neural-network-based false-reject reduction rather than incremental sensor upgrades.
Growth Catalysts
- DSCSA Enforcement:FDA deadlines for unit-level traceability are compelling US pharmaceutical packagers to retrofit lines with validated inspection stations before compliance windows close.
- EU GMP Annex 1 Revisions:EMA-aligned sterility assurance mandates are expanding automated container-closure integrity testing across aseptic filling operations in European sterile injectables.
- Stuttgart-Düsseldorf Machinery Cluster:German OEM concentration accelerates technology diffusion through integrated line sales where inspection modules ship pre-validated with fillers and labelers.
Market Restraints
- Specialized Optics Supply Concentration:High-resolution CMOS sensors and telecentric lenses for pharmaceutical-grade vision systems source predominantly from East Asian component fabricators, creating single-source vulnerability.
- Validation Timeline Friction:FDA 21 CFR Part 11 and EU GMP Annex 15 documentation requirements extend commissioning cycles for AI-based inspection systems, delaying revenue recognition for vendors.
- Manual Sampling Persistence:Cost-sensitive food processors in private-label segments continue relying on statistical quality control rather than 100% automated inspection, capping addressable market expansion.
Strategic Opportunities
- Indian Pharmaceutical Export Growth:CDSCO alignment with PIC/S standards and US FDA inspection readiness investments are creating greenfield demand for serialization-ready vision systems in Ahmedabad and Hyderabad formulation clusters.
- X-Ray Convergence with Checkweighing:Combination systems integrating density-based foreign-object detection with precision mass measurement are penetrating metallized pouch applications in premium ready-meal segments.
- Outcome-Based Service Contracts:Predictive maintenance subscriptions tied to uptime guarantees are displacing traditional break-fix service revenue models among mid-cap contract packagers seeking operational expenditure predictability.
Industry Challenges
- Deep Learning Validation Expertise Gap:Pharmaceutical quality assurance teams lack personnel capable of training neural networks for defect classification while maintaining FDA-compliant algorithm change control.
- Legacy Line Integration Complexity:Retrofitting 1990s-era filling equipment with modern vision systems requires mechanical synchronization and protocol translation that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Inspection Systems Market |
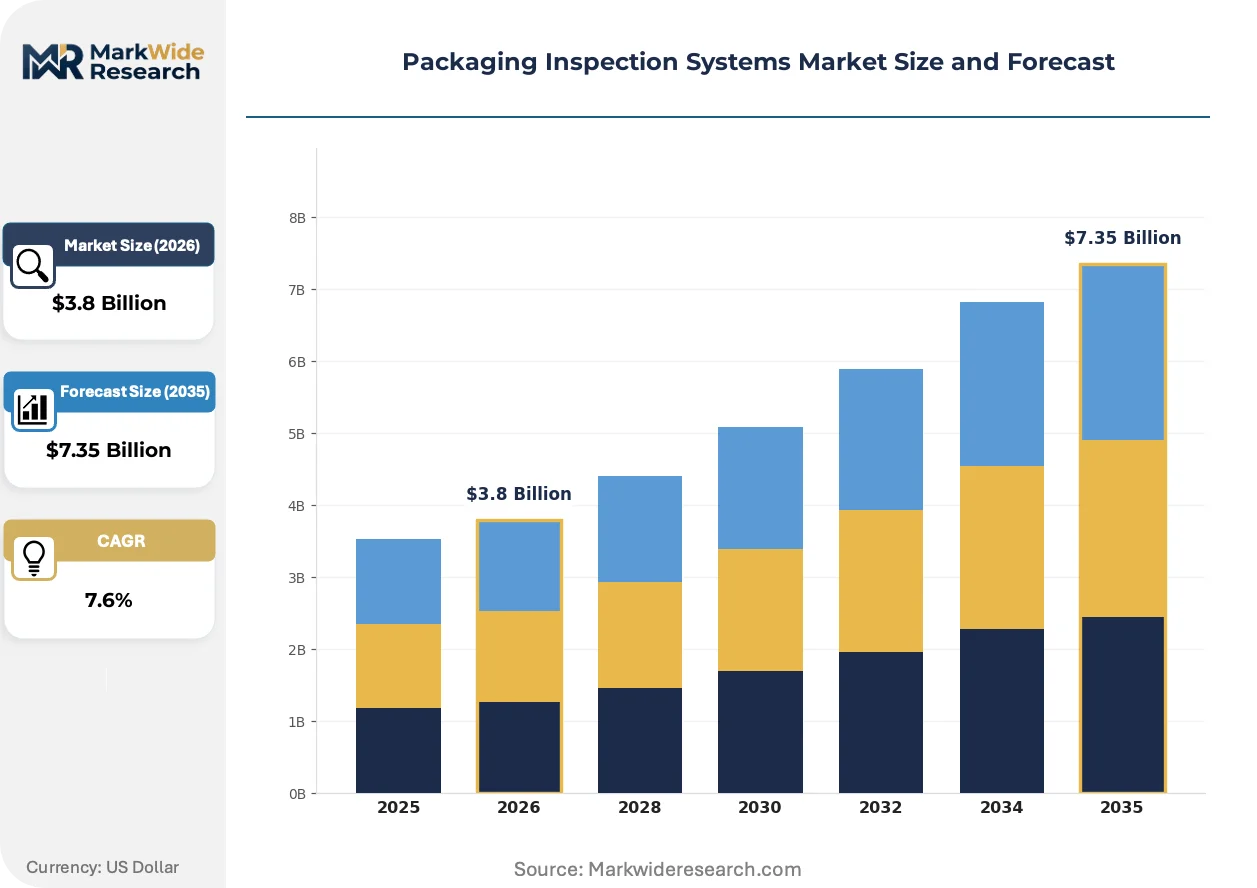
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vision Systems, X-ray Inspection, Metal Detectors, Leak Detection Application: Food Packaging, Pharmaceutical Packaging, Cosmetics, Electronics End User: Manufacturers, Distributors, Retailers, Quality Control Labs Technology: Automated Systems, Manual Inspection, Robotics, AI-Based Solutions |
| Companies Covered | PTI, Omron, Cognex, Sacmi Group, Industrial Physics, METTLER TOLEDO, Antares Vision Group, Dr. Schenk GmbH, ISRA VISION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Inspection Systems Market Evolving Landscape
Deep learning architectures are compressing the trade-off between inspection speed and classification accuracy, enabling pharmaceutical packagers to validate complex biologic container formats without sacrificing line throughput.
Hyperspectral imaging is migrating from laboratory material science applications into production-line foreign-object detection, where pharmaceutical glass manufacturers deploy the technology to identify inorganic contaminants invisible to standard RGB cameras. Early adopters in parenteral packaging are achieving sub-100-micron defect resolution at 400 units per minute. The technology is migrating from premium biologics into mainstream small-molecule injectables as sensor costs decline and FDA validation precedents accumulate.
EMA's 2023 revision to EU GMP Annex 1 mandates continuous viable and non-viable particle monitoring during aseptic processing, compelling isolator and restricted access barrier system manufacturers to integrate environmental monitoring with product inspection workflows. Sterile drug manufacturers must now demonstrate real-time contamination control data alongside container-closure integrity verification. German and Swiss fill-finish equipment vendors are responding with unified control architectures that merge environmental and product inspection data streams for single-source batch records.
Contract packagers are unbundling inspection system procurement from filler OEM line purchases, establishing direct relationships with specialized vision vendors to secure algorithm update commitments and faster technical support response. This disintermediation concentrates in North American pharmaceutical outsourcing, where CDMOs prioritize inspection flexibility across multiple client quality systems over integrated line warranties. Independent vision system vendors are capturing specification influence earlier in project cycles, reshaping how inspection technology penetrates greenfield capacity expansions.
Packaging Inspection Systems Market Segmentation
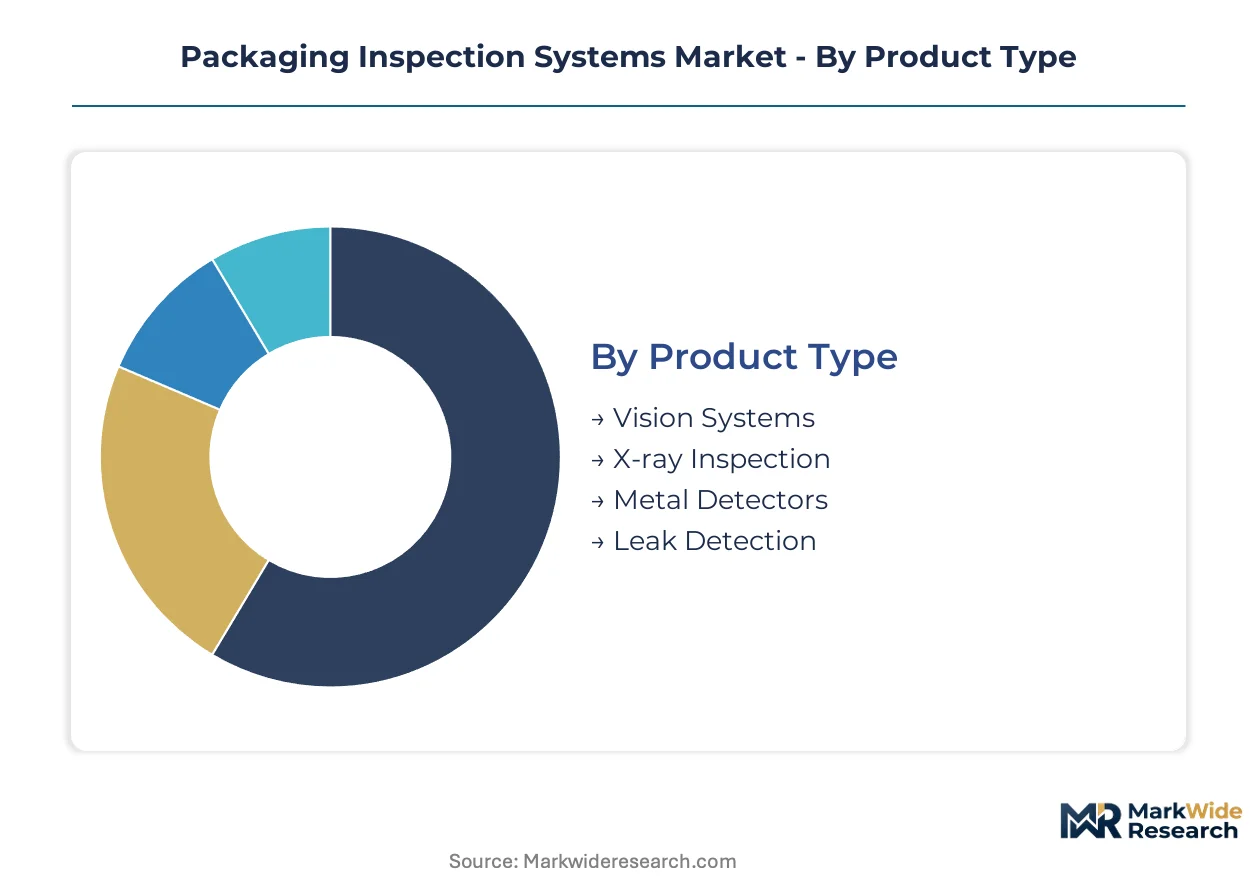
Segmentation in packaging inspection systems reveals how technology specialization, regulatory intensity, and end-use requirements fragment procurement patterns across industries. Pharmaceutical serialization mandates and food safety certifications create divergent specification pathways that vendors must navigate simultaneously.
Product Type:
Cost tier determines technology accessibility and validation burden across inspection modalities.
- Vision Systems:Machine vision platforms employ high-resolution CMOS sensors and telecentric optics for label verification, dimensional checking, and print quality assessment at throughputs exceeding 600 units per minute. Demand concentrates in German pharmaceutical packaging clusters around Stuttgart and Düsseldorf, where OEMs pre-validate vision modules with fillers and labelers to accelerate commissioning timelines.
- X-ray Inspection:Density-based detection systems penetrate metallized containers, composite packaging, and dense product matrices where optical methods fail, commanding premium pricing per unit. Food processors in premium ready-meal segments deploy these systems for foreign-object detection in retort pouches and foil-lidded trays, driven by BRCGS certification requirements and retailer liability protocols.
- Metal Detectors:Electromagnetic sensing platforms detect ferrous, non-ferrous, and stainless steel contaminants in dry and wet product environments.
- Leak Detection:Pressure-decay and vacuum-based systems verify container-closure integrity in aseptic and modified-atmosphere packaging applications.
Vision Systems holds installed capacity. X-ray Inspection is rotating up the share rankings.
Application:
Application scope reflects divergent regulatory enforcement intensity and contamination risk profiles across consumer industries.
- Food Packaging:Inspection protocols address foreign-object exclusion, fill-level verification, and seal integrity across high-speed filling operations. Private-label segments in cost-sensitive categories continue relying on statistical quality control rather than 100% automated inspection, capping addressable expansion in mainstream processed foods.
- Pharmaceutical Packaging:Serialization-ready vision systems enforce unit-level traceability, container-closure integrity, and label accuracy for sterile injectables and oral solid doses. FDA DSCSA enforcement and EU Falsified Medicines Directive compliance windows are compelling retrofit investments across US and European packaging lines.
- Cosmetics:Aesthetic defect detection and fill-level verification dominate specification requirements for premium personal care products.
- Electronics:Precision dimensional checking and component presence verification support semiconductor and consumer electronics packaging workflows.
Food Packaging commands current deployment volume. Pharmaceutical Packaging is gaining share fastest.
End User:
Customer type shapes procurement authority, technical sophistication, and service contract structures.
- Manufacturers:Brand-owner packaging operations specify inspection systems during greenfield capacity expansions and legacy line retrofits, prioritizing validated protocols and algorithm update commitments. North American pharmaceutical manufacturers are disintermediating filler OEMs to establish direct relationships with specialized vision vendors for faster technical support response.
- Distributors:Third-party logistics providers deploy inspection systems for inbound quality verification and outbound shipment validation.
- Retailers:Private-label quality assurance teams specify inspection requirements for contract packaging networks.
- Quality Control Labs:Laboratory environments utilize offline inspection systems for batch release testing and complaint investigation protocols.
Manufacturers retain specification authority. Quality Control Labs are expanding fastest as outsourcing deepens.
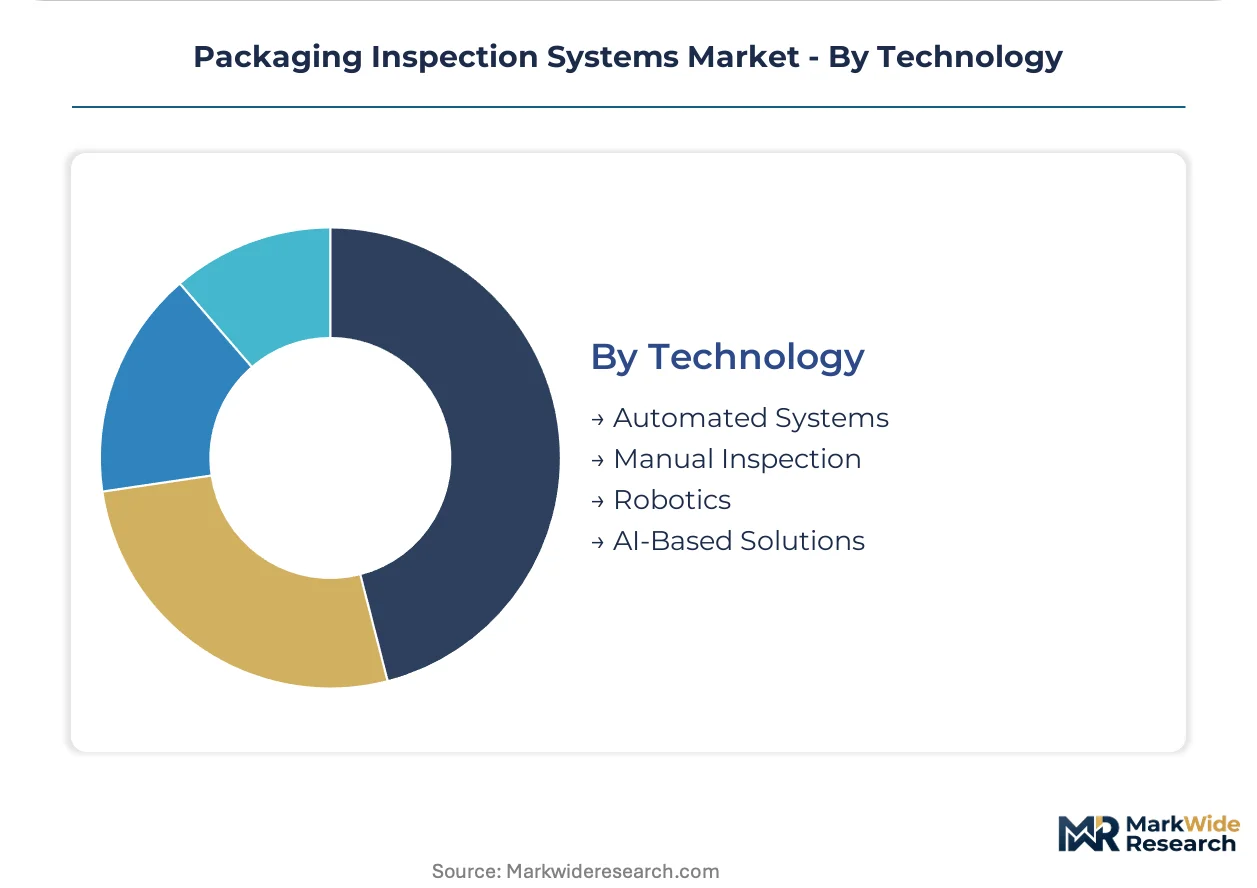
Technology:
Technology maturity determines validation timeline length and false-reject performance trade-offs.
- Automated Systems:Conventional machine vision and sensor fusion platforms operate at production speeds with established validation precedents and documented algorithm change control procedures. These systems dominate current installed bases across food and pharmaceutical packaging lines where regulatory familiarity reduces commissioning risk.
- AI-Based Solutions:Neural network architectures reduce false-reject rates in complex packaging formats through deep learning defect classification, though FDA 21 CFR Part 11 documentation requirements extend validation cycles. Pharmaceutical quality assurance teams face expertise gaps in training neural networks while maintaining compliant algorithm governance.
- Manual Inspection:Human visual verification persists in low-volume specialty applications and complaint investigation workflows.
- Robotics:Collaborative inspection cells integrate adaptive handling with vision-guided defect removal for flexible packaging formats.
Automated Systems anchors current deployment. AI-Based Solutions shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical packagers deploy vision systems primarily for serialization compliance, while US food processors emphasize X-ray detection for liability mitigation, revealing a regulatory-versus-risk split in technology preference across major demand centers.
United States
FDA enforcement of DSCSA unit-level traceability deadlines drives retrofit demand across legacy pharmaceutical packaging lines. The agency's 21 CFR Part 11 validation requirements extend commissioning cycles for AI-based inspection systems. New Jersey and North Carolina formulation clusters anchor domestic demand for serialization-ready vision platforms.
Germany
EMA-aligned EU GMP Annex 1 sterility assurance mandates expand automated container-closure integrity testing across aseptic filling operations. Stuttgart and Düsseldorf machinery OEM clusters accelerate technology diffusion through pre-validated inspection modules bundled with fillers and labelers. German packagers prioritize integrated line architectures over standalone system procurement.
India
CDSCO alignment with PIC/S standards and US FDA inspection readiness investments create greenfield demand for serialization-ready vision systems. Ahmedabad and Hyderabad formulation clusters represent the fastest-expanding addressable market for pharmaceutical-grade inspection technology. Domestic contract manufacturers prioritize direct vendor relationships to secure algorithm update commitments.
China
NMPA serialization requirements for domestic pharmaceutical distribution converge with export-oriented FDA and EMA compliance investments. Yangtze River Delta packaging machinery manufacturers integrate vision modules with filling equipment for regional and overseas markets. Shanghai and Suzhou industrial zones concentrate both OEM production and end-user demand.
Switzerland
Swissmedic enforcement of batch release documentation standards sustains premium positioning for validated inspection protocols across sterile injectables manufacturing. Basel and Zurich biologics clusters demand sub-100-micron defect resolution for complex container formats. Swiss fill-finish equipment vendors merge environmental monitoring with product inspection data streams for unified batch records.
Packaging Inspection Systems Market Competitive Landscape
Capability concentration sits with specialized vision technology developers; scale advantage sits with diversified automation conglomerates. The vendor base organizes around three strategic archetypes: machine vision specialists leveraging deep learning differentiation, integrated control system providers bundling inspection with line automation, and precision instrumentation houses combining checkweighing with contaminant detection. Portfolio diversification and geographic expansion through machinery OEM partnerships constitute the dominant competitive moves.
Among diversified automation conglomerates, Omron and Cognex exemplify contrasting positioning strategies. Omron anchors its presence through integrated control systems that merge inspection functionality with broader line automation architectures. Cognex occupies a specialist position emphasizing deep learning vision tools for pharmaceutical serialization applications. METTLER TOLEDO represents the precision instrumentation archetype, competing via precision checkweighing and metal detection combinations that occupy critical control points in processing lines. Sacmi Group and Antares Vision Group sit within the machinery OEM tier, embedding inspection modules within integrated filling and labeling systems.
| Leading Market Players |
|---|
| PTI |
| Omron |
| Cognex |
| Sacmi Group |
| Industrial Physics |
| METTLER TOLEDO |
| Antares Vision Group |
| Dr. Schenk GmbH |
| ISRA VISION |
| Others |
Value Network & Pricing Analysis
Undercapacity in high-resolution CMOS sensor fabrication is compressing margins for vision system vendors while simultaneously elevating pricing power among East Asian optical component suppliers serving pharmaceutical-grade inspection markets.
Pricing Analysis
Long-term service contracts dominate procurement structures, with predictive maintenance subscriptions displacing transactional hardware sales across mid-cap contract packagers. Three-tier pricing structure across premium, standard, and economy levels separates AI-native validation-ready systems from conventional machine vision and basic sensor platforms. Cost compression in standard-tier hardware is intensifying because German OEMs bundle pre-validated inspection modules at volume discounts. Private-label food processors exhibit highest price sensitivity, while sterile injectables manufacturers prioritize validation speed over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwanese and South Korean CMOS foundries, alongside German precision optics houses in Jena and Oberkochen. Supply chains draw from rare-earth phosphors for X-ray detectors, telecentric lens assemblies, and FPGA processors for real-time image processing. Single-source vulnerability in high-resolution sensor supply creates exposure to geopolitical disruption and allocation constraints. Distribution runs through machinery OEM integration channels in Stuttgart-Düsseldorf clusters and direct vendor relationships with North American CDMOs seeking algorithm governance autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical serialization compliance deadlines are driving a cyclical recovery in retrofit demand, with FDA DSCSA enforcement windows creating predictable replacement cycles across legacy packaging lines.
For Market Incumbents: Pre-empt disintermediation by filler OEMs through direct algorithm update commitments and faster technical support response to North American CDMOs. Secure captive supply of high-resolution CMOS sensors via strategic partnerships with Taiwanese foundries to mitigate single-source exposure. Deep learning validation expertise gaps among pharmaceutical quality teams represent a defensive moat for vendors with compliant neural network governance frameworks.
For New Entrants and Emerging Players: Indian pharmaceutical export clusters in Ahmedabad and Hyderabad offer underpenetrated greenfield demand for serialization-ready vision systems as CDSCO aligns with PIC/S standards. Target outcome-based service contracts with mid-cap contract packagers seeking operational expenditure predictability rather than capital-intensive hardware sales. Partner with German machinery OEMs for pre-validated module integration to bypass lengthy standalone validation cycles.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized vision vendors with predictive maintenance subscriptions and algorithm update entitlements. Long-term viability favors AI-native architectures capable of FDA-compliant neural network governance rather than incremental sensor upgrades. Monitor CDSCO inspection readiness investments and US FDA warning letter trends as inflection indicators for Indian pharmaceutical packaging demand.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Validation Platform Development | Neural network architectures reduce false-reject rates in complex biologic container formats while compressing FDA 21 CFR Part 11 documentation cycles. |
| Predictive Maintenance Subscription Conversion | Outcome-based service contracts displace break-fix revenue models among mid-cap contract packagers seeking uptime guarantees. |
| Direct CDMO Relationship Establishment | Disintermediation from filler OEMs concentrates specification influence with specialized vision vendors in North American pharmaceutical outsourcing. |
| Hyperspectral Imaging Production Migration | Sub-100-micron defect resolution at 400 units per minute penetrates mainstream small-molecule injectables as sensor costs decline. |
| East Asian Component Supply Partnership | Strategic alliances with Taiwanese CMOS foundries mitigate single-source vulnerability in high-resolution sensor procurement. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical quality assurance directors, packaging machinery OEM procurement leads, contract manufacturing operations managers, and vision system integration specialists and refined through secondary validation against FDA 21 CFR Part 11 guidance documents, EMA EU GMP Annex 1 revision texts, CDSCO regulatory circulars, and machinery OEM technical specifications. Bottom-up triangulation across installed base estimates and top-down cross-checks against pharmaceutical packaging capital expenditure disclosures anchored volume and value outputs.
Demand-supply-balance framing structured the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application, technology maturity, and regional regulatory cluster intensity. CAGRs were derived from regression analysis of historical retrofit cycles and greenfield capacity expansion patterns, incorporating pharmaceutical serialization compliance windows and food safety certification renewal schedules as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-native entrants with validated deep learning architectures would shift outcomes beyond modeled ranges. Quarterly review of FDA DSCSA enforcement actions, EMA inspection deficiency trends, and CDSCO PIC/S alignment progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Package Testing Silicone Rubber Socket Market
Packaging Testing
Heat Sealing Tester Market
Packaging Testing
Pre-Validated Packaging Market
Packaging Testing
Food Packaging Tester Market
Packaging Testing
Packaging Burst Strength Test Market
Packaging Testing
Packaging Extended Producer Responsibility Compliance Test Platforms Market
Packaging Testing
Middle East and Africa Package Testing Market
Packaging Testing
Europe Package Testing Market
Packaging Testing
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market
Packaging Testing
Packaging Testing Equipment Market
Packaging Testing
Packaging Testing Market
Packaging Testing
Box Compression Tester Market
Packaging Testing
Bottle Perpendicularity Tester Market
Packaging Testing
Humidity Indicator Cards (HIC) Market
Packaging Testing
North America Package Testing Market
Packaging Testing
Packaging Testing Services Market