
 GCC Paper Packaging Market | 2026-2036
GCC Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Paper Packaging Market Intelligence
Modular packaging configurations are restructuring how GCC buyers specify container formats across food delivery and retail channels. Huhtamaki Oyj leverages its molded fiber technology leadership to supply quick-service restaurant chains across the Gulf. Al Ghurair Packaging LLC anchors regional corrugated board production with integrated paper mill operations in Dubai. Mondi plc competes through specialty kraft paper grades engineered for humidity resistance in Gulf climates.
GCC paper packaging encompasses containers, wraps, and protective structures fabricated from kraft paper, corrugated paper, carton board, or paperboard, typically ranging from 150 gsm to 600 gsm depending on load-bearing requirements, and serves to enclose, protect, and present goods for distribution and sale. The material dimension shows corrugated paper dominating industrial and e-commerce applications due to stack strength and recyclability, while kraft paper gains share in food wraps and carry bags as plastic substitution accelerates. Food packaging leads the application structure, with hot-fill and grease-resistant coatings expanding functional performance for regional ready-meal brands.
Saudi Standards, Metrology and Quality Organization (SASO) mandates govern fiber-based food contact materials, while UAE's Ministry of Climate Change and Environment enforces extended producer responsibility frameworks for packaging waste. These regulations shape demand by requiring recyclable content thresholds and restricting per-fluorinated chemical treatments in food-grade paper. Stakeholders must monitor how Gulf harmonization of circular economy standards affects imported versus locally manufactured board specifications.
Market Dynamics
Regulatory mandates from Saudi Vision 2030 and UAE's single-use plastic restrictions are compressing substitution timelines, forcing foodservice operators to accelerate molded fiber and kraft paper adoption across quick-service restaurant chains and e-commerce fulfillment networks.
Growth Catalysts
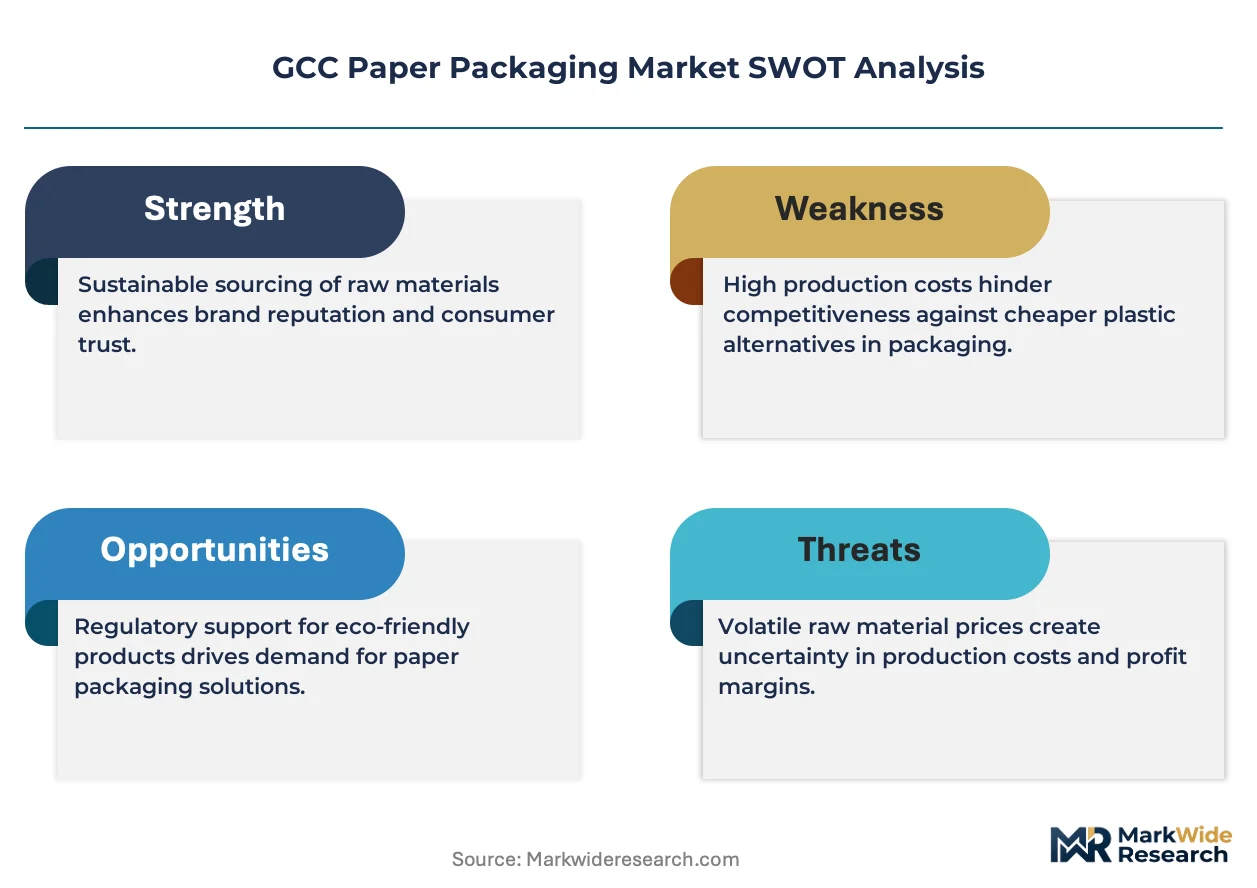
- SASO Fiber-Based Food Contact Standards:Saudi Arabia's technical regulations mandate recyclable content thresholds for food-grade paper, compelling quick-service restaurant chains to source compliant molded fiber trays from regional converters.
- Quick-Service Restaurant Expansion:Drive-thru and delivery formats across Riyadh-Jeddah corridor are consuming corrugated clamshells and grease-resistant wraps at volumes that justify dedicated regional production lines.
- Water-Based Barrier Coatings:Hot-fill and oil-resistant formulations are displacing per-fluorinated chemical treatments, enabling paper packaging penetration into ready-meal and fried food segments previously blocked by performance gaps.
Market Restraints
- Recycled Pulp Supply Concentration:GCC domestic pulp production remains minimal, leaving converters dependent on European and Southeast Asian recovered fiber imports subject to shipping rate volatility.
- Humidity Performance Ceiling:Standard kraft paper grades suffer structural degradation above 75% relative humidity, limiting shelf-stable food applications in coastal UAE and Saudi Eastern Province.
- Extended Producer Responsibility Cost Allocation:UAE's Ministry of Climate Change and Environment packaging waste frameworks impose collection infrastructure investments that compress margins for imported board distributors versus integrated local producers.
Strategic Opportunities
- Kuwait and Bahrain Underpenetration:These markets lack integrated molded fiber production, creating first-mover advantage for Saudi and UAE converters with cross-border logistics capabilities.
- E-Commerce Cold Chain Expansion:Insulated corrugated liners for fresh grocery delivery represent white space as regional online grocers scale temperature-controlled last-mile networks.
- Green Building Material Certification:LEED and Estidama standards are creating specification pull for paper-based protective packaging in construction materials, diverting volume from expanded polystyrene.
Industry Challenges
- Barrier Coating Technical Talent Scarcity:Formulation chemists with water-based grease and moisture resistance expertise command premium compensation, constraining regional R&D expansion.
- SASO Compliance Timeline Compression:New food contact material notification requirements extend product qualification cycles, delaying commercialization of innovative substrate grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Paper Packaging Market |
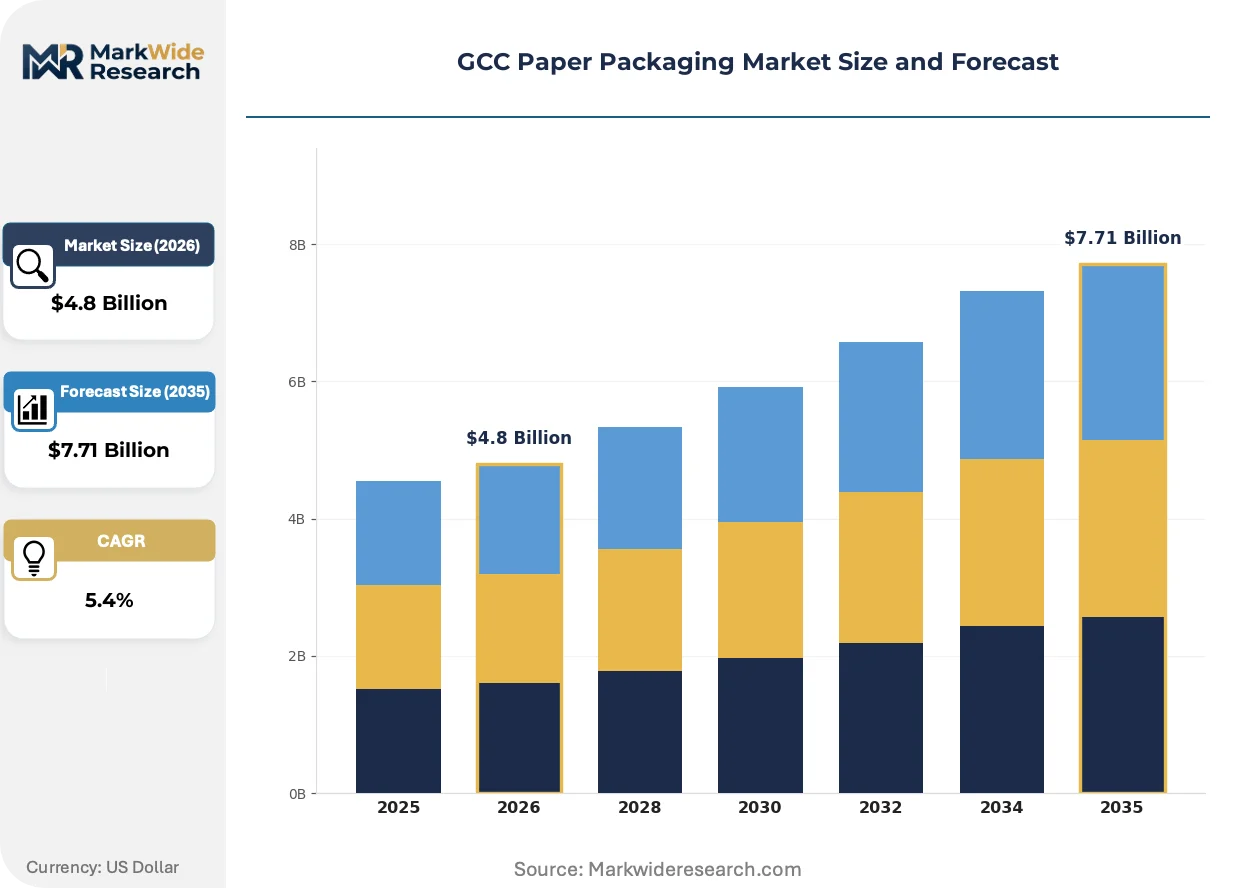
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Wraps, Labels Material: Kraft Paper, Corrugated Paper, Carton Board, Paperboard Application: Food Packaging, Electronics Packaging, Cosmetics Packaging, Industrial Packaging End User: Food & Beverage, Retail, Healthcare, E-commerce |
| Companies Covered | Huhtamaki Oyj, Al Ghurair Packaging LLC, Tetra Pak International SA, Najmuddin Packaging and Refilling Industry LLC, Gulf East Paper and Plastic Industries LLC, Mondi plc, Napco National CJSC, Hotpack Packaging Industries LLC, Arabian Packaging LLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Paper Packaging Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are converging to redefine performance specifications across hot-fill, frozen, and ambient food packaging applications in Gulf climates.
Water-based barrier coating technology is unifying grease resistance and moisture protection in single-substrate solutions. Quick-service restaurant chains in Dubai and Riyadh are specifying these coatings for fried chicken and burger packaging to eliminate polyethylene lamination layers. This unification is compressing the cost gap between functional paper and plastic alternatives, accelerating volume migration in segments where performance parity was previously unattainable.
UAE's Ministry of Climate Change and Environment extended producer responsibility frameworks are mandating packaging waste collection and recycling infrastructure investments by brand owners and importers. Industrial consequence includes preferential procurement from converters with in-house recycling loops or verified post-consumer content chains. Food and beverage multinationals operating Gulf manufacturing are responding by consolidating supplier bases toward vertically integrated regional paperboard producers.
Centralized procurement by e-commerce platform operators is consolidating box specification power into fewer decision-makers. Traditional distributor networks serving fragmented retail are losing share to direct mill relationships for corrugated and mailer formats. This concentration is most visible in Jebel Ali and Riyadh industrial zones where Amazon, Noon, and Talabat fulfillment centers negotiate annual volume contracts with board producers.
GCC Paper Packaging Market Segmentation
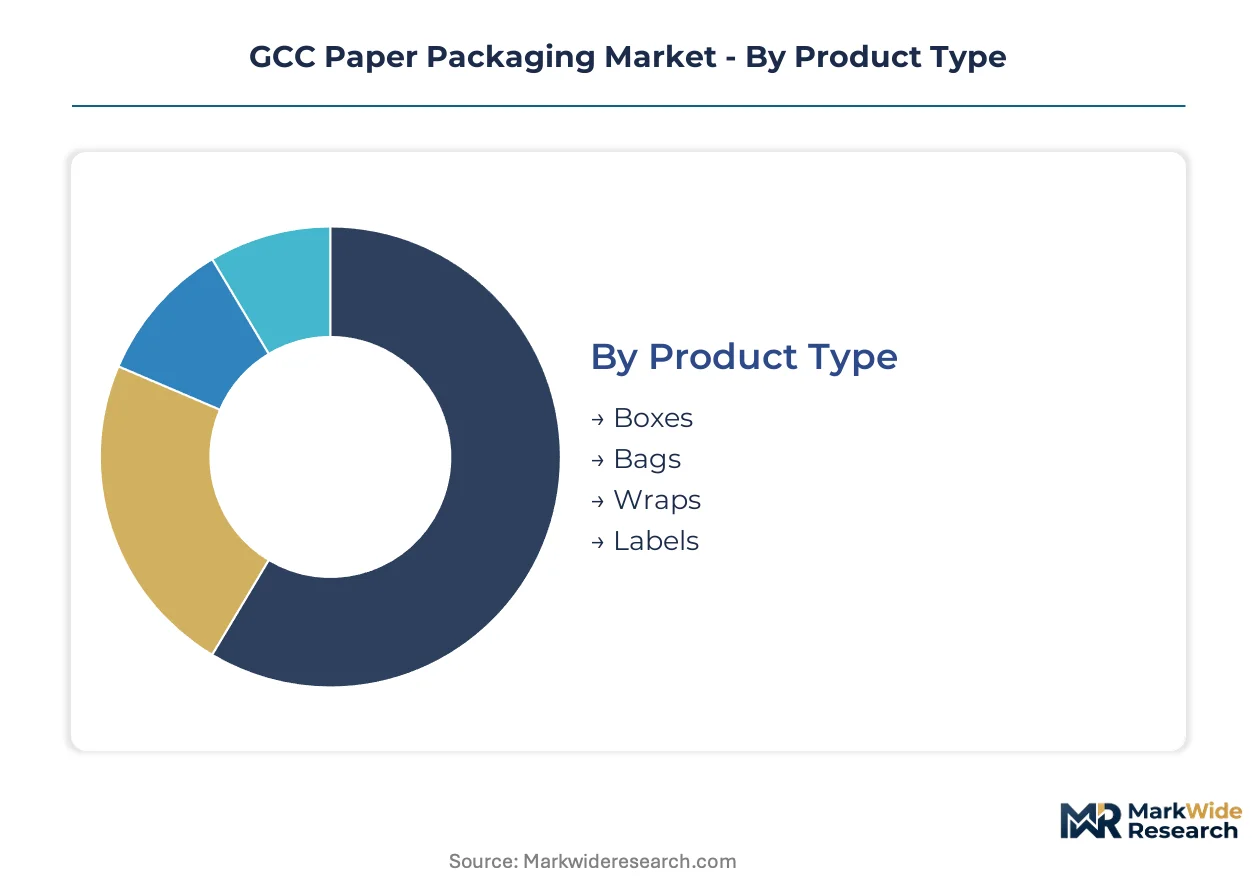
Paper packaging procurement across the GCC clusters around load-bearing specifications and barrier performance requirements that vary sharply by end-use. Understanding these segment boundaries reveals where capital deployment yields the strongest returns for converters and where regulatory compliance creates entry barriers.
Product Type:
Boxes demand the heaviest upfront investment in corrugators and die-cutting infrastructure, while labels require precision printing equipment with lower capital thresholds.
- Boxes:Corrugated and carton board containers ranging from 150 gsm to 600 gsm provide stack strength for e-commerce fulfillment and industrial distribution. Riyadh-Jeddah corridor fulfillment centers for Amazon, Noon, and Talabat negotiate annual volume contracts directly with board producers, bypassing traditional distributor networks.
- Bags:Kraft paper carry bags and pouches substitute for banned single-use plastics under UAE Ministry of Climate Change and Environment frameworks. Quick-service restaurant chains across Dubai industrial zone specify grease-resistant formulations for fried food applications.
- Wraps:Flexible kraft and parchment papers protect perishables and ready-meals.
- Labels:Adhesive-backed paper stocks for branding and regulatory compliance marking.
Boxes absorb the bulk of installed capacity; bags are expanding most quickly as plastic substitution accelerates.
Material:
Corrugated paper commands the highest per-tonne capital intensity due to integrated pulping and linerboard production requirements.
- Corrugated Paper:Fluted medium sandwiched between linerboards delivers compression resistance for shipping containers. E-commerce cold chain expansion across Saudi Arabia and the UAE is driving specification of insulated corrugated liners for fresh grocery delivery.
- Kraft Paper:Unbleached sulfate pulp yields high tear strength for wraps and bags. Humidity performance ceilings above 75% relative humidity constrain shelf-stable food applications in coastal UAE and Saudi Eastern Province.
- Carton Board:Folding boxboard for retail-ready packaging.
- Paperboard:Multi-ply grades for premium cosmetic and pharmaceutical cartons.
Corrugated paper dominates tonnage throughput; kraft paper is climbing the fastest as foodservice operators eliminate polyethylene lamination layers.
Application:
Food packaging requires the most complex coating investments to meet SASO fiber-based food contact standards.
- Food Packaging:Hot-fill and grease-resistant coatings enable molded fiber trays and corrugated clamshells for quick-service restaurant chains. Water-based barrier formulations displace per-fluorinated chemical treatments previously blocking paper penetration in fried food segments.
- Electronics Packaging:Anti-static corrugated and molded fiber cushions protect semiconductors and consumer devices during Gulf climate shipping.
- Cosmetics Packaging:Rigid boxboard and folding cartons for premium beauty brands.
- Industrial Packaging:Heavy-duty corrugated and protective wraps for construction materials and machinery.
Food packaging claims the largest share of converter revenue; electronics packaging is gaining share fastest as regional device assembly expands.
End User:
E-commerce operators concentrate procurement power through centralized specification, while healthcare demands the most stringent validation documentation.
- Food & Beverage:Quick-service restaurant chains and ready-meal brands across Saudi Arabia and the UAE specify recyclable content thresholds mandated by SASO. Molded fiber tray volumes justify dedicated regional production lines.
- E-commerce:Platform operators including Amazon and Noon consolidate box specifications into direct mill relationships. Jebel Ali and Riyadh industrial zone fulfillment centers drive standardization of mailer formats.
- Retail:Supermarket and hypermarket chains for private-label packaging.
- Healthcare:Sterile barrier systems and pharmaceutical cartons requiring compliance with national pharmaceutical regulators.
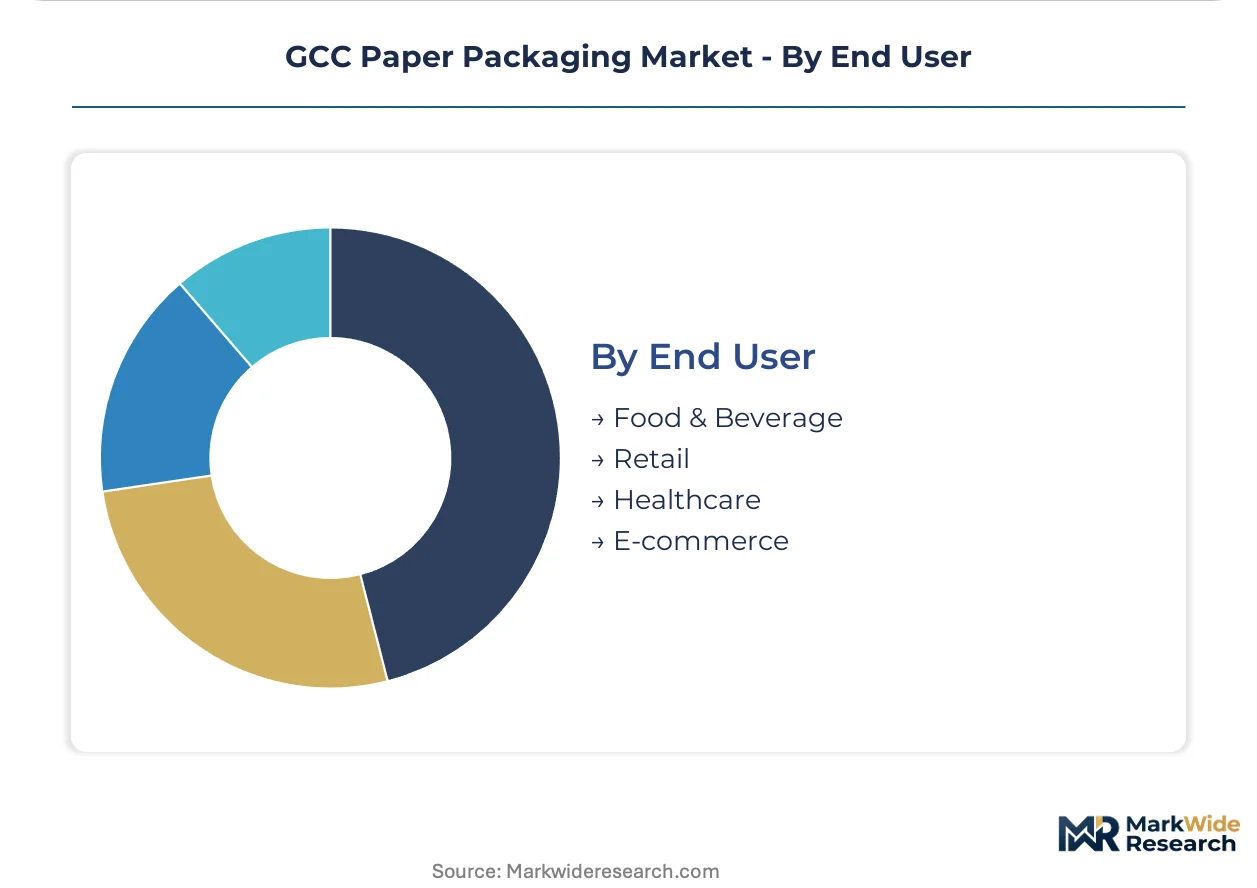
Food and beverage anchors current demand; e-commerce is expanding most quickly as online grocery penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GCC paper packaging consumption outstrips regional pulp production, creating import dependency that shapes procurement patterns. Saudi Arabia and the UAE absorb the majority of tonnage, while smaller markets present expansion opportunities for cross-border suppliers.
Saudi Arabia
Quick-service restaurant chains and e-commerce fulfillment centers drive molded fiber tray and corrugated box demand across the Riyadh-Jeddah corridor. SASO fiber-based food contact standards mandate recyclable content thresholds, compelling operators to source compliant packaging from regional converters. Jeddah's industrial zone hosts dedicated production lines serving Western Province foodservice networks.
United Arab Emirates
Dubai's logistics hub concentrates procurement power among Amazon, Noon, and Talabat fulfillment operators negotiating direct mill contracts. UAE Ministry of Climate Change and Environment extended producer responsibility frameworks impose collection infrastructure investments on importers. Jebel Ali industrial zone standardizes mailer formats across e-commerce cold chain expansion.
Kuwait
Foodservice operators rely on cross-border supply from Saudi and UAE converters due to absent integrated molded fiber production. The country's national environmental regulator enforces packaging waste guidelines without domestic recycling infrastructure. Kuwait City retail chains import corrugated containers through Gulf East Paper and Plastic Industries distribution networks.
Qatar
Hospitality and retail sectors generate premium carton board demand for luxury goods presentation. National sustainability frameworks align with broader Gulf circular economy harmonization efforts. Doha industrial zone hosts limited converting capacity, leaving most specifications fulfilled by UAE-based suppliers.
Bahrain
Underpenetrated converting infrastructure creates first-mover positioning for Saudi exporters with established cross-border logistics. Food contact material regulations follow Gulf Cooperation Council technical harmonization rather than independent standards. Manama's retail and foodservice sectors source kraft bags and wraps through regional distributor networks.
GCC Paper Packaging Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across GCC paper packaging procurement channels. The market structure shows moderate consolidation around integrated pulp-to-board producers and regional converting specialists. Two strategic archetypes dominate: multinational packaging technology leaders with Gulf distribution partnerships, and vertically integrated local conglomerates controlling captive paper mill supply. Competitive dynamics center on capacity expansion in Riyadh-Jeddah and Dubai industrial corridors, alongside strategic partnerships securing water-based barrier coating formulation access.
Among Nordic-based packaging technology groups, Huhtamaki Oyj exemplifies the multinational specialist archetype through molded fiber technology deployment. Al Ghurair Packaging LLC anchors the integrated regional producer tier with Dubai-based paper mill operations. Mondi plc occupies a position representing European specialty kraft paper supply into Gulf humidity-resistant applications.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Al Ghurair Packaging LLC |
| Tetra Pak International SA |
| Najmuddin Packaging and Refilling Industry LLC |
| Gulf East Paper and Plastic Industries LLC |
| Mondi plc |
| Napco National CJSC |
| Hotpack Packaging Industries LLC |
| Arabian Packaging LLC |
| Others |
Cost & Logistics Intelligence
Recovered fiber price indices from European and Southeast Asian export markets cascade through GCC converter cost structures, stratifying procurement economics between integrated mill operators and import-dependent distributors across Saudi Arabia and the UAE.
Pricing Analysis
Margin tightening in standard-grade kraft paper reflects shipping rate volatility on recovered pulp imports from European and Southeast Asian sources. Three-tier pricing structure across premium, standard, and economy levels separates water-based barrier-coated food-grade substrates from commodity corrugated grades. Pricing pressure intensifies in standard tiers as UAE extended producer responsibility frameworks impose collection infrastructure investments on non-integrated distributors. Quick-service restaurant chains demonstrate highest price sensitivity through centralized procurement, while pharmaceutical and cosmetics buyers absorb premiums for certified food-contact and humidity-resistant specifications.
Supply Chain Analysis
Post-consumer collection and mill recycling loops are consolidating around Jebel Ali and Riyadh industrial zones as UAE and Saudi regulators mandate verified recycled content chains. Geographic supply concentrates in Finland, Sweden, and Germany for specialty kraft pulp, and in Indonesia and Thailand for containerboard-grade recovered fiber. Raw material dependencies rest on European linerboard imports, Southeast Asian OCC (old corrugated containers) shipments, and regional water-based coating chemical supplies. Single-source vulnerability on coated food-grade substrates creates procurement risk for quick-service restaurant chains. Distribution runs through direct mill relationships for e-commerce platform operators, while fragmented retail channels persist with regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive pulp supply and in-house coating formulation capability is becoming the decisive competitive moat as SASO compliance timelines compress and barrier coating talent scarcity intensifies.
For Market Incumbents: Extend water-based barrier coating R&D capabilities through specialist chemist recruitment in Dubai and Riyadh to defend against emerging pure-play coating technology firms. Consolidate supplier relationships with European pulp traders through long-term offtake agreements that lock in recovered fiber supply ahead of shipping rate spikes. Capacity addition in Jeddah industrial zone anchors Western Province quick-service restaurant demand. For New Entrants and Emerging Players: Quick-service restaurant distributors in Kuwait and Bahrain represent the most penetrable channel target, given absent integrated molded fiber production and reliance on cross-border Saudi supply. White-space opportunities concentrate in insulated corrugated liners for e-commerce cold chain expansion, where regional online grocers lack qualified domestic suppliers. Go-to-market positioning should emphasize SASO pre-certified substrate grades to compress qualification cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale UAE converters with underutilized corrugator capacity and established Jebel Ali logistics access. Long-term viability hinges on water-based coating formulation ownership rather than toll-processing dependencies. Acquisition target archetype: Saudi-based integrated producers with captive paper mill supply and existing quick-service restaurant chain contracts. Signal to watch: SASO notification requirement backlogs that strand competitor product launches.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber Supply | Captive pulp supply insulates margin from shipping rate volatility on European and Southeast Asian imports. |
| Water-Based Barrier Coating Capacity Expansion | In-house formulation capability captures quick-service restaurant volume migrating from polyethylene-laminated alternatives. |
| SASO Pre-Certification Investment | Accelerated product qualification cycles defend share as Saudi food contact standards tighten. |
| Cross-Border Logistics Infrastructure | Kuwait and Bahrain distribution networks exploit underpenetrated molded fiber demand. |
| E-Commerce Cold Chain Packaging Development | Insulated corrugated liners address white space in Saudi and UAE fresh grocery delivery scaling. |
Research Approach
Trade statistics from Saudi Customs Authority, UAE Federal Customs Authority, and Eurostat export databases formed the secondary backbone, cross-referenced with SASO technical regulation filings and UAE Ministry of Climate Change and Environment circular economy policy documents. Primary interviews with procurement directors at quick-service restaurant chains, plant managers at Dubai and Riyadh converting facilities, and coating formulation specialists informed capacity utilization and technology adoption patterns. Bottom-up volume estimates from individual facility throughput triangulated against top-down demand aggregation from e-commerce platform fulfillment center expansion announcements.
Historical trendline analysis of corrugated and kraft paper consumption patterns informed baseline calibration across the projection horizon. Segmentation modeling incorporated product type, material grade, application functional requirements, and end-user procurement concentration dimensions. CAGRs were derived from elasticity-adjusted demand drivers including quick-service restaurant outlet expansion, e-commerce penetration rates, and regulatory substitution timelines. Industry-specific forecast inputs included water-based coating technology maturity curves and Gulf harmonization progress on extended producer responsibility frameworks.
Caveats apply where shipping rate volatility on recovered fiber imports or SASO compliance timeline extensions could materially shift the outlook. Forecasts reflect assumptions regarding coating formulation performance parity achievement and quick-service restaurant chain consolidation trajectories. Practitioners should monitor European pulp export policy shifts and Gulf Cooperation Council circular economy harmonization announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Germany Honeycomb Paper Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
Air Fryer Paper Liners Market
Paper & Paperboard Packaging
Paper Based Consumer Bags Market
Paper & Paperboard Packaging
Medical Packaging Paper Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Sublimation Paper Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Kraft Paper Bags Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
Global VCI Paper Market