
 Gun Care Products Market | 2026-2036
Gun Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Gun Care Products Market Analytics
ISO 9001 certification is reorganizing competitive access in gun care products, as defense contractors and law enforcement agencies require documented quality management systems for supplier qualification. Lucas Oil Products leverages its automotive lubricant R&D infrastructure to cross-develop firearm-specific formulations. Hoppe's sustains brand dominance through century-plus retail channel penetration in sporting goods. Ballistol anchors its position with plant-based chemistry that navigates tightening environmental compliance in European markets.
Gun care products encompass chemical formulations and mechanical tools engineered to remove carbon fouling, copper deposits, and moisture from weapon systems while maintaining operational reliability; solvent formulations typically specify flash points above 140°F and chloride-free composition to prevent barrel pitting. Lubricants command the largest product-type margin pool due to recurring application cycles, while cleaning kits experience faster volume growth as first-time firearm purchasers seek integrated maintenance solutions. Military application segments concentrate procurement through multi-year supply agreements, whereas hobbyist end users fragment across retail and e-commerce channels with higher price sensitivity.
EPA regulations under the Clean Air Act constrain volatile organic compound content in aerosolized solvents, pushing manufacturers toward low-VOC and water-based alternatives. REACH compliance in Europe restricts specific corrosion inhibitors, reshaping formulation portfolios for exporters. The EU Green Deal's chemical sustainability targets will compound these pressures. Stakeholders must monitor evolving state-level restrictions in California and New York, where air quality boards impose stricter thresholds than federal baselines, and decide whether to maintain separate regional SKUs or unify formulations at the most restrictive standard.
Market Dynamics
EPA volatile organic compound enforcement is compressing formulation choices for solvent-based gun cleaners, forcing manufacturers to rebuild product architectures around water-based chemistry or absorb compliance-driven cost increases.
Growth Catalysts
- NATO Small Arms Modernization:Multi-year defense procurement programs across member states mandate standardized maintenance protocols, creating recurring demand for certified gun care kits and lubricants.
- REACH Chemical Restrictions:European corrosion inhibitor bans are accelerating R&D investment in plant-based alternatives, opening formulation patent opportunities for early movers.
- Civilian Firearm Ownership Concentration:United States hobbyist segments drive integrated cleaning kit purchases as first-time buyers seek complete maintenance solutions rather than standalone solvents.
Market Restraints
- Petrochemical Input Volatility:Synthetic lubricant base oils and aerosol propellants face price instability tied to crude oil fluctuations, squeezing margin predictability for mid-tier producers.
- Supply Concentration in Specialty Additives:Three chemical suppliers dominate military-grade corrosion inhibitor production, creating single-source vulnerability for defense-contracted formulators.
- Technical Limitation in Water-Based Penetration:Low-VOC aqueous solvents exhibit slower carbon fouling dissolution rates compared to legacy chlorinated formulations, requiring extended soak times that tactical users resist.
Strategic Opportunities
- Underpenetrated Law Enforcement Segments:Municipal police departments in secondary United States markets still issue minimal maintenance equipment, representing white space for bundled training-plus-product contracts.
- EU Green Deal Chemical Sustainability Targets:Anticipated 2030 biodegradability mandates will advantage formulators with existing bio-based portfolios, potentially locking out late-adapting competitors.
- E-Commerce Channel Expansion:Direct-to-consumer subscription models for consumable lubricants bypass traditional sporting goods retail markups while capturing recurring revenue streams.
Industry Challenges
- ISO 9001 Certification Timeline Compression:Defense contractor qualification windows now demand documented quality management systems within 90-day bid cycles, straining smaller formulators' administrative capacity.
- Formulation IP Fragmentation:Proprietary additive packages face patent thickets around bio-based corrosion inhibitors, complicating freedom-to-operate analyses for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gun Care Products Market |
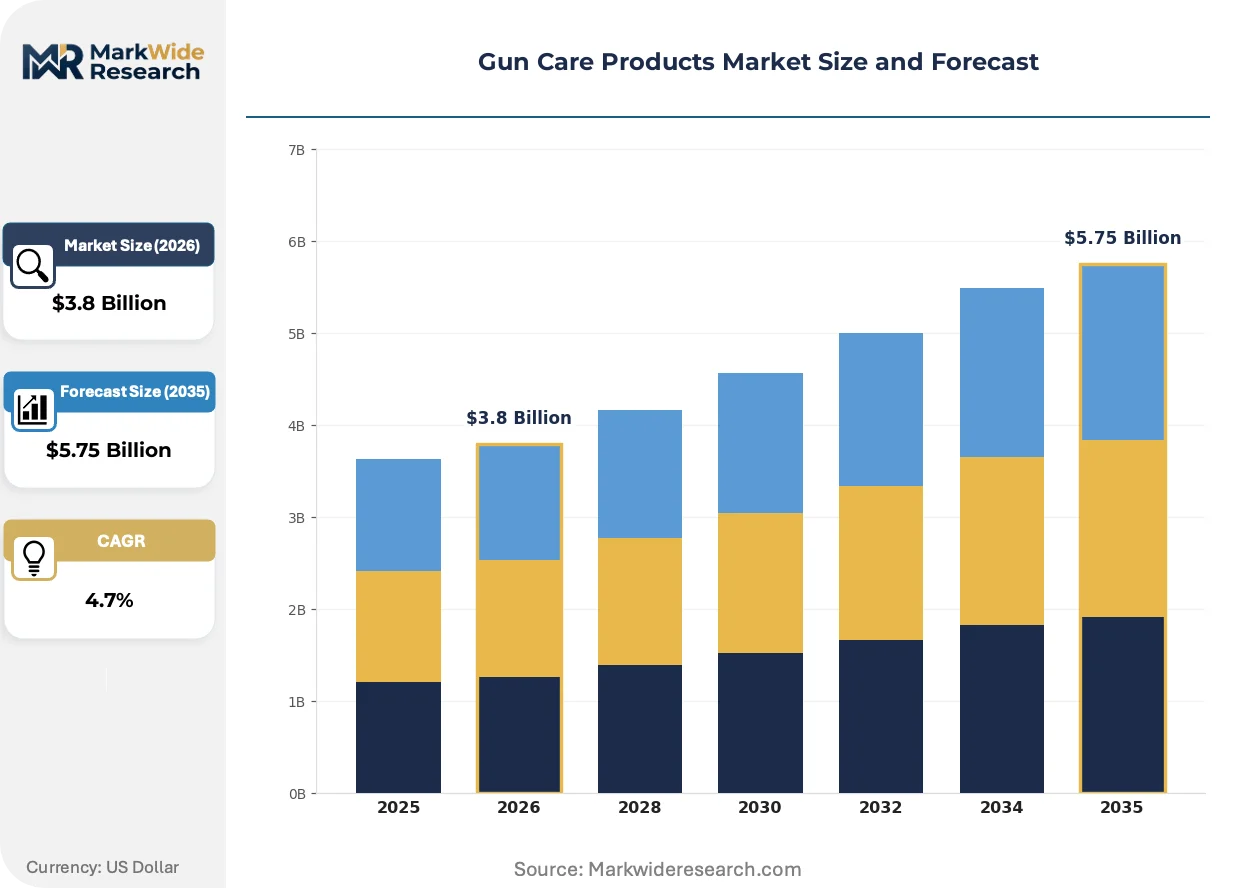
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cleaning Kits, Lubricants, Solvents, Protectants Application: Firearms, Airsoft, Archery, Military End User: Law Enforcement, Hobbyists, Military Personnel, Collectors Packaging Type: Bottles, Cans, Tubes, Pouches |
| Companies Covered | Lucas Oil Products, Inc., ROCOL, L&R Manufacturing, Amsoil Inc, G96 Products Inc., Ballistol, Hoppe's, Pro-Shot Products Inc., Bore Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gun Care Products Market Evolving Landscape
Formulation chemistry and distribution architecture are undergoing parallel transformation as environmental compliance tightens and buyer procurement preferences fragment across channel types.
Plant-based solvent chemistry is supplanting petroleum-derived chlorinated formulations in European commercial markets. German and Austrian hunting associations now specify biodegradable cleaners in equipment tenders. This shift is compressing shelf space for legacy solvent brands in continental European retail.
REACH authorization requirements for specific corrosion inhibitors are forcing reformulation of military-grade lubricants exported from the United States. Defense contractors serving NATO supply chains must maintain dual stock-keeping units to satisfy divergent regulatory baselines. Smaller exporters are exiting European markets rather than absorbing compliance costs.
Subscription-based consumable replenishment is displacing episodic retail purchases among United States civilian enthusiasts. Online direct channels now capture lubricant reorder cycles previously routed through brick-and-mortar sporting goods. This pattern concentrates most visibly in competitive shooting communities with predictable maintenance schedules.
Gun Care Products Market Segmentation
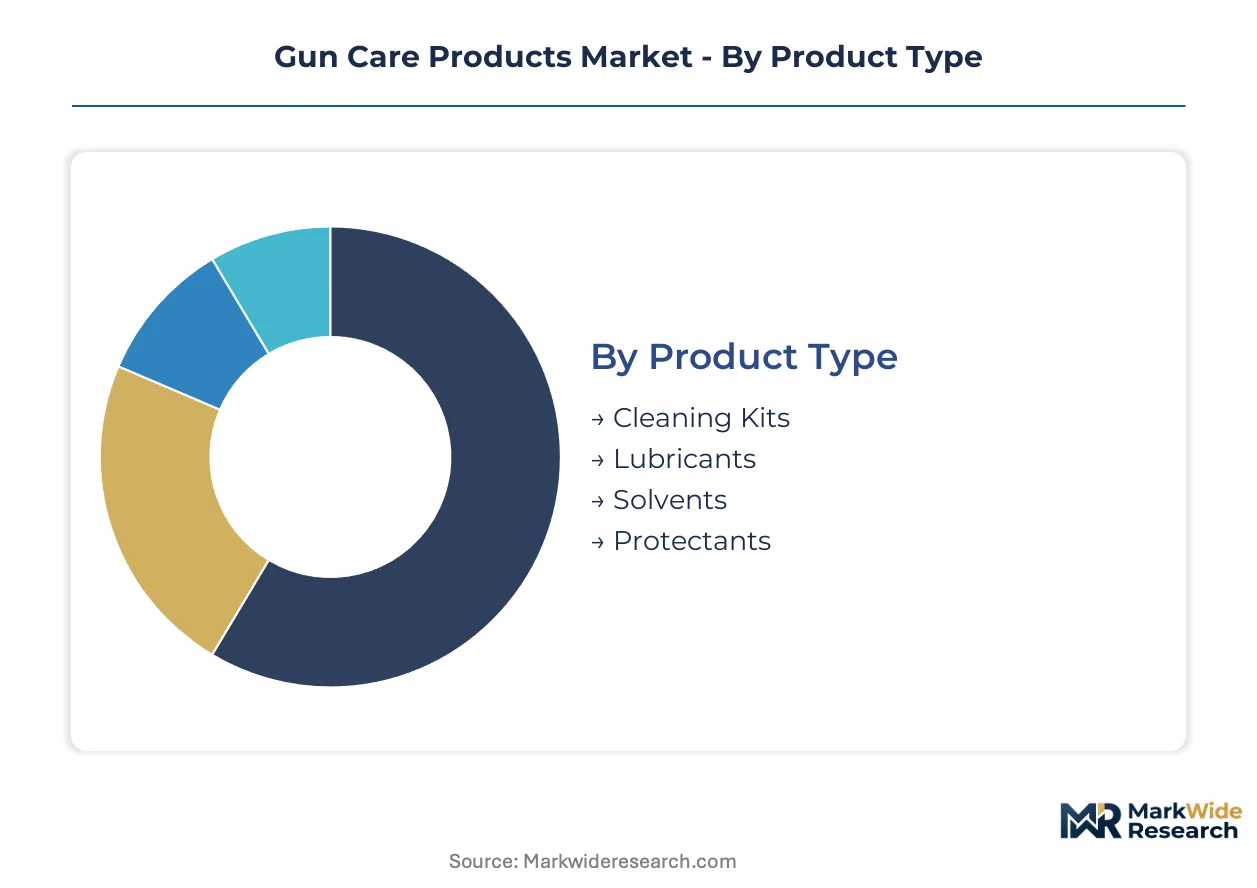
Segmentation in gun care products determines procurement pathways and margin capture, with military contracts favoring certified lubricant systems while civilian channels fragment across integrated cleaning kits. Understanding where value concentrates within each dimension exposes white space for formulation specialization and channel strategy.
Product Type:
Lubricants command the deepest margin pools due to recurring application cycles and military specification premiums, while cleaning kits compete on volume velocity through retail integration.
- Lubricants:Synthetic and bio-based formulations engineered for temperature stability between -40°F and 400°F. United States defense maintenance contracts specify MIL-PRF-63460E compliance, creating price-insulate demand for certified suppliers.
- Cleaning Kits:Integrated mechanical tools and consumable bundles designed for field-stripping protocols. First-time firearm purchasers in United States sporting goods channels drive kit adoption over standalone solvents, accelerating volume expansion.
- Solvents:Carbon-dissolving formulations with flash points above 140°F and chloride-free composition to prevent barrel pitting.
- Protectants:Moisture-displacing films and corrosion inhibitors for long-term storage applications.
The dominant share belongs to Lubricants, while Cleaning Kits are closing the gap fastest.
Application:
Volume concentration tracks weapon system complexity, with firearms maintenance generating the most frequent consumable replenishment cycles.
- Firearms:Centerfire and rimfire weapon systems requiring carbon, copper, and lead residue removal after each firing session. Civilian ownership in United States markets sustains the largest absolute demand base for recurring solvent and lubricant purchases.
- Military:NATO small arms modernization programs mandate standardized maintenance protocols across member state arsenals. Multi-year supply agreements lock in formulators with ISO 9001 certification and documented quality management systems.
- Airsoft:Replica weapon maintenance with lower thermal stress profiles and reduced fouling accumulation.
- Archery:Bowstring waxes, rail lubricants, and carbon arrow cleaning solutions for compound and crossbow systems.
Military procurement delivers the most stable revenue streams, though Firearms applications are expanding most quickly through civilian channel penetration.
End User:
Price sensitivity and purchase frequency diverge sharply between institutional buyers with technical specifications and individual enthusiasts with brand preferences.
- Hobbyists:Competitive shooters and recreational firearm owners purchasing through retail and direct channels. Subscription-based lubricant replenishment models now capture recurring orders previously routed through brick-and-mortar sporting goods.
- Military Personnel:Institutional end users procuring through defense supply chains with mandatory certification requirements. REACH compliance for European deployment forces drives dual-SKU strategies for exporters.
- Law Enforcement:Municipal police departments with underpenetrated maintenance equipment budgets in secondary United States markets.
- Collectors:Curators prioritizing long-term storage protectants and museum-grade corrosion prevention over high-frequency cleaning.
Hobbyists generate the highest transaction velocity, while Military Personnel anchor the most defensible margin position.
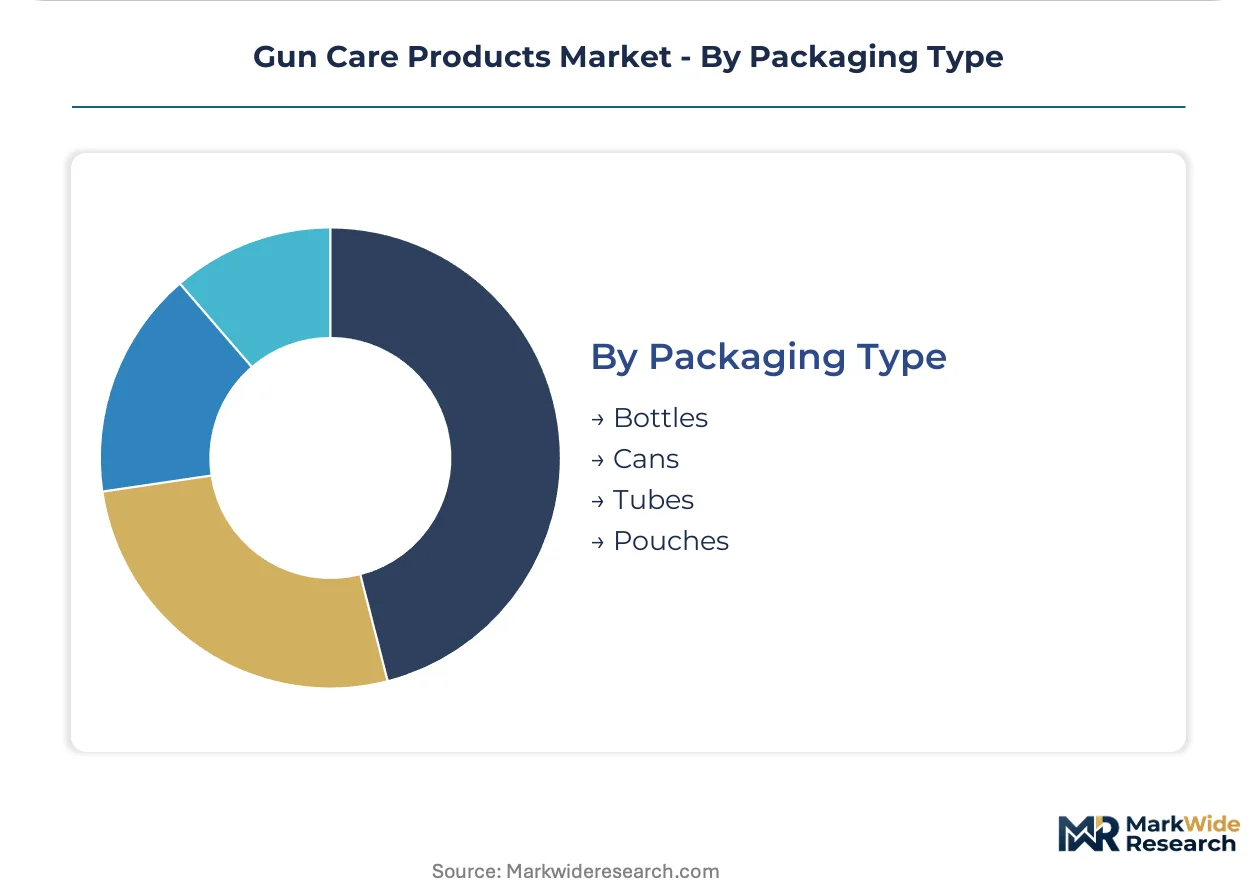
Packaging Type:
Distribution economics and application convenience determine format selection, with aerosol systems facing EPA volatile organic compound constraints.
- Cans:Aerosolized delivery systems for solvent penetration into barrel bores and action mechanisms. EPA Clean Air Act enforcement is compressing high-VOC formulations and accelerating water-based alternative development.
- Bottles:Precision-applicator containers for controlled lubricant dispensing onto slide rails and pivot points. E-commerce direct channels favor bottle formats for reduced shipping weight and hazmat classification.
- Tubes:Grease and heavy-viscosity lubricant packaging for bolt lug and bearing surface applications.
- Pouches:Single-use solvent wipes and pre-saturated cleaning patches for field deployment kits.
Bottles hold the installed base advantage, though Cans face steepest regulatory headwinds requiring formulation reinvestment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for gun care formulations, while the Union Pacific rail corridor links Midwest chemical plants to United States civilian markets. These infrastructure assets concentrate formulation manufacturing and finished goods distribution across distinct regulatory environments.
United States
Civilian firearm ownership and defense sector maintenance contracts drive concentrated demand. The EPA enforces Clean Air Act volatile organic compound limits on aerosolized solvents, compressing high-VOC formulation availability. Manufacturing clusters in the Midwest chemical corridor supply both military specification lubricants and retail cleaning kits.
Germany
German and Austrian hunting associations specify biodegradable cleaners in equipment tenders, accelerating plant-based solvent adoption. REACH authorization requirements restrict specific corrosion inhibitors, forcing reformulation of military-grade lubricants for NATO supply chains. The Bavarian industrial belt hosts specialty chemical producers developing bio-based alternatives.
United Kingdom
Law enforcement procurement through the National Police Chiefs Council creates institutional demand for certified maintenance kits. The Health and Safety Executive enforces workplace chemical exposure limits affecting solvent handling protocols. Manufacturing activity concentrates in the Midlands region, serving both domestic and export defense contracts.
Canada
Health Canada and the Pest Management Regulatory Agency regulate chemical formulations entering civilian and institutional channels. The Prairie Provinces sustain hunting and sport shooting cultures that drive recurring consumable purchases. Toronto and Vancouver serve as distribution hubs for cross-border supply into United States retail networks.
France
The French National Agency for Food, Environmental and Occupational Health Safety (ANSES) monitors chemical safety in consumer products, including firearm maintenance formulations. The Auvergne-Rhône-Alpes region hosts precision chemical manufacturing serving European defense and civilian markets. Lyon-based distributors coordinate supply into Mediterranean and North African export corridors.
Gun Care Products Market Competitive Landscape
Listed leaders compete with private specialists across formulation certification and channel access. The vendor base fragments across automotive lubricant crossovers, century-old sporting goods brands, and plant-based chemistry specialists. Three strategic archetypes dominate: diversified chemical conglomerates leveraging R&D infrastructure, heritage brands sustaining retail penetration, and bio-based formulators capturing regulatory tailwinds. Competitive moves concentrate on dual-SKU strategies for divergent regulatory baselines and subscription-based direct channel expansion.
Within the heritage brand tier, Hoppe's occupies a position sustained by century-plus retail channel relationships in United States sporting goods. Lucas Oil Products, Inc. exemplifies the automotive crossover archetype, applying lubricant formulation expertise to firearm-specific applications. Ballistol anchors the bio-based specialist position, with plant-based chemistry navigating tightening environmental compliance in European markets. These three companies represent distinct strategic responses to regulatory fragmentation and channel evolution.
| Leading Market Players |
|---|
| Lucas Oil Products, Inc. |
| ROCOL |
| L&R Manufacturing |
| Amsoil Inc |
| G96 Products Inc. |
| Ballistol |
| Hoppe's |
| Pro-Shot Products Inc. |
| Bore Tech |
| Others |
Value Network & Pricing Analysis
Ninety-day defense contractor qualification windows compress inventory cycles for specialty corrosion inhibitors, tethering pricing power to ISO 9001 certification status and locking out formulators without documented quality systems. This lead-time compression concentrates margin capture among pre-qualified suppliers while forcing uncertified competitors toward civilian retail channels with thinner spreads.
Pricing Analysis
Volume-discount tiering separates MIL-PRF-63460E certified lubricants for NATO defense contracts from standard retail formulations and economy private-label alternatives. Certification grade and volume scale drive price differentiation, with military specification premiums insulating certified suppliers from cost compression in water-based solvent development. Pricing pressure stems from EPA VOC compliance investments, which squeeze mid-tier producers lacking R&D scale. Hobbyist segments exhibit highest price sensitivity, while defense procurement demonstrates lowest sensitivity due to operational reliability requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate civilian retail channels, whereas NATO supply chains maintain strategic stockpiles of certified lubricants to ensure operational continuity. Manufacturing concentrates in the United States Midwest chemical corridor, Germany's Bavarian industrial belt, and the United Kingdom Midlands region. Synthetic base oils, aerosol propellants, and military-grade corrosion inhibitors constitute critical input dependencies. Single-source vulnerability in specialty additive supply creates structural risk for defense-contracted formulators. Distribution runs through sporting goods retail, direct-to-consumer e-commerce, and defense supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among NATO defense procurement offices and large-format sporting goods retailers, fragmenting pricing leverage for mid-tier formulators without certification or channel scale.
For Market Incumbents: Shield market position by deepening ISO 9001 certification moats and securing multi-year NATO supply agreements before qualification windows compress further. Prioritize backward integration into specialty corrosion inhibitor production to reduce single-source vulnerability. Channel control through exclusive retail partnerships defends against private-label erosion. For New Entrants and Emerging Players: Differentiate on plant-based chemistry platforms that satisfy REACH biodegradability mandates ahead of EU Green Deal deadlines. Municipal police departments in secondary United States markets represent the most penetrable segment, with bundled training-plus-product contracts offering lower competitive density. Direct-to-consumer subscription models bypass traditional retail markups while capturing recurring lubricant replenishment cycles. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergence between EPA and REACH compliance baselines rewards formulators with dual-SKU capabilities. Acquisition targets should display existing bio-based portfolios and established European distribution infrastructure. Watch for EU Green Deal chemical sustainability target acceleration as the primary inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-SKU Formulation Development | Enables simultaneous EPA and REACH compliance without market exit. |
| ISO 9001 Certification Investment | Unlocks NATO defense procurement qualification and multi-year supply agreements. |
| Plant-Based Chemistry R&D Expansion | Positions formulators ahead of EU Green Deal biodegradability mandates. |
| Direct-to-Consumer Subscription Launch | Captures recurring lubricant revenue previously routed through sporting goods retail. |
| Backward Integration into Additives | Reduces single-source vulnerability in military-grade corrosion inhibitor supply. |
Research Methodology
A spread of perspectives from defense procurement officers, chemical formulators, sporting goods category managers, and EPA compliance consultants converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from EPA Clean Air Act filings, REACH authorization databases, NATO maintenance protocol documents, and customs trade records. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Segmentation dimensions modeled include product type, application, end user, packaging format, and regional regulatory cluster across the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking procurement schedule alignment. Forecast inputs incorporated NATO small arms modernization timelines and EPA enforcement intensity projections.
Material uncertainties — petrochemical input volatility, REACH authorization scope expansion, and state-level VOC threshold adjustments — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and defense budget allocation patterns. Revision becomes warranted when EU Green Deal chemical sustainability targets accelerate beyond baseline expectations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Pool Speakers Market
Consumer Electronics
Professional Headset Market
Consumer Electronics
Waterproof Speaker Market
Consumer Electronics
Europe Gaming Headset Market
Consumer Electronics
IoT in Consumer Electronics Market
Consumer Electronics
Pillow Holder for Tablets Market
Consumer Electronics
Learning Remote Controls Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
Gaming Mouse Market
Consumer Electronics
China Massage Equipment Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Japan Gaming Peripherals Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Closed Back Studio Headphone Market