
 Global Heat Stabilizers Market | 2026-2036
Global Heat Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Heat Stabilizers Market Foresight
Aftermarket technical service revenue is fragmenting as equipment lifespans extend and processors seek formulation optimization support. Clariant AG leverages its global technical service network to capture recurring advisory contracts. Baerlocher GmbH anchors its position through backward integration into key raw material streams. Songwon Industrial Company specializes in high-performance organic stabilizer blends for demanding wire and cable applications.
Heat stabilizers are chemical additives, typically metal soaps or organometallic compounds, that inhibit thermal degradation of halogenated polymers by scavenging liberated hydrogen chloride at processing temperatures above 180°C. Their primary purpose is to preserve mechanical properties and color stability during extrusion, injection molding, and calendering of PVC and related resins. Calcium zinc stabilizers now lead product type demand as processors abandon lead-based systems under regulatory pressure, while organic stabilizers represent the fastest-expanding category for medical and food-contact films where heavy metal exclusion is mandatory. Wire and cable applications command premium pricing due to stringent thermal aging requirements, whereas profiles and floorings operate as mature volume segments with thinner margins.
REACH restrictions on lead compounds, RoHS directives governing electrical equipment, and EPA toxicity evaluations under the Toxic Substances Control Act are restructuring permissible chemistries and reformulation timelines across manufacturing regions. The EU Green Deal's circular economy mandates are additionally pressuring stabilizer suppliers to demonstrate recyclability compatibility and reduced carbon intensity in production. Stakeholders must monitor regulatory divergence between jurisdictions and pre-position alternative metal-free platforms before compliance deadlines eliminate incumbent product lines.
Market Dynamics
Regulatory phase-out of lead-based chemistries across multiple jurisdictions is forcing immediate reformulation investments, while construction-driven PVC demand in emerging economies creates parallel pressure for volume scalability.
Growth Catalysts
- REACH lead compound restrictions:European processors face mandatory conversion timelines, accelerating calcium zinc and organic stabilizer substitution across extrusion and calendering operations.
- India infrastructure investment:National highway, water distribution, and urban housing projects are expanding PVC pipe consumption, pulling stabilizer demand toward South Asian manufacturing clusters.
- Calcium zinc technology maturation:Improved thermal stability profiles now match legacy lead performance in rigid profiles, enabling regulatory-compliant volume production without process re-engineering.
Market Restraints
- Epoxidized soybean oil price volatility:Co-stabilizer input costs fluctuate with agricultural commodity markets, compressing blend margins for calcium zinc formulators.
- Chinese rare earth processing concentration:Cerium-based heat stabilizer precursors depend on concentrated upstream supply, exposing European and North American compounders to export quota risks.
- Organic stabilizer thermal ceiling:Current organometallic formulations degrade above 200°C, excluding them from high-speed wire and cable jacketing lines.
Strategic Opportunities
- Brazilian automotive wire harness expansion:Local OEM supplier parks are reshoring cable production, creating demand for high-performance stabilizer technical partnerships.
- EU Green Deal circular economy mandates:Recyclability certification requirements favor stabilizer platforms compatible with multi-generation PVC reprocessing.
- Digital formulation services:Remote rheology optimization and thermal aging prediction tools enable stabilizer suppliers to capture recurring advisory revenue without field deployment.
Industry Challenges
- Regulatory compliance timeline compression:California DTSC and EPA TSCA parallel evaluations create overlapping reformulation deadlines with incompatible testing protocols.
- Legacy equipment retrofit costs:Processors running 1990s-era extrusion lines face capital barriers to stabilizer transitions requiring modified temperature profiles or screw geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Heat Stabilizers Market |
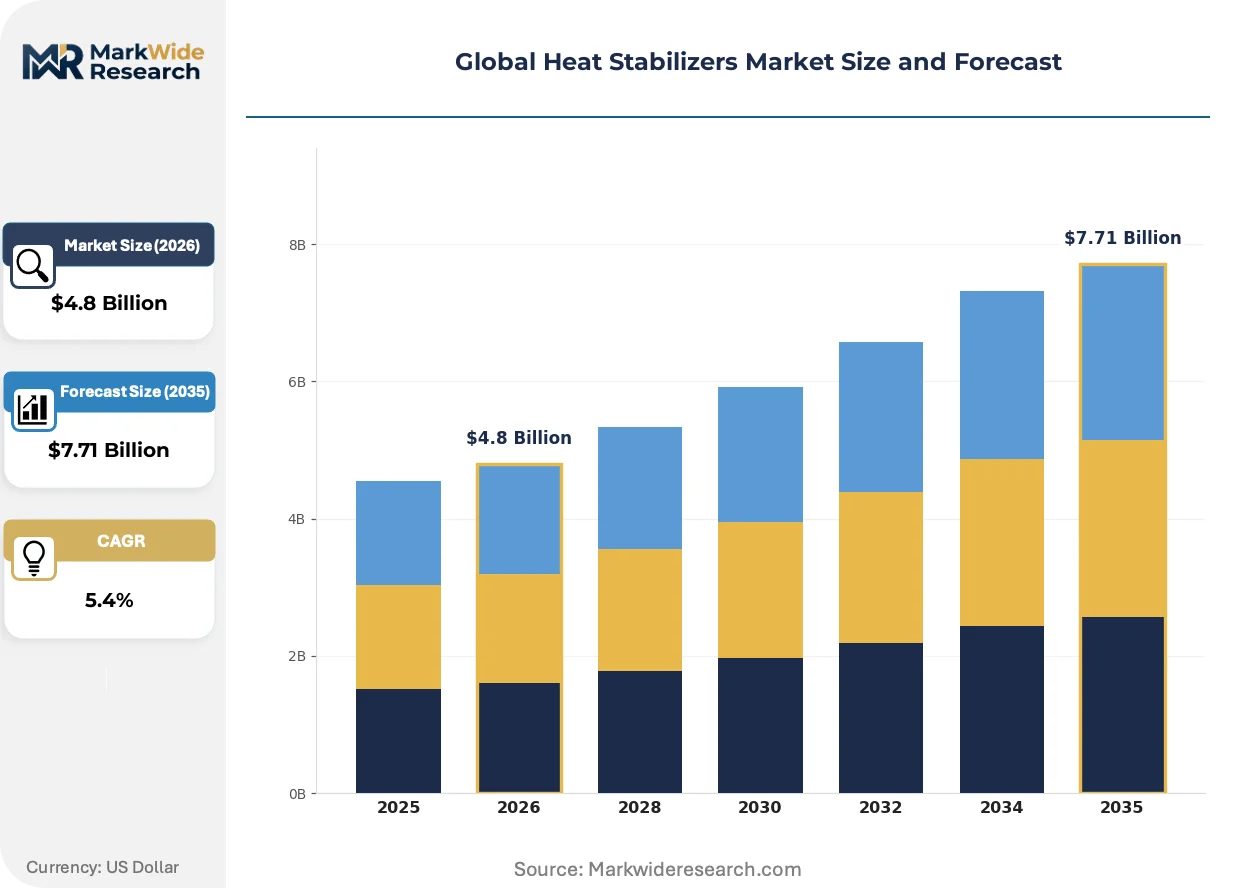
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Stabilizers, Calcium Zinc Stabilizers, Organic Stabilizers, Mixed Metal Stabilizers, Tin Stabilizers Application: Wire & Cable, PVC Pipes & Fittings, Profiles, Films & Sheets, Floorings End User Industry: Construction, Electrical & Electronics, Agriculture, Packaging Form: Powder, Granules, Pellets, Liquid |
| Companies Covered | Clariant AG, Galata Chemicals, BASF SE, PMC Group, Valtris Specialty Chemicals Limited, Baerlocher GmbH, Songwon Industrial Company, Kisuma Chemicals, ADEKA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Heat Stabilizers Market Shifts & Advancements
Formulation science is converging with digital process control and sustainability verification, compressing product development cycles while raising performance thresholds for regulatory acceptance.
Hybrid calcium-organic stabilizer systems are hybridizing conventional metal soap performance with heavy-metal-free compliance. Medical device manufacturers and food-contact film processors in Germany and Switzerland are adopting these blends to satisfy BfR and EFSA migration limits. The technology is hybridizing what were previously separate premium and commodity supply chains into unified platforms.
EPA toxicity evaluations under the Toxic Substances Control Act are expanding scrutiny to organotin and barium-zinc alternatives previously exempt from lead-phase-out pressures. Industrial consequence includes preemptive abandonment of chemistries before formal listing, with compounders in Texas and Ohio accelerating organic platform validation. Wire and cable producers serving defense and aerospace contracts are most affected, shifting procurement toward ISO-certified suppliers with established TSCA compliance documentation.
Technical service unbundling from product supply is restructuring buyer-supplier relationships in North American and European markets. Large PVC processors are separating stabilizer procurement from formulation optimization contracts, awarding advisory engagements to specialized technical consultancies or regional distributors with in-house rheology laboratories. This pattern is most visible in Benelux and northern Italy, where custom compounders operate lean purchasing functions and outsource complex regulatory navigation.
Global Heat Stabilizers Market Segmentation
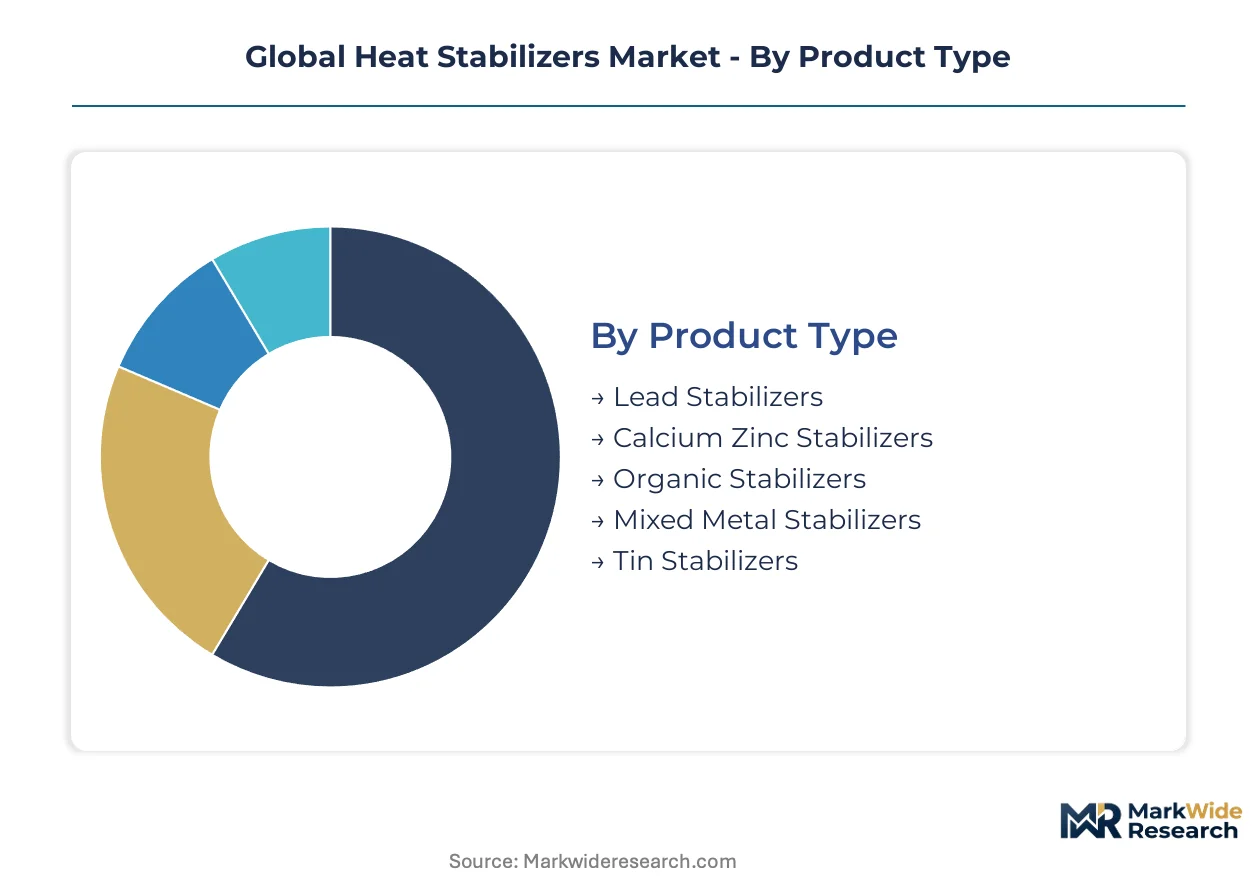
Heat stabilizer procurement patterns diverge sharply across product chemistries and end-use specifications. Formulators must align supply chain investments with the diverging cycle times of construction-driven bulk applications versus precision-engineered electrical components.
Product Type:
Cycle times vary from commodity metal soaps with quarterly contract resets to organic platforms requiring eighteen-month validation protocols.
- Calcium Zinc Stabilizers:These heavy-metal-free metal soap blends deliver thermal stability for rigid PVC extrusion without REACH lead restrictions. Demand concentrates in Germany and India where construction regulators enforce strict migration limits on potable water piping.
- Organic Stabilizers:Organometallic and phenolic antioxidant systems eliminate metal content entirely for medical films and food-contact applications. Swiss and German medical device manufacturers drive specification premiums due to BfR and EFSA compliance requirements.
- Lead Stabilizers:Legacy formulations persist in price-sensitive emerging markets lacking enforcement infrastructure.
- Mixed Metal Stabilizers:Barium-zinc and calcium-barium hybrids serve transitional reformulation needs.
- Tin Stabilizers:Organotin mercaptides dominate transparent packaging and bottle applications.
Calcium zinc stabilizers anchor the volume base while organic stabilizers gain share at the steepest rate.
Application:
Cost tiers separate specification-heavy electrical grades from construction commodities with thinner margin structures.
- Wire & Cable:High-performance stabilizer systems must survive accelerated thermal aging under IEC 60811 test protocols. Defense and aerospace cable producers in the United States impose ISO-certified documentation requirements that exclude uncertified compounders.
- PVC Pipes & Fittings:Pressure-rated piping for water distribution commands formulation precision to prevent HCl liberation during fusion welding. India's national highway and urban housing programs concentrate demand in Gujarat and Maharashtra manufacturing clusters.
- Profiles:Window and door extrusions operate as mature volume segments with established calcium zinc conversion.
- Films & Sheets:Calendered products for medical and food packaging require heavy metal exclusion.
- Floorings:Resilient vinyl tile production favors cost-optimized stabilizer blends.
PVC pipes and fittings generate the highest absolute tonnage while wire and cable commands the steepest price premiums per kilogram.
End User Industry:
Customer procurement maturity determines whether stabilizer supply includes bundled technical services or bare product delivery.
- Construction:Project-driven demand fluctuates with infrastructure investment cycles and housing starts. Brazilian federal housing programs and Indian smart city initiatives create concentrated procurement windows for pipe-grade stabilizers.
- Electrical & Electronics:OEM qualification protocols extend eighteen to thirty-six months but lock in multi-year supply agreements. RoHS and REACH compliance documentation is mandatory for European automotive wire harness reshoring programs.
- Agriculture:Irrigation piping for drought mitigation schemes in Spain and Australia operates on seasonal procurement patterns.
- Packaging:Food-contact film processors prioritize migration-tested organic stabilizer platforms.
Construction absorbs the highest stabilizer volumes while electrical and electronics delivers the most predictable recurring revenue streams.
Form:
Supply chain configuration favors powder and granule formats for high-volume extrusion while liquid systems serve specialized calendering operations.
- Powder:Free-flowing metal soap blends dominate rigid profile and pipe extrusion with lowest unit dosing cost.
- Granules:Dust-reduced formats improve handling safety in high-throughput compounding operations.
- Pellets:Pre-dispersed concentrates enable precise metering for medical film and wire jacketing lines.
- Liquid:Pumpable organotin and organic systems integrate directly into plastisol mixing for flooring and coating applications.
Powder and granule formats command the volume base while pelletized concentrates expand most quickly in precision extrusion segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for heat stabilizers diverges sharply across geographies. Indian infrastructure buyers prioritize volume scalability over formulation sophistication. German medical device manufacturers absorb substantial premiums for heavy-metal-free certification.
United States
Wire and cable producers serving defense contracts drive specification-grade stabilizer procurement. EPA TSCA evaluations under Section 5 pre-manufacture notification rules are accelerating organic platform validation. Compounding clusters in Ohio and Texas are preemptively abandoning organotin chemistries before formal regulatory listings.
Germany
Construction regulators enforce strict BfR migration limits on potable water piping systems. REACH lead compound restrictions mandate calcium zinc conversion timelines across extrusion operations. Industrial concentration in North Rhine-Westphalia anchors European formulation R&D and technical service capabilities.
India
National highway and urban housing programs are expanding PVC pipe consumption at double-digit rates. Bureau of Indian Standards certification requirements for pressure-rated piping create formulation precision barriers. Manufacturing clusters in Gujarat and Maharashtra are pulling stabilizer supply toward South Asian production bases.
Brazil
Federal housing programs and automotive wire harness reshoring create concentrated procurement windows. ANVISA regulations governing food-contact materials are migrating processors toward organic stabilizer platforms. OEM supplier parks in São Paulo state are qualifying high-performance stabilizer technical partnerships for local cable production.
China
Rare earth processing concentration for cerium-based stabilizer precursors exposes downstream compounders to export quota volatility. MIIT industrial standards for PVC construction materials are tightening heavy metal content thresholds. Yangtze River Delta chemical manufacturing bases are consolidating calcium zinc production capacity for domestic and export markets.
Global Heat Stabilizers Market Competitive Landscape
Capability concentration sits with formulation specialists possessing ISO-certified regulatory documentation; scale advantage sits with diversified chemical conglomerates with captive raw material streams. The vendor base stratifies across three tiers: global technical service networks, regionally anchored compounders, and commodity metal soap blenders. Strategic moves center on backward integration into epoxidized soybean oil and rare earth precursor supply, plus unbundling of advisory services from product supply contracts.
Within the technical service tier, Clariant AG exemplifies the advisory-contract model through its global rheology optimization network. Baerlocher GmbH anchors the backward-integrated archetype with captive control over key raw material streams. Songwon Industrial Company occupies the high-performance specialization position for demanding wire and cable thermal aging requirements.
| Leading Market Players |
|---|
| Clariant AG |
| Galata Chemicals |
| BASF SE |
| PMC Group |
| Valtris Specialty Chemicals Limited |
| Baerlocher GmbH |
| Songwon Industrial Company |
| Kisuma Chemicals |
| ADEKA Corporation |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor carries epoxidized soybean oil and rare earth precursors whose freight cost swings directly shape calcium zinc stabilizer pricing power in European compounding operations and downstream price differentiation between medical-grade organic blends and commodity pipe formulations.
Pricing Analysis
Aftermarket technical service contracts now drive lifetime value more than base product margins. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified wire and cable stabilizers from construction-grade calcium zinc blends and legacy lead systems in price-sensitive emerging markets. Cost compression in commodity metal soaps is intensifying because agricultural feedstock volatility feeds directly into co-stabilizer blend economics. Construction sector buyers in India exhibit highest price sensitivity while German medical device manufacturers absorb substantial premiums for BfR-compliant heavy-metal-free certification.
Supply Chain Analysis
Chinese export controls on rare earth processing technology limit cerium-based stabilizer precursor flows to European and North American compounders. Upstream concentration centers on China for rare earth oxides, India for calcium carbonate processing, and Germany for organometallic synthesis expertise. Raw material dependencies include epoxidized soybean oil from agricultural commodity markets, cerium and lanthanum oxides from concentrated mining operations, and zinc metal from smelter networks. Single-source vulnerability in Chinese rare earth refining exposes downstream formulators to quota-driven supply interruptions. Distribution runs through regional compounding hubs that blend masterbatches for localized PVC processor delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large PVC processors that unbundle stabilizer procurement from technical advisory contracts, a fragmentation pattern visible across Benelux and northern Italy where lean purchasing functions now dominate supplier selection.
For Market Incumbents: Entrench market position through captive backward integration into epoxidized soybean oil supply and accelerated certification investment for REACH-compliant organic platforms. The threat of EPA TSCA organotin listing demands preemptive reformulation capacity. Vertical integration into agricultural co-stabilizer streams defends margin compression from commodity price swings. For New Entrants and Emerging Players: Mid-tier wire and cable compounders in Brazil's automotive supplier parks represent the most penetrable entry point for high-performance stabilizer technical partnerships. White-space concentration also sits with Indian PVC pipe processors seeking calcium zinc conversion support without legacy technical service baggage. A digital formulation advisory model enables recurring revenue capture without field deployment infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ISO-certified specialists with established regulatory documentation libraries over undifferentiated metal soap blenders. Long-term viability hinges on multi-jurisdiction compliance capability as REACH, EPA TSCA, and state-level restrictions converge. The signal to watch is California DTSC evaluation timelines that may force accelerated lead-phase-out deadlines beyond current assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxidized Soybean Oil | Captive supply of critical co-stabilizer feedstock insulates Baerlocher GmbH from agricultural commodity volatility. |
| Digital Formulation Services Launch | Remote rheology optimization enables Clariant AG to capture recurring advisory revenue without technical field deployment. |
| Calcium Zinc Capacity Expansion in Gujarat | Localized production for India's national highway and urban housing programs reduces logistics costs to Maharashtra pipe clusters. |
| Organic Stabilizer Platform Certification | BfR and EFSA compliance documentation unlocks premium medical film specifications in German and Swiss device manufacturing. |
| Joint Venture with Rare Earth Processor | Upstream partnership mitigates Chinese export quota exposure for cerium-based heat stabilizer precursor supply. |
Research Methodology
Desk research of customs trade databases, ECHA REACH registration filings, and SEC chemical sector disclosures preceded structured interviews with PVC plant managers, procurement leads at wire and cable OEMs, distribution channel partners, and technical R&D directors at stabilizer formulators. Primary fieldwork combined telephone and video interviews with secondary validation against BIS certification records and Bureau of Indian Standards pressure-piping specifications. Bottom-up demand modeling from end-use consumption patterns triangulated against top-down supply-side capacity assessments across calcium zinc and organic stabilizer production bases.
Assumptions held fixed include regulatory enforcement timelines for lead-phase-out restrictions and baseline agricultural commodity price bands for epoxidized soybean oil feedstock, while variables included infrastructure investment cycles across emerging markets and substitution rates between metal soap and organic stabilizer chemistries. The analytical framework modeled segmentation across product chemistry tiers, application thermal requirements, end-user industry procurement maturity, and regional regulatory clusters. CAGRs derived from weighted average of historical volume trajectories and elasticity-adjusted demand projections. Industry-specific inputs included PVC resin consumption coefficients by application and thermal aging test protocol compliance thresholds for wire and cable specifications.
Practitioners should monitor EPA TSCA Section 5 pre-manufacture notification timelines and California DTSC priority product evaluations for early signals of accelerated regulatory compression. Forecasts reflect documented assumptions about REACH enforcement consistency and Indian Bureau of Indian Standards certification adoption rates. Material shifts in Chinese rare earth export policy or epoxidized soybean oil crop yields would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Lentein Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Filler Masterbatch Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
United States Caustic Potash Market
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Resin Capsule Market
Specialty Compounds
Methyl Anthranilate Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Fluoropolymer Masterbatch Market
Specialty Compounds
Global Quaternary Ammonium Compounds Market