
 Pet Toys Market | 2026-2036
Pet Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Toys Market Analysis
Chinese manufacturing clusters is restructuring output toward automated injection molding and textile finishing for pet accessories. KONG Company leverages proprietary natural rubber formulations to sustain premium positioning across North American veterinary channels. Spectrum Brands Holdings, Inc. anchors mass-market penetration through big-box retail partnerships. Fressnapf Tierfutter GmbH dominates European pet specialty distribution with vertically controlled private-label sourcing.
Pet toys comprise purpose-built objects designed for animal enrichment, exercise, and behavioral conditioning, typically fabricated from vulcanized rubber, woven synthetics, or food-grade polymers to withstand repetitive mechanical stress and oral contact. Their primary commercial function centers on reducing destructive behaviors in companion animals while extending product replacement cycles for owners. Plush toys carry the highest margin pools in premium gifting segments despite faster wear rates, while interactive toys represent the fastest-growing category as sensor-enabled and treat-dispensing designs penetrate educated urban households. Chew toys remain the volume backbone across mass retail, with natural fiber variants gaining share among sustainability-focused pet owners.
US FDA guidelines on animal product safety, EU REACH chemical restrictions, and China's GB standards for plastic goods collectively govern material composition, migration limits, and labeling requirements across major supply corridors. These frameworks elevate compliance costs for smaller exporters while creating certification barriers that favor scaled manufacturers with dedicated testing laboratories. Stakeholders must monitor evolving biodegradable material standards and channel-specific packaging mandates to preserve market access.
Market Dynamics
Automated injection molding clusters in China's Pearl River Delta are compressing production cycles for vulcanized rubber and woven synthetic toys, forcing legacy manufacturers to absorb capital expenditures or cede mass-market positioning to vertically integrated competitors.
Growth Catalysts
- EU REACH chemical restrictions:Migration limits on phthalates and heavy metals in oral-contact products are accelerating certified natural rubber adoption, opening premium positioning for compliant manufacturers.
- Millennial pet owner demographics:Educated urban households with disposable income are prioritizing sensor-enabled interactive designs that reduce destructive companion animal behaviors.
- Automated textile finishing:Guangdong and Zhejiang manufacturing hubs are deploying robotic cutting and bonding systems that cut plush toy unit costs while improving seam durability standards.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian latex supply fluctuations compress margins for premium chew toy producers dependent on proprietary vulcanized formulations.
- Supply concentration in Chinese molding clusters:Overreliance on Dongguan and Shenzhen injection facilities creates vulnerability to regional power rationing and labor availability shocks.
- Technical limitation in biodegradable polymers:Current PLA and PBAT blends lack the tensile strength and saliva resistance required for aggressive chewers, limiting material substitution in durability segments.
Strategic Opportunities
- German veterinary channel penetration:Underdeveloped specialty retail presence for prescription-grade enrichment toys offers first-mover positioning for clinically tested product lines.
- EU Green Deal packaging mandates:Compostable and recycled-content labeling requirements create certification-based differentiation for sustainability-focused private-label suppliers.
- Convergence of IoT sensors and treat-dispensing mechanisms:Smartphone-connected behavioral tracking is enabling subscription-based toy replacement models in educated urban markets.
Industry Challenges
- Specialized polymer chemist scarcity:Formulation expertise for food-grade, migration-safe elastomers concentrates among aging technical workforces in Ohio and Bavaria.
- Multi-jurisdiction certification timelines:Simultaneous US FDA, EU REACH, and China GB standard compliance testing extends product launch cycles by eight to fourteen months.
- Legacy ERP integration with automated quality systems:Mid-tier manufacturers face data architecture friction when connecting real-time defect detection to batch traceability protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Toys Market |
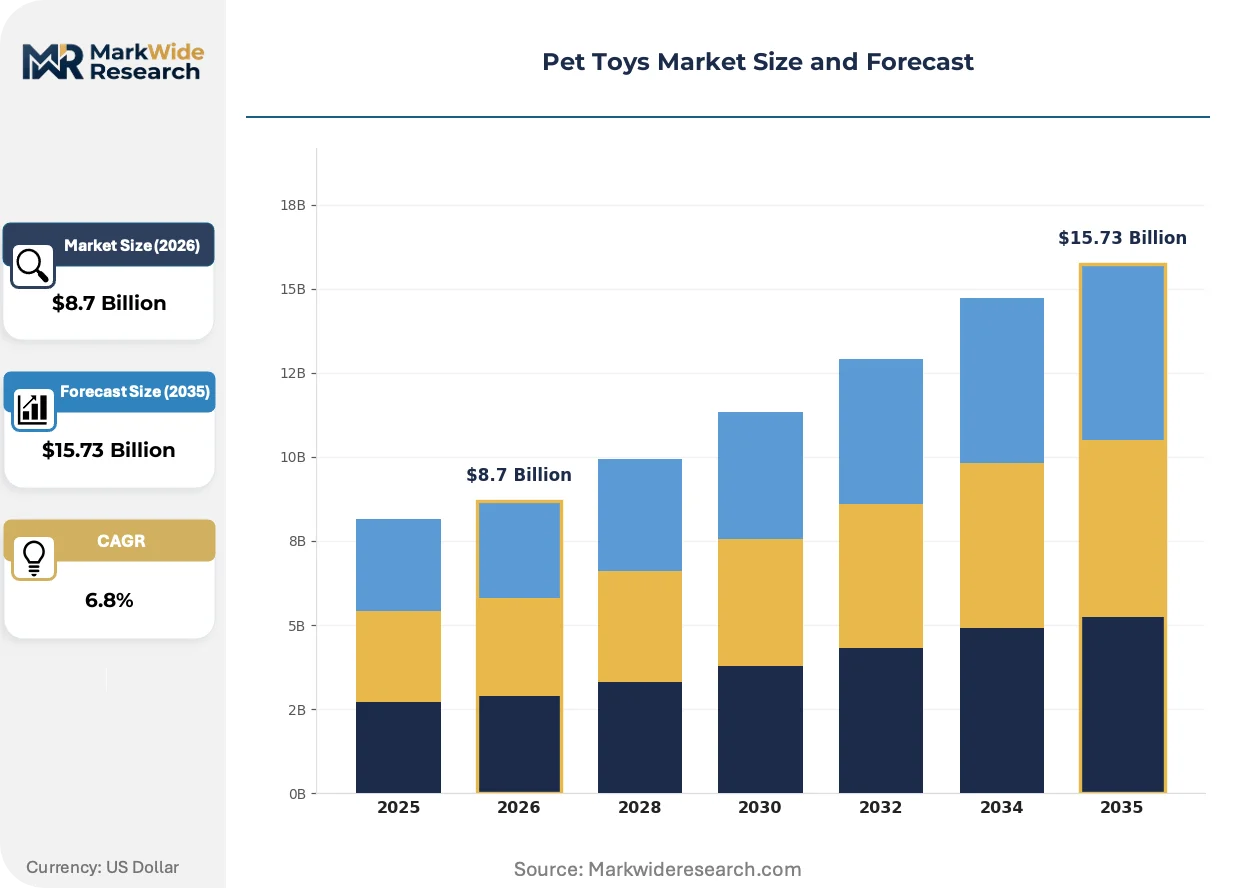
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plush Toys, Chew Toys, Interactive Toys, Balls Material: Rubber, Nylon, Natural Fiber, Plastic Customer Type: Pet Owners, Retailers, Veterinary Clinics, Animal Shelters Distribution Channel: Online Retail, Pet Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Fressnapf Tierfutter GmbH, Unicharm Corporation, Spectrum Brands Holdings, Inc., Petz Group, Outward Hound, KONG Company, Pets at Home Group Plc, Tractor Supply Company, Chewy, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Toys Market Emerging Trajectories
Sensor-enabled interactivity and sustainable material substitution are bifurcating competitive strategy between premium technology integration and mass-market eco-positioning, with regulatory compliance acting as the gating mechanism for cross-border market access.
Thermoplastic elastomer compounds with Shore A hardness tunability are expanding into veterinary-recommended dental chew segments. Specialist formulators in Akron and Leverkusen are supplying custom vulcanization recipes to brands targeting aggressive chewers. This material expansion is compressing natural rubber's historical dominance in durability applications while elevating unit economics for compounders with proprietary additive packages.
China's GB standards for plastic goods are tightening migration limits on colorants and plasticizers used in oral-contact pet accessories. SAMR enforcement actions in 2024 have accelerated third-party laboratory certification requirements for export-oriented manufacturers. Domestic brands serving the Shanghai and Beijing metropolitan markets are responding by pre-certifying entire product lines against both GB and EU REACH thresholds to streamline dual-market entry.
Subscription-based toy replacement programs are displacing traditional retail replenishment cycles among millennial pet owners in the United States and Germany. Direct-to-consumer platforms offering curated monthly boxes with wear-rated durability guarantees are capturing share from big-box pet specialty retailers. This channel shift concentrates most visibly in metropolitan markets with high pet insurance penetration and disposable income thresholds above national medians.
Pet Toys Market Segmentation
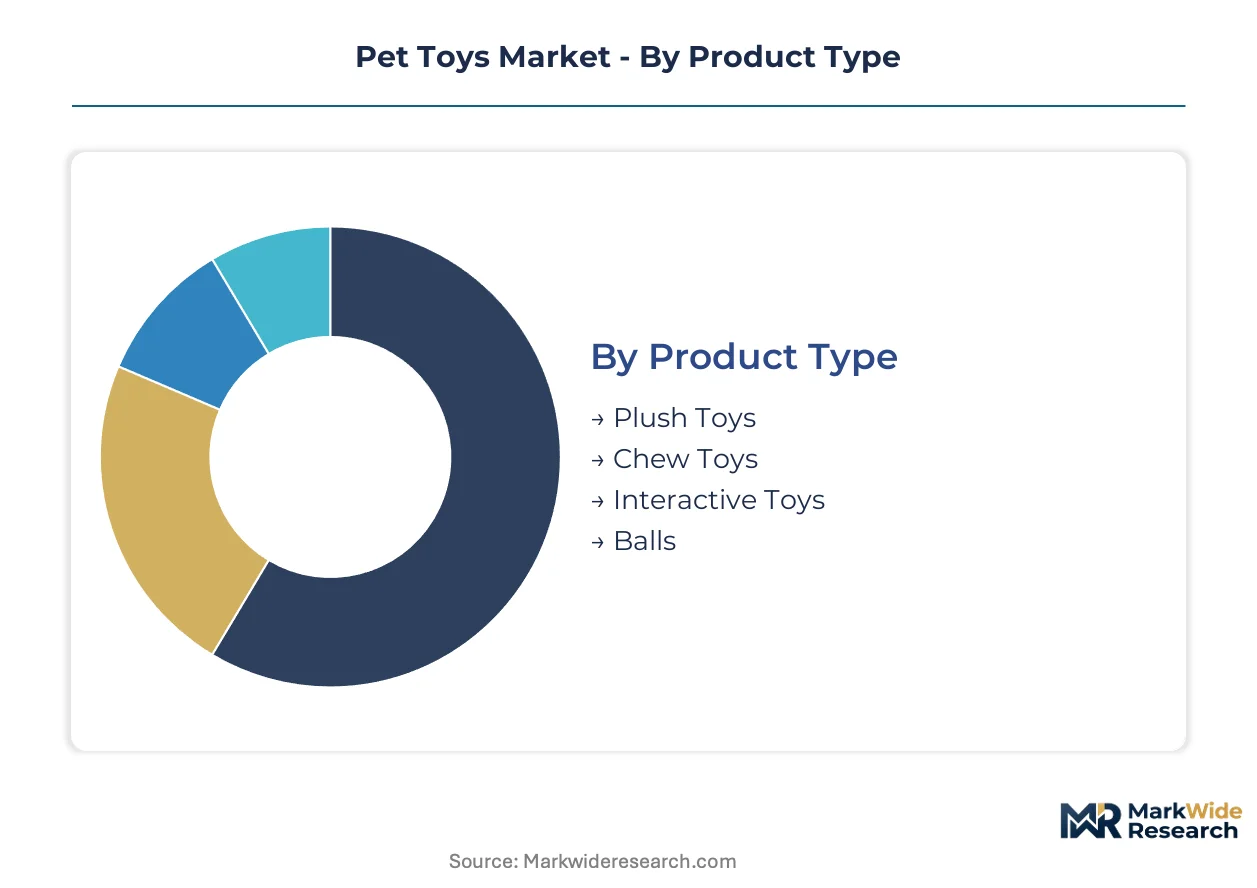
Segmentation in pet toys determines replacement frequency, margin capture, and channel access. Material durability and interactive functionality create divergent upgrade cycles that reshape procurement patterns across owner demographics.
Product Type:
Replacement cycles vary dramatically by durability design and enrichment purpose.
- Plush Toys:Soft-bodied constructions of woven synthetics or natural fibers prioritize comfort and owner gifting appeal over longevity. Demand clusters in premium urban households seeking behavioral comfort for anxious companion animals, with faster replenishment cycles driving recurring revenue.
- Interactive Toys:Sensor-enabled and treat-dispensing mechanisms integrate smartphone connectivity for remote behavioral monitoring. Educated millennial owners in metropolitan United States and Germany are adopting these designs most aggressively as substitutes for supervised exercise time.
- Chew Toys:Vulcanized rubber and thermoplastic elastomer formulations engineered for aggressive oral wear dominate mass retail volume.
- Balls:Standardized spherical designs in rubber or hard plastic serve fetch-based exercise routines across all owner income tiers.
Volume placements concentrate in Chew Toys; the faster expansion belongs to Interactive Toys.
Material:
Cost tiers align with regulatory certification burden and sourcing geography.
- Rubber:Natural latex and synthetic vulcanized compounds deliver Shore A hardness tunability for durability segments. Thai and Indonesian supply fluctuations compress margins for premium producers, while REACH-compliant natural rubber commands veterinary channel premiums in Germany.
- Natural Fiber:Cotton, hemp, and jute weaves target sustainability-focused owners seeking compostable end-of-life pathways. EU Green Deal packaging mandates accelerate certified fiber adoption among private-label suppliers serving metropolitan European markets.
- Nylon:High-tensile synthetic polymers dominate aggressive chewer segments with injection-molded dental ridges.
- Plastic:Food-grade polymers and thermoplastic elastomers serve cost-sensitive mass retail through automated Chinese molding clusters.
Procurement volume clusters in Rubber; Natural Fiber is climbing the fastest on sustainability premiums.
Customer Type:
Application context dictates performance specifications and purchasing authority.
- Pet Owners:Individual consumers making discretionary enrichment purchases based on companion animal behavior and household disposable income. Sensor-enabled interactive designs and subscription replacement models are penetrating educated urban demographics with pet insurance coverage.
- Veterinary Clinics:Prescription-grade enrichment and dental health toys recommended as behavioral interventions. Underdeveloped specialty retail presence in Germany creates first-mover positioning for clinically tested product lines with documented efficacy.
- Retailers:Big-box and specialty merchants curating assortments by margin pool and turnover velocity.
- Animal Shelters:Volume purchasers prioritizing unit cost and durability for high-turnover companion animal populations.
Transaction volume concentrates with Pet Owners; Veterinary Clinics present the steepest expansion trajectory on clinical validation requirements.
Distribution Channel:
Channel selection determines margin retention and customer data access.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enabling subscription-based replenishment with wear-rated durability guarantees. Millennial owners in United States metropolitan markets are displacing traditional retail cycles through curated monthly boxes.
- Pet Specialty Stores:Vertically controlled private-label sourcing through European chains like Fressnapf Tierfutter GmbH dominates premium positioning with trained staff consultation.
- Supermarkets:Mass-market penetration through high-velocity SKU placement targets convenience-oriented purchasers.
- Direct Sales:Manufacturer-controlled channels bypassing retail markup for veterinary and institutional accounts.
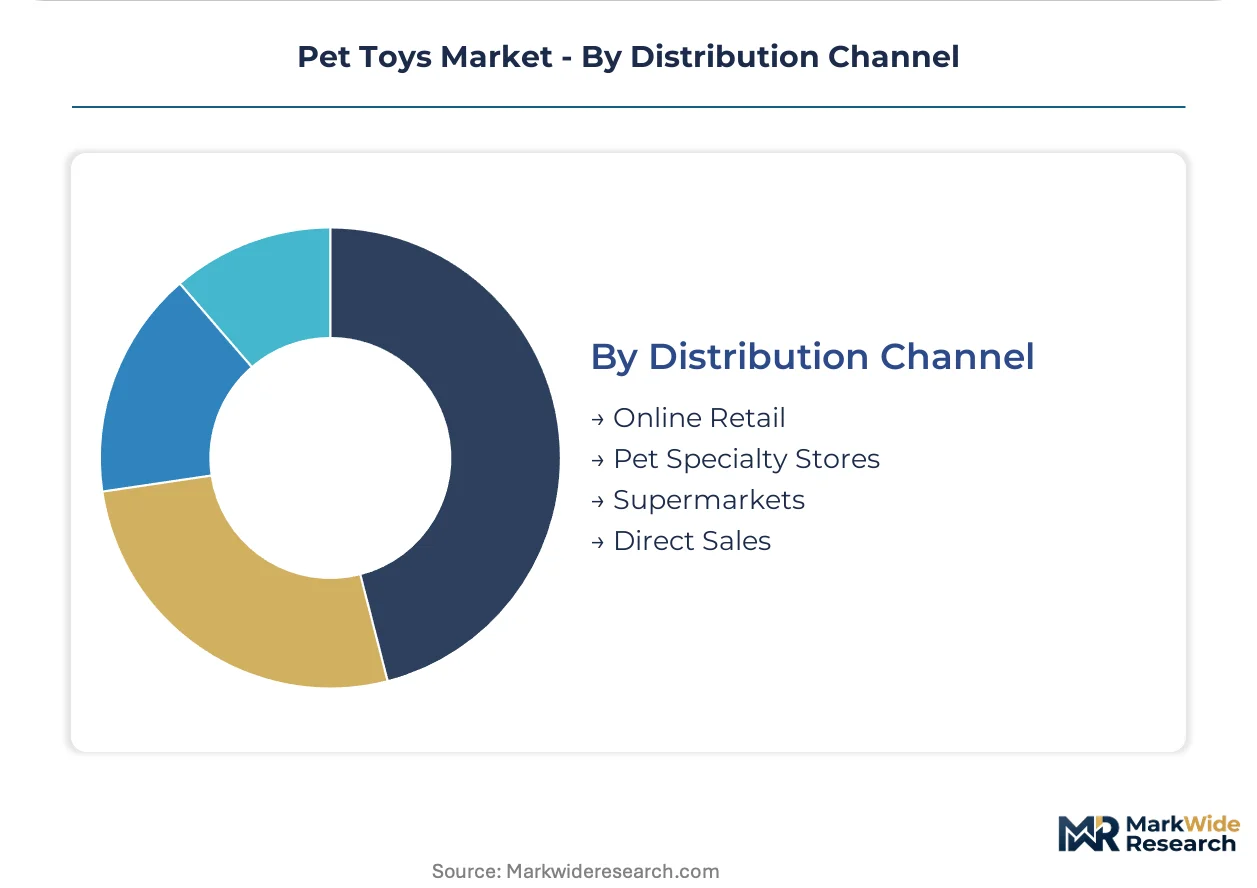
Shipment volume concentrates in Pet Specialty Stores; Online Retail is gaining share fastest on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai and Indonesian latex plantations anchor raw material flows for vulcanized rubber chew toys, while automated molding clusters in China's Pearl River Delta compress production economics for woven synthetics and thermoplastic elastomers.
United States
Millennial pet owners in metropolitan markets drive sensor-enabled interactive toy adoption through subscription-based replacement programs. FDA guidelines on animal product safety govern material composition and migration limits for oral-contact accessories. Injection molding facilities in Ohio and technical formulation expertise in Akron supply custom vulcanization recipes to premium veterinary channels.
Germany
Educated urban households with pet insurance coverage prioritize clinically tested enrichment toys for behavioral intervention. EU REACH chemical restrictions on phthalates and heavy metals accelerate certified natural rubber adoption among compliant manufacturers. Fressnapf Tierfutter GmbH dominates European pet specialty distribution through vertically controlled private-label sourcing from regional suppliers.
China
Domestic brands serving Shanghai and Beijing metropolitan markets pre-certify product lines against GB standards and EU REACH thresholds for streamlined dual-market entry. SAMR enforcement actions in 2024 tightened migration limits on colorants and plasticizers in oral-contact accessories. Automated injection molding clusters in Dongguan and Shenzhen compress unit costs while improving seam durability for export-oriented plush toy production.
Japan
Metropolitan pet owners in Tokyo and Osaka exhibit strong preference for premium gifting segments despite faster plush toy wear rates. METI standards and JIS certification requirements elevate compliance burdens for imported accessories. Technical partnerships between Japanese distributors and Leverkusen-based formulators supply custom elastomer compounds for aggressive chewer segments.
United Kingdom
Subscription-based direct-to-consumer platforms displace traditional retail replenishment cycles among educated urban demographics. Pets at Home Group Plc anchors mass-market penetration through high-velocity SKU placement across national store networks. Greater London manufacturing consultants specialize in connecting legacy ERP systems to automated quality detection for mid-tier exporters serving EU markets.
Pet Toys Market Vendor Landscape
Global majors compete with regional champions across material certification and channel access dimensions, producing a tiered structure where premium positioning depends on REACH-compliant natural rubber formulations and veterinary channel relationships. Three archetypes dominate: vertically integrated Chinese molding specialists, European private-label distributors with captive sourcing, and North American direct-to-consumer platforms leveraging subscription economics. Capacity expansion in automated injection facilities and backward integration into raw material testing laboratories represent the dominant competitive moves.
Among Germany-based distributors, Fressnapf Tierfutter GmbH exemplifies the vertically integrated private-label archetype through controlled sourcing networks. KONG Company occupies a position representing premium vulcanized rubber specialists with proprietary formulation expertise. Spectrum Brands Holdings, Inc. sits within the mass-market penetration tier, anchoring big-box retail partnerships across North American channels.
| Leading Market Players |
|---|
| Fressnapf Tierfutter GmbH |
| Unicharm Corporation |
| Spectrum Brands Holdings, Inc. |
| Petz Group |
| Outward Hound |
| KONG Company |
| Pets at Home Group Plc |
| Tractor Supply Company |
| Chewy, Inc. |
| Others |
Supply Flow & Price Mechanics
Natural rubber latex from Thai and Indonesian plantations flows through vulcanization facilities in Ohio and Bavaria before reaching three distinct pricing tiers downstream. REACH-compliant certified grades command veterinary channel premiums in Germany, while mass-market injection-molded synthetics compete on unit cost through Chinese manufacturing clusters.
Pricing Analysis
Wear-rated durability guarantees bundled into subscription replacement programs separate premium positioning from transactional retail. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service inclusion. Pricing pressure stems from automated Chinese molding compression in mass-market tiers. Veterinary clinics and insured urban households show lowest price sensitivity; animal shelters and convenience-oriented supermarket purchasers exhibit highest elasticity.
Supply Chain Analysis
EU Green Deal packaging mandates and domestic-content preferences in European procurement are reshaping sourcing toward certified fiber suppliers in Portugal and Turkey. Raw material flows draw from Thai latex plantations, Guangdong textile finishing hubs, and Leverkusen specialty elastomer formulators. Single-source vulnerability concentrates in Dongguan and Shenzhen injection molding clusters vulnerable to regional power rationing. Distribution runs through vertically controlled European specialty retail, North American big-box partnerships, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as multi-jurisdiction certification timelines and automated capital requirements force smaller exporters toward acquisition or exit. REACH compliance costs and real-time quality system investments favor scaled manufacturers with dedicated testing laboratories.
For Market Incumbents: Hedge against natural rubber price volatility through backward integration into vulcanization recipe development with Akron and Leverkusen specialty formulators. Capture channel control by deepening veterinary relationships in underpenetrated German specialty retail. Counter subscription-based displacement through proprietary IoT-enabled behavioral tracking platforms.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting metropolitan United States pet insurance households with curated monthly replacement boxes. White-space opportunities concentrate in clinically tested prescription-grade enrichment toys for German veterinary channels and compostable fiber designs for EU Green Deal compliance. Prioritize pre-certification against both GB and REACH thresholds for streamlined dual-market entry.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier manufacturers with legacy ERP systems requiring automated quality integration in Greater London consulting corridors. Long-term viability over a multi-year horizon rests on acquisition targets possessing captive raw material testing laboratories and established REACH certification protocols. Monitor SAMR enforcement intensity in China's oral-contact accessories segment as inflection indicator for compliance-cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Investment | EU chemical restrictions on phthalates and heavy metals create veterinary channel access barriers for uncertified competitors. |
| Automated Injection Molding Scale-Up | Pearl River Delta robotic deployment compresses plush toy unit costs while improving seam durability standards. |
| Subscription Platform Launch | Direct-to-consumer curated boxes displace traditional retail replenishment among millennial pet insurance households. |
| Specialty Elastomer Backward Integration | Proprietary vulcanization recipes from Akron and Leverkusen formulators defend premium positioning against thermoplastic substitution. |
| GB-REACH Dual Pre-Certification | Streamlined dual-market entry accelerates product launch cycles for Shanghai and Beijing metropolitan brand expansion. |
Methodological Framework
Independent corroboration across regulatory filing databases, customs trade records, and retail audit data underwrites the qualitative findings in this study. Primary interviews with pet product procurement managers at veterinary distributors, category buyers at European specialty retailers, formulation chemists at elastomer compounders, and supply chain directors at Chinese molding facilities combined with secondary validation from FDA guidance documents, ECHA REACH restriction entries, SAMR enforcement notices, and Nielsen retail tracking data. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Rate-of-change decomposition across product type, material grade, customer application, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating millennial demographic penetration curves, pet insurance coverage expansion patterns, and automated manufacturing adoption rates. Industry-specific forecast inputs included natural rubber futures volatility indices and EU Green Deal implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for biodegradable polymer tensile strength breakthroughs would alter the outlook. Forecasts reflect assumptions regarding sustained REACH enforcement intensity and continued Chinese manufacturing cluster concentration. Supply disruption scenarios from regional power rationing or latex plantation climate events could revise trajectories materially. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Car Seat Market
Pet Care Products
China Pet Clothing Market
Pet Care Products
USA Bird Food Market
Pet Care Products
Pet Food Bowl Market
Pet Care Products
Dog Dental Chews Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
Argentina Pet Food Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Brazil Cat Litter Market
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
Taiwan Pet Food Market
Pet Care Products
Global Cat Trees and Towers Market
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
Pet Clothing Market
Pet Care Products
Insulated Dog House Market
Pet Care Products
Dog Bathing Systems Market