
 China Pet Training Services Market | 2026-2036
China Pet Training Services Market Size, Share, and Industry Trends Forecast 2026-2036
China Pet Training Services Market Insights
The service tier split in China pet training is hardening between premium personalized programs and standardized group classes. PetDog leverages its urban studio network to dominate premium obedience instruction in Shanghai and Beijing. Ringpai sustains mass-market penetration through franchise partnerships in second-tier cities. Favor Pets differentiates via specialized behavior modification protocols for rescue animals sourced through shelter networks.
Pet training services encompass structured behavioral instruction delivered by certified professionals using standardized curricula and progressive skill assessment protocols, with session frequencies typically ranging from weekly 45-minute classes to intensive daily immersion programs lasting 2-4 weeks. The primary commercial purpose centers on modifying animal conduct to ensure public safety, reduce property damage, and strengthen human-animal bonds in residential settings. Obedience training occupies the largest revenue pool due to mandatory municipal registration requirements in major Chinese cities, while behavior modification commands premium pricing for aggression and anxiety cases. Positive reinforcement methods lead volume growth as pet owners reject aversive techniques, though clicker training retains a dedicated niche among competitive agility participants.
SAMR's evolving consumer service classification rules and municipal pet management ordinances in Beijing and Shanghai shape operator licensing requirements and facility inspection protocols. The national standardization administration under GB framework development for companion animal services further structures curriculum certification and trainer credentialing pathways. Stakeholders must monitor regulatory harmonization between provincial pet registration systems and emerging national service quality benchmarks to anticipate compliance cost shifts and market access barriers.
Market Dynamics
Digital training platforms are compressing session delivery costs while SAMR's evolving consumer service classification rules reshape facility licensing requirements across tier-one cities. This structural tension between platform scalability and regulatory compliance is forcing operators to recalibrate capital deployment strategies.
Growth Catalysts
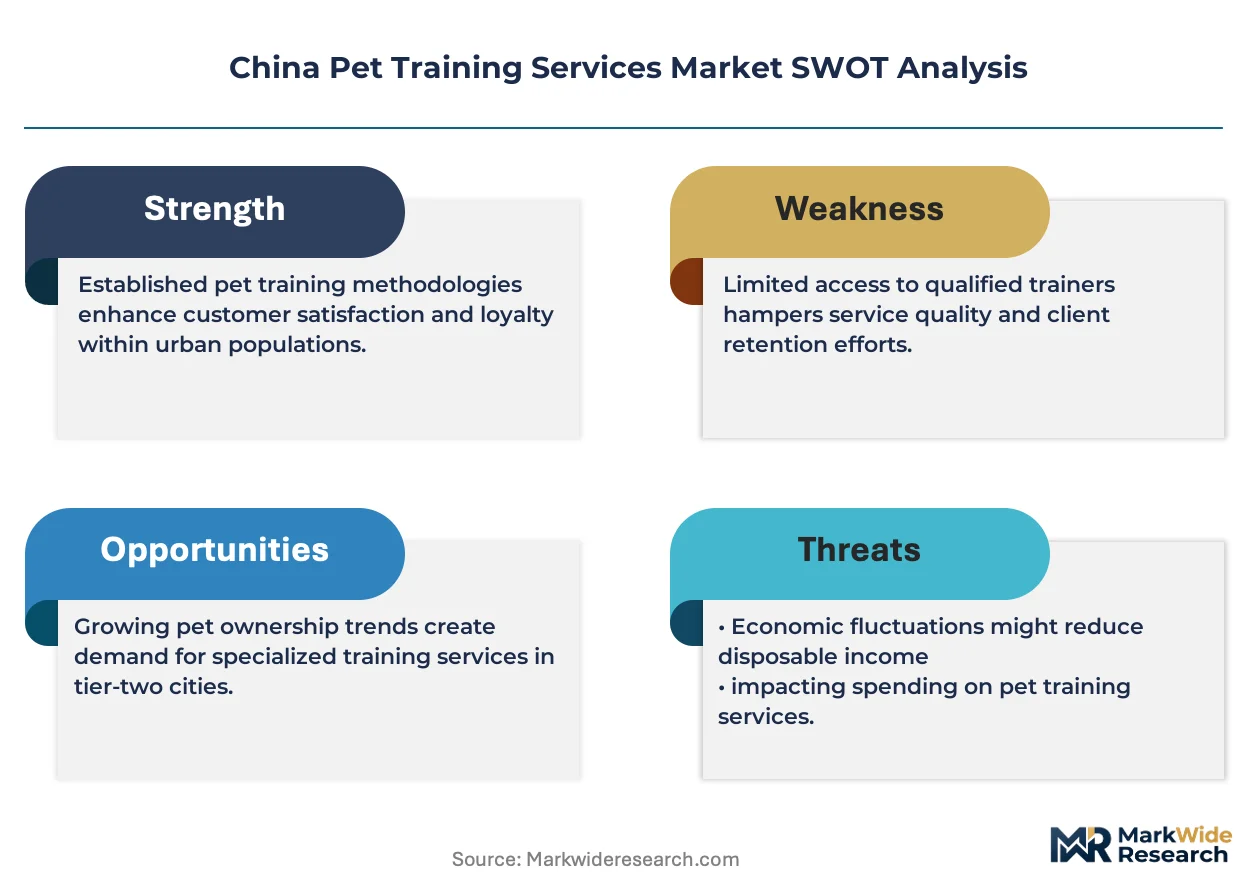
- GB Standards Framework Development:The national standardization administration's companion animal service benchmarks are creating curriculum certification pathways that reduce buyer uncertainty and accelerate professionalization.
- Urban Household Pet Ownership:Shanghai and Beijing municipal registration mandates require obedience certification, converting compliance into recurring service demand.
- Positive Reinforcement Methodology:Rejection of aversive techniques among millennial pet owners is expanding addressable market for certified behavioral consultants.
Market Restraints
- Trainer Certification Bottlenecks:SAMR's facility inspection protocols and provincial registration system fragmentation create multi-month licensing delays for new market entrants.
- Second-Tier City Infrastructure Gaps:Concentration of certified professionals in Shanghai, Beijing, and Shenzhen leaves interior provinces underserved and service quality inconsistent.
- Digital Platform Substitution:AI-powered training apps and video-on-demand modules capture price-sensitive segments that previously enrolled in group classes.
Strategic Opportunities
- Shelter Network Partnerships:Rescue animal behavior modification protocols command premium pricing while addressing municipal stray management priorities in Shenzhen and Guangzhou.
- Dual Carbon Goals Alignment:MEE's environmental compliance incentives favor urban studio operators with LEED-certified facilities and low-emission transport for mobile services.
- Agility Competition Ecosystem:Clicker training specialization for competitive sports creates recurring revenue through tournament preparation and equipment bundling.
Industry Challenges
- Certified Professional Scarcity:GB framework credentialing pathways remain underdeveloped, constraining expansion velocity for premium personalized program operators.
- Facility Capex Intensity:SAMR's spatial requirements for group class venues and outdoor training zones elevate real estate costs in core urban districts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Pet Training Services Market |
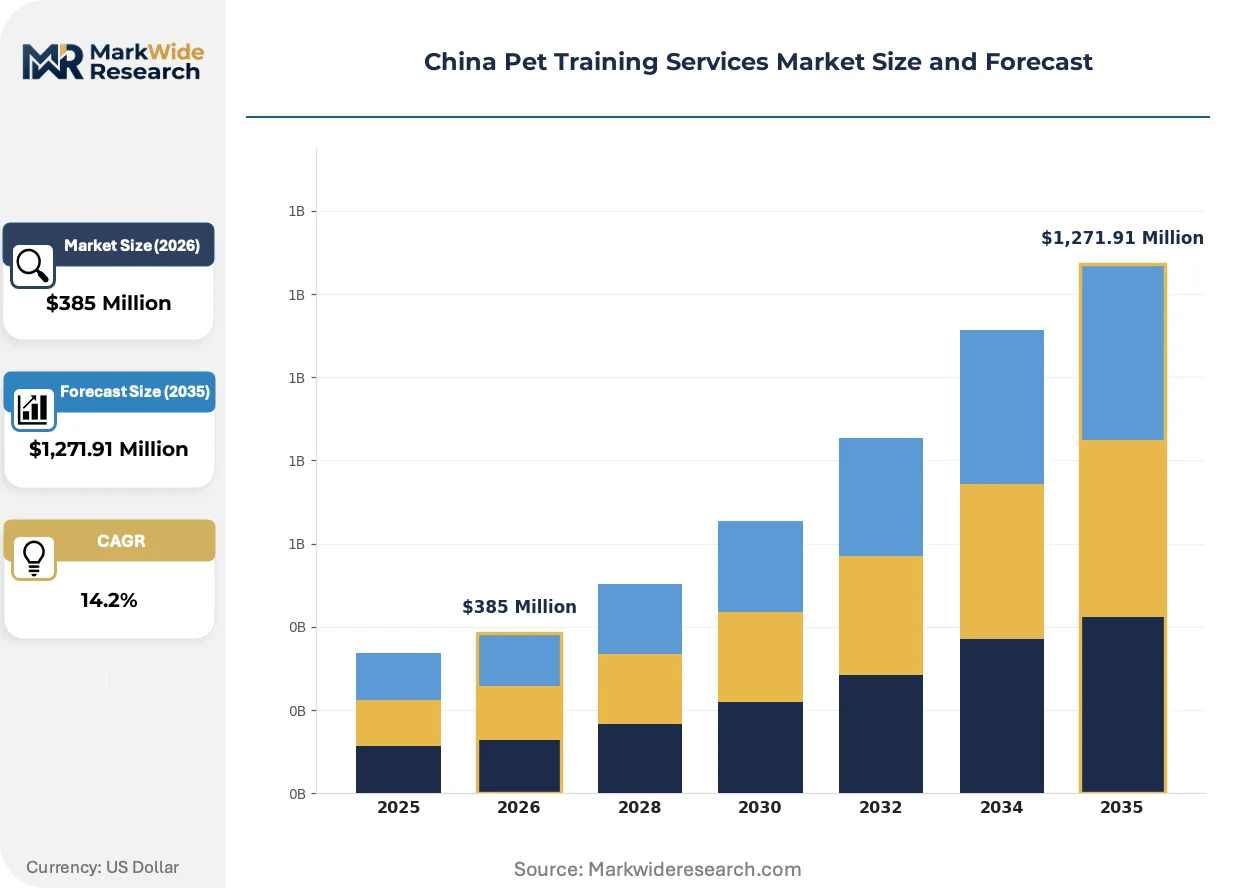
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $1,271.91 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Obedience Training, Behavior Modification, Agility Training, Puppy Training Pet Type: Dogs, Cats, Birds, Rabbits Training Method: Positive Reinforcement, Clicker Training, Leash Training, Remote Training Customer Type: Pet Owners, Breeders, Shelters, Trainers |
| Companies Covered | PetDog, Ringpai, Favor Pets, Nestlé Purina, Mars Incorporated, Your Hakimi, ZhuaZhua, Advanced Vet Care (AVC), Petsfolio, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Pet Training Services Market Trends and Innovations
Service delivery models are bifurcating between high-touch studio experiences and algorithm-assisted remote coaching. This divergence is compressing mid-market positioning while creating distinct capability requirements for each trajectory.
AI-powered behavioral assessment tools are integrating video analysis of canine body language with customized homework protocols. Tier-one city operators deploy these systems to maintain client engagement between in-person sessions. The technology is integrating predictive analytics that flag regression risks before owners recognize symptoms, enabling proactive intervention scheduling.
SAMR's draft consumer service classification rules are mandating liability insurance minimums and trainer background verification for facilities serving more than fifty animals annually. Beijing and Shanghai municipal authorities have accelerated inspection frequency ahead of national harmonization. Premium studio networks are absorbing compliance costs through membership tier restructuring while franchise operators in second-tier cities face exit pressure.
Subscription-based maintenance programs are displacing episodic class enrollment among affluent urban households. Annual contracts with quarterly refresher sessions and 24/7 chat support now dominate Shanghai's high-end segment. This shift is most visible among dual-income households with large-breed dogs subject to strict leash-law enforcement.
China Pet Training Services Market Segmentation
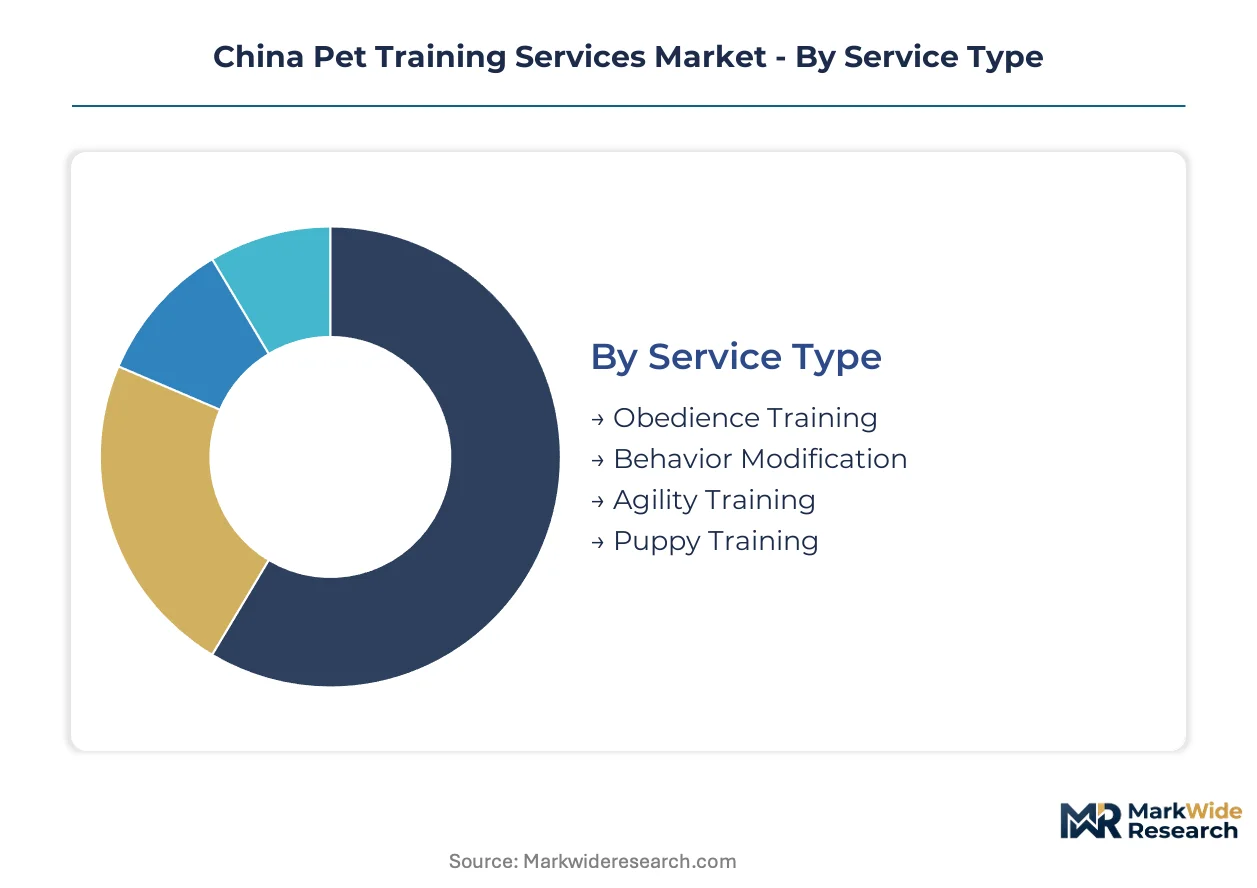
Training service providers in China configure delivery models around four distinct axes. Each segmentation layer reveals divergent margin structures, certification requirements, and geographic concentration patterns that shape competitive positioning.
Service Type:
Revenue concentration varies sharply by program intensity and municipal compliance mandates.
- Obedience Training:Structured instruction covering basic commands, leash manners, and municipal registration compliance. Shanghai and Beijing registration mandates convert certification requirements into recurring revenue streams for urban studio networks.
- Behavior Modification:Intensive protocols addressing aggression, anxiety, and trauma in companion animals. Shenzhen and Guangzhou shelter networks drive premium pricing for rescue animal rehabilitation services.
- Agility Training:Competitive sports preparation with equipment-intensive curricula. Tournament circuits in tier-one cities sustain niche demand among performance-oriented owners.
- Puppy Training:Early socialization programs targeting animals under six months. First-time millennial owners in Beijing and Shanghai dominate enrollment.
Volume sits with Obedience Training; growth tilts toward Behavior Modification.
Pet Type:
Species-specific physiological and behavioral characteristics dictate trainer specialization and facility design.
- Dogs:Dominant species by service volume, spanning municipal compliance mandates to competitive sports. Large-breed ownership restrictions in Beijing and Shanghai intensify demand for advanced obedience certification.
- Cats:Litter box issues and inter-pet aggression drive consultation demand. Urban apartment dwellers in Guangzhou and Shenzhen represent the expanding customer base.
- Birds:Vocalization control and harness training for companion parrots. Enthusiast communities in Chengdu and Hangzhou sustain specialized practitioners.
- Rabbits:Litter training and handling desensitization for indoor housing. Young pet owners in second-tier cities drive emerging demand.
Canine services absorb the bulk of professional capacity; feline programming expands most quickly.
Training Method:
Methodology selection correlates with owner demographics, price sensitivity, and intended activity outcomes.
- Positive Reinforcement:Reward-based protocols rejecting aversive stimuli. Millennial owners across tier-one cities reject punishment-based alternatives, expanding addressable market for certified behavioral consultants.
- Clicker Training:Precision marking techniques for competitive agility and trick training. Tournament preparation circuits in Shanghai sustain dedicated practitioner networks.
- Leash Training:Walking manners and public space compliance. Municipal enforcement intensity in Beijing drives enrollment spikes following policy announcements.
- Remote Training:Electronic collar protocols for off-leash reliability. Rural and suburban owners with large property footprints sustain demand despite urban rejection.
Positive Reinforcement commands the widest adoption; Clicker Training maintains the steepest expansion trajectory among competitive segments.
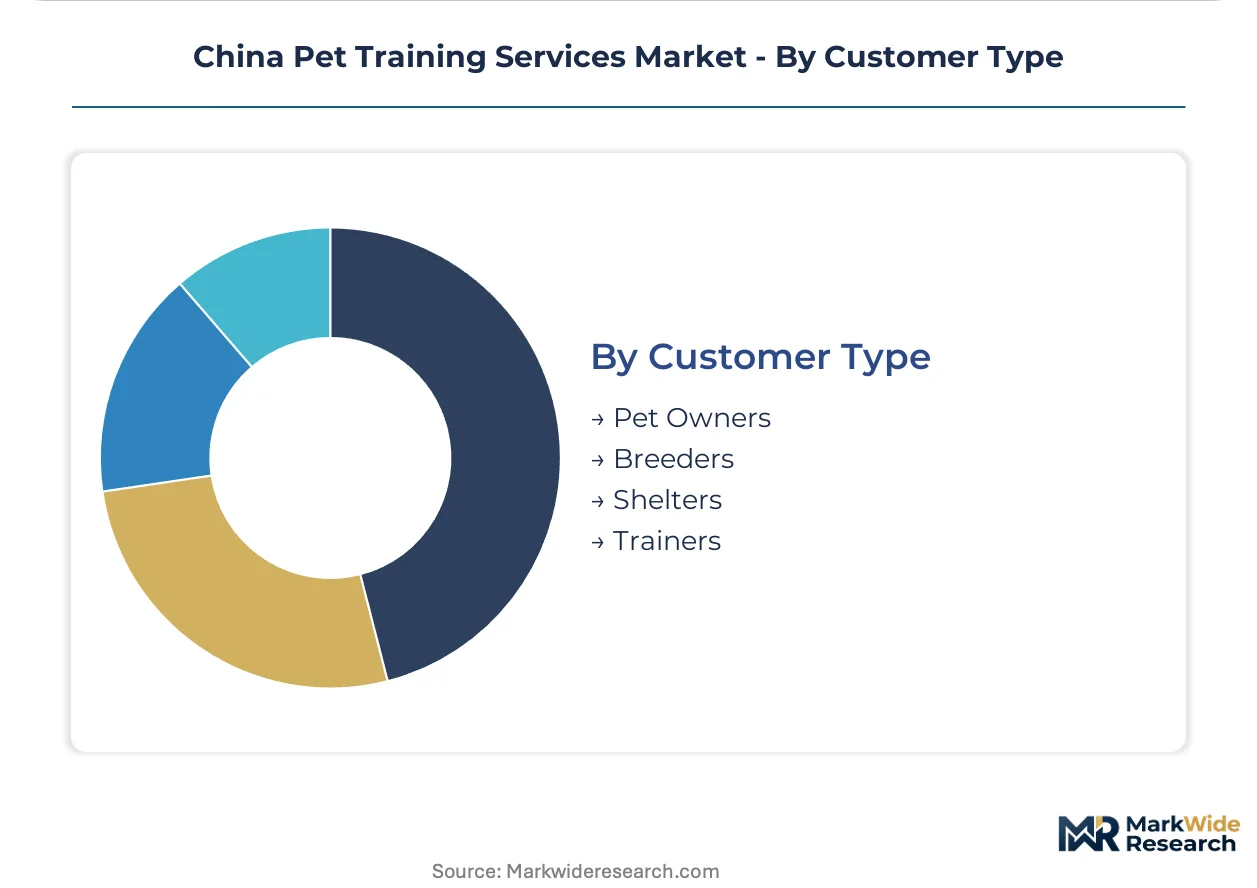
Customer Type:
Procurement authority and volume scale separate institutional buyers from individual consumers.
- Pet Owners:Individual households purchasing direct-to-consumer services. Dual-income families in Shanghai with large-breed dogs drive subscription maintenance program adoption.
- Breeders:Commercial operations requiring puppy socialization and buyer handover protocols. Kennel concentration in Hebei and Shandong provinces shapes regional service demand.
- Shelters:Municipal and nonprofit organizations managing rescue animal rehabilitation. Shenzhen and Guangzhou stray management priorities fund behavior modification contracts.
- Trainers:Professional certification candidates and continuing education seekers. GB framework development under the national standardization administration structures credentialing pathways.
Individual Pet Owners generate the highest transaction frequency; institutional Shelters deliver the most predictable contract volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors China's pet training services demand through municipal registration mandates that convert compliance into recurring revenue streams for urban studio networks.
Beijing
Beijing's large-breed ownership restrictions intensify demand for advanced obedience certification among dual-income households. SAMR facility inspection protocols and municipal pet management ordinances shape operator licensing requirements. Chaoyang and Haidian districts concentrate premium studio networks serving affluent pet owners.
Shenzhen
Shenzhen's shelter network partnerships drive premium pricing for rescue animal behavior modification services. Municipal stray management priorities fund rehabilitation contracts with specialized operators. Nanshan and Futian districts host the highest density of certified behavioral consultants.
Guangzhou
Guangzhou's expanding feline service demand stems from urban apartment dwellers seeking litter box and inter-pet aggression solutions. Provincial registration system fragmentation creates multi-month licensing delays for new market entrants. Tianhe district concentrates emerging cat-specific training practitioners.
Chengdu
Chengdu's enthusiast communities sustain specialized bird training practitioners for vocalization control and harness protocols. Second-tier city infrastructure gaps leave certified professionals concentrated in coastal provinces. Jinjiang district hosts niche operators serving companion parrot owners.
China Pet Training Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and facility quality dimensions. The service tier split hardens between personalized programs and standardized group classes. Three archetypes dominate: urban studio networks with SAMR-compliant facilities, franchise operators pursuing mass-market penetration, and specialized behavior modification consultants. Competitive moves concentrate on municipal licensing acquisition and shelter network partnership formation.
Within the urban studio archetype, PetDog and Ringpai exemplify divergent scaling strategies. PetDog occupies a position representing premium obedience instruction concentration in tier-one cities. Ringpai anchors the franchise-driven expansion model into second-tier markets. Favor Pets sits within the specialized tier, representing behavior modification protocol development for rescue animal segments.
| Leading Market Players |
|---|
| PetDog |
| Ringpai |
| Favor Pets |
| Nestlé Purina |
| Mars Incorporated |
| Your Hakimi |
| ZhuaZhua |
| Advanced Vet Care (AVC) |
| Petsfolio |
| Others |
Pricing and Supply Chain Analysis
Certified behavioral consultant concentration in Shanghai and Beijing generates labor-cost differentials that widen pricing-tier spreads between premium personalized programs and mass-market group classes. Tier-one city operators absorb SAMR compliance costs through membership restructuring while second-tier franchise networks compete on entry-level session rates.
Pricing Analysis
Outcome-based pricing anchors on municipal registration compliance success and behavioral modification guarantees rather than hourly rates. Three-tier pricing structure across premium, standard, and economy levels separates PetDog's urban studio memberships from Ringpai's franchise group classes and digital platform subscriptions. Price differentiation rests on trainer certification tier under GB framework pathways and facility LEED certification status. Cost compression in the mid-market intensifies as AI-powered training apps capture price-sensitive segments previously enrolled in standardized curricula. Individual pet owners with large-breed dogs in Shanghai demonstrate lowest price sensitivity due to leash-law enforcement stakes, while rural remote-training users exhibit highest elasticity.
Supply Chain Analysis
Specialized training equipment supply rests on German and Japanese manufacturers for agility apparatus and precision clicker systems. Raw material dependencies include high-grade polymer flooring for indoor studios, custom-fit harness hardware, and veterinary-grade treat formulations for positive reinforcement protocols. Supply chain risk centers on single-source vulnerability for certified assessment tools under GB standardization administration protocols. Distribution runs through direct studio procurement for premium networks and centralized franchise supply hubs for mass-market operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over certified trainer pipelines and shelter network relationships determines pricing power and municipal contract access.
For Market Incumbents: To counter digital platform substitution threatening group class enrollment, urban studio networks should deepen backward integration into trainer certification academies under GB framework pathways. Incumbents must secure exclusive shelter network partnerships in Shenzhen and Guangzhou before municipal stray management contracts consolidate with single providers.
For New Entrants and Emerging Players: Short-form video platforms and algorithm-assisted remote coaching channels offer the lowest customer acquisition cost route into price-sensitive millennial segments. White-space targets include feline behavior modification in Guangzhou apartment complexes and bird training specialization in Chengdu enthusiast communities. Go-to-market positioning should emphasize subscription-based maintenance programs with 24/7 chat support to displace episodic class enrollment.
For Investors and Strategic Acquirers: Re-rating potential sits with dual-certified operators possessing both SAMR-compliant facilities and shelter network rehabilitation contracts given municipal stray management funding expansion. Long-term viability favors platforms integrating AI behavioral assessment with in-person studio networks. The signal to watch is GB framework credentialing pathway completion rates as inflection indicator for addressable professional capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Trainer Certification Academy Establishment | GB framework credentialing pathways reduce licensing bottlenecks and accelerate studio expansion velocity. |
| Shelter Network Partnership Formation | Shenzhen and Guangzhou municipal stray management priorities fund predictable rehabilitation contract volumes. |
| AI Behavioral Assessment Integration | Predictive analytics flag regression risks before owners recognize symptoms, enabling proactive intervention scheduling. |
| Subscription Maintenance Program Launch | Annual contracts with quarterly refresher sessions dominate Shanghai's high-end dual-income household segment. |
| LEED-Certified Facility Rollout | MEE environmental compliance incentives favor urban studio operators with low-emission transport for mobile services. |
Research Methodology
Document review covered SAMR regulatory filings, GB standards development records, and municipal pet management ordinances, complemented by interviews with certified behavioral consultants, urban studio network operators, franchise development heads, and shelter program directors. Secondary validation drew from national standardization administration publications, provincial registration system documentation, and MEE environmental compliance disclosures. Bottom-up service provider capacity modeling triangulated against top-down household pet ownership projections.
Market size and growth trajectory outputs across the analysis window reflect segmented modeling by service type, pet species, training methodology, and customer archetype. CAGRs were derived from trend extrapolation of municipal registration mandate enforcement intensity and digital platform adoption curves. Industry-specific inputs incorporated SAMR facility inspection protocol evolution and GB framework credentialing pathway development timelines.
The model holds under stable regulatory harmonization between provincial pet registration systems and national service quality benchmarks; deviation in SAMR consumer service classification rule finalization or municipal leash-law enforcement intensity shifts would revise expansion velocity assumptions. Forecasts reflect documented base conditions with acknowledged sensitivity to certified professional scarcity and facility real estate cost trajectories. A small set of named triggers—GB framework implementation pace, shelter network contract consolidation, and AI platform penetration rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Hotels Market
Pet Care Products
Dog Nail Clippers Market
Pet Care Products
South Africa Pet Boarding Market
Pet Care Products
South Korea Dog Food Market
Pet Care Products
Dog Harness Market
Pet Care Products
Interactive Dog Toys Market
Pet Care Products
Germany Pet Training Services Market
Pet Care Products
Frozen Pet Food Market
Pet Care Products
South America Pet Diet Market
Pet Care Products
Large Breed Dog Food Market
Pet Care Products
Pet Snacks and Treats Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
Europe Pet Diet Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Dog Litter Boxes Market