
 Indonesia Pet Food Market | 2026-2036
Indonesia Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Pet Food Market Outlook
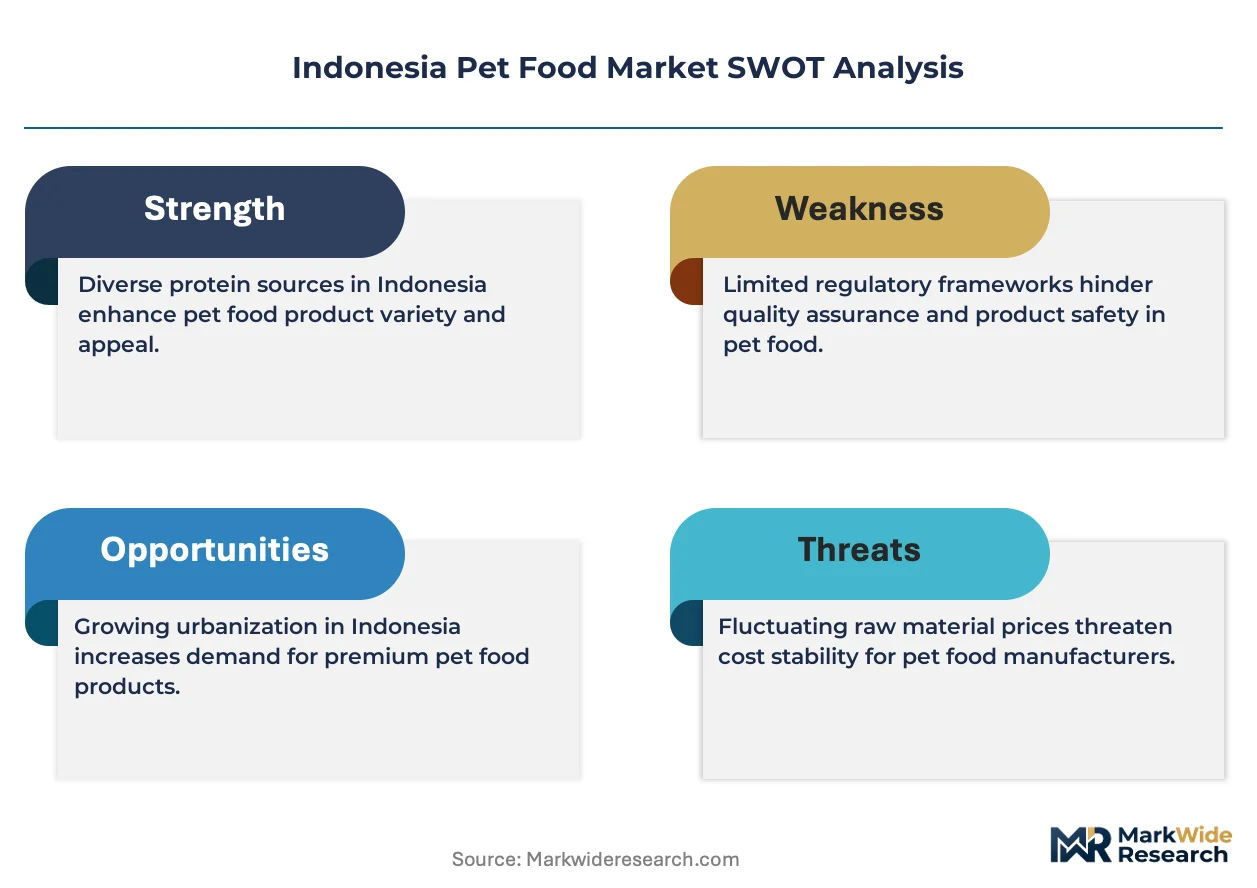
BPI certification for animal feed producers is unwinding the competitive landscape, forcing smaller mills to consolidate or exit. Mars Incorporated leverages its manufacturing scale to dominate modern trade channels across Java. Charoen Pokphand Group anchors its position through backward integration into poultry protein supply chains. Nestle Purina differentiates via veterinary channel partnerships and prescription diet formulations.
Indonesia pet food comprises nutritionally formulated feed products manufactured through extrusion, retorting, or cold-pressing processes, with protein content typically ranging from 18% to 32% depending on species life stage. These products serve commercial purposes by meeting complete dietary requirements for companion animals in household, clinical, and retail environments. Dry food occupies the volume leadership position due to shelf stability and lower logistics costs in archipelago distribution. Wet food commands premium shelf space in urban supermarkets as cat ownership rises in Jakarta apartments. Treats represent the fastest-expanding margin pool, driven by humanization trends among middle-class pet owners.
Indonesia's Ministry of Agriculture and the National Agency of Drug and Food Control (BPOM) enforce feed safety and labeling standards that shape product registration timelines and import permissions. BIS-equivalent national standards for pet food manufacturing are tightening facility hygiene requirements, raising capital barriers for new entrants. Stakeholders must monitor regulatory harmonization between ASEAN feed safety protocols and domestic certification to anticipate compliance cost shifts.
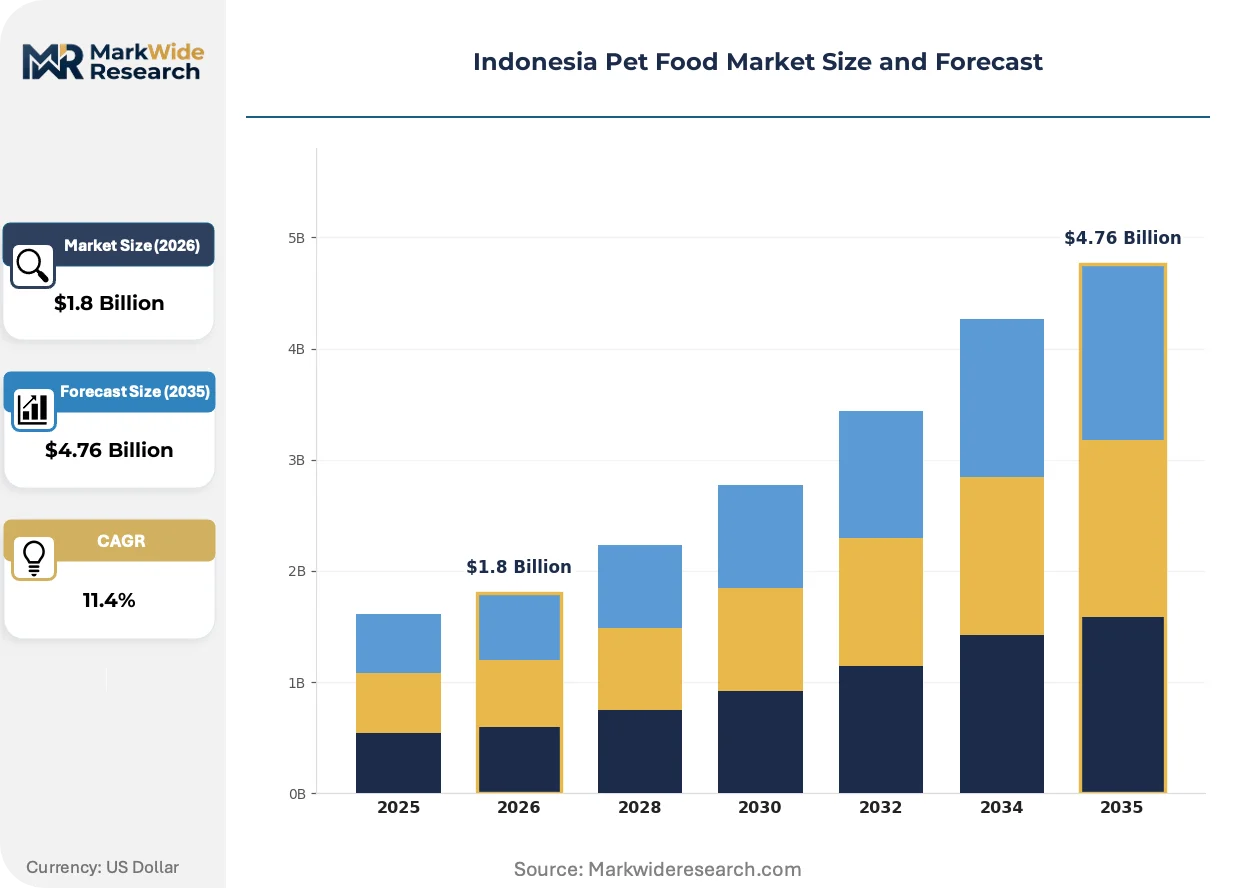
Market Dynamics
Indonesia's Ministry of Agriculture BPI certification mandate is restructuring manufacturing capacity, forcing consolidation among animal feed producers while elevating compliance costs for new market entrants across Java and Sumatra.
Growth Catalysts
- Urban Pet Humanization:Jakarta and Surabaya millennial households now treat companion animals as family members, driving complete diet substitution from table scraps to formulated nutrition. This behavioral pivot expands addressable household penetration.
- ASEAN Feed Safety Harmonization:Regulatory alignment with regional protocols is streamlining cross-border ingredient sourcing for Indonesian manufacturers, reducing procurement friction for imported protein inputs.
- Cold-Pressed Manufacturing:Low-temperature processing technology preserves heat-sensitive nutrients in premium formulations, enabling functional claim differentiation that commands shelf space in modern retail channels.
Market Restraints
- Poultry Protein Input Volatility:Charoen Pokphand Group and other integrated poultry processors control the bulk of rendered protein supply, creating feedstock pricing power that squeezes independent pet food margins.
- Archipelago Logistics Cost Structure:Dry bulk shipping between Java manufacturing centers and outer island retail endpoints adds 15-25% to landed product costs, disadvantaging volume players against local milling operations.
- Import Quota Friction:Ministry of Agriculture feed safety regulations impose registration timelines that delay new international product introductions by 8-14 months, protecting incumbent domestic producers.
Strategic Opportunities
- Prescription Diet Channel Expansion:Veterinary clinic partnerships offer a defensible route to premium pricing, with Nestle Purina's therapeutic formulations demonstrating proof-of-concept for clinical channel capture.
- Outer Island Distribution Infrastructure:Makassar and Medan metropolitan corridors remain underserved by modern trade pet food availability, presenting first-mover advantages for cold-chain capable entrants.
- Treat Segment Margin Capture:Humanization trends concentrate discretionary spending on reward and training products, where ingredient cost-to-price ratios exceed complete diets by substantial margins.
Industry Challenges
- BPI Certification Timeline Compression:Facility hygiene audits and documentation requirements are extending product launch cycles, demanding dedicated regulatory affairs capacity that smaller mills cannot staff.
- Veterinary Nutrition Specialist Scarcity:Formulation expertise combining companion animal clinical nutrition with extrusion process engineering remains concentrated among a handful of Jakarta-based technical consultants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Pet Food Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements End User: Pet Owners, Veterinary Clinics, Pet Shops, Online Retailers Animal Type: Dogs, Cats, Birds, Small Mammals Packaging Type: Bags, Cans, Pouches, Bulk |
| Companies Covered | PT Evo Nusa Bersaudara, Citra Mandiri Kencana, Charoen Pokphand Group, Nestle Purina, Colgate-Palmolive Company (Hill's Pet Nutrition Inc.), Matahari Sakti, Mars Incorporated, PT Central Proteina Prima Tbk, PT Japfa Comfeed Indonesia Tbk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Pet Food Market Strategic Shifts
Extrusion technology advancement and regulatory compliance automation are redefining manufacturing economics, while channel fragmentation between modern retail, veterinary clinics, and direct-to-consumer platforms creates new competitive battlegrounds for shelf access and customer relationships.
High-moisture extrusion technology is decomposing the traditional dry-wet food boundary by producing shelf-stable products with elevated moisture content and fresh-meat inclusion rates. Urban cat owners in Jakarta apartment complexes are adopting these hybrid formats at accelerating rates, compressing the volume advantage historically held by conventional kibble manufacturing.
Indonesia's Ministry of Agriculture is tightening BPI certification requirements for animal feed producers, mandating HACCP-equivalent facility standards and batch traceability systems. This regulatory escalation is raising capital barriers for new entrants while rewarding incumbent manufacturers with compliant infrastructure, particularly affecting mid-scale mills in Central Java seeking to expand into companion animal formulations.
Subscription-based replenishment models are capturing recurring revenue from Jakarta's time-constrained professional households, displacing traditional supermarket stock-up behavior. Direct-to-consumer platforms with predictive algorithms are securing customer loyalty through personalized portion recommendations, with the highest adoption concentration visible among dual-income millennial dog owners in Greater Jakarta's gated residential clusters.
Indonesia Pet Food Market Segmentation
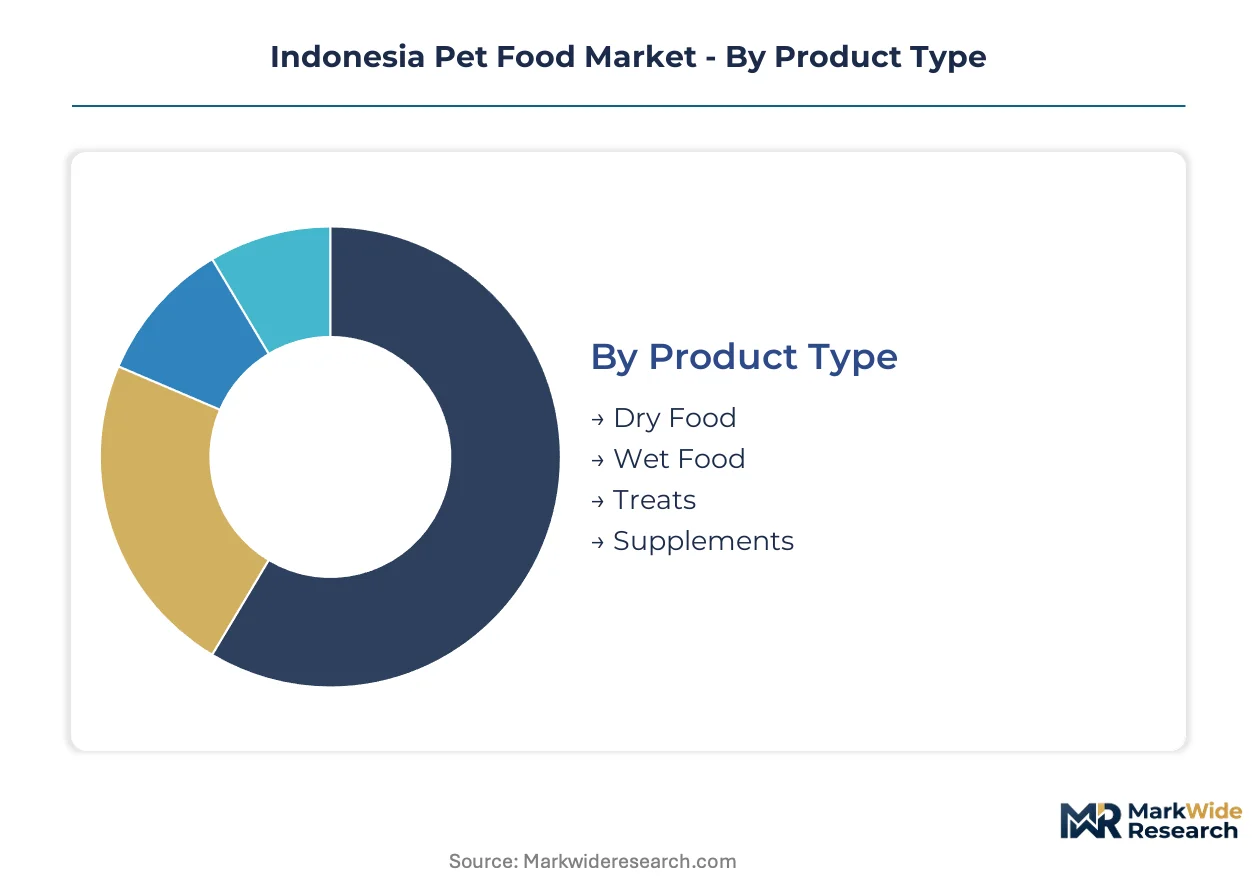
Indonesia's archipelago distribution economics and BPI certification tiers fragment the pet food market into sharply differentiated segments. Regulatory compliance costs and logistics constraints determine which product formats and channels can achieve viable unit economics across Java versus outer islands.
Product Type:
Regulatory differentiation separates shelf-stable formats from those requiring cold-chain infrastructure or specialized import permissions under Ministry of Agriculture feed safety protocols.
- Dry Food:Extruded kibble formulations with 8-12% moisture content dominate manufacturing scale economics. Demand concentrates in Greater Jakarta's supermarket channels, where Mars Incorporated and Charoen Pokphand Group leverage their compliant facilities to secure shelf space. Extended shelf life offsets archipelago shipping costs that penalize heavier wet alternatives.
- Wet Food:Retorted cans and pouches with 75-85% moisture content command premium positioning in urban apartment settings. Jakarta cat owners drive adoption as humanization trends elevate palatability expectations, though import quota friction delays new international product introductions by 8-14 months.
- Treats:Functional and reward products targeting training and bonding rituals capture discretionary spending from middle-class households.
- Supplements:Joint health, digestive, and coat-conditioning formulations serve aging pet demographics and veterinary-directed nutrition protocols.
Dry food handles the majority of throughput; treats are expanding most quickly on share.
End User:
Channel cost structures and customer acquisition economics determine which end-user segments support viable margin extraction.
- Pet Owners:Direct household purchasing through modern retail and e-commerce platforms represents the volume anchor. Subscription-based replenishment models capture recurring revenue from Jakarta's dual-income professional households, displacing traditional supermarket stock-up behavior.
- Veterinary Clinics:Prescription diet dispensing and clinical nutrition counseling generate premium pricing power. Nestle Purina's therapeutic formulations demonstrate proof-of-concept for this defensible channel, though veterinary nutrition specialist scarcity limits formulation expertise.
- Pet Shops:Independent specialty retailers serve breed-specific and premium niche demands in Surabaya and Bandung metropolitan corridors.
- Online Retailers:Direct-to-consumer platforms with predictive algorithms secure customer loyalty through personalized portion recommendations.
Pet owners generate the dominant revenue base; veterinary clinics deliver the steepest margin expansion trajectory.
Animal Type:
Species-specific nutritional requirements and household penetration rates create divergent growth profiles across companion animal categories.
- Dogs:Larger body mass and complete diet substitution from table scraps drive absolute consumption volume. Urban millennial households in Greater Jakarta treat companion animals as family members, expanding addressable household penetration for formulated nutrition.
- Cats:Rising apartment-dwelling populations in dense urban centers elevate wet food and high-moisture extrusion adoption. Jakarta's vertical residential clusters favor smaller-footprint pets with lower exercise requirements.
- Birds:Seed and pellet formulations serve established avian-keeping traditions in Java and Sumatra.
- Small Mammals:Rabbit, hamster, and guinea pig nutrition represents an emerging specialty segment.
Dogs anchor volume consumption; cats are gaining share fastest as urbanization reshapes household pet preferences.
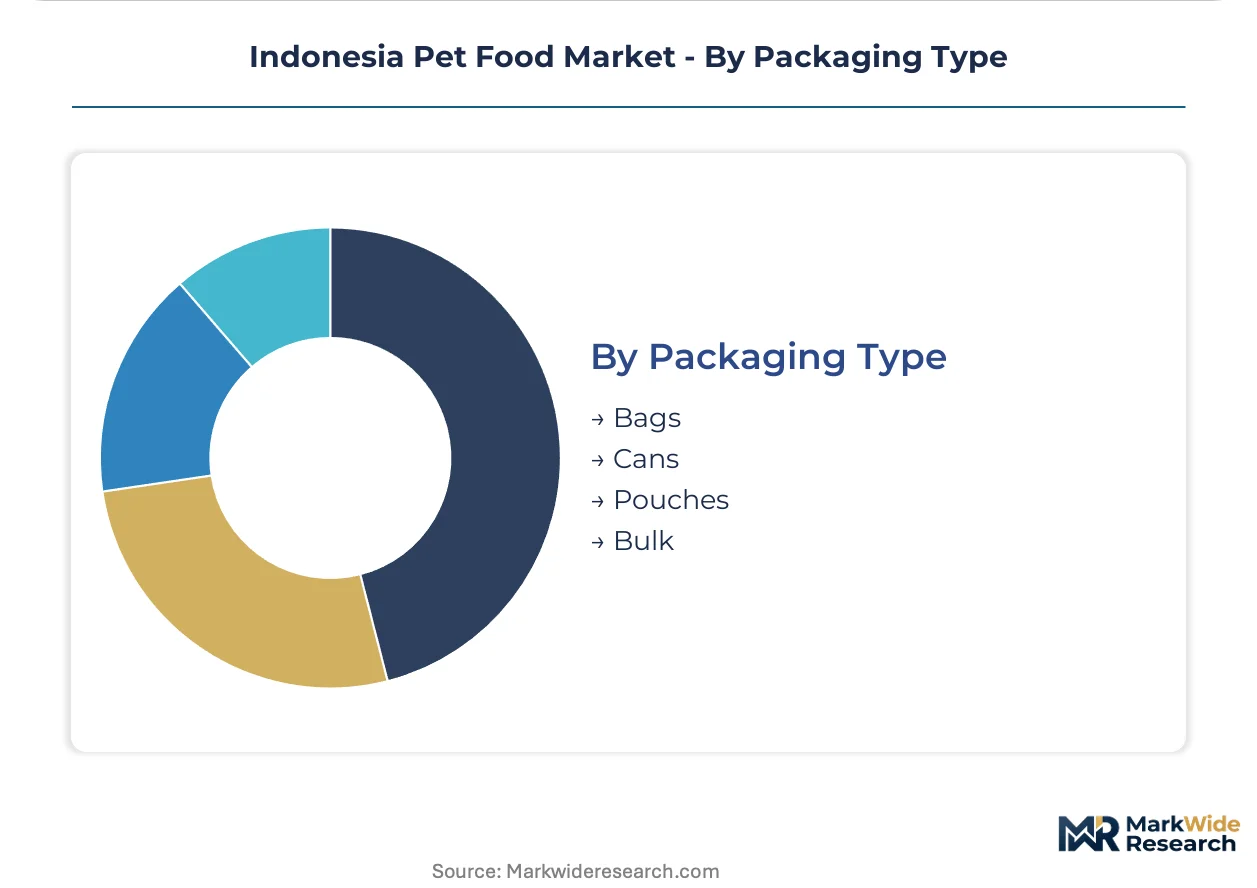
Packaging Type:
Material specifications and unit economics determine packaging suitability across Indonesia's fragmented retail infrastructure.
- Bags:Multi-layer polymer and paper-based flexible packaging dominates dry food distribution. Lower logistics costs in archipelago shipping favor lightweight formats for Java-to-outer-island distribution.
- Cans:Steel and aluminum retort containers preserve wet food sterility without refrigeration. Modern trade channels in Surabaya and Jakarta allocate premium shelf space to these formats.
- Pouches:Stand-up and flat flexible formats reduce material cost versus rigid alternatives while enabling portion-controlled dispensing.
- Bulk:Loose-fill and institutional packaging serves commercial kennels and multi-pet households.
Bags carry the highest shipment volumes; pouches are climbing the fastest on adoption rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tanjung Priok Port complex in North Jakarta anchors Indonesia's pet food distribution architecture, handling bulk ingredient imports and finished product transshipment across the archipelago's 17,000 islands.
Greater Jakarta
Millennial households in Bekasi and Tangerang satellite cities drive premium dog food adoption through modern retail channels. Indonesia's Ministry of Agriculture enforces BPI certification standards that filter non-compliant products from supermarket shelves. Cikarang industrial estates host Mars Incorporated's extrusion facilities serving the capital's 30 million metropolitan population.
East Java
Surabaya's middle-class neighborhoods exhibit accelerating cat ownership in high-rise apartments, elevating wet food demand. BPOM labeling requirements extend registration timelines for imported formulations entering through Tanjung Perak port. Malang and Sidoarjo manufacturing clusters supply private-label products to eastern Java's independent pet shop networks.
North Sumatra
Medan's emerging professional class generates nascent demand for formulated companion animal nutrition beyond traditional table-scrap feeding. The Ministry of Agriculture's feed safety protocols apply BPI certification requirements to local milling operations seeking to expand into pet food. Deli Serdang regency hosts several animal feed producers pivoting toward companion animal formulations.
South Sulawesi
Makassar's metropolitan corridor remains underserved by modern trade pet food availability, creating first-mover opportunities for cold-chain capable distributors. ASEAN feed safety harmonization initiatives streamline cross-border ingredient sourcing for regional manufacturers. The Makassar-Parepare industrial zone hosts emerging feed milling capacity targeting eastern Indonesia's underserved outer island markets.
Bali
Denpasar's expatriate and tourism-driven households sustain demand for imported premium formulations despite higher logistics costs. Import quota restrictions under Ministry of Agriculture regulations delay new international product introductions to the island. Badung regency's retail clusters concentrate veterinary clinic and specialty pet shop distribution for high-margin therapeutic diets.
Indonesia Pet Food Market Competitive Environment
Listed leaders compete with private specialists across manufacturing scale and channel access dimensions. The market exhibits moderate consolidation, with integrated agribusiness conglomerates leveraging captive protein supplies against multinational CPG subsidiaries deploying brand equity. Three archetypes dominate: poultry-integrated conglomerates with backward control over rendered protein inputs, global CPG majors with veterinary channel partnerships, and domestic mills seeking BPI compliance for modern retail entry. Competitive moves concentrate on facility certification acquisition and cold-chain infrastructure deployment to outer islands.
Within the integrated agribusiness tier, Charoen Pokphand Group and PT Japfa Comfeed Indonesia Tbk represent archetypes of poultry-protein supply control, while Mars Incorporated and Nestle Purina occupy positions exemplifying multinational brand and veterinary channel strategies. PT Central Proteina Prima Tbk and Matahari Sakti sit within the domestic specialist segment pursuing BPI certification for modern trade penetration.
| Leading Market Players |
|---|
| PT Evo Nusa Bersaudara |
| Citra Mandiri Kencana |
| Charoen Pokphand Group |
| Nestle Purina |
| Colgate-Palmolive Company (Hill's Pet Nutrition Inc.) |
| Matahari Sakti |
| Mars Incorporated |
| PT Central Proteina Prima Tbk |
| PT Japfa Comfeed Indonesia Tbk |
| Others |
Value Chain & Pricing Dynamics
High-moisture extrusion technology substitution for conventional retorting is simultaneously relocating manufacturing toward Java-based extrusion hubs and compressing wet food price premiums that historically justified import-dependent canning operations. This input shift rewards domestic producers with BPI-certified facilities while penalizing brands tethered to overseas retort supply.
Pricing Analysis
Volume-discount tiering structures separate Mars Incorporated's pallet-scale supermarket contracts from independent pet shop single-unit purchases by 18-25% landed cost differentials. Price differentiation rests on BPI certification grade and cold-chain capability, with veterinary clinic dispensing commanding steepest premiums. Pricing pressure stems from Charoen Pokphand Group's captive poultry protein supply squeezing independent margins. Economy-tier buyers in outer island markets exhibit highest price sensitivity; prescription diet purchasers in Jakarta veterinary channels show lowest.
Supply Chain Analysis
Strategic stockpiling of imported protein meals dominates inventory strategy among Java-based manufacturers seeking to buffer against Ministry of Agriculture import quota delays. Geographic supply concentration centers on Thailand and Australia for rendered poultry meals, with Brazilian soy protein concentrate as secondary anchor. Raw material dependencies include poultry by-product meal, fish meal, and corn gluten. Single-source vulnerability runs through Tanjung Priok Port's bulk handling capacity. Distribution feeds from Cikarang industrial estates through regional cold-chain distributors to outer island retail endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's pet food market fragments around channel specialization gaps, as veterinary clinic dispensing and subscription direct-to-consumer platforms create defendable niches that mass-market incumbents under-serve. Urban millennial pet owner demand for personalized nutrition protocols is splintering the historically supermarket-consolidated purchase journey.
For Market Incumbents: Compound BPI certification advantages by acquiring distressed Central Java milling assets before regulatory timelines compress further. Charoen Pokphand Group's captive protein supply and Mars Incorporated's extrusion scale must extend into cold-chain infrastructure for Makassar and Medan corridors to preempt emerging distribution specialists. Threat substitution from high-moisture extrusion formats demands R&D investment in hybrid product platforms. For New Entrants and Emerging Players: Prescription diet formulation services represent the service-layer gap where Nestle Purina's veterinary channel concentration leaves specialty therapeutic niches under-served. Target outer island metropolitan corridors with cold-chain capable direct-to-consumer platforms, leveraging subscription algorithms to capture Jakarta's time-constrained professional households before incumbents adapt. Go-to-market angle: veterinary partnership programs with personalized portion recommendations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with domestic feed mills seeking BPI compliance capital for companion animal formulation pivots. Long-term viability favors vertically integrated protein processors with regulatory affairs capacity across the 5-10 year certification escalation horizon. Acquisition target archetype: Central Java-based mills with partial BPI documentation and established outer island distribution relationships. Signal to watch: Ministry of Agriculture harmonization announcements with ASEAN feed safety protocols triggering compliance cost step-changes.| Strategic Initiative | Industry Significance |
|---|---|
| BPI Certification Acquisition | Facility compliance with Ministry of Agriculture standards secures modern trade shelf access against non-certified competitors. |
| Cold-Chain Infrastructure Deployment | Makassar and Medan distribution capabilities capture first-mover advantages in underserved outer island metropolitan corridors. |
| Veterinary Channel Partnership | Prescription diet dispensing through clinical networks commands premium pricing power and customer loyalty. |
| Subscription Platform Development | Predictive replenishment algorithms secure recurring revenue from Jakarta's dual-income professional households. |
| Backward Protein Integration | Captive poultry rendering supply insulates margin pressure from Charoen Pokphand Group's feedstock pricing power. |
Study Parameters
Desk research of customs import records, Ministry of Agriculture BPI certification registries, and BPOM product registration databases preceded structured interviews with extrusion plant managers, veterinary clinic procurement heads, modern trade category buyers, and cold-chain logistics operators. Primary fieldwork across Jakarta, Surabaya, and Medan manufacturing clusters combined with secondary validation from ASEAN feed safety harmonization documentation. Bottom-up volume modeling triangulated against top-down expenditure surveys of urban millennial pet owner households.
Variance decomposition across product type, animal species, packaging format, and channel structure informed the analytical framework over the projection horizon. Segmentation dimensions modeled include dry-wet-treat format, dog-cat-bird species, bag-can-pouch packaging, and pet owner-veterinary clinic-pet shop-online retailer channel. CAGRs derived from unit consumption trajectories and average selling price evolution across certification tiers. Industry-specific forecast inputs incorporated poultry protein meal price indices and Tanjung Priok port throughput capacity utilization.
Forecasts assume regulatory continuity in Ministry of Agriculture BPI certification and BPOM labeling regimes; material policy shifts would require re-modeling compliance cost trajectories and import permission timelines. Specific risk factors include ASEAN feed safety harmonization acceleration, poultry disease outbreaks affecting protein meal supply, and cold-chain infrastructure investment shortfalls in eastern Indonesia. Revision becomes warranted when BPI certification backlog durations exceed 18 months or outer island shipping cost differentials compress below local milling breakevens.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Accessories Market
Pet Care Products
Automatic Dog Feeder Market
Pet Care Products
Pet Daycare Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Dog Food Market
Pet Care Products
Japan Dog Food Market
Pet Care Products
Cat Litter Market
Pet Care Products
GCC Organic and Natural Pet Food Market
Pet Care Products
Cat Condos and Indoor Houses Market
Pet Care Products
Hypoallergenic Dog Food Market
Pet Care Products
UAE Dog Food Market
Pet Care Products
Europe Organic and Natural Pet Food Market
Pet Care Products
UAE Cat Food Market
Pet Care Products
Pet Odor Absorber Market
Pet Care Products
Asia-Pacific Pet Treats Market
Pet Care Products
Argentina Pet Food Market