
 GCC Cat Food Market | 2026-2036
GCC Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Cat Food Market Intelligence
Premium nutrition consulting revenue is tilting toward subscription-based feeding programs across Gulf veterinary clinics. Mars Petcare leverages its veterinary channel partnerships to anchor shelf presence in Saudi pet stores. Nestlé Purina Petcare sustains R&D intensity around renal health formulations tailored to regional cat demographics. Hill's Pet Nutrition competes through prescription diet exclusivity with licensed veterinary practitioners.
GCC cat food comprises commercially manufactured nutritional products formulated to feline dietary requirements, typically containing protein levels between 26-40% dry matter with taurine supplementation mandatory for cardiac and ocular health. Wet food segments command margin premiums due to hydration benefits in arid climates, while dry food dominates volume throughput through longer shelf stability. Online retail channels represent the fastest-growing distribution vector as pet owners across Dubai, Riyadh, and Jeddah shift toward subscription replenishment models.
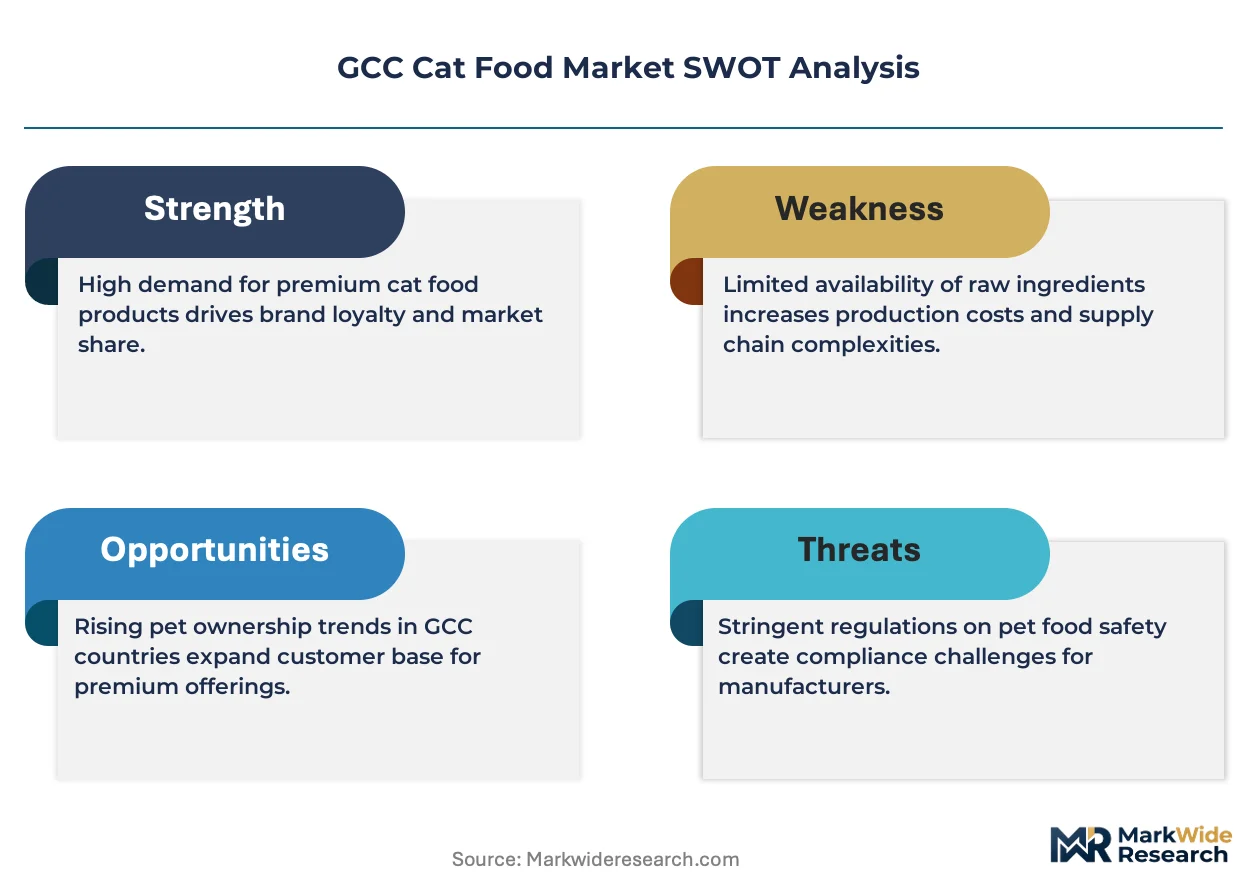
SFDA Saudi Arabia and MOHAP UAE enforce ingredient disclosure standards and import certification for animal feed products entering Gulf markets, while municipal veterinary authorities in Dubai and Abu Dhabi mandate vaccination documentation for commercially sold pet nutrition lines. Compliance with these overlapping frameworks determines market access velocity for international suppliers. Stakeholders must monitor evolving halal certification requirements for meat-based formulations as domestic production incentives expand across the Gulf.
Market Dynamics
Pet humanization across Gulf urban centers is restructuring demand toward veterinary-channel nutrition programs, compressing traditional retail margins while elevating subscription-based feeding advisory services into the core revenue model for clinics.
Growth Catalysts
- SFDA Saudi Arabia ingredient disclosure mandates:Transparency requirements are accelerating premium formulation upgrades as manufacturers compete on verifiable protein sourcing and additive-free positioning.
- MOHAP UAE import certification streamlining:Faster veterinary product clearance timelines are reducing working capital cycles for distributors serving Dubai and Abu Dhabi pet retail networks.
- Halal meat certification convergence:Domestic production incentives across Saudi Arabia and Kuwait are localizing supply chains for religiously compliant protein inputs.
Market Restraints
- Animal protein input cost volatility:Gulf dependence on imported poultry and fishmeal exposes margins to Red Sea shipping disruptions and currency fluctuations against supplier currencies.
- Veterinary channel concentration in Riyadh and Dubai:Prescription diet distribution relies on a narrow specialist clinic base, creating bottleneck risk for renal and therapeutic formulation access.
- Arid climate hydration formulation limits:Wet food production requires water-intensive processing that conflicts with municipal conservation regulations in water-stressed emirates.
Strategic Opportunities
- Kuwait and Bahrain underpenetrated retail infrastructure:Premium wet food shelf space remains underdeveloped relative to pet population growth in these smaller GCC markets.
- Veterinary telemedicine subscription bundling:Remote consultation platforms in the UAE are creating attachment points for automated nutrition replenishment programs.
- Saudi Vision 2030 local manufacturing incentives:Tax holidays and industrial zone subsidies are drawing European and Asian producers toward Jeddah and Dammam production facilities.
Industry Challenges
- Veterinary nutritionist talent scarcity:Feline clinical nutrition specialization remains concentrated in Western training programs, limiting Gulf clinic advisory capacity expansion.
- Dual halal-veterinary certification timelines:Parallel approval tracks through religious authorities and SFDA/MOHAP extend product launch cycles for meat-based therapeutic diets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Cat Food Market |
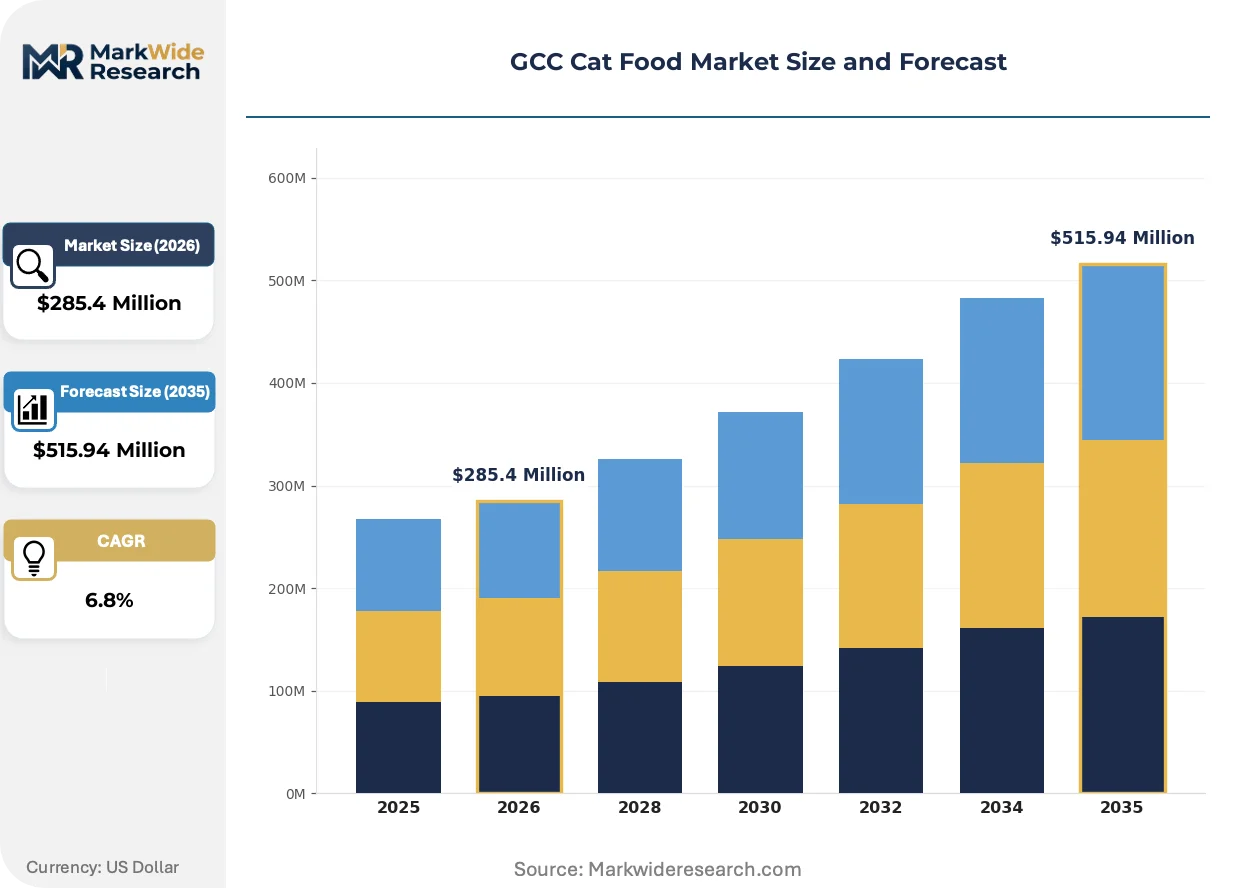
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Grain-Free Ingredient Type: Meat-Based, Fish-Based, Plant-Based, Organic Distribution Channel: Online Retail, Supermarkets, Pet Stores, Specialty Shops End User: Households, Animal Shelters, Veterinarians, Breeders |
| Companies Covered | Blue Buffalo, Diamond Pet Foods, Mars Petcare, Affinity Petcare, General Mills, Nestlé Purina Petcare, The J.M. Smucker Company, WellPet, Hill's Pet Nutrition, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Cat Food Market Strategic Shifts & Innovations
Formulation science and distribution architecture are converging around climate-adapted nutrition and digital replenishment infrastructure, with regulatory transparency becoming a competitive differentiator rather than baseline compliance.
Precision thermal processing for nutrient retention in wet food manufacturing is migrating from European suppliers to newly commissioned Saudi production lines. Domestic manufacturers in Jeddah and Riyadh are adopting low-temperature retort systems previously licensed from Italian equipment specialists. This technology transfer is compressing price premiums for high-moisture formulations while enabling localized supply of veterinary prescription diets.
SFDA Saudi Arabia and MOHAP UAE are tightening parallel import documentation requirements for pet nutrition products, forcing distributors to consolidate supplier relationships around authorized manufacturer representatives. Smaller trading houses in Dubai's Jebel Ali free zone are exiting the category as compliance costs rise. Premium brands with direct veterinary channel investments are capturing shelf space abandoned by fragmented gray-market operators.
Subscription replenishment models are displacing episodic retail purchasing among urban cat owners across Dubai, Riyadh, and Jeddah. Veterinary clinics are unbundelling feeding advisory from consultation fees, converting nutrition planning into recurring revenue streams. This behavioral shift is most pronounced in Saudi Arabia's central region, where pet insurance penetration is creating predictable reimbursement pathways for prescription diet costs.
GCC Cat Food Market Segmentation
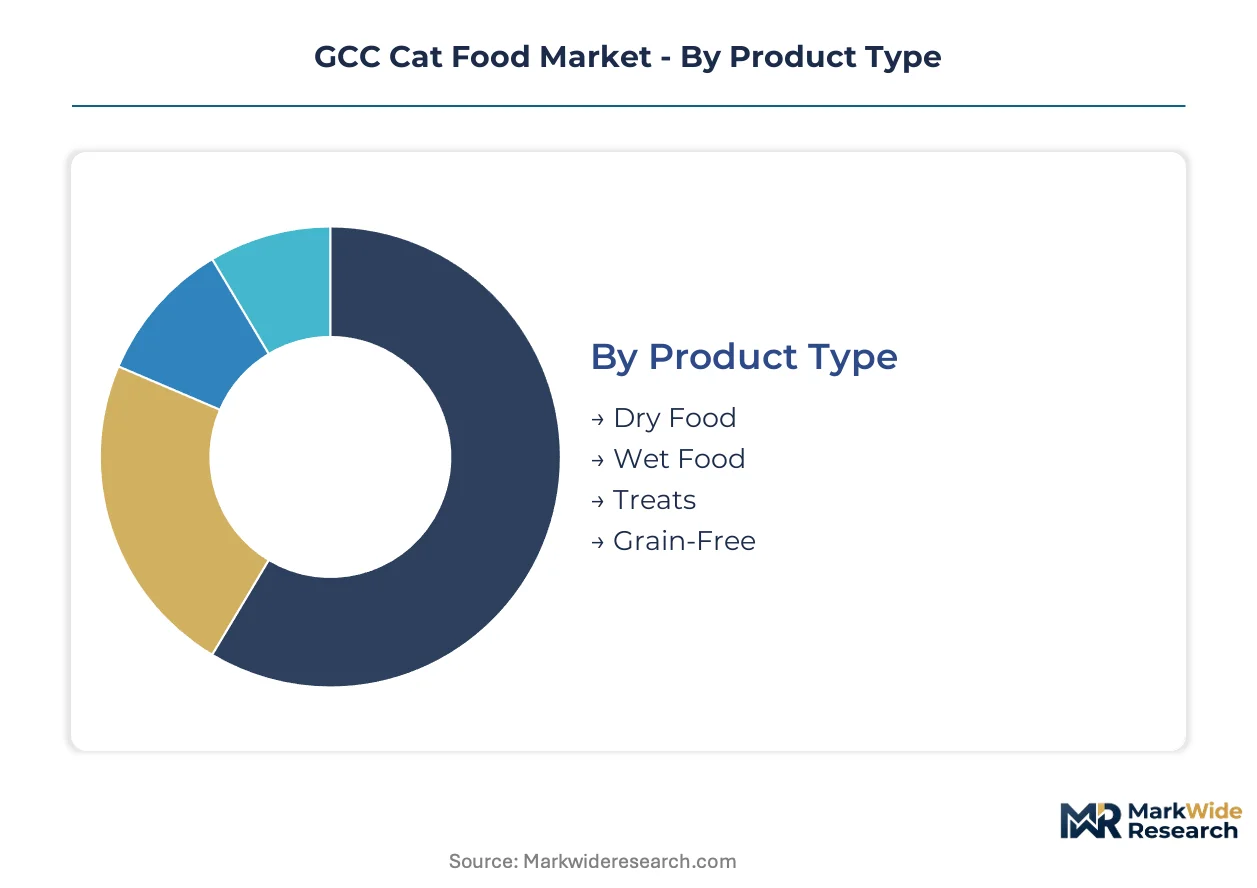
Segmentation in the GCC cat food market reveals how arid climate conditions, regulatory frameworks, and channel infrastructure differentially reward specific product formats and distribution investments across Saudi Arabia and the UAE.
Product Type:
Inventory velocity varies dramatically across formats, with wet food requiring tighter replenishment cycles due to shorter shelf windows while dry food sustains longer holding periods in climate-controlled warehousing.
- Dry Food:Kibble formulations achieve 26-40% protein content through extrusion processing, delivering shelf stability exceeding 18 months in sealed packaging. Saudi households in Riyadh and Jeddah favor bulk purchasing patterns, driven by storage capacity in larger residential units and lower per-gram cost positioning relative to hydration-focused alternatives.
- Wet Food:Canned and pouch formats contain 75-85% moisture content, addressing feline hydration deficits in high-temperature environments. Demand concentrates among UAE veterinary clinics in Dubai and Abu Dhabi, where prescription renal and urinary health formulations command recurring subscription revenue through clinic-anchored replenishment programs.
- Treats:Functional dental and hairball formulations serve intermittent reward occasions across Gulf urban households.
- Grain-Free:Alternative carbohydrate sourcing from sweet potato and legume inputs targets digestive sensitivity concerns among premium-purchasing cat owners.
Dry food dominates installed base volume across GCC retail channels. Wet food is where margin expansion and veterinary channel penetration concentrate.
Ingredient Type:
Cost tiering separates commodity protein sourcing from certified inputs, with halal compliance and organic accreditation commanding substantial price premiums in Saudi Arabia's religiously observant consumer base.
- Meat-Based:Poultry and red meat proteins supply essential taurine for cardiac function, with halal slaughter certification mandatory for market access in Saudi Arabia and Kuwait. SFDA Saudi Arabia enforces chain-of-custody documentation for meat inputs, extending formulation launch timelines but insulating compliant manufacturers from gray-market competition.
- Fish-Based:Tuna, salmon, and whitefish meals deliver omega-3 fatty acids for coat health and inflammatory management. UAE pet stores in Dubai Mall and Mall of the Emirates anchor shelf presence for imported Thai and European fish-based premium lines, supported by MOHAP UAE's streamlined veterinary product clearance pathways.
- Plant-Based:Soy and pea protein concentrates serve cost-sensitive segments and vegetarian household preferences.
- Organic:Certified additive-free formulations with EU or USDA organic accreditation target expatriate communities in Abu Dhabi and Doha.
Meat-based formulations retain volume leadership across GCC markets. Fish-based lines are gaining share fastest in UAE premium retail.
Distribution Channel:
Customer acquisition economics diverge sharply between digital subscription models with lifetime value optimization and transactional retail with high rent burdens in Gulf commercial real estate.
- Online Retail:E-commerce platforms and veterinary telemedicine bundling enable automated replenishment with predictive shipping algorithms. Saudi Arabia's central region demonstrates the strongest subscription attachment rates, where pet insurance reimbursement pathways reduce price sensitivity for recurring prescription diet purchases.
- Supermarkets:Hypermarket chains including Carrefour and Lulu anchor mass-market dry food distribution with promotional slotting fees.
- Pet Stores:Independent and chain specialty retailers in Jeddah and Riyadh provide tactile product evaluation and staff consultation for first-time premium purchasers.
- Specialty Shops:Grooming-salon-adjacent boutiques in Dubai's Jumeirah district serve high-net-worth households with imported limited-ingredient diets.
Supermarkets and pet stores command current transaction volume. Online retail is climbing the fastest as logistics infrastructure matures.
End User:
Procurement authority and volume scale separate individual household purchasing from institutional buyers with veterinary oversight and population-scale nutrition requirements.
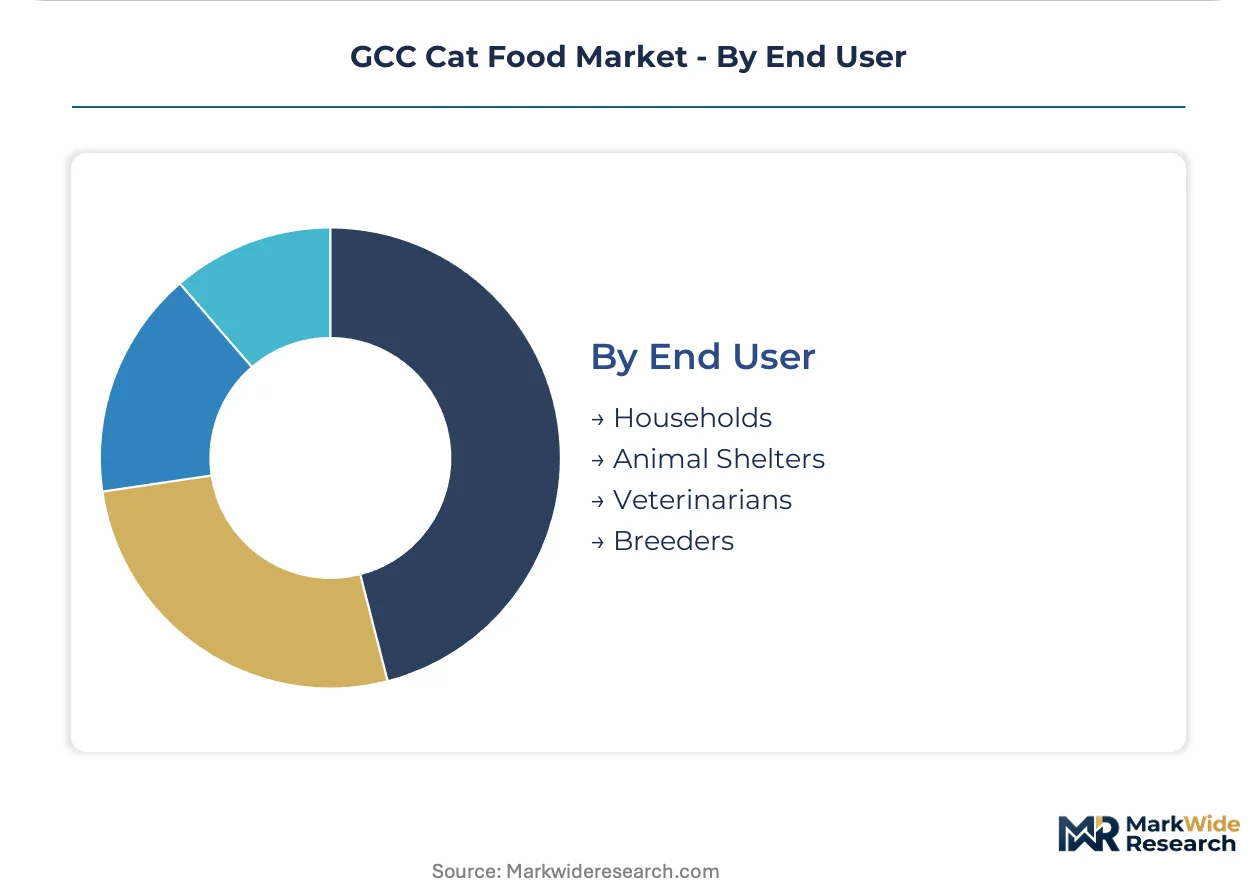
- Households:Individual cat owners across Saudi Arabia and the UAE drive premiumization through pet humanization behaviors, with single-cat and multi-cat households segmenting into mass-market and super-premium tiers based on disposable income and veterinary relationship depth.
- Veterinarians:Licensed practitioners in Riyadh and Dubai prescription-diet-exclusive partnerships with Hill's, Royal Canin, and Purina Pro Plan, converting clinical authority into captive nutrition revenue streams through clinic-dispensed therapeutic formulations.
- Animal Shelters:Municipal and private shelter operations in Kuwait and Bahrain source economy-format dry food through bulk tender processes.
- Breeders:Cattery operations in the UAE's Al Ain region prioritize growth-stage kitten formulations and reproductive health nutrition.
Households represent the deepest installed demand base. Veterinary channels are where pricing power and retention economics concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity among GCC cat food buyers varies sharply across the six member states. Saudi households demonstrate the strongest volume-driven purchasing patterns. Kuwait and Bahrain consumers exhibit markedly lower price elasticity for premium formulations.
Saudi Arabia
Riyadh and Jeddah anchor the region's largest installed base of cat-owning households, with bulk dry food purchasing dominating residential storage patterns. SFDA ingredient disclosure mandates are compressing launch timelines for imported formulations while accelerating domestic manufacturing investments in Jeddah's industrial zones. Dammam production facilities are capturing technology transfer from European thermal processing specialists.
United Arab Emirates
Dubai and Abu Dhabi veterinary clinics command the Gulf's highest prescription diet attachment rates, with subscription replenishment models displacing retail purchasing among insured pet owners. MOHAP import certification streamlining is reducing distributor working capital cycles for therapeutic nutrition lines. Jebel Ali free zone consolidation is eliminating gray-market trading houses as compliance costs escalate.
Kuwait
Retail infrastructure for premium wet food remains underdeveloped relative to pet population growth in Kuwait City and surrounding governorates. Halal meat certification convergence with veterinary approval tracks is extending product launch cycles for therapeutic diets. Domestic production incentives are drawing Asian equipment suppliers toward industrial zone partnerships.
Qatar
Doha's expatriate-heavy household base sustains demand for EU-accredited organic formulations with limited local manufacturing presence. Municipal veterinary authorities mandate vaccination documentation for commercially distributed nutrition lines. Specialty retail in West Bay and The Pearl districts serves high-net-worth segments with imported limited-ingredient diets.
Bahrain
Manama's compact urban geography supports rapid last-mile delivery experimentation for subscription cat food services. Regulatory frameworks align with Saudi SFDA standards while maintaining independent import documentation requirements. Retail consolidation in Seef and City Centre districts is reducing independent pet store count.
GCC Cat Food Market Key Industry Players
Multinational nutrition conglomerates and specialized therapeutic diet manufacturers split the GCC cat food market along channel lines. Mars Petcare and Nestlé Purina Petcare anchor mass-market and premium retail presence through veterinary partnerships and hypermarket distribution networks. Hill's Pet Nutrition occupies the prescription diet tier through exclusive licensed practitioner relationships. Competitive dynamics center on manufacturing localization under Saudi Vision 2030 incentives and veterinary telemedicine platform bundling.
Within the multinational conglomerate tier, Mars Petcare and Nestlé Purina Petcare exemplify scale-driven market presence across Saudi and UAE retail channels. Hill's Pet Nutrition occupies the clinical nutrition archetype through prescription exclusivity arrangements with Riyadh and Dubai veterinary specialists. Among mid-scale specialists, Blue Buffalo and WellPet represent premium-natural positioning targeting organic-accreditation-seeking expatriate communities in Abu Dhabi and Doha.
| Leading Market Players |
|---|
| Blue Buffalo |
| Diamond Pet Foods |
| Mars Petcare |
| Affinity Petcare |
| General Mills |
| Nestlé Purina Petcare |
| The J.M. Smucker Company |
| WellPet |
| Hill's Pet Nutrition |
| Others |
Cost & Logistics Intelligence
Red Sea shipping disruptions for poultry and fishmeal imports determine both pricing tier spreads and supply chain shape across GCC cat food markets. Manufacturers absorbing currency volatility against supplier currencies must choose between margin compression at the premium tier or volume sacrifice in economy segments.
Pricing Analysis
Subscription-based feeding advisory programs drive lifetime value for veterinary clinics in Riyadh and Dubai. Pricing stratifies across premium therapeutic formulations, standard retail lines, and economy bulk formats based on certification grade and after-sales nutrition consulting depth. Cost compression in economy dry food is intensifying because Saudi households prioritize volume purchasing over formulation sophistication. Mass-market supermarket buyers exhibit highest price sensitivity; insured pet owners through veterinary channels demonstrate lowest elasticity.
Supply Chain Analysis
European and Thai contract manufacturers hold dominant capacity for wet food thermal processing equipment licensed to Saudi production lines. Supply concentrates in Thailand for fishmeal inputs, Europe for precision retort machinery, and domestic Saudi facilities for halal-certified poultry protein. Raw material dependencies include imported fishmeal, pharmaceutical-grade taurine supplements, and specialized packaging films. Single-source vulnerability runs through Red Sea logistics corridors for Thai fishmeal shipments. Distribution runs through veterinary clinic networks for prescription diets and hypermarket chains for mass-market dry food.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC cat food market functions as a defensive-moat story anchored in regulatory entrenchment. SFDA and MOHAP certification requirements create switching costs that protect incumbent positions against gray-market competition.
For Market Incumbents: Entrench through exclusive prescription diet partnerships with licensed veterinary practitioners in Riyadh and Dubai, converting clinical authority into captive replenishment revenue. Deepen backward integration into halal-certified poultry processing within Saudi Vision 2030 industrial zones to offset currency exposure against European and Thai supplier currencies. Expand manufacturing footprint in Jeddah and Dammam to compress price premiums for high-moisture formulations. For New Entrants and Emerging Players: Underdeveloped premium wet food shelf space in Kuwait City and Manama represents the most penetrable entry point for mid-scale specialists with halal certification capabilities. Telemedicine-anchored subscription bundling in UAE veterinary clinics offers a direct-to-consumer angle bypassing hypermarket slotting fee barriers. Target Asian equipment partnerships for domestic production incentives in Kuwaiti industrial zones. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive halal protein supply. Long-term viability over a five-to-ten-year window rests on regulatory compliance infrastructure rather than brand equity alone. Acquisition targets should demonstrate dual SFDA-MOHAP approval track records and established veterinary channel relationships. Watch for Jebel Ali free zone exits by gray-market trading houses as early signals of authorized distributor capture.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Exclusivity Agreements | Prescription diet partnerships with Riyadh and Dubai clinics lock in recurring revenue streams. |
| Domestic Manufacturing Localization | Saudi Vision 2030 tax holidays in Jeddah industrial zones reduce import dependency and currency exposure. |
| Halal Certification Infrastructure Investment | Parallel religious authority and SFDA approval tracks extend competitive moats against unlicensed competitors. |
| Telemedicine Platform Integration | UAE remote consultation bundling creates automated nutrition replenishment attachment points. |
| Subscription Replenishment Model Deployment | Predictive shipping algorithms through Saudi pet insurance reimbursement pathways reduce customer acquisition costs. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with veterinary nutritionists, SFDA regulatory affairs specialists, pet retail category managers, and halal certification auditors; alongside secondary validation through SFDA ingredient disclosure filings, MOHAP import certification records, Saudi customs trade data, and veterinary clinic procurement databases. Bottom-up volume estimates from product format segmentation were triangulated against top-down market sizing from distributor revenue disclosures.
Forecast inputs include protein sourcing cost trajectories, regulatory approval timeline distributions, and channel shift velocities across the projection horizon. Segmentation dimensions modeled encompass product format, ingredient certification tier, distribution channel, and end-user procurement authority. CAGRs were derived from regression analysis of historical volume trends against pet population growth and disposable income elasticity coefficients. Climate-adapted formulation adoption curves and veterinary telemedicine penetration rates served as industry-specific forecast inputs.
Practitioners should monitor Red Sea shipping disruption frequency, SFDA halal certification requirement expansions, and Jebel Ali free zone trading house exit rates for early signals of forecast revision. Quarterly review of veterinary channel subscription attachment rates and domestic manufacturing incentive utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
Cat Massage Comb Market
Pet Care Products
Aquarium Supplies Market
Pet Care Products
US Pet Boarding Market
Pet Care Products
Pet Collar Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
Pet Hotels Market
Pet Care Products
Dog Hats Market
Pet Care Products
Dog Pen Market
Pet Care Products
South America Pet Food Market
Pet Care Products
Smart Pet Supply Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Pet Noise Anxiety Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Netherlands Pet Food Market