
 Plastic Additives Market | 2026-2036
Plastic Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Additives Market Analysis
Engineering-grade additive specifications is unwinding commoditization pressures across the plastic additives sector. BASF SE leverages its integrated antioxidant and light stabilizer portfolio to anchor European automotive supply chains. Evonik Industries AG specializes in high-performance processing aids that dominate medical-grade polymer applications. Dow Inc. controls North American distribution networks for flame retardant masterbatches, extending its reach into construction end uses.
Plastic additives encompass chemical substances blended into polymer matrices at concentrations typically ranging from 0.1% to 50% by weight to modify processing characteristics, durability, or functional performance. These compounds serve industrial purposes including thermal stabilization during extrusion, plasticization of rigid PVC for flexible applications, and flame suppression in electronic housings. Stabilizers represent the most mature margin pool, with producers concentrating on hindered amine light stabilizers for agricultural film longevity. Flame retardants compete for fastest-growing status as electronics manufacturers face stricter ignition-resistance mandates. Specialty-grade formulations command premium positioning due to customer-specific certification requirements in healthcare and aerospace channels.
REACH in Europe, RoHS directives, and EPA chemical review frameworks collectively restrict legacy phthalate plasticizers and halogenated flame retardants, redirecting formulation investment toward bio-based and phosphorus alternatives. FDA food-contact regulations and ECHA substance authorization processes create divergent compliance pathways that fragment product portfolios by geography. Stakeholders must monitor regulatory pre-announcements in multiple jurisdictions to anticipate reformulation cycles before supply contracts lock in additive specifications.
Market Dynamics
Automotive lightweighting mandates are compressing formulation cycles for high-performance stabilizers and flame retardants, forcing additive suppliers to synchronize R&D pipelines with OEM platform launches rather than traditional commodity supply rhythms.
Growth Catalysts
- REACH substance authorization:European chemical frameworks are accelerating substitution of legacy halogenated flame retardants, redirecting formulation investment toward phosphorus-based alternatives in electronics housings.
- Electric vehicle battery enclosures:Thermal runaway protection standards are intensifying demand for intumescent coatings and ceramic additives across automotive supply chains.
- China's dual carbon goals:Domestic polymer processors face mounting pressure to source bio-based plasticizers, creating localized supply gaps that specialty additive producers are racing to fill.
Market Restraints
- Feedstock volatility:Propylene oxide and phthalic anhydride price swings compress margin predictability for plasticizer manufacturers serving construction and flooring segments.
- Supply concentration:Hindered amine light stabilizer production clusters in the Rhine-Ruhr industrial corridor, exposing automotive film customers to single-point disruption risks from regional energy shortages.
- Technical ceiling:Current bio-based alternatives fail to match the thermal stability of petroleum-derived antioxidants above 180°C, limiting adoption in under-the-hood automotive applications.
Strategic Opportunities
- Medical-grade polymer channels:FDA 21 CFR compliance requirements for implantable devices create defensible niches for additive producers willing to absorb multi-year certification timelines.
- India's PLI scheme for specialty chemicals:Domestic manufacturing incentives are luring masterbatch producers to establish localized compounding facilities for agricultural film and packaging.
- AI-driven formulation platforms:Machine learning tools are compressing experimental design cycles for custom stabilizer blends, enabling faster response to OEM specification changes.
Industry Challenges
- Regulatory fragmentation:Divergent EPA chemical review timelines versus ECHA authorization processes force additive suppliers to maintain parallel product portfolios with incompatible compliance documentation.
- Specialized talent scarcity:Polymer chemists with cross-functional expertise in both regulatory toxicology and reactive extrusion command premium compensation, constraining mid-tier producer expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Additives Market |
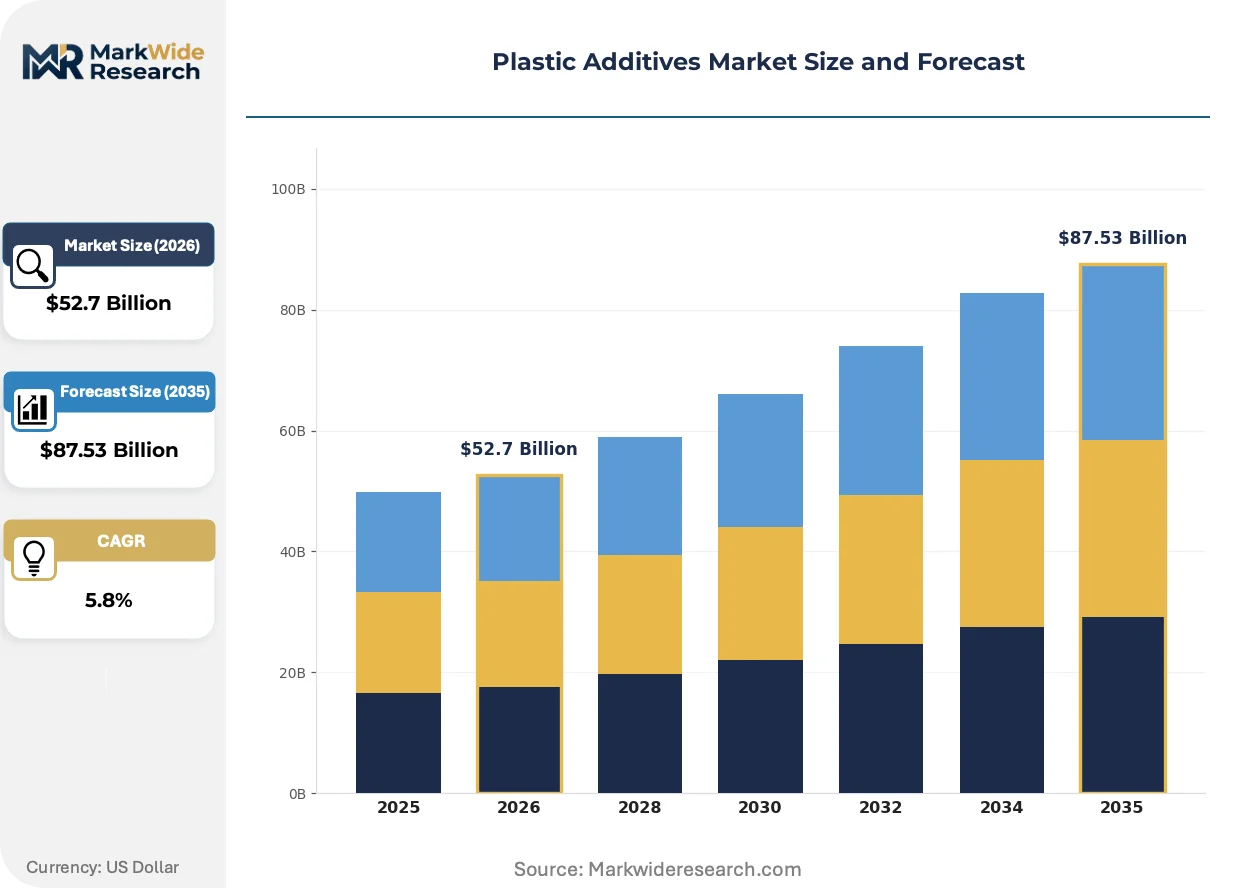
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $87.53 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stabilizers, Plasticizers, Fillers, Flame Retardants Grade: Commodity, Engineering, Specialty, High-Performance Application: Automotive, Construction, Electronics, Packaging End Use Industry: Consumer Goods, Healthcare, Agriculture, Others |
| Companies Covered | BASF SE, Clariant AG, Dow Inc., Evonik Industries AG, Songwon Industrial Co., Ltd., LANXESS AG, Kaneka Corporation, Nouryon, Albemarle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Additives Market Emerging Trajectories
Reactive extrusion technologies are rewriting compounding economics, while regulatory pre-announcement monitoring becomes a core competitive capability. Formulation-as-a-service models are emerging to capture value from specification complexity.
Nucleating agents based on sorbitol derivatives are miniaturizing crystallite structures in polypropylene, enabling thinner-wall packaging without sacrificing stiffness. Food-contact brand owners in Germany and the Netherlands are adopting these systems at compressed trial-to-production cycles. The technology is miniaturizing material usage per unit, directly compressing resin demand volumes across European dairy packaging.
REACH Annex XIV authorization lists are systematically removing medium-chain chlorinated paraffins from rubber and adhesive applications, forcing compounders to validate alternative plasticizer systems under compressed substitution deadlines. Automotive sealant manufacturers face the most acute compliance pressure, with several Tier 1 suppliers accelerating bio-based ester trials to maintain European OEM qualification status.
Specification-driven procurement is consolidating buying power among multinational polymer processors, compressing spot-market volumes for standard-grade additives. Masterbatch distributors in the US Midwest are responding by unbundling technical service from product supply, selling formulation consulting as standalone recurring revenue. The shift is most visible in flexible PVC compounding for medical tubing, where hospital group purchasing organizations now mandate pre-qualified additive packages.
Plastic Additives Market Segmentation
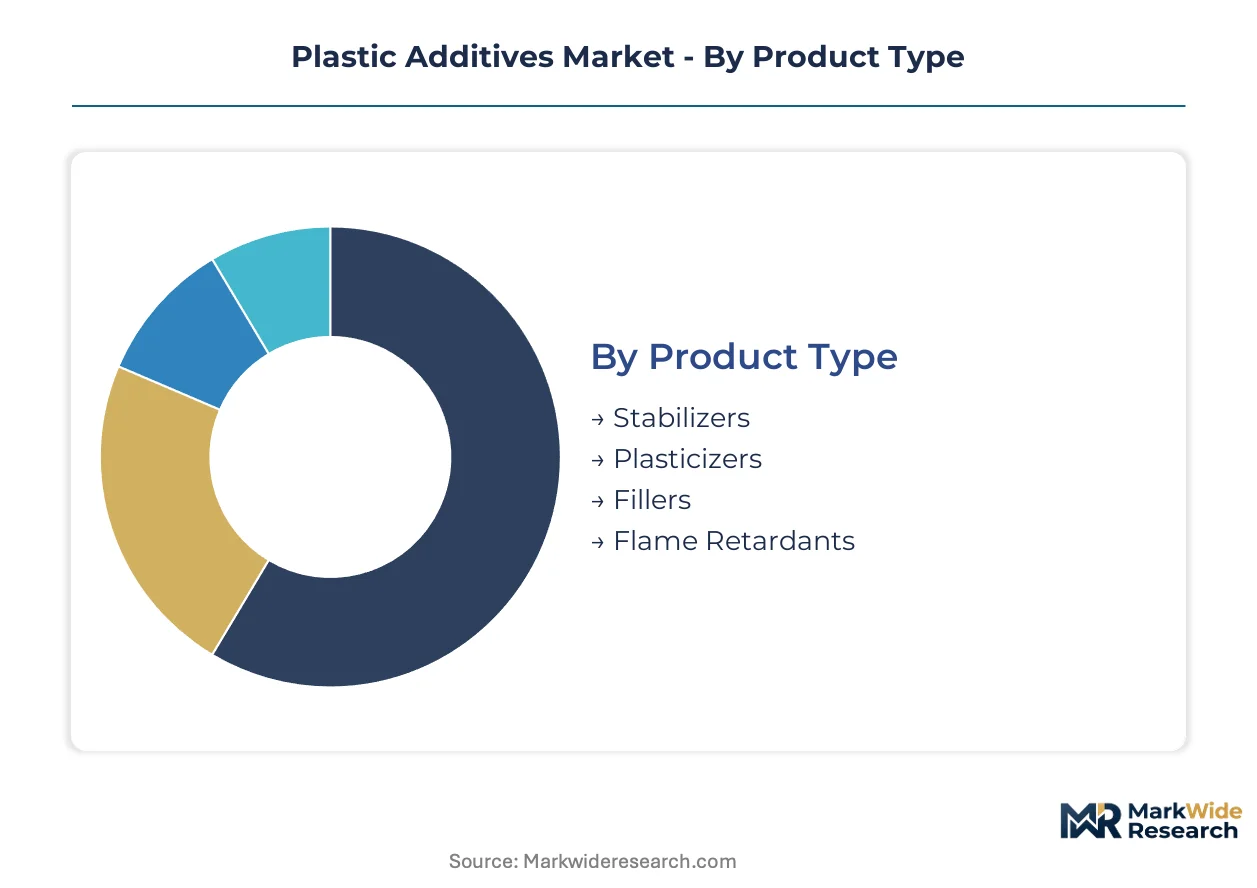
Segmentation in plastic additives reflects divergent compliance burdens and performance specifications that fragment supply contracts. Formulators must maintain parallel product portfolios to satisfy REACH substance authorizations, FDA food-contact rules, and China's GB standards simultaneously.
Product Type:
REACH Annex XIV restrictions on halogenated chemistries and EPA chemical review timelines create divergent formulation requirements across each product class.
- Stabilizers:Hindered amine light stabilizers and antioxidant blends prevent thermal degradation during extrusion and UV-induced embrittlement in outdoor applications. Demand concentrates in agricultural film production across Germany and the US Midwest, where multiseason durability specifications exceed 36 months of field exposure. REACH authorization deadlines for legacy phenolic antioxidants are forcing reformulation toward phosphite-based alternatives in European automotive supply chains.
- Flame Retardants:Intumescent, phosphorus-based, and mineral filler systems suppress ignition in electronic housings and battery enclosures. Electric vehicle thermal runaway protection standards in China and Germany are accelerating specification changes faster than traditional automotive platform cycles. RoHS directives and state-level restrictions in California and Washington are compressing the transition timeline from halogenated to halogen-free systems.
- Plasticizers:Phthalate and bio-based ester compounds modify PVC flexibility for medical tubing, flooring, and cable insulation. FDA 21 CFR compliance requirements for implantable devices create defensible niches for specialty-grade producers willing to absorb multi-year certification timelines.
- Fillers:Calcium carbonate, talc, and glass fiber reinforcements reduce resin costs and improve mechanical properties in polypropylene and nylon compounds. Construction applications in the US Sun Belt and Chinese provincial infrastructure projects drive volume throughput.
Stabilizers handle the majority of throughput; flame retardants are expanding most quickly on share.
Grade:
Customer certification requirements stratify margin pools across four distinct performance tiers.
- Specialty:Custom-formulated additive packages for medical devices and aerospace composites command premium positioning due to FDA, EMA, and ISO 13485 compliance documentation. Hospital group purchasing organizations now mandate pre-qualified additive systems, consolidating procurement among validated suppliers.
- Engineering:Performance-optimized stabilizers and processing aids serve automotive under-the-hood applications requiring thermal stability above 180°C. OEM platform launches in Germany, Japan, and the US are compressing formulation cycle times from 24 months to 12 months.
- High-Performance:Ceramic additives and intumescent coatings for EV battery enclosures meet emerging thermal runaway protection standards. China's MIIT and Germany's KBA are issuing divergent test protocols that fragment product development roadmaps.
- Commodity:Standard-grade antioxidants and plasticizers serve construction and packaging applications where price sensitivity dominates procurement decisions. Feedstock volatility in propylene oxide and phthalic anhydride compresses margin predictability.
Commodity grade moves the highest tonnage; specialty grade captures the steepest margin expansion.
Application:
End-use specifications dictate additive selection through divergent durability, ignition-resistance, and regulatory requirements.
- Automotive:Lightweighting mandates accelerate demand for nucleating agents in thin-wall polypropylene and flame retardants in battery enclosures. OEM qualification status in Stuttgart, Detroit, and Shanghai requires synchronized R&D pipelines across three regulatory jurisdictions.
- Electronics:RoHS and REACH restrictions on legacy halogenated chemistries redirect investment toward phosphorus-based alternatives in laptop housings and server chassis. Taiwan and South Korean contract manufacturers are consolidating buying power through specification-driven procurement.
- Construction:PVC siding, roofing membranes, and flooring applications consume plasticizers and UV stabilizers with regional building code variations. US state-level restrictions on phthalates in California and New York fragment product portfolios.
- Packaging:Nucleating agents based on sorbitol derivatives enable thinner-wall dairy containers without stiffness loss. German and Dutch brand owners are adopting these systems at compressed trial-to-production cycles.
Construction absorbs the largest additive volumes; electronics is climbing the fastest on specification intensity.
End Use Industry:
Regulatory stringency and certification timelines stratify customer profitability across four vertical channels.
- Healthcare:FDA 21 CFR and EMA medical device regulations mandate extractables and leachables testing for implantable polymers. Multi-year qualification timelines create defensible competitive moats for additive producers with established compliance documentation.
- Consumer Goods:Food-contact regulations from FDA, EFSA, and China's NMPA require divergent substance approvals for packaging additives. Brand owner sustainability commitments are accelerating bio-based plasticizer trials beyond regulatory minimums.
- Agriculture:Multiseason agricultural film specifications in the US Great Plains and Chinese provincial farming regions demand UV stabilizer performance exceeding 36 months. REACH authorization for hindered amine light stabilizers maintains supply continuity in European markets.
- Others:Industrial textiles, marine applications, and recreational equipment consume niche additive formulations with specialized weathering and ignition-resistance requirements.
Consumer goods channels move the highest standard-grade volumes; healthcare delivers the most durable margin structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net additive trade flows concentrate in chemical-exporting economies with integrated polymer value chains, while import-dependent regions absorb specialty formulations through distributor networks. Germany, China, and the United States generate surplus production capacity, whereas India and Southeast Asian markets deepen reliance on formulated masterbatch imports.
China
Domestic polymer processors face mounting pressure to source bio-based plasticizers under the country's dual carbon goals. MIIT thermal runaway protection standards for EV battery enclosures are accelerating demand for ceramic additives and intumescent coatings. The Yangtze River Delta cluster around Shanghai anchors specialty-grade compounding capacity for automotive supply chains.
Germany
REACH Annex XIV authorization deadlines are forcing automotive sealant manufacturers to validate alternative plasticizer systems under compressed substitution timelines. The KBA issues divergent test protocols for EV battery safety that fragment product development roadmaps. The Rhine-Ruhr industrial corridor concentrates hindered amine light stabilizer production, exposing customers to single-point disruption risks from regional energy shortages.
United States
State-level restrictions on phthalates in California and Washington are compressing the transition timeline from halogenated to halogen-free flame retardant systems. EPA chemical review timelines force additive suppliers to maintain parallel product portfolios with incompatible compliance documentation. The US Midwest masterbatch distributors are unbundling technical service from product supply, selling formulation consulting as standalone recurring revenue.
India
The PLI scheme for specialty chemicals is luring masterbatch producers to establish localized compounding facilities for agricultural film and packaging. Domestic polymer processors face feedstock volatility in propylene oxide and phthalic anhydride that compresses margin predictability. Maharashtra and Gujarat industrial corridors are absorbing the majority of new capacity investments in nucleating agent production.
Japan
METI industrial standards for electronic housings are redirecting investment toward phosphorus-based flame retardant alternatives. Polymer chemists with cross-functional expertise in regulatory toxicology and reactive extrusion command premium compensation, constraining mid-tier producer expansion. The Kansai region around Osaka maintains concentrated demand for medical-grade polymer additives serving implantable device manufacturers.
Plastic Additives Market Vendor Landscape
Listed leaders compete with private specialists across formulation certification depth and geographic coverage. The vendor base stratifies into three tiers: integrated chemical conglomerates with full antioxidant-to-flame-retardant portfolios, mid-scale compounders dominating regional masterbatch distribution, and niche specialists capturing medical-grade and aerospace certification premiums. Strategic moves center on backward integration into hindered amine light stabilizer intermediates and AI-driven formulation platforms that compress experimental design cycles.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify archetypes of European-listed conglomerates anchoring automotive supply chains through REACH-compliant stabilizer portfolios. Dow Inc. occupies a position representing North American scale-driven players controlling distribution networks for flame retardant masterbatches. Songwon Industrial Co., Ltd. sits within the Asia-Pacific specialist segment, reflecting private industrial group structures concentrated on light stabilizer technology. These three entities represent divergent strategic postures: full-portfolio integration, regional distribution dominance, and technology-specific specialization.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Dow Inc. |
| Evonik Industries AG |
| Songwon Industrial Co., Ltd. |
| LANXESS AG |
| Kaneka Corporation |
| Nouryon |
| Albemarle Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Rhine-Ruhr hindered amine light stabilizer plants anchors both supply concentration and price floors across European automotive supply chains, compressing margin buffers when regional energy shortages trigger force majeure clauses.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across specialty, engineering, and commodity tiers. Price differentiation rests on REACH certification tier and volume scale, with FDA 21 CFR medical-grade packages commanding substantial premiums over standard construction grades. Cost compression in commodity plasticizers is intensifying because feedstock volatility in propylene oxide and phthalic anhydride squeezes producer margins. Construction and flooring segments exhibit highest price sensitivity, while healthcare channels absorb premium positioning with minimal procurement pushback.
Supply Chain Analysis
Inventory buffers for hindered amine light stabilizer intermediates stretch to twelve weeks, exposing automotive film customers to disruption cascades. Production gravity centers on Germany, China, and the United States, with the Yangtze River Delta and Rhine-Ruhr corridors anchoring specialty-grade capacity. Raw material flows draw from propylene oxide, phthalic anhydride, and phosphorus-based flame retardant precursors. Single-source vulnerability concentrates in the Rhine-Ruhr corridor where regional energy shortages threaten supply continuity. Distribution runs through masterbatch distributors unbundling technical service from product supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation-as-a-service revenue layers are expanding faster than hardware tonnage, converting technical consulting into recurring subscription structures that outpace traditional additive sales growth.
For Market Incumbents: Compound defensive positioning through backward integration into hindered amine light stabilizer intermediates and captive supply of phosphorus-based flame retardant precodes. REACH authorization deadlines for legacy chemistries threaten margin pools, making certification investment in bio-based ester alternatives the priority lever. Capacity addition in India's Maharashtra and Gujarat corridors captures PLI scheme incentives before localized competition intensifies.
For New Entrants and Emerging Players: Differentiate on AI-driven formulation platforms that compress experimental design cycles for custom stabilizer blends. India's agricultural film segment presents the most penetrable white space, with domestic processors seeking localized compounding alternatives to imported masterbatches. A specification-driven go-to-market angle targeting hospital group purchasing organizations bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among masterbatch distributors unbundling technical service from product supply. Long-term viability over the next decade hinges on regulatory compliance depth rather than commodity scale. Acquisition targets should display established FDA 21 CFR and REACH Annex XIV documentation archives. The signal to watch is MIIT thermal runaway protection standard revisions that redirect EV battery enclosure specification cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HALS Intermediates | Rhine-Ruhr producers secure captive supply against regional energy disruption risks. |
| AI-Driven Formulation Platform Deployment | Machine learning tools compress OEM specification response cycles from months to weeks. |
| Medical-Grade Certification Investment | FDA 21 CFR compliance creates defensible moats in implantable polymer channels. |
| India PLI Scheme Capacity Buildout | Maharashtra and Gujarat corridors absorb agricultural film compounding demand locally. |
| Formulation-as-a-Service Unbundling | US Midwest distributors convert technical consulting into standalone recurring revenue streams. |
Methodological Framework
Two parallel data streams informed the analysis: structured conversations with polymer plant managers, automotive Tier 1 procurement leads, and masterbatch distribution partners; and secondary validation through customs/trade data, ACC and Cefic industry reports, and SEC 10-K chemical segment disclosures. Bottom-up volume modeling triangulated against top-down value estimates derived from production capacity announcements and regional pricing benchmarks.
Across the analysis window, the forecasting framework segmented projections by grade tier, end-use industry, and regional production hub. CAGRs emerged from regression analysis of historical volume trajectories and elasticity-adjusted demand drivers. Industry-specific inputs included REACH authorization timelines, MIIT thermal runaway test protocol developments, and hospital group purchasing organization contract renewal cycles.
Material uncertainties — feedstock price volatility, regulatory pre-announcement timing, and OEM platform launch delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about substitution rates for halogenated flame retardants and bio-based plasticizer performance ceilings. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Sodium Acetate Trihydrate Market
Additives
Driveline Additives Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Global Pearlizing Agent Market
Additives
Global Corrosion Inhibitor Market
Additives
Hydroxyethyl Cellulose Market
Additives
Europe Anti-Caking Market
Additives
Global Formulation Additives Market
Additives
Anti-Wear Additives Market
Additives
Ascorbyl Stearate Market
Additives
Defoaming Coating Additives Market
Additives
Gluconic Acid and Derivatives Market
Additives
Americas Coating Additives Market
Additives
Cetane Improver Additives Market
Additives
Polysaccharides and Oligosaccharides Market
Additives
Global Hindered Amine Light Stabilizers Market