
 Medium Chain Triglyceride (MCT) Food Market | 2026-2036
Medium Chain Triglyceride (MCT) Food Market Size, Share, and Industry Trends Forecast 2026-2036
Medium Chain Triglyceride (MCT) Food Market Insights
Southeast Asian palm kernel oil producers is consolidating MCT supply chains through backward integration into fractionation and esterification assets. BASF SE leverages its Ludwigshafen specialty lipids complex to sustain pharmaceutical-grade MCT output for medical food clients. Croda International Plc anchors European demand with high-purity C8-C10 concentrates tailored to ketogenic formulations. Musim Mas Holdings dominates upstream feedstock flows from Indonesian oleochemical operations, while KLK Oleo competes on Malaysian plantation-to-refinery traceability.
Medium chain triglycerides comprise fatty acids with six to twelve carbon atoms, typically derived from fractional distillation of coconut or palm kernel oil to isolate caprylic (C8) and capric (C10) acids before re-esterification with glycerol; these structured lipids bypass standard lymphatic absorption, delivering rapid hepatic metabolism for energy-dense food systems. Powder formats lead volume in sports nutrition dry blends where shelf stability and instant solubility command formulation preference, while oil variants capture premium positioning in ketogenic and medical food channels where purity certificates and fatty acid ratios determine procurement decisions. Dietary supplements occupy the deepest margin pools through direct-to-consumer subscription models, whereas food and beverage applications extend into functional creamers and meal replacements with cleaner-label positioning.
FDA GRAS self-affirmation pathways and EFSA novel food consultations govern MCT ingredient access in North America and Europe, with both agencies scrutinizing lipid oxidation markers and residual solvent limits in concentrated formats. China's SAMR imposes stricter import registration for MCT oils claiming therapeutic utility, creating divergent compliance burdens for cross-border suppliers. Stakeholders must monitor evolving ketogenic health claims regulation and carbon disclosure requirements for tropical oil sourcing as these dual pressures reshape supplier qualification criteria and procurement is shifting toward verified sustainable feedstock documentation.
Market Dynamics
Fractionation technology upgrades at Southeast Asian oleochemical complexes are compressing C8-C10 isolation costs, enabling broader MCT penetration beyond premium ketogenic channels into mass-market functional foods and sports nutrition.
Growth Catalysts
- Ketogenic diet protocols:Clinical adoption of medical ketogenic therapies for epilepsy management and metabolic syndrome treatment is expanding institutional procurement of pharmaceutical-grade MCT oils.
- EFSA novel food consultations:Streamlined approval pathways for C8-C10 concentrates in EU functional foods are accelerating product launch timelines for European formulators.
- Sports nutrition dry blends:Powder MCT formats with instant solubility profiles are capturing formulation preference in pre-workout and recovery product lines.
Market Restraints
- Palm kernel oil feedstock volatility:Indonesian and Malaysian plantation yields fluctuate with El Niño weather patterns, creating raw material cost instability for fractionation operators.
- Upstream supply concentration:Southeast Asian oleochemical complexes control over 70% of global C8-C10 fatty acid output, creating geographic single-point vulnerability.
- Long-chain triglyceride substitution:Structured lipid competitors with comparable energy density claims compete for sports nutrition formulation slots at lower price points.
Strategic Opportunities
- China functional food channels:SAMR regulatory clarity on MCT health claims is opening direct-to-consumer subscription models for ketogenic meal replacements.
- Microencapsulation technology convergence:Combination of spray-drying and lipid shell stabilization is enabling beverage applications previously blocked by oxidation and taste challenges.
- EU Green Deal carbon border adjustments:Verified sustainable feedstock documentation creates procurement preference for RSPO-certified plantation sources.
Industry Challenges
- Specialized lipid chemist scarcity:Fractionation process optimization and esterification quality control require expertise concentrated in Basel and Singapore talent pools.
- Pharmaceutical-grade certification timelines:FDA medical food compliance and IPEC-PQG GMP certification extend product development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium Chain Triglyceride (MCT) Food Market |
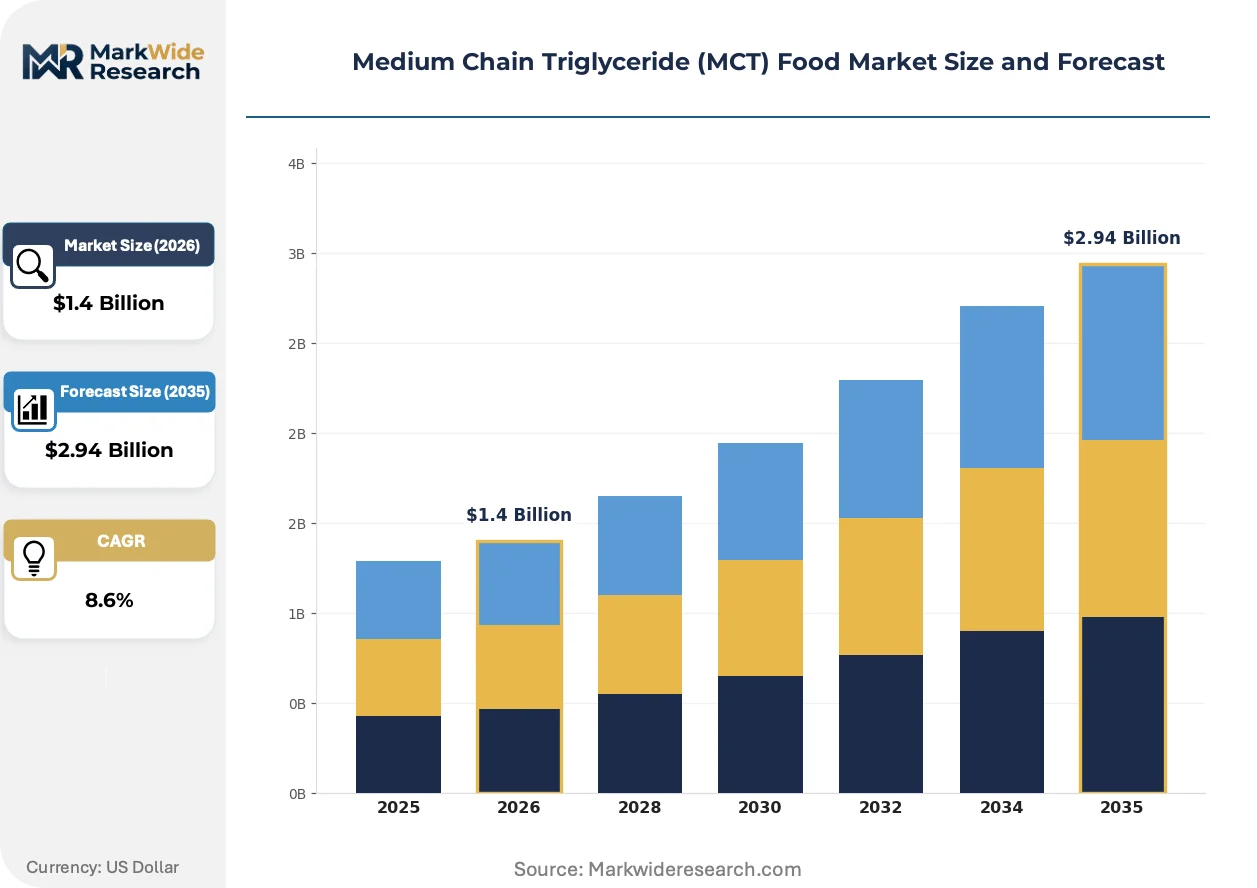
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Oil, Capsules, Liquid Application: Dietary Supplements, Sports Nutrition, Food & Beverages, Medical Foods End User: Health Enthusiasts, Athletes, Diabetics, General Population Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | BASF SE, Koninklijke DSM N.V., Croda International Plc, Musim Mas Holdings, Stepan Company, Wilmar International Limited, DuPont, Lonza Group Ltd., KLK Oleo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium Chain Triglyceride (MCT) Food Market Trends and Innovations
Continuous processing technologies and regulatory data transparency requirements are compressing batch-to-batch variability while expanding addressable application spaces beyond legacy supplement formats.
Membrane filtration systems paired with simulated moving bed chromatography are automating C8-C10 separation from crude coconut and palm kernel oil fractions. European pharmaceutical-grade MCT producers are adopting these units to displace energy-intensive vacuum distillation. This automation is compressing capital recovery periods while tightening fatty acid ratio precision for medical food clients.
China's SAMR issued draft guidelines requiring novel food registration for MCT oils with therapeutic utility claims, creating compliance divergence from FDA GRAS self-affirmation pathways. Domestic formulators are restructuring product positioning to avoid registration triggers. Ketogenic medical food imports face extended review timelines versus standard functional food classifications.
Direct-to-consumer subscription models are displacing traditional supplement retail distribution for MCT powders and oils. Ketogenic lifestyle brands are bypassing brick-and-mortar vitamin chains through personalized nutrition platforms. Germany and the United States exhibit the fastest channel migration, with recurring revenue models capturing lifetime value from adherence-focused consumer segments.
Medium Chain Triglyceride (MCT) Food Market Segmentation
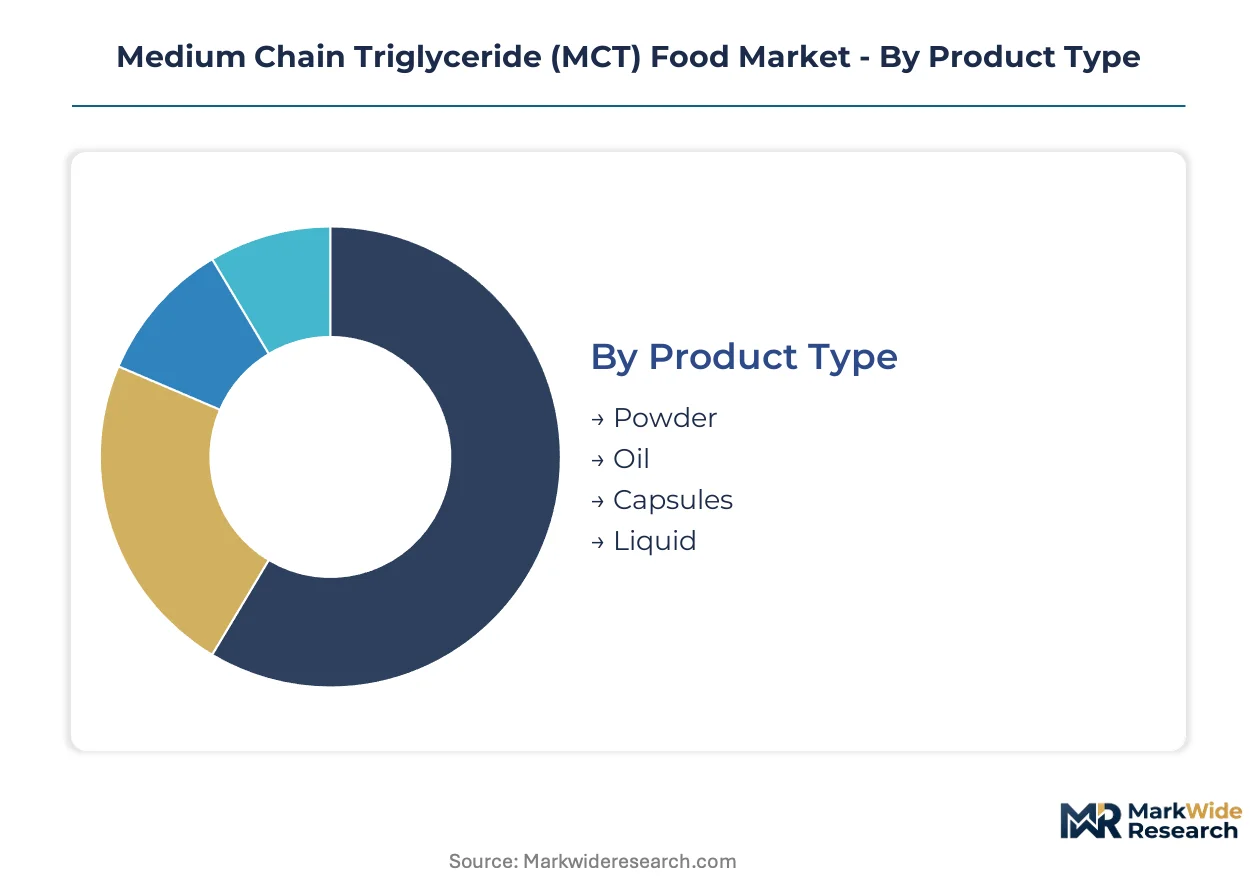
MCT food market segmentation reveals how formulation chemistry, regulatory classification, and channel economics partition buyer access. Each dimension carries distinct margin profiles and compliance burdens that reshape supplier prioritization.
Product Type:
Buyers differentiate by handling requirements, shelf stability needs, and incorporation mechanics into finished goods.
- Powder:Spray-dried MCT oils encapsulated in maltodextrin or gum arabic matrices deliver instant solubility for dry-blend sports nutrition. Demand concentrates in United States pre-workout formulations where manufacturing lines favor free-flowing inputs over liquid handling infrastructure. Powder formats command formulation preference when clean-label positioning requires absence of anti-caking agents.
- Oil:Pharmaceutical-grade C8-C10 concentrates in liquid form bypass standard lymphatic absorption pathways, enabling rapid hepatic metabolism for ketogenic medical foods. Procurement decisions in Germany and China hinge on fatty acid ratio certificates and oxidation marker thresholds. Oil purity grades determine access to institutional epilepsy therapy protocols versus standard wellness positioning.
- Capsules:Softgel delivery systems target health enthusiasts seeking precise dosing without taste exposure.
- Liquid:Bulk liquid formats serve food and beverage manufacturers requiring pumpable inputs for functional creamer production.
Volume sits with Powder; growth tilts toward Oil as ketogenic medical food protocols expand institutional procurement.
Application:
Margin capture varies sharply by regulatory pathway and end-user price sensitivity.
- Dietary Supplements:Direct-to-consumer subscription models generate recurring revenue through personalized nutrition platforms. United States and German consumers drive deepest lifetime value from adherence-focused ketogenic lifestyle segments. SAMR registration requirements in China create divergence from FDA GRAS pathways, forcing domestic formulators to restructure positioning.
- Sports Nutrition:Pre-workout and recovery formulations embed MCTs for rapid energy density without gastric distress. Powder formats dominate dry-blend manufacturing in United States contract facilities serving CrossFit and endurance athlete demographics. EFSA novel food consultations accelerate European product launches versus medical food compliance timelines.
- Food & Beverages:Functional creamers and meal replacements leverage MCTs for satiety signaling and texture modification.
- Medical Foods:Institutional procurement for epilepsy management requires pharmaceutical-grade certification extending development cycles.
Revenue concentrates in Dietary Supplements; steepest expansion trajectory belongs to Sports Nutrition as dry-blend formats capture formulation slots.
End User:
Health outcome specificity and clinical supervision levels segment buyer willingness-to-pay.
- Health Enthusiasts:Ketogenic lifestyle adopters purchasing through subscription platforms in Germany and United States drive premium pricing for purity-certified oils.
- Athletes:Endurance and strength training demographics prioritize rapid energy availability in pre-workout windows.
- Diabetics:Metabolic syndrome management protocols leverage MCTs for ketone body generation without carbohydrate load.
- General Population:Mass-market functional foods target satiety and cognitive performance claims with lower concentration formulations.
Spending intensity clusters with Health Enthusiasts; patient volume expansion centers on Diabetics as metabolic syndrome prevalence climbs.
Distribution Channel:
Channel selection determines margin retention versus customer acquisition economics.
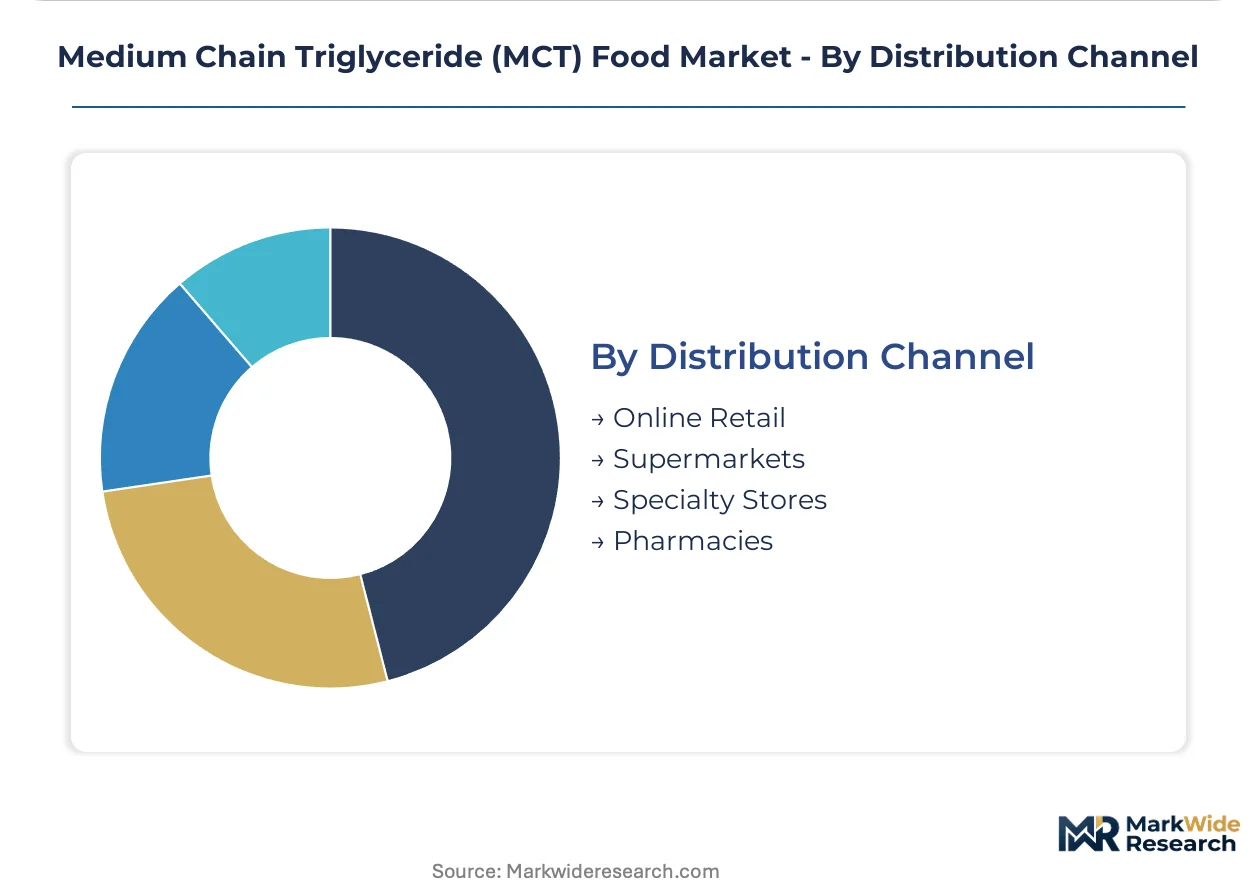
- Online Retail:Direct-to-consumer platforms bypass brick-and-mortar vitamin chains, capturing lifetime value through personalized nutrition subscriptions in United States and Germany.
- Supermarkets:Mass-market functional creamers and meal replacements reach general population segments through conventional grocery placement.
- Specialty Stores:Ketogenic-focused retailers curate pharmaceutical-grade oils for health enthusiasts seeking fatty acid ratio transparency.
- Pharmacies:Medical food distribution requires pharmacist consultation for epilepsy therapy protocols.
Margin retention favors Online Retail; prescription volume flows through Pharmacies where clinical validation commands price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian and Malaysian palm kernel oil plantations anchor upstream MCT feedstock flows, concentrating fractionation capacity in Southeast Asian oleochemical corridors. Downstream formulation demand fragments across three major consumption clusters.
United States
Ketogenic lifestyle adoption drives dietary supplement subscription models through direct-to-consumer platforms. FDA GRAS self-affirmation pathways accelerate product launch timelines versus pharmaceutical-grade certification. California and Texas host contract manufacturing facilities serving CrossFit and endurance athlete demographics with powder format pre-workout blends.
Germany
Health enthusiasts seeking pharmaceutical-grade oils command premium pricing for purity-certified C8-C10 concentrates. EFSA novel food consultations streamline approval pathways for functional food formulators. The Ludwigshafen specialty lipids complex sustains medical-grade output for institutional epilepsy therapy protocols.
China
SAMR import registration requirements for therapeutic utility claims create compliance divergence from Western regulatory frameworks. Domestic formulators restructure product positioning to avoid extended review timelines. Shanghai and Beijing concentrate ketogenic meal replacement subscription growth as metabolic syndrome prevalence climbs.
Indonesia
Musim Mas Holdings dominates upstream feedstock flows through plantation-to-refinery traceability systems. El Niño weather patterns introduce raw material cost volatility for fractionation operators. Sumatran oleochemical complexes control C8-C10 fatty acid isolation through backward integration into esterification assets.
Medium Chain Triglyceride (MCT) Food Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue microencapsulation and beverage application niches. The supplier base concentrates around Southeast Asian oleochemical conglomerates with captive plantation access and European pharmaceutical-grade specialists with medical food certification. Three archetypes dominate: integrated plantation-refinery operators, specialty lipids formulators, and sports nutrition contract manufacturers. Competitive moves center on RSPO-certified feedstock documentation for EU Green Deal compliance and membrane filtration technology licensing to displace vacuum distillation.
Among European-based specialty lipids producers, BASF SE and Croda International Plc exemplify pharmaceutical-grade archetypes with medical food certification depth. Southeast Asian plantation-refinery integration finds representation in Musim Mas Holdings, which anchors upstream feedstock control through Indonesian oleochemical operations. These three occupy positions across distinct competitive vectors—European purity certification, Asian feedstock security, and ketogenic formulation expertise.
| Leading Market Players |
|---|
| BASF SE |
| Koninklijke DSM N.V. |
| Croda International Plc |
| Musim Mas Holdings |
| Stepan Company |
| Wilmar International Limited |
| DuPont |
| Lonza Group Ltd. |
| KLK Oleo |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade C8-C10 certification requirements from German medical food clients are compressing margin structures for fractionation operators, forcing Southeast Asian suppliers to absorb esterification quality-control investments or surrender procurement slots to Ludwigshafen-based competitors.
Pricing Analysis
Certification-bundling arrangements separate pharmaceutical-grade oils with FDA medical food compliance and IPEC-PQG GMP documentation from standard wellness-tier products sold unbundled. Three-tier pricing structure across premium, standard, and economy levels tracks fatty acid ratio precision, oxidation marker thresholds, and RSPO-certified feedstock documentation. Pricing pressure stems from long-chain triglyceride substitutes competing for sports nutrition formulation slots at lower price points. Mass-market functional creamer manufacturers exhibit highest price sensitivity; institutional epilepsy therapy protocols demonstrate lowest sensitivity due to clinical validation requirements.
Supply Chain Analysis
EU Green Deal carbon border adjustments and domestic-content preferences in European pharmaceutical procurement are reshaping sourcing toward RSPO-certified Indonesian and Malaysian plantation networks with verified traceability. C8-C10 fatty acid isolation draws from crude coconut oil fractions and palm kernel oil distillates, with membrane filtration systems displacing vacuum distillation. Single-source vulnerability concentrates in Sumatran oleochemical corridors exposed to El Niño weather volatility. Distribution runs through direct-to-consumer subscription platforms in Germany and the United States, bypassing traditional brick-and-mortar vitamin chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into plantation-to-refinery traceability systems has become the defining competitive race, with control over C8-C10 fatty acid isolation assets determining margin retention against Ludwigshafen pharmaceutical-grade specialists.
For Market Incumbents: Acquire membrane filtration technology licenses to displace energy-intensive vacuum distillation and compress capital recovery periods. Secure RSPO-certified feedstock documentation to defend procurement slots against EU Green Deal carbon border adjustments. Extend pharmaceutical-grade certification depth to counter emerging microencapsulation specialists targeting beverage applications. For New Entrants and Emerging Players: EFSA novel food consultations in Europe open a window for streamlined C8-C10 concentrate approvals in functional food formulations. Target United States sports nutrition dry-blend contract manufacturers seeking instant-solubility powder formats without anti-caking agents. Pursue direct-to-consumer subscription platform partnerships to capture lifetime value from adherence-focused ketogenic lifestyle segments. For Investors and Strategic Acquirers: The window for entry favors Southeast Asian plantation-refinery operators with captive C8-C10 fractionation capacity and established SAMR registration pathways for China. Monitor ketogenic health claims regulation evolution as the inflection signal for pharmaceutical-grade versus wellness-tier margin divergence. Long-term viability rests on sustained clinical adoption of medical ketogenic therapies for epilepsy management and metabolic syndrome treatment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fractionation Assets | Musim Mas Holdings and KLK Oleo consolidate C8-C10 supply security against El Niño volatility. |
| Pharmaceutical-Grade Certification Investment | BASF SE sustains Ludwigshafen medical food output through FDA and IPEC-PQG GMP compliance depth. |
| Microencapsulation Technology Licensing | Spray-drying and lipid shell stabilization unlock beverage applications blocked by oxidation challenges. |
| Direct-to-Consumer Platform Launch | Ketogenic lifestyle brands in Germany and the United States bypass brick-and-mortar vitamin chains. |
| RSPO-Certified Feedstock Documentation | Verified sustainable sourcing creates procurement preference under EU Green Deal carbon border adjustments. |
Research Methodology
Trade databases, SEC filings from specialty lipids producers, and EFSA novel food consultation records formed the secondary backbone. Primary interviews with fractionation process engineers at Southeast Asian oleochemical complexes, procurement leads at German medical food formulators, regulatory affairs specialists navigating SAMR registration pathways, and sports nutrition contract manufacturing executives in California and Texas provided ground-truth validation. Bottom-up demand modeling across powder, oil, and capsule formats triangulated against top-down value-chain analysis.
Historical trendline analysis of C8-C10 fatty acid ratio precision and oxidation marker thresholds informed the analytical framework across the projection horizon. Segmentation dimensions included product type, application category, end-user health outcome specificity, and distribution channel economics. CAGRs were derived from penetration trajectories in ketogenic medical food protocols and sports nutrition dry-blend adoption curves, with membrane filtration technology diffusion and regulatory approval timelines as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for continuous processing and simulated moving bed chromatography would alter the outlook. Forecasts reflect assumptions about EFSA consultation streamlining, SAMR registration clarity, and sustained clinical validation of ketogenic therapies. El Niño frequency, palm kernel oil yield volatility, and long-chain triglyceride substitution rates represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Human Nutrition Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
North America Spirulina Extract Market
Nutritional Supplements
GLP-1 Hydration Product Market
Nutritional Supplements
India Whey Protein Market
Nutritional Supplements
Calcium Market
Nutritional Supplements
Nicotine Gum Market
Nutritional Supplements
Maternity Vitamins and Supplements Market
Nutritional Supplements
Functional Carbohydrates Market
Nutritional Supplements
Health Supplements Market
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
Folate Market
Nutritional Supplements
Wellness Supplements Market