
 Bone Broth Protein Market | 2026-2036
Bone Broth Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Broth Protein Market Outlook
Subscription-based replenishment programs is hardening as the dominant service layer in bone broth protein commerce, locking consumers into recurring revenue streams that stabilize manufacturer forecasting. Ancient Nutrition leverages direct-to-consumer subscription tiers to sustain repeat purchase rates across its collagen and broth-derived SKU portfolio. Vital Proteins anchors its market position through broad retail distribution, while NOW Foods competes on price accessibility in mass-market channels.
Bone broth protein denotes hydrolyzed collagen and gelatin fractions extracted from simmered animal bones, typically yielding 15–20 grams of protein per serving with measurable glycine and proline amino acid profiles. Manufacturers employ low-temperature dehydration to preserve peptide bioactivity for sports recovery and gut health applications. Powdered formats currently lead volume shipments due to shelf stability and formulation flexibility in smoothies and baking, though ready-to-drink cartons represent the fastest-growing segment as convenience-seeking athletes shift from scoop-and-mix routines. Health food stores capture premium margin pools through personalized staff recommendations, while online retail channels erode that advantage with subscription discounts and bulk pricing.
The FDA oversees protein content labeling accuracy and structure-function claims for bone broth products sold in the United States, while USDA Organic certification shapes premium tier eligibility and consumer trust thresholds. EFSA novel food assessments govern European market entry for bone broth isolates, creating compliance bottlenecks for exporters. Stakeholders must monitor evolving amino acid fortification standards and regenerative agriculture sourcing requirements as dual levers that will determine which suppliers retain shelf space and pricing power.
Market Dynamics
Clean-label certification requirements from the USDA and EFSA are compressing ingredient sourcing standards, forcing manufacturers to document regenerative agriculture provenance and low-temperature processing protocols to retain retail shelf placement.
Growth Catalysts
- Ketogenic diet adherence:Health-conscious consumers in the United States maintain repeat purchasing patterns for collagen-rich recovery formulations, creating stable demand baselines for hydrolyzed protein SKUs.
- Low-temperature dehydration:This processing technology preserves peptide bioactivity for gut health applications, differentiating premium tier products from heat-damaged alternatives in sports nutrition channels.
- EFSA novel food assessments:European regulatory clearance for bone broth isolates creates compliant export pathways for North American manufacturers seeking cross-border revenue streams.
Market Restraints
- Bovine collagen input volatility:Cattle bone supply fluctuations in Argentina and Brazil transmit price instability to hydrolyzed protein production costs, compressing margin predictability for mid-tier suppliers.
- Plant-based protein substitution:Pea and rice protein isolates capture label-conscious consumers seeking animal-free alternatives, eroding addressable market share in flexitarian demographics.
- USDA Organic certification bottlenecks:Regenerative sourcing documentation requirements extend qualification timelines, delaying premium tier eligibility for smaller processors lacking dedicated compliance staff.
Strategic Opportunities
- Ready-to-drink carton expansion:Convenience-seeking athletes in Germany and France shift from powder formats, creating white space for ambient-stable liquid collagen formulations with extended shelf life.
- Sports recovery application convergence:Functional beverage manufacturers integrate bone broth protein with adaptogenic botanicals, opening formulation partnerships with CrossFit and endurance sports event sponsors.
- Subscription channel penetration:Direct-to-consumer replenishment programs lock recurring revenue streams, reducing customer acquisition costs compared to retail slotting fee dependence.
Industry Challenges
- Amino acid fortification standardization:Divergent glycine and proline measurement protocols across ISO and national reference laboratories create labeling disputes and batch rejection risks at customs checkpoints.
- Peptide bioactivity validation:Analytical method development for molecular weight distribution testing requires specialized chromatography equipment, stretching R&D budgets for emerging market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Broth Protein Market |
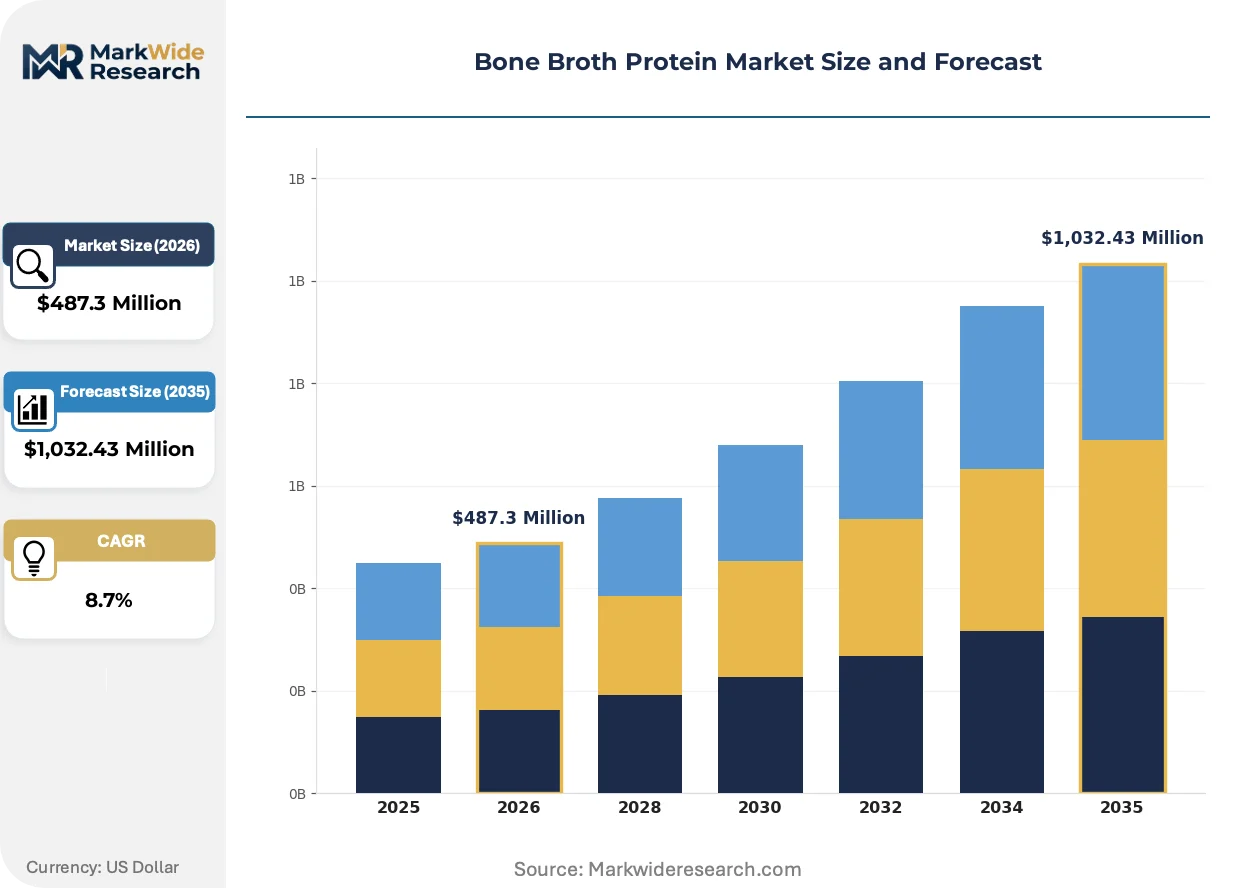
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Liquid, Ready-to-Drink, Concentrate End User: Athletes, Fitness Enthusiasts, Health-conscious Consumers, Culinary Professionals Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Packaging Type: Boxes, Pouches, Jars, Tetra Packs |
| Companies Covered | Ancient Nutrition, Kettle & Fire, NOW Foods, Bonafide Provisions, Bare Bones Broth Co., Vital Proteins, Epic Provisions, Organixx, Nutra Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Broth Protein Market Strategic Shifts
Processing transparency and format convenience are rewriting competitive differentiation in bone broth protein, as manufacturers race to document supply chain provenance while reducing consumer preparation friction.
Enzymatic hydrolysis at controlled pH levels is rewriting the cost-efficiency frontier for collagen extraction. Sports nutrition contract manufacturers in the Netherlands and Denmark adopt continuous-flow reactor systems to reduce batch cycle times. This technology is rewriting the economics of small-batch artisan positioning versus industrial scale.
REACH registration requirements for novel collagen peptides are tightening purity documentation obligations for European market entry. Manufacturers must submit toxicological dossiers demonstrating absence of heavy metal contamination from bone sourcing. Ready-to-drink formulations face the steepest compliance burden due to expanded shelf stability testing mandates.
Athlete purchasing patterns are compressing switching cycles between protein formats as trial-size sampler programs proliferate in CrossFit affiliate boxes and marathon expos. Health food store staff recommendations formerly governed brand selection; digital subscription discounts and influencer-coded promotions now displace that channel authority. This behavioral shift concentrates most visibly in California and Texas metropolitan corridors where fitness culture penetration exceeds national baselines.
Bone Broth Protein Market Segmentation
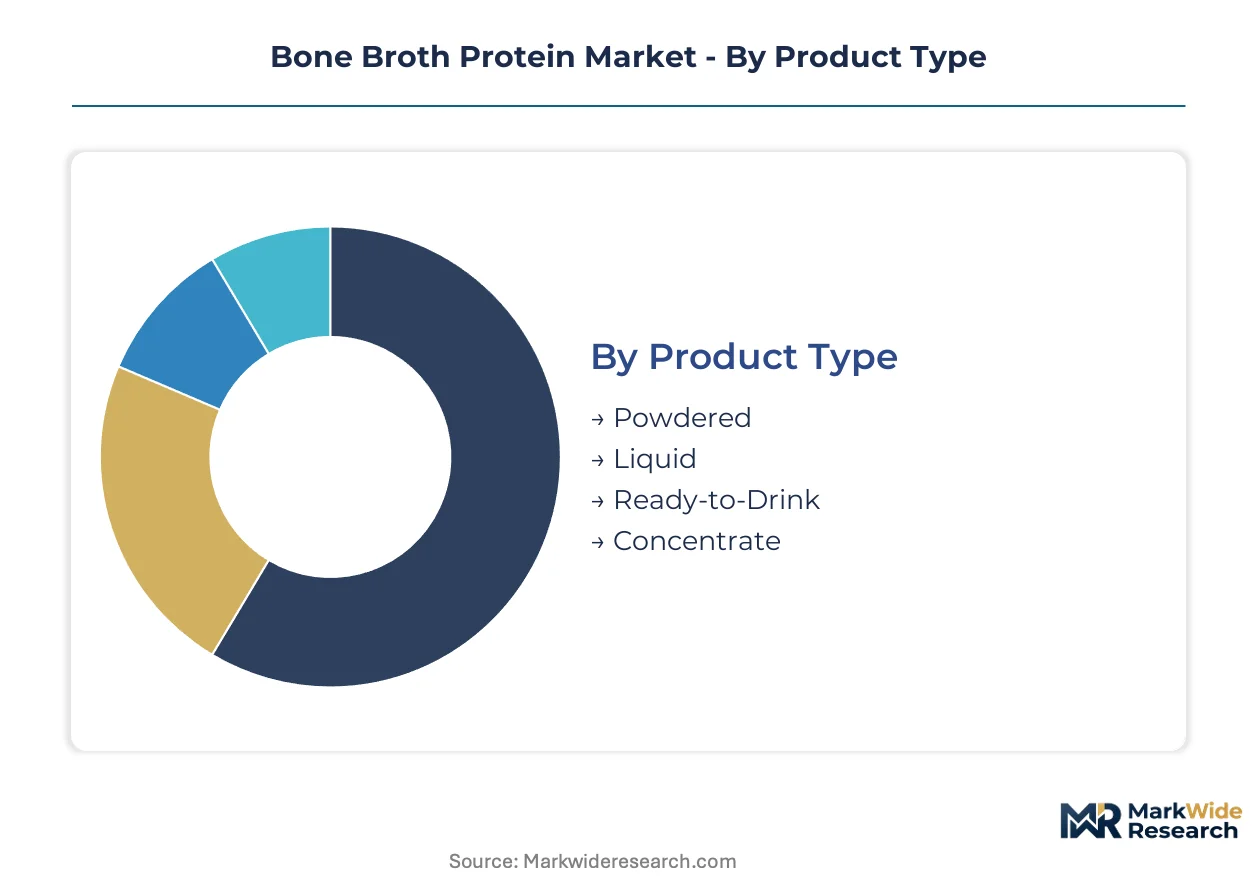
Segmentation in bone broth protein reveals how processing technology, consumption context, and purchase behavior split addressable demand into discrete margin pools. Each dimension carries distinct capital requirements and regulatory exposure that reshape supplier strategy.
Product Type:
Powdered formats demand the heaviest upfront investment in spray-drying towers and low-temperature dehydration infrastructure, while liquid and ready-to-drink variants require aseptic filling lines and extended shelf-stability testing budgets.
- Powdered:Hydrolyzed collagen and gelatin fractions dried through controlled-temperature spray towers yield 15–20 gram protein servings with preserved peptide bioactivity. Demand concentrates in United States ketogenic and paleo diet adherents who prioritize scoop-and-mix flexibility for smoothies and baking applications.
- Ready-to-Drink:Ambient-stable liquid formulations in portable cartons eliminate preparation friction for time-constrained athletes. Convenience-seeking consumers in Germany and France are shifting from powder formats, creating white space for collagen beverages with extended shelf life.
- Liquid:Refrigerated concentrates requiring cold-chain distribution serve premium health food store channels with shorter shelf windows and higher per-unit margins.
- Concentrate:Reduced-water extracts targeting culinary professionals and bulk foodservice operations emphasize cost efficiency over convenience positioning.
Powdered formats absorb the bulk of installed capacity; ready-to-drink is expanding most quickly.
End User:
Customer type segmentation tracks protein literacy levels and purchase frequency, with athletes and fitness enthusiasts driving volume while culinary professionals command specialized formulation specifications.
- Athletes:CrossFit competitors and endurance sports participants prioritize rapid amino acid absorption for recovery windows, subscribing to replenishment programs that lock recurring revenue streams.
- Fitness Enthusiasts:Recreational gym-goers in California and Texas metropolitan corridors respond to influencer-coded promotions and trial-size sampler programs at marathon expos.
- Health-conscious Consumers:Gut health and clean-label adherents in United States suburban markets seek USDA Organic certification and regenerative agriculture provenance documentation.
- Culinary Professionals:Restaurant and foodservice buyers source unflavored concentrates for sauce and broth applications where collagen functionality replaces traditional gelatin.
Athletes absorb the bulk of installed capacity; health-conscious consumers are climbing the fastest.
Distribution Channel:
Channel segmentation exposes divergent customer acquisition economics, with online retail eroding health food store margin premiums through subscription discounts and bulk pricing.
- Online Retail:Direct-to-consumer platforms capture subscription-based replenishment programs with automated recurring shipments that reduce forecasting volatility for manufacturers.
- Health Food Stores:Staff recommendation channels command premium pricing through personalized consultation but face displacement from digital discovery.
- Supermarkets:Mass-market placement competes on price accessibility with NOW Foods and similar brands targeting grocery aisle visibility.
- Specialty Shops:Boutique fitness and wellness retailers curate premium tier SKUs with localized brand curation and community event tie-ins.
Online retail absorbs the bulk of customer acquisition investment; health food stores are losing share fastest.
Packaging Type:
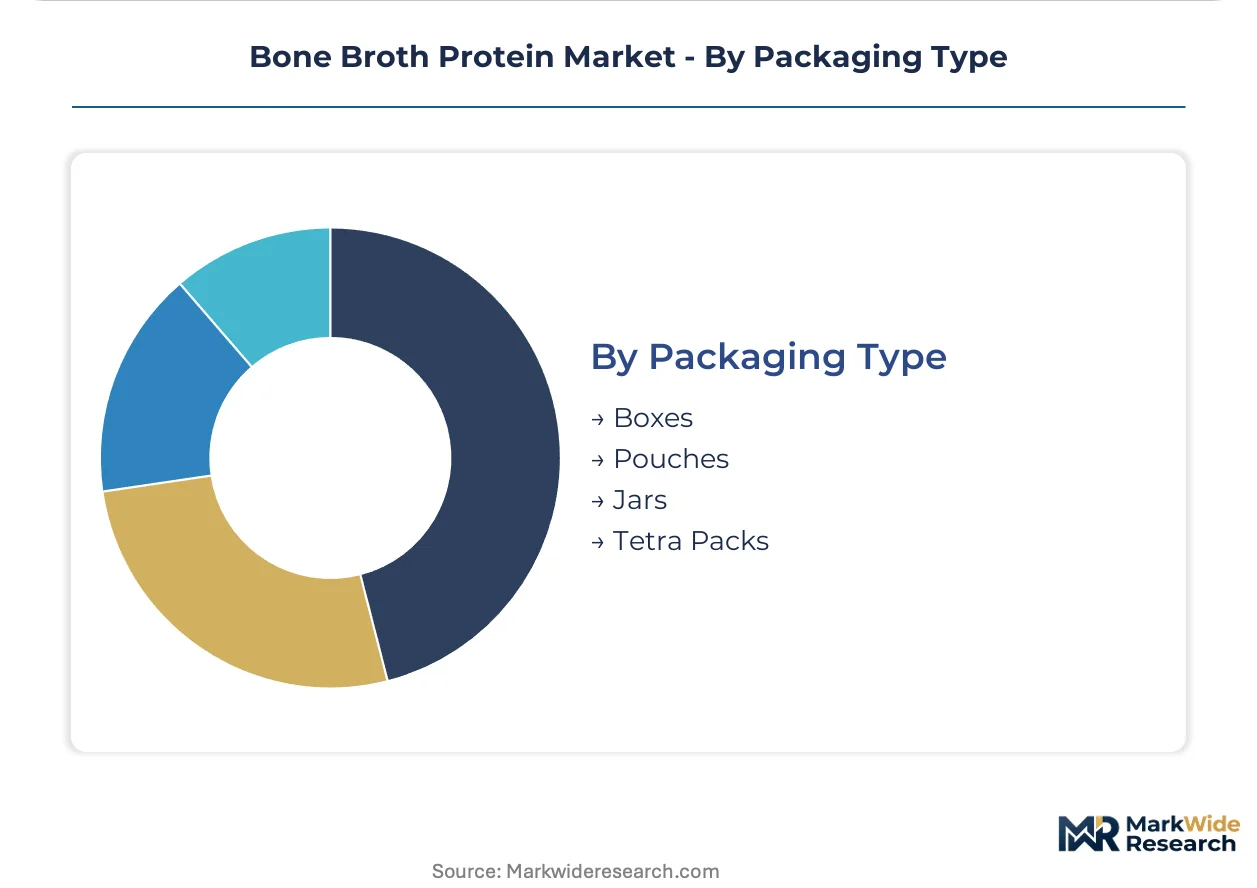
Packaging segmentation reflects shelf stability requirements and sustainability positioning, with material selection directly impacting EFSA novel food assessment documentation and REACH registration compliance.
- Pouches:Flexible film structures minimize shipping cube and material cost for powdered formats targeting subscription replenishment economics.
- Tetra Packs:Aseptic carton systems enable ambient-stable liquid collagen with extended shelf life, facing the steepest European compliance burden for expanded stability testing mandates.
- Jars:Rigid containers serve premium powdered positioning with resealability and kitchen counter visibility.
- Boxes:Corrugated secondary packaging for multi-unit subscription shipments emphasizes unboxing experience and brand narrative.
Pouches absorb the bulk of powdered format shipments; tetra packs are gaining share fastest in ready-to-drink expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of hydrolyzed bone broth protein concentrates in Argentina and Brazil supplies North American and European formulators, while consumption clusters in affluent metropolitan corridors where ketogenic diet adherence and sports nutrition culture intersect.
United States
Ketogenic and paleo diet communities in California and Texas drive repeat purchasing of collagen-rich recovery formulations. FDA oversight of protein content labeling and structure-function claims shapes compliance investments for domestic manufacturers. CrossFit affiliate boxes in Austin and Los Angeles distribute trial-size sampler programs that compress consumer switching cycles between brands.
Germany
Convenience-seeking athletes in Berlin and Munich shift from powdered formats to ambient-stable liquid collagen beverages. EFSA novel food assessments for bone broth isolates create documentation bottlenecks for exporters seeking European market entry. Sports nutrition contract manufacturers in Hamburg adopt continuous-flow enzymatic hydrolysis reactors to reduce batch cycle times.
France
Health-conscious consumers in Paris and Lyon prioritize regenerative agriculture provenance and USDA Organic certification equivalency. REACH registration requirements for novel collagen peptides tighten purity documentation obligations for importers. Specialty wellness retailers in Provence curate premium tier SKUs with localized community event tie-ins.
Netherlands
Functional beverage manufacturers in Amsterdam and Rotterdam integrate bone broth protein with adaptogenic botanicals for sports recovery applications. EFSA clean-label certification requirements reshape ingredient sourcing standards for exporters targeting EU markets. Contract manufacturing clusters in Eindhoven specialize in low-temperature dehydration infrastructure for peptide bioactivity preservation.
Canada
Health food store channels in Toronto and Vancouver command premium pricing through personalized staff recommendations. Health Canada and PMRA oversight of natural health product licensing governs structure-function claims for bone broth supplements. Digital subscription platforms erode traditional retail margins with automated replenishment programs and bulk pricing incentives.
Bone Broth Protein Market Competitive Environment
Capital-heavy producers with in-house low-temperature dehydration infrastructure compete with asset-light brands outsourcing collagen extraction to third-party processors. The vendor base stratifies across three tiers: vertically integrated specialists controlling cattle bone supply chains, direct-to-consumer subscription platforms capturing recurring revenue, and mass-market distributors competing on price accessibility in grocery channels. Dominant competitive moves include backward integration into regenerative agriculture sourcing and geographic expansion through EFSA compliance investments.
Within the vertically integrated tier, Ancient Nutrition and Vital Proteins exemplify archetypes of supply chain control and broad retail penetration respectively. NOW Foods occupies a position in mass-market price accessibility. Kettle & Fire and Bonafide Provisions represent the premium direct-to-consumer vector with subscription-first business models. These five entities collectively illustrate the competitive spectrum from cattle sourcing to digital replenishment.
| Leading Market Players |
|---|
| Ancient Nutrition |
| Kettle & Fire |
| NOW Foods |
| Bonafide Provisions |
| Bare Bones Broth Co. |
| Vital Proteins |
| Epic Provisions |
| Organixx |
| Nutra Organics |
| Others |
Value Chain & Pricing Dynamics
USDA Organic certification gates qualified supply and premium-tier pricing access, forcing manufacturers to document regenerative agriculture provenance and low-temperature processing protocols before commanding shelf placement in health food channels. Buyers without certification documentation face exclusion from the highest-margin consumer segments.
Pricing Analysis
Margin tightening in mid-tier SKUs reflects bovine collagen input volatility from Argentina and Brazil, compressing predictability for suppliers lacking long-term cattle bone contracts. Pricing stratifies across premium, standard, and economy tiers based on USDA Organic certification status and peptide bioactivity validation. Cost-down pressure on economy-positioned powders accelerates because pea and rice protein isolates capture label-conscious flexitarian consumers. Health-conscious suburban buyers demonstrate lowest price sensitivity, while mass-market grocery purchasers drive hardest bargain.
Supply Chain Analysis
Cattle bone supply rests on regenerative ranching operations in Argentina, Brazil, and the United States, with hydrolyzed collagen extraction feeding North American and European formulators. Raw material dependencies include grass-fed cattle bones, enzymatic processing agents, and low-temperature dehydration infrastructure. Single-source vulnerability concentrates in South American bone meal processors exposed to commodity price swings. Distribution runs through direct-to-consumer subscription platforms, health food store networks, and mass-market retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA novel food assessment compliance operates as a cost-of-compliance moat, erecting documentation barriers that filter out undercapitalized entrants while rewarding prepared exporters with European market access.
For Market Incumbents: Anticipate plant-based protein substitution threats by securing backward integration into regenerative cattle sourcing and accelerating USDA Organic certification investments. Locking captive bone supply from Argentine and Brazilian ranching networks defends margin position against input volatility. Prioritize peptide bioactivity validation capabilities to differentiate from heat-damaged alternatives. For New Entrants and Emerging Players: The price-point gap between premium certified SKUs and economy-positioned powders creates white-space opportunity in Germany and France ready-to-drink expansion. Convenience-seeking athletes shifting from scoop-and-mix routines represent the most penetrable segment. Launch with ambient-stable liquid collagen in Tetra Pack format through CrossFit affiliate sampling programs. For Investors and Strategic Acquirers: EFSA clearance announcements for North American bone broth isolates are the leading indicator that cross-border revenue streams are opening for compliant exporters. Long-term viability favors vertically integrated specialists controlling cattle sourcing through extraction infrastructure. Watch for REACH registration submissions as inflection signal for European market readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Sourcing Certification | USDA Organic documentation unlocks premium-tier shelf placement and pricing power in health food channels. |
| Continuous-Flow Enzymatic Hydrolysis | Dutch and Danish contract manufacturers reduce batch cycle times, rewriting small-batch versus industrial scale economics. |
| Ready-to-Drink Format Expansion | Ambient-stable liquid collagen in Tetra Packs captures convenience-seeking athletes in Berlin and Munich metropolitan corridors. |
| Subscription Platform Penetration | Direct-to-consumer replenishment programs lock recurring revenue streams and reduce customer acquisition cost dependence. |
| EFSA Compliance Investment | Novel food assessment documentation opens European export pathways for North American hydrolyzed protein manufacturers. |
Study Parameters
Document review covered SEC filings from sports nutrition and functional beverage manufacturers, USDA and EFSA regulatory databases, and customs trade records, complemented by interviews with contract manufacturing executives, health food store category buyers, and regulatory affairs specialists at collagen extraction facilities. Bottom-up demand modeling triangulated against top-down market sizing from hydrolyzed protein production capacity assessments.
Historical volume trajectories cross-referenced against expert panel input on ketogenic diet adherence patterns and sports nutrition channel shifts. Segmentation dimensions modeled include product format, end-user archetype, distribution channel, and packaging type across the projection horizon. CAGRs derived from trend extrapolation adjusted for EFSA regulatory timeline uncertainty and regenerative agriculture adoption curves.
Inputs from FDA structure-function claim filings and EFSA novel food assessment registers were available through the study window; gaps in peptide bioactivity standardization protocols introduce uncertainty bands around premium-tier volume forecasts. Forecasts reflect documented assumptions on consumer format switching velocity and certification penetration rates. A small set of triggers—EFSA clearance velocity, cattle bone commodity swings, and plant-based protein substitution rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
Mexico Collagen Peptides Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Isoleucine Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Mediterranean Metabolic Syndrome Support Ingredient Packs Market
Nutritional Supplements
Phytoceramide Supplement Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
Prenatal Vitamin Supplements Market
Nutritional Supplements
Nutraceutical Gummies Market
Nutritional Supplements
Maternity Vitamins and Supplements Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market