
 South America Pet Diet Market | 2026-2036
South America Pet Diet Market Size, Share, and Industry Trends Forecast 2026-2036
South America Pet Diet Market Insights
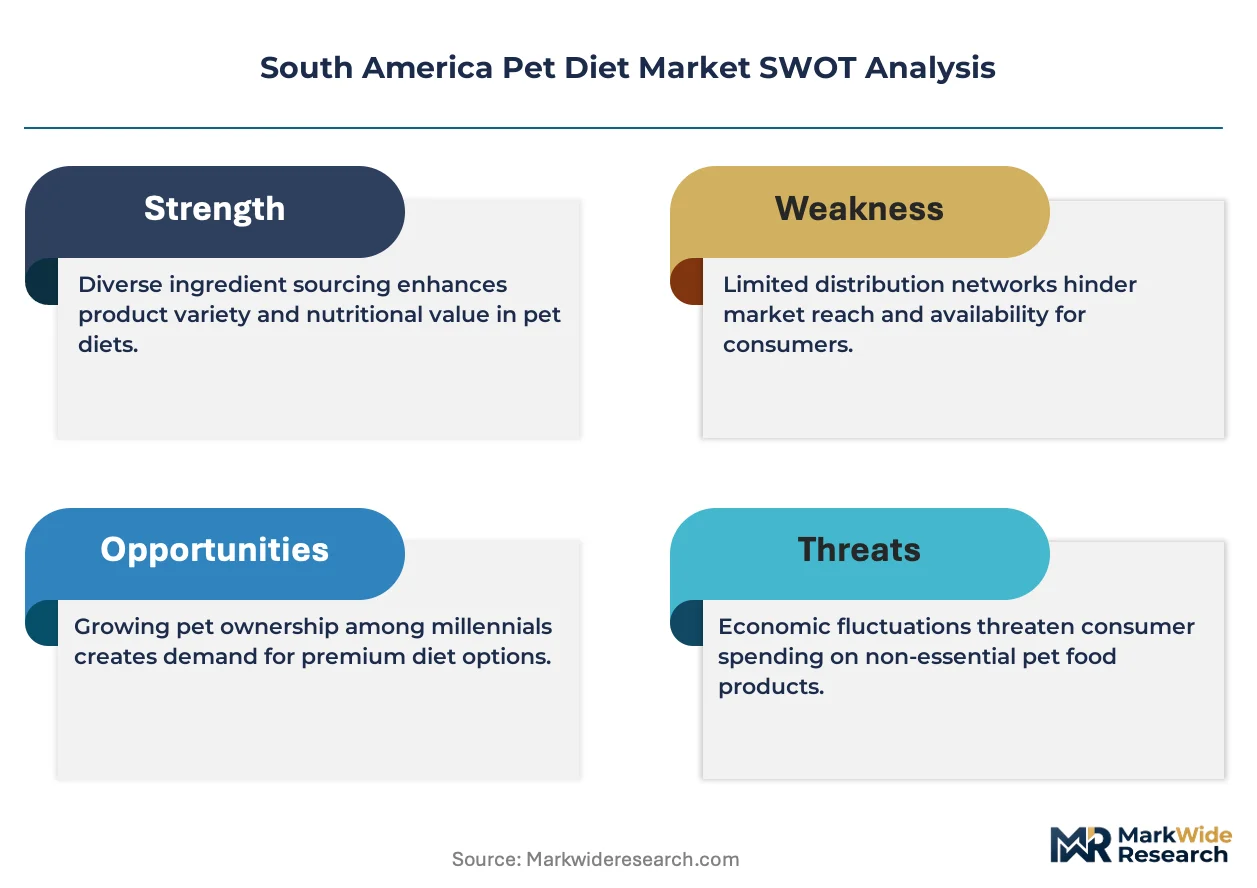
Consolidation among veterinary clinic chains is repositioning how premium therapeutic diets reach end consumers in South America. Mars Incorporated leverages its global R&D network to sustain formulation leadership across therapeutic and wellness segments. Nestlé Purina PetCare anchors its regional position through manufacturing scale in Brazil and deep veterinary channel relationships. BRF S.A. competes on localized protein sourcing and cost-efficient production of mid-tier dry food lines.
The South America Pet Diet comprises formulated nutritional products manufactured to specific macronutrient profiles, moisture content thresholds, and digestibility coefficients for companion animals, with dry food typically processed through extrusion at temperatures exceeding 120 degrees Celsius to achieve shelf stability and nutrient density. Its primary commercial purpose centers on delivering species-appropriate nutrition that supports longevity, disease management, and performance optimization across canine and feline populations. Dry food remains the volume anchor due to logistics efficiency and price accessibility, while raw diet segments attract margin concentration from affluent urban consumers seeking biologically appropriate feeding protocols. Wet food sustains growth in aging pet populations where palatability and hydration support drive veterinary recommendations.
ANVISA governs ingredient safety and manufacturing hygiene standards for commercial pet foods in Brazil, while Argentina's national food safety regulator enforces parallel controls on imported products and local production facilities. These frameworks elevate compliance costs for new entrants but reinforce quality differentiation among established manufacturers. Stakeholders must monitor evolving Mercosur harmonization discussions and shifting e-commerce distribution regulations to anticipate channel access constraints and labeling requirement changes.
Market Dynamics
Veterinary clinic consolidation across Brazil and Argentina is restructuring distribution economics, with prescription diet programs now capturing margin that previously flowed through retail channels. This channel shift is compressing wholesale tiers and elevating formulation partnerships as the primary competitive lever.
Growth Catalysts
- ANVISA Labeling Mandates:Brazil's updated ingredient disclosure standards are accelerating premiumization as manufacturers compete on transparency credentials.
- São Paulo-Rio Corridor:Concentrated affluence in Brazil's southeastern urban zone sustains demand for therapeutic and wellness nutrition portfolios.
- Extrusion Technology:Advances in high-temperature processing above 120 degrees Celsius are improving nutrient density and shelf stability in dry food formats.
Market Restraints
- Poultry Protein Volatility:Feed input costs fluctuate with Brazilian agricultural commodity cycles, pressuring mid-tier dry food margins.
- Import Dependency:Argentina's local production capacity constraints create supply vulnerability for specialized therapeutic formulations.
- Raw Diet Substitution:Biologically appropriate feeding protocols among affluent urban consumers divert spending from commercial extruded products.
Strategic Opportunities
- Chilean Market Entry:Underpenetrated veterinary channel infrastructure in Santiago and Valparaíso offers first-mover positioning for prescription diet programs.
- Mercosur Harmonization:Pending regulatory alignment discussions could streamline cross-border manufacturing and reduce compliance fragmentation.
- Veterinary E-Commerce:Direct-to-clinic digital platforms are emerging as a channel innovation, bypassing traditional distributor markups.
Industry Challenges
- Veterinary Nutritionist Shortage:Qualified formulation specialists are scarce across Brazilian research institutions, constraining R&D pipeline velocity.
- Legacy System Integration:Clinic chains face complexity merging proprietary diet ordering platforms with existing practice management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Pet Diet Market |
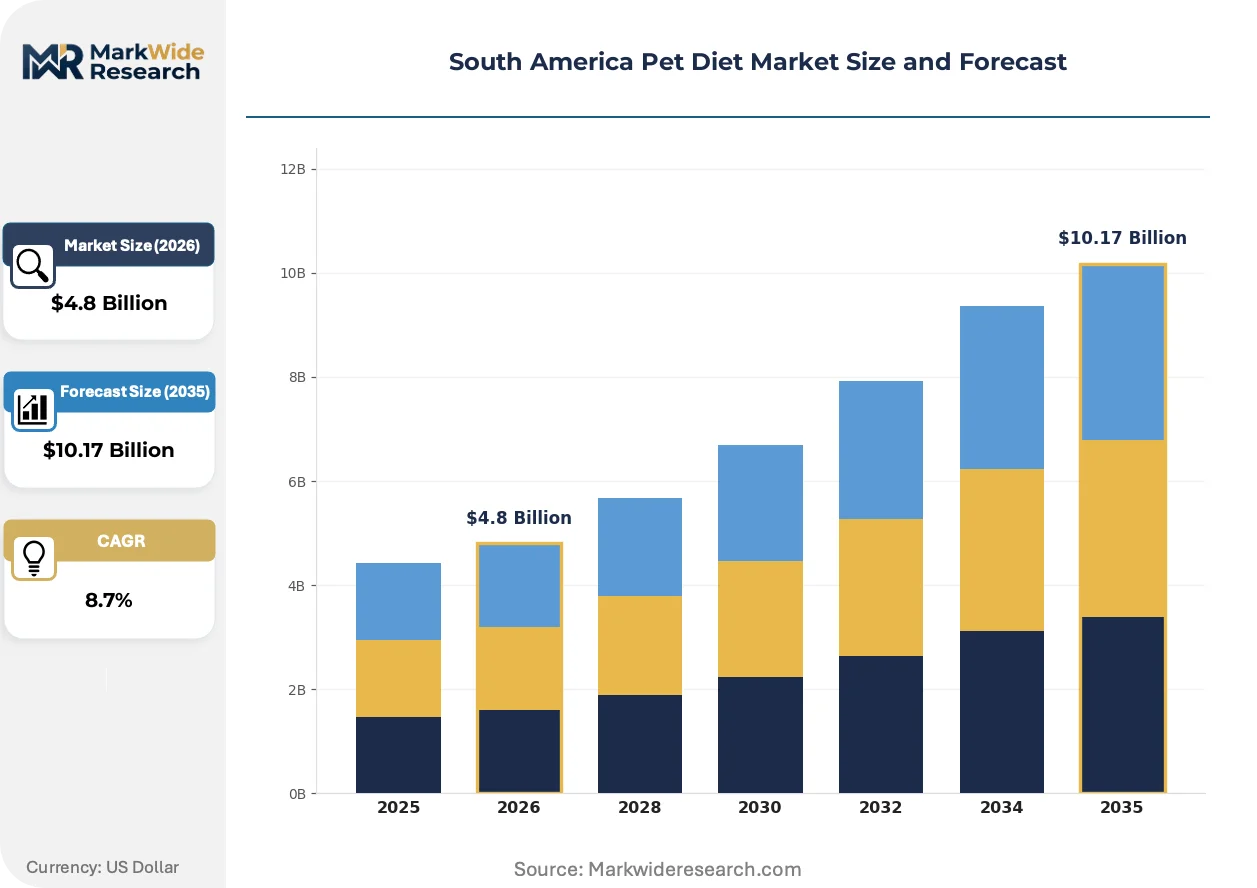
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Diet Ingredient Source: Meat-Based, Plant-Based, Grain-Free, Others End User: Pet Owners, Veterinary Clinics, Pet Stores, Online Retailers Distribution Channel: Supermarkets, Specialty Stores, E-commerce, Pet Expos |
| Companies Covered | Mars Incorporated, Nestlé Purina PetCare, BRF S.A., PremieRpet Holding, Empresas Carozzi S.A., Colgate-Palmolive Company, Alltech, Hill's Pet Nutrition, Grupo Pilar, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Pet Diet Market Trends and Innovations
Formulation science is advancing through precision nutrition approaches that match macronutrient profiles to specific life stages and disease states. These developments are elevating therapeutic diets from commodity feed to clinical intervention tools.
Cold-pressed processing technology is converging with high-pressure pasteurization to preserve raw ingredient bioactivity without sacrificing shelf stability. Premium manufacturers in Brazil's southeastern corridor are adopting these methods for limited-ingredient diet lines. The structural consequence is compressing the price-performance gap between raw alternatives and premium commercial formats.
ANVISA's evolving manufacturing hygiene standards are tightening facility certification requirements for both domestic producers and Mercosur importers. Compliance investments are elevating capital barriers for new entrants while reinforcing quality differentiation among established Brazilian manufacturers. Wet food and fresh-format segments face the steepest adaptation costs due to shorter shelf-life protocols.
Subscription-based replenishment models are displacing traditional retail purchasing among urban Brazilian pet owners with aging companion animals. Veterinary clinics in São Paulo are piloting auto-ship programs tied to wellness plan memberships. This pattern is most visible in feline renal support and canine mobility diet categories where compliance continuity drives clinical outcomes.
South America Pet Diet Market Segmentation
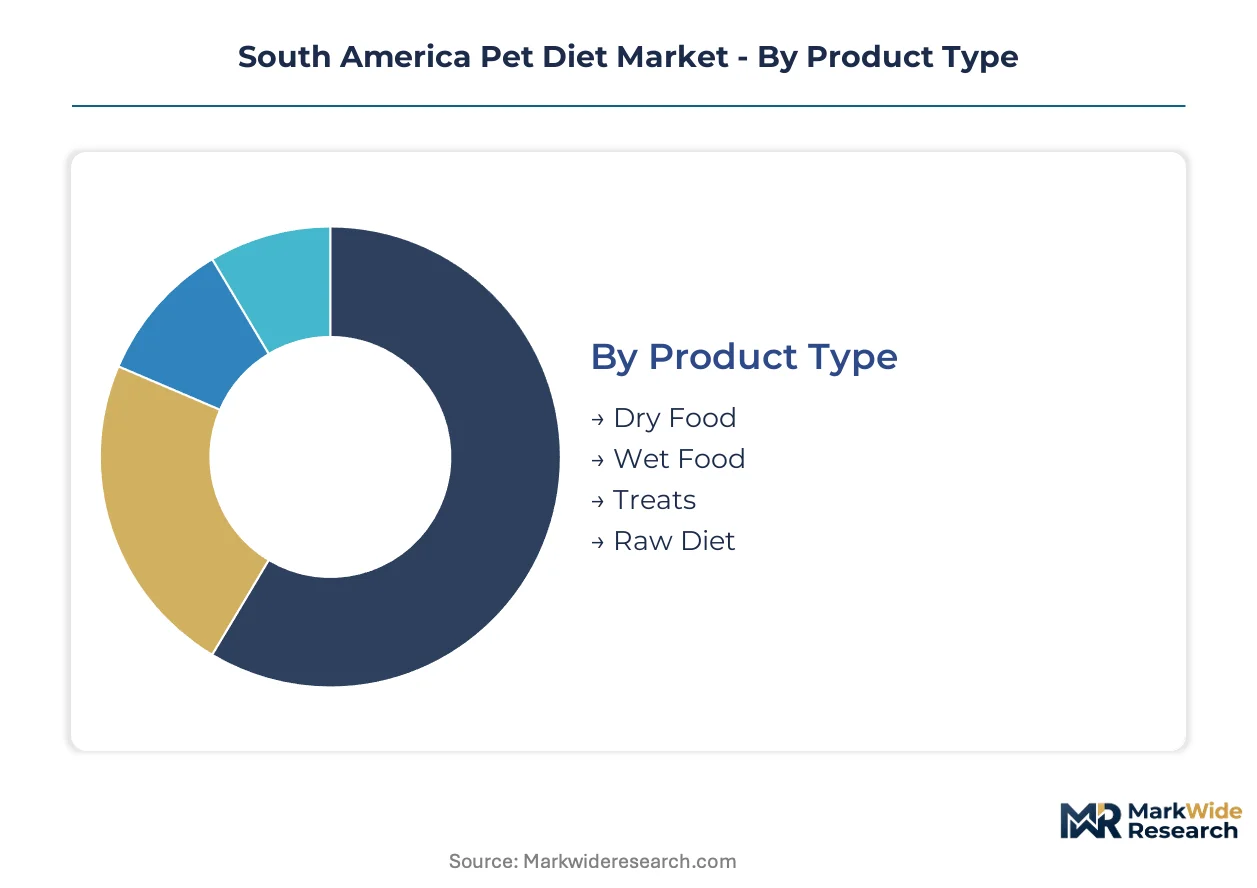
Pet diet manufacturers in South America deploy differentiated formulation and channel strategies across four intersecting dimensions. Each segmentation axis reveals distinct margin structures, regulatory exposure, and competitive intensity patterns that shape portfolio investment priorities.
Product Type:
Standardization dominates extruded formats while customization accelerates in fresh and raw alternatives, reflecting divergent supply chain economics across the moisture-content spectrum.
- Dry Food:Extruded kibble processed above 120 degrees Celsius delivers shelf stability and nutrient density through precise macronutrient calibration. São Paulo metro veterinary clinics now prescribe therapeutic dry formulations for diabetes management and renal support, displacing retail purchases through subscription-based replenishment programs.
- Wet Food:Canned and pouch formats with elevated moisture content address hydration requirements in aging feline populations and post-surgical recovery protocols. Rio de Janeiro's premium pet specialty stores report concentrated demand for limited-ingredient wet diets targeting food sensitivity cases.
- Treats:Functional reward products with dental or joint health claims occupy mid-tier price positioning in Brazilian supermarkets.
- Raw Diet:Frozen and freeze-dried formats preserve bioactive enzymes through minimal thermal processing, attracting affluent urban consumers in Brazil's southeastern corridor seeking biologically appropriate feeding protocols.
Leading the category by volume: Dry Food. Expanding most quickly: Raw Diet.
Ingredient Source:
Cost tier stratification separates commodity protein inputs from certified specialty streams, with certification premiums widening across Brazilian retail channels.
- Meat-Based:Poultry, beef, and fish meals provide complete amino acid profiles through rendered protein concentrates. Argentina's import dependency for specialized meat proteins creates supply vulnerability for therapeutic formulations, while Brazilian producers leverage local poultry integration for cost advantage.
- Grain-Free:Tapioca, pea, and lentil carbohydrate substitutes eliminate gluten and corn from macronutrient matrices. São Paulo pet owners with breed-specific sensitivity concerns drive veterinary recommendations for grain-free protocols in brachycephalic and dermatitis-prone populations.
- Plant-Based:Soy and pulse protein isolates address emerging sustainability preferences among urban Brazilian millennials.
- Others:Insect protein and cultured meat alternatives remain experimental in regional R&D pipelines.
Meat-Based formulations command the largest revenue share. Grain-Free alternatives gain share fastest among premium-positioned portfolios.
End User:
Customer type determines margin capture location, with institutional buyers extracting value through formulation partnerships rather than transactional purchasing.
- Veterinary Clinics:Prescription diet programs capture margin previously flowing through retail tiers, with São Paulo clinic chains consolidating ordering platforms into practice management software. ANVISA's therapeutic claim requirements elevate compliance costs but reinforce quality differentiation for certified manufacturers.
- Pet Owners:Direct purchasing concentrates in Brazil's southeastern urban corridor where aging companion animal demographics sustain premium nutrition spending.
- Pet Stores:Specialty retailers in Rio de Janeiro and Buenos Aires curate premium and super-premium assortments with nutritionist consultation services.
- Online Retailers:E-commerce platforms bypass traditional distributor markups through direct-to-consumer fulfillment.
Veterinary Clinics now lead volume growth. Pet Owners remain the largest absolute consumption base.
Distribution Channel:
Geographic concentration in Brazil's southeastern corridor shapes channel profitability, with urban density enabling alternative format experimentation.
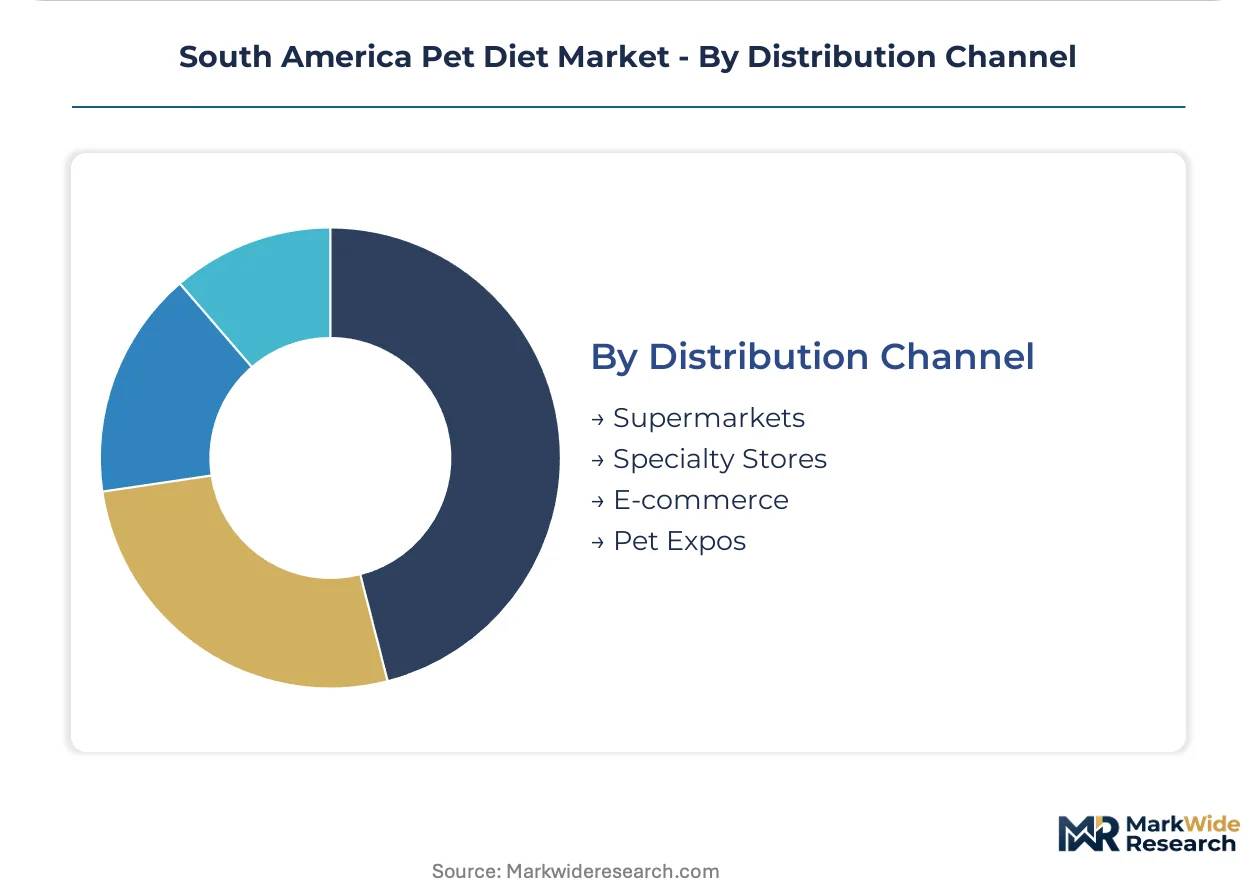
- E-commerce:Direct-to-clinic digital platforms and consumer-facing auto-ship programs displace traditional wholesale tiers. São Paulo veterinary practices pilot subscription models tied to wellness plan memberships, ensuring compliance continuity in chronic disease management categories.
- Specialty Stores:Independent pet retailers in Rio de Janeiro differentiate through nutritionist consultation and therapeutic diet access.
- Supermarkets:Mass retail anchors volume in mid-tier dry food segments with price-promotional mechanics.
- Pet Expos:Trade and consumer exhibition circuits in Buenos Aires and Santiago generate trial conversion for emerging brands.
Supermarkets retain volume leadership. E-commerce demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil's southeastern urban corridor, where São Paulo and Rio de Janeiro metro areas generate the majority of premium pet nutrition consumption. Argentina's veterinary channel expansion and Chile's underpenetrated markets present complementary growth vectors.
Brazil
Veterinary clinic consolidation in São Paulo and Rio de Janeiro is restructuring prescription diet distribution, with subscription-based auto-ship programs now capturing margin previously flowing through retail tiers. ANVISA's updated labeling mandates are accelerating transparency competition among manufacturers. The southeastern corridor anchors regional production scale, with extrusion facilities clustered around São Paulo state supplying dry food formats across Mercosur.
Argentina
Buenos Aires pet specialty retailers are curating premium therapeutic assortments with nutritionist consultation services to differentiate against clinic channels. The national food safety regulator enforces parallel import controls and local production facility standards that elevate compliance costs for foreign entrants. Clinic chains in the capital region are piloting direct-to-consumer digital platforms to bypass traditional distributor markups.
Chile
Santiago and Valparaíso present first-mover opportunities for prescription diet programs given underpenetrated veterinary channel infrastructure. Local regulations align with Mercosur harmonization discussions, potentially streamlining cross-border manufacturing compliance. Specialty retailers in Santiago's affluent districts are introducing limited-ingredient wet diets targeting food sensitivity cases in aging feline populations.
Colombia
Bogotá's urban pet owner base is expanding premium nutrition spending as companion animal aging demographics shift toward therapeutic and wellness portfolios. The national sanitary regulator maintains import inspection protocols that create supply vulnerability for specialized formulations. E-commerce platforms in the capital region are displacing traditional wholesale tiers through direct-to-clinic fulfillment models.
Uruguay
Montevideo's concentrated affluence supports niche demand for raw and cold-pressed diet formats among biologically appropriate feeding advocates. Regulatory alignment with Mercosur standards reduces cross-border friction for Brazilian manufacturers. Veterinary practices in the capital are exploring wellness plan memberships tied to chronic disease management categories.
South America Pet Diet Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fresh-format and subscription-based distribution models. The market structure reflects moderate consolidation, with multinational nutrition conglomerates anchoring volume through manufacturing scale while regional protein integrators compete on cost-efficient mid-tier positioning. Three archetypes dominate: global R&D-driven formulators, local supply-chain-integrated producers, and veterinary-channel-specialized therapeutic brands. Competitive intensity centers on formulation partnerships with consolidating clinic chains and backward integration into captive protein sourcing.
Among global nutrition conglomerates, Mars Incorporated and Nestlé Purina PetCare exemplify scale-driven archetypes with extensive Brazilian manufacturing footprints. BRF S.A. represents the regional protein-integrator model, leveraging localized supply chains for cost positioning. These three anchors demonstrate how competitive advantage in South American pet nutrition increasingly depends on veterinary channel relationships rather than retail shelf presence alone.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé Purina PetCare |
| BRF S.A. |
| PremieRpet Holding |
| Empresas Carozzi S.A. |
| Colgate-Palmolive Company |
| Alltech |
| Hill's Pet Nutrition |
| Grupo Pilar |
| Others |
Pricing and Supply Chain Analysis
Brazilian poultry meal price indices cascade through South American pet diet manufacturing, compressing mid-tier dry food margins while elevating premium therapeutic tier spreads. ANVISA compliance investments and São Paulo state logistics costs stratify final pricing across veterinary clinic, specialty retail, and mass-market channels.
Pricing Analysis
Volume concentrates in economy-tier extruded kibble while margin pools in subscription-based therapeutic diets. Price differentiation rests on certification grade and veterinary channel access, with ANVISA therapeutic claim status commanding substantial premiums. Cost compression in mid-tier poultry-based formulations is intensifying because Brazilian agricultural commodity cycles pressure feed input costs. Mass-market supermarket buyers exhibit highest price sensitivity; São Paulo clinic chains with wellness plan memberships show lowest.
Supply Chain Analysis
Workforce availability for extrusion technicians and veterinary nutritionists constrains capacity expansion in São Paulo state and Rio de Janeiro manufacturing clusters. Geographic supply concentration centers on Brazil, Argentina, and Chile, with Brazilian producers leveraging localized poultry integration for cost advantage. Raw material dependencies include rendered poultry meal, tapioca starch, and fish oil concentrates. Single-source vulnerability runs through Brazilian poultry protein integration. Distribution runs through consolidating veterinary clinic chains displacing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American pet nutrition is transitioning from commodity extrusion to precision formulation technologies, with cold-pressed processing and high-pressure pasteurization displacing legacy high-temperature methods.
For Market Incumbents: Extend formulation partnerships with consolidating São Paulo clinic chains to lock in prescription diet distribution before competitor entry. Deepen backward integration into captive poultry rendering capacity to defend against Brazilian agricultural commodity volatility. ANVISA therapeutic claim certification investment represents the critical defensive lever against emerging cold-pressed format substitutes.
For New Entrants and Emerging Players: The premium-economy price-point gap in Argentine therapeutic diets offers white-space positioning for import-dependent specialized formulations. Chile's underpenetrated Santiago veterinary channel infrastructure presents first-mover opportunity for subscription-based auto-ship programs. Direct-to-clinic digital platform go-to-market angles bypass legacy distributor markups.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier dry food producers with São Paulo manufacturing footprints during Brazilian poultry input cost spikes. Long-term viability over the projection horizon hinges on veterinary channel relationship depth rather than retail shelf presence alone. Monitor ANVISA Mercosur harmonization progress as inflection indicator for cross-border manufacturing consolidation plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership Expansion | São Paulo clinic chain consolidation locks in prescription diet distribution before competitor entry. |
| Cold-Pressed Processing Adoption | High-pressure pasteurization preserves bioactive enzymes for limited-ingredient premium lines. |
| Subscription-Based Replenishment Launch | Auto-ship programs tied to wellness plans ensure compliance continuity in chronic disease categories. |
| ANVISA Therapeutic Certification Investment | Compliance differentiation elevates capital barriers against unqualified new entrants. |
| Backward Integration into Poultry Rendering | Captive protein sourcing insulates margins from Brazilian agricultural commodity volatility. |
Research Methodology
Document review covered ANVISA regulatory filings, Mercosur trade databases, and Brazilian veterinary clinic chain financial disclosures, complemented by interviews with pet food formulation scientists, São Paulo clinic operations directors, Argentine specialty retail buyers, and Chilean import distributors. Secondary validation drew from ANVISA manufacturing facility registrations, Brazilian agricultural commodity price indices, and clinic chain practice management software vendor disclosures. Bottom-up demand modeling and top-down supply capacity assessments were cross-referenced for triangulation.
Cross-reference between historical pricing elasticity patterns and expert panel input on veterinary channel shift velocity anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product moisture format, ingredient certification tier, end-user channel type, and geographic urban density cluster. CAGRs were derived from demand buildup across clinic subscription conversions, retail channel displacement rates, and raw material cost pass-through assumptions. Forecast inputs incorporated ANVISA regulatory timeline uncertainty and Mercosur harmonization progress indicators.
Inputs from ANVISA facility inspection reports and São Paulo state manufacturing employment data were available through the study window; gaps in real-time Argentine import volume statistics introduce uncertainty bands around Buenos Aires demand estimates. Forecasts reflect documented assumptions on veterinary consolidation velocity and cold-pressed technology adoption curves. Material deviation in Brazilian poultry commodity price spikes or ANVISA labeling mandate enforcement timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Omega-3 Pet Supplement Market
Pet Care Products
Pet Hotels Market
Pet Care Products
Elevated Dog Bowls Market
Pet Care Products
US Pet Boarding Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Dog Seat Belt Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
Pet Care Ingredients Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
Pet Hair Brush Market
Pet Care Products
Pet Clothing Market
Pet Care Products
Italy Pet Food Market
Pet Care Products
Netherlands Pet Food Market
Pet Care Products
Pet Gadgets Market
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
Dog Treats Market