
 Plant-Based Pet Food Market | 2026-2036
Plant-Based Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Pet Food Market Outlook
The gap between premium plant-based formulations and commodity-grade alternatives is expanding, with ingredient provenance and protein digestibility scores splitting the competitive landscape. Nestlé Purina leverages its veterinary nutrition research infrastructure to anchor clinical credibility for high-margin SKUs. Mars, Incorporated sustains broad retail penetration through shelf-stable dry food lines stocked in mass-market channels. Wild Earth, Inc. differentiates via fungal protein fermentation technology that delivers complete amino acid profiles without conventional agriculture inputs.
Plant-based pet food denotes formulated nutrition products deriving primary protein and caloric content from non-animal biomass including legume isolates, oilseed meals, and microbial biomass, manufactured through extrusion, retort processing, or cold-pressing to achieve target macronutrient density and shelf stability for carnivore and omnivore companion species. Dry food occupies the dominant volume position due to logistics efficiency and extended shelf life, though wet food commands disproportionate margin pools from freshness-positioned consumers. Pea protein leads ingredient source adoption for its functional binding properties and low allergenicity profile in canine formulations, while sweet potato bases gain traction in limited-ingredient diets targeting digestive sensitivity. Online retail channels capture the fastest growth trajectory as direct-to-consumer subscription models bypass traditional pet store markups and enable personalized formulation matching.
The FDA Center for Veterinary Medicine oversees ingredient safety and labeling claims for plant-based pet food distributed in the United States, while the EU Feed Hygiene Regulation and EFSA nutritional adequacy protocols govern commercialization across European member states. These frameworks elevate compliance costs for new entrants but simultaneously validate product safety narratives that convert skeptical veterinarians and pet owners. Stakeholders must monitor evolving AAFCO nutrient profiles and emerging state-level packaging sustainability mandates as these standards will determine which formulations retain shelf access and which face reformulation deadlines.
Market Dynamics
The divergence between veterinary-grade clinical validation and commodity positioning is compressing mid-tier margins, forcing manufacturers to commit capital to either fermentation infrastructure or mass-market distribution scale.
Growth Catalysts
- Fungal protein fermentation:Precision-controlled mycelium cultivation delivers complete amino acid profiles without agricultural land use, attracting sustainability-positioned urban consumers.
- EU Feed Hygiene Regulation:Harmonized ingredient safety standards across member states reduce cross-border compliance friction for formulated products.
- Subscription commerce:Direct-to-consumer replenishment models bypass pet specialty retail markups and enable personalized macronutrient matching.
Market Restraints
- Pea protein price volatility:Crop yield fluctuations in Canada and Ukraine concentrate input cost risk for legume-dependent formulations.
- AAFCO nutrient profile gaps:Incomplete feline taurine and arachidonic acid guidelines create regulatory uncertainty for cat food commercialization.
- Veterinary skepticism:Clinician preference for ancestral carnivore diets limits prescription channel access for plant-based alternatives.
Strategic Opportunities
- Senior pet nutrition:Geriatric renal support formulations with controlled phosphorus and enhanced palatability address expanding companion animal longevity.
- Indian urban markets:Emerging pet humanization in Mumbai and Bangalore creates first-mover advantage for localized lentil-protein recipes.
- Blockchain traceability:Immutable ingredient provenance records satisfy EFSA transparency mandates and command retail price premiums.
Industry Challenges
- Clinical trial capacity:Extended feeding study timelines for digestibility validation strain veterinary research infrastructure.
- Extrusion equipment retrofitting:Legacy pet food manufacturing lines require capital-intensive modification to process high-fiber plant matrices without thermal degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Pet Food Market |
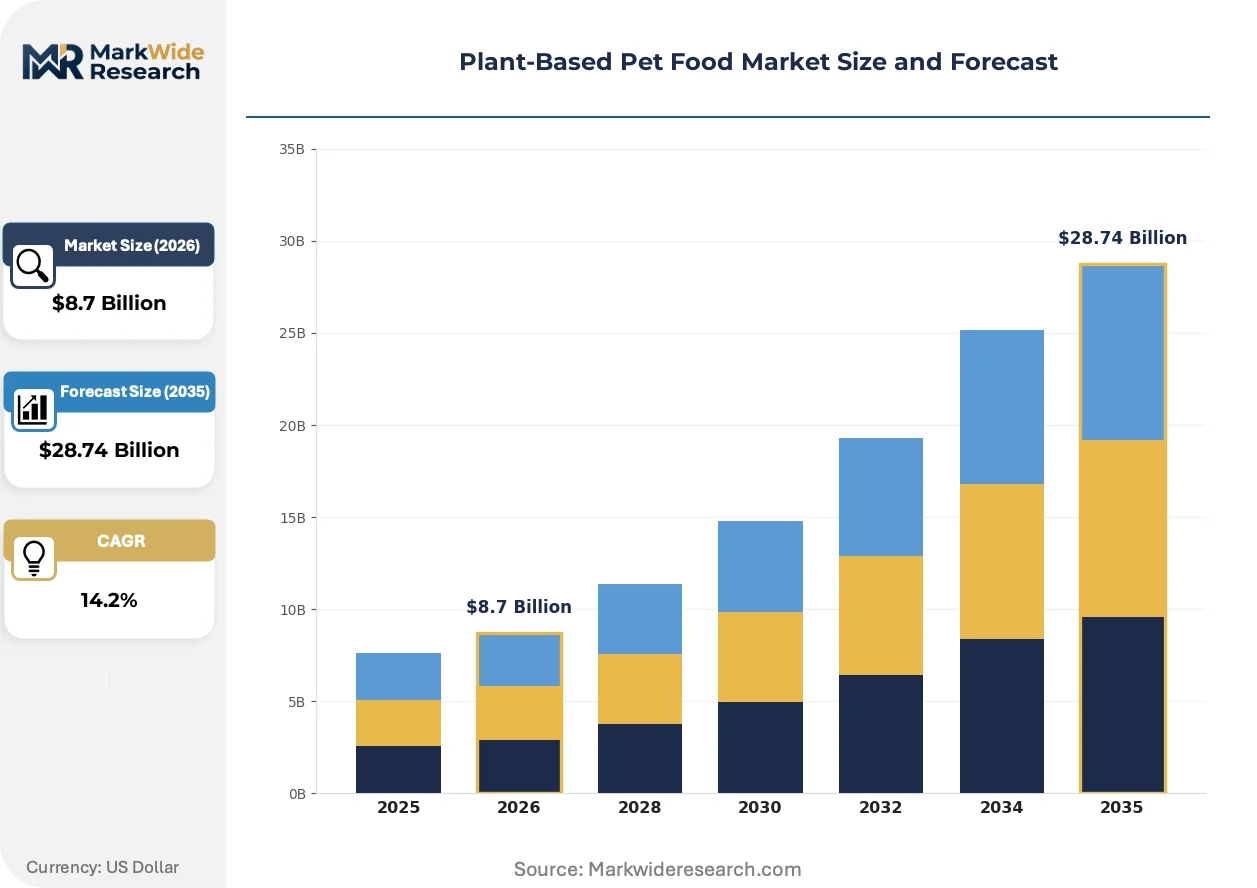
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Source: Pea Protein, Lentils, Quinoa, Sweet Potatoes Target Animal: Dogs, Cats, Rabbits, Birds Distribution Channel: Online Retail, Pet Stores, Supermarkets, Specialty Shops |
| Companies Covered | Nestlé Purina, Mars, Incorporated, Wild Earth, Inc., Yarrah Organic Petfood B.V., Vegeco Ltd., Benevo, V-dog, Amì Pet Food, Antos B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Pet Food Market Strategic Shifts
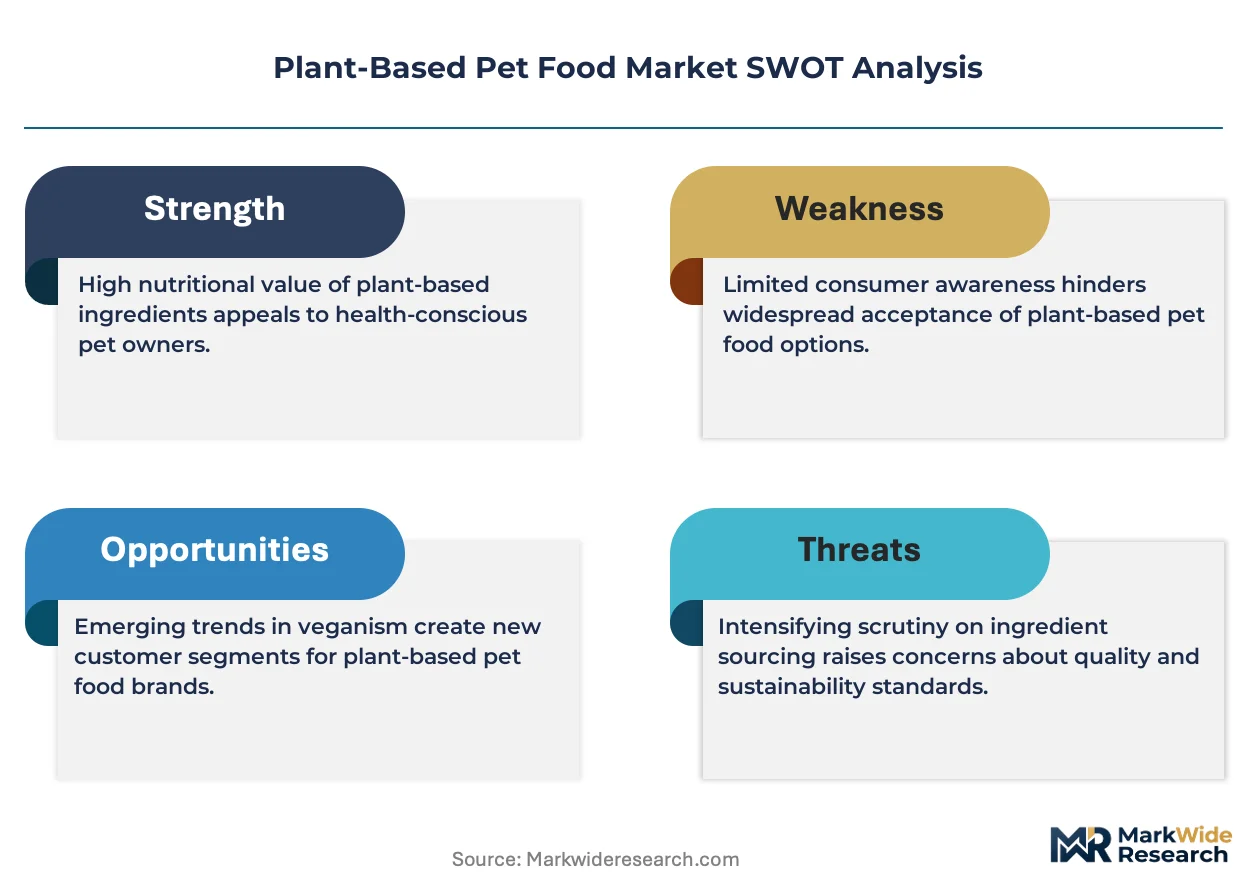
Biotechnology-enabled protein production and regulatory transparency mandates are converging to reshape formulation credibility and supply chain accountability.
Precision fermentation of fungal biomass is consolidating protein sourcing away from conventional agriculture. Urban millennial pet owners in Germany and the United Kingdom are adopting these formulations at accelerated rates. The technology is consolidating supplier power among biotech-enabled manufacturers while compressing margins for commodity legume processors.
EFSA nutritional adequacy protocols are tightening substantiation requirements for complete-and-balanced claims. Pet food manufacturers must now submit digestibility data from controlled feeding studies before market authorization. Wet food specialists targeting veterinary channels face the steepest compliance burden and are consolidating regulatory affairs functions.
Subscription-based replenishment is displacing episodic pet store purchasing among digitally native consumers. Direct-to-consumer platforms in the United States are capturing recurring revenue through automated portion-calibration algorithms. This shift is most visible among urban dog owners seeking convenience without nutritional compromise.
Plant-Based Pet Food Market Segmentation
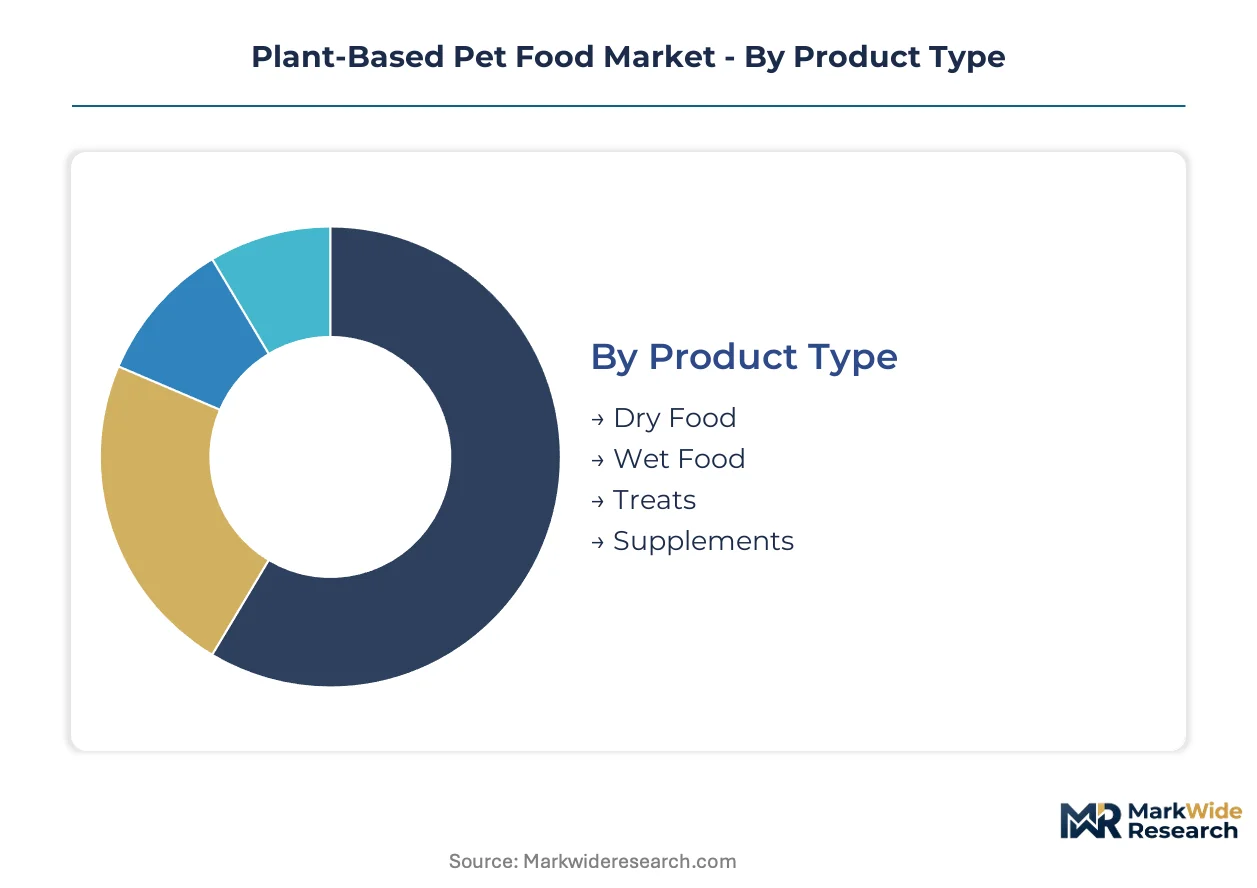
Plant-based pet food manufacturers segment their offerings across four critical dimensions that determine formulation complexity, regulatory pathway, and channel economics. Each category reflects distinct technical requirements and purchasing behaviors that shape competitive positioning.
Product Type:
Dry formulations operate as standalone nutrition systems with extended shelf stability, while wet and supplemental formats embed into broader feeding routines with different margin structures.
- Dry Food:Extruded kibble formulations achieve 12-18 month shelf life through moisture reduction below 10%. German and United Kingdom urban millennial owners drive demand for high-protein legume-based recipes with fungal protein fortification. Logistics efficiency and bulk purchasing patterns cement this segment's volume leadership.
- Wet Food:Retort-processed cans and pouches deliver 75-85% moisture content with enhanced palatability for selective eaters. Veterinary channels in the United States favor these formulations for renal support and senior pet applications where hydration compliance matters.
- Treats:Bite-sized formats with concentrated flavor profiles serve training reinforcement and bonding rituals.
- Supplements:Powder and chewable formats address targeted nutritional gaps including taurine, omega fatty acids, and digestive enzymes.
Volume placements concentrate in Dry Food; the faster expansion belongs to Wet Food.
Ingredient Source:
Cost tier differentiation separates commodity legume processors from precision fermentation operators with proprietary strain libraries.
- Pea Protein:Isolated protein fractions from yellow peas provide functional binding and 80%+ protein concentration. Canadian crop volatility creates input cost pressure for formulations dependent on North American supply.
- Lentils:Red and green lentil meals offer complementary amino acid profiles to pea-based bases. Indian urban markets in Mumbai and Bangalore show emerging preference for locally sourced lentil proteins in price-sensitive formulations.
- Quinoa:Andean-sourced complete protein delivers all nine essential amino acids without blending complexity.
- Sweet Potatoes:Starch-rich tuber bases support limited-ingredient diets targeting canine digestive sensitivity and glycemic control.
Cost-sensitive manufacturers anchor formulations in Pea Protein; premium positioning climbs fastest through Quinoa.
Target Animal:
Species-specific metabolic requirements dictate formulation rigor, with obligate carnivores demanding more stringent amino acid supplementation than omnivore companions.
- Dogs:Omnivore digestive physiology accommodates diverse plant protein sources with appropriate amino acid fortification. United States direct-to-consumer subscription platforms capture disproportionate share among urban dog owners seeking convenience.
- Cats:Obligate carnivore metabolism requires synthetic taurine, arachidonic acid, and preformed vitamin A supplementation. FDA Center for Veterinary Medicine scrutiny intensifies for feline formulations claiming complete nutrition status.
- Rabbits:Herbivore digestive systems align naturally with plant-based feeding, reducing formulation complexity.
- Birds:Seed and pellet conversions face species-specific acceptance challenges requiring gradual transition protocols.
Commercial investment concentrates in Dogs; regulatory validation timelines extend longest for Cats.
Distribution Channel:
Customer type stratification separates digitally native subscribers from episodic brick-and-mortar purchasers with distinct lifetime value profiles.
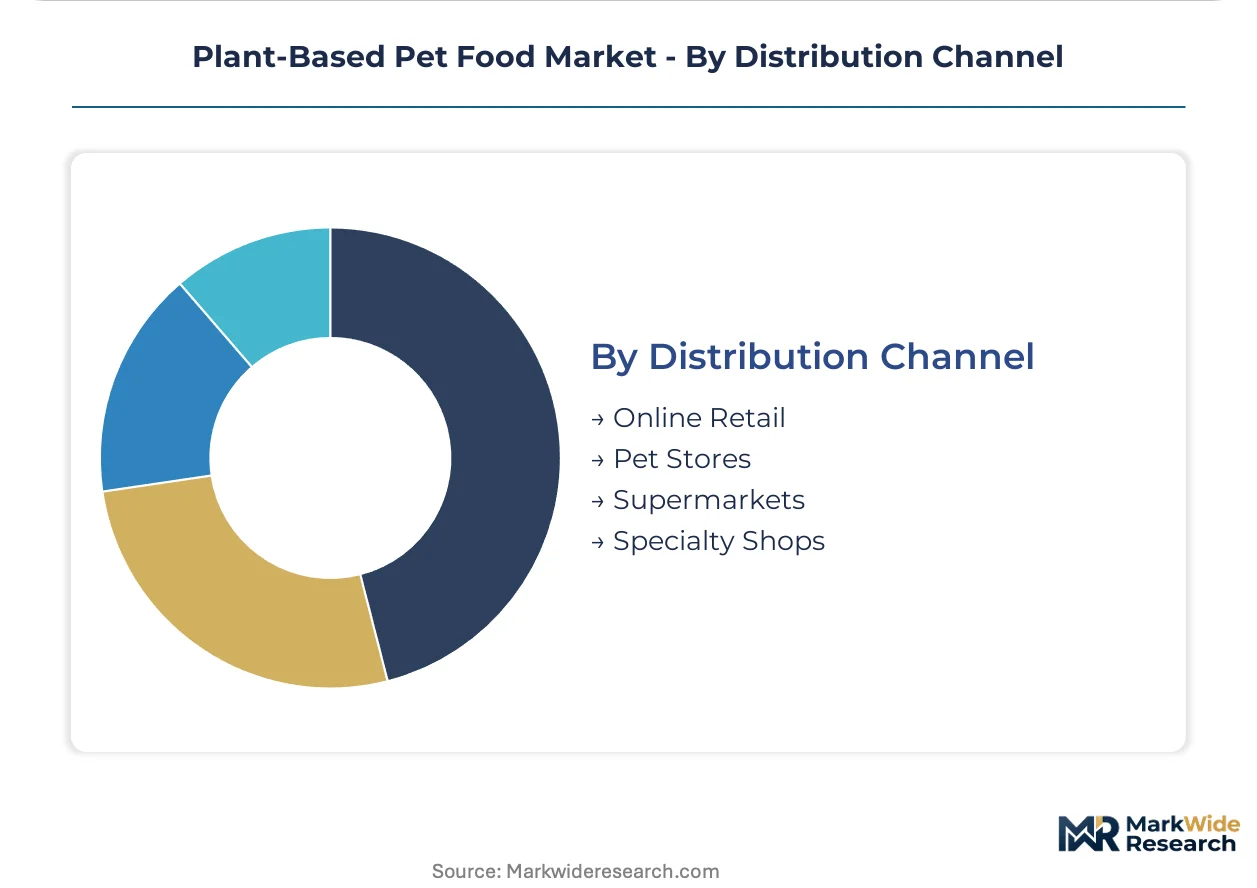
- Online Retail:Direct-to-consumer platforms bypass traditional retail markups through automated replenishment algorithms. Urban United States markets show highest penetration of subscription models with personalized portion calibration.
- Pet Stores:Specialty retailers provide tactile product evaluation and staff consultation for first-time plant-based converters.
- Supermarkets:Mass-market placement demands price competitiveness and shelf-stable packaging for inventory turnover.
- Specialty Shops:Veterinary clinics and boutique nutrition centers command premium pricing through clinical credibility endorsement.
Transaction volume concentrates in Pet Stores; customer acquisition efficiency gains share fastest through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin anchors European plant-based pet food innovation, hosting multiple precision fermentation startups and regulatory affairs consultancies serving the EU single market. Urban millennial pet ownership in German metropolitan corridors drives formulation sophistication ahead of neighboring markets.
United States
Direct-to-consumer subscription platforms capture disproportionate share among urban dog owners in San Francisco, Los Angeles, and New York seeking convenience without nutritional compromise. FDA Center for Veterinary Medicine oversight of ingredient safety and labeling claims elevates compliance costs but validates product credibility. California's packaging sustainability mandates are forcing reformulation timelines for manufacturers targeting West Coast retail access.
Germany
EU Feed Hygiene Regulation harmonization reduces cross-border compliance friction for formulated products distributed across member states. EFSA nutritional adequacy protocols tighten substantiation requirements for complete-and-balanced claims before market authorization. Munich and Hamburg industrial clusters concentrate wet food specialists targeting veterinary channels with renal support formulations.
United Kingdom
Post-Brexit regulatory divergence from EU standards creates dual compliance burdens for manufacturers serving both markets. Urban millennial adoption in London and Manchester accelerates faster than continental European peers. British specialty pet retailers provide tactile product evaluation and staff consultation for first-time plant-based converters.
India
Emerging pet humanization in Mumbai and Bangalore creates first-mover advantage for localized lentil-protein recipes at price-sensitive entry points. FSSAI oversight of pet food labeling remains less prescriptive than Western counterparts, enabling faster commercialization cycles. Maharashtra and Karnataka industrial corridors attract contract manufacturing investment from multinational brands.
Australia
TGA-aligned state regulators enforce ingredient safety standards for imported plant-based formulations. Sydney and Melbourne urban pet owners show accelerating interest in fungal protein alternatives. Local quinoa sourcing from South Australian growers supports premium positioning for limited-ingredient diets.
Plant-Based Pet Food Market Competitive Environment
Premium-margin players sit above commodity-margin players across protein sourcing and clinical validation dimensions. The competitive structure stratifies between multinational nutrition conglomerates with veterinary research infrastructure, biotechnology-enabled fermentation specialists, and regional organic formulators with localized supply chains. Three archetypes dominate: scale-driven mass-market distributors, precision fermentation technology licensors, and certified-organic niche producers. Consolidation pressure is intensifying through strategic partnerships between ingredient suppliers and finished goods manufacturers, alongside capacity expansion in fungal protein cultivation facilities.
Within the multinational nutrition tier, Nestlé Purina and Mars, Incorporated anchor mass-market penetration through contrasting channel strategies. Wild Earth, Inc. exemplifies the biotechnology archetype with fungal protein fermentation positioning. Among European organic specialists, Yarrah Organic Petfood B.V. and Benevo occupy certified-production positions serving regulatory-sensitive markets.
| Leading Market Players |
|---|
| Nestlé Purina |
| Mars, Incorporated |
| Wild Earth, Inc. |
| Yarrah Organic Petfood B.V. |
| Vegeco Ltd. |
| Benevo |
| V-dog |
| Amì Pet Food |
| Antos B.V. |
| Others |
Value Chain & Pricing Dynamics
Clinical-grade certification divergence splits the market between veterinary-endorsed formulations and commodity legume alternatives, with EFSA nutritional adequacy protocols and AAFCO nutrient profiles creating tiered compliance costs that concentrate supply chain investment in Germany and the United States while compressing margins for Canadian pea protein processors.
Pricing Analysis
Subscription-based recurring revenue anchors pricing for direct-to-consumer platforms serving urban dog owners in San Francisco and New York. Three-tier pricing structure across premium, standard, and economy levels separates fungal protein formulations with complete amino acid profiles from blended legume recipes and commodity-grade extruded kibble. Cost compression in mid-tier wet food is intensifying because extrusion equipment retrofitting demands capital outlays that smaller manufacturers cannot absorb. Price-sensitive entry points in Indian urban markets contrast with premium positioning among British specialty retailers.
Supply Chain Analysis
Freight cost differentials between North American legume corridors and European precision fermentation hubs concentrate input sourcing decisions. Canada, Ukraine, and India anchor global pea and lentil protein supply. Formulations draw from yellow pea isolates, fungal mycelium biomass, and Andean quinoa. Single-source vulnerability in Canadian crop yields threatens input cost stability for legume-dependent manufacturers. Distribution runs through direct-to-consumer subscription platforms, pet specialty retailers, and veterinary clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation infrastructure scarcity props pricing for biotech-enabled protein suppliers, constraining volume expansion for brands dependent on conventional agriculture inputs.
For Market Incumbents: Anchor clinical credibility through controlled feeding study investments that satisfy EFSA nutritional adequacy protocols before competitors achieve veterinary channel access. Deepen backward integration into fungal protein cultivation facilities to secure captive supply of complete amino acid biomass. Certification investment in blockchain traceability systems addresses emerging European transparency mandates while creating switching costs for retail partners. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting urban cat owners in London and Manchester, where post-Brexit regulatory divergence has slowed incumbent response times. White-space opportunity concentrates in feline taurine-fortified formulations where AAFCO guideline gaps delay multinational commercialization. Localized lentil-protein recipes for price-sensitive Indian households in Mumbai and Bangalore offer faster regulatory cycles under FSSAI oversight. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation technology licensors given EU Feed Hygiene Regulation harmonization accelerating cross-border market access. Long-term viability across the analysis window favors biotech-enabled manufacturers with proprietary strain libraries over commodity legume processors exposed to crop volatility. Acquisition targets should demonstrate veterinary research partnerships and digestibility data portfolios. The signal to watch is FDA Center for Veterinary Medicine guidance clarity on feline nutritional adequacy claims.| Strategic Initiative | Industry Significance |
|---|---|
| Fungal Protein Fermentation Scale-Up | Precision mycelium cultivation secures complete amino acid supply without agricultural land use constraints. |
| Veterinary Research Partnership | Clinical feeding studies with university veterinary schools validate complete-and-balanced claims for regulatory submission. |
| Direct-to-Consumer Platform Launch | Subscription algorithms bypass pet specialty retail markups and enable personalized macronutrient matching. |
| Blockchain Traceability Implementation | Immutable ingredient records satisfy EFSA transparency mandates and command retail price premiums. |
| Extrusion Equipment Retrofit | Legacy line modification enables high-fiber plant matrix processing without thermal degradation in kibble production. |
Study Parameters
Trade publications, regulatory filings, and veterinary nutrition journals formed the secondary backbone for initial market sizing and competitive mapping. Primary interviews with pet food formulation scientists, regulatory affairs consultants, veterinary nutritionists, and specialty retail buyers grounded qualitative assessments of adoption barriers and channel dynamics. Bottom-up volume modeling from ingredient sourcing data and top-down value validation from retail audit sources were triangulated against subscription platform disclosures.
Historical trendline analysis of plant-based pet food commercialization patterns informed projection assumptions across the modeling period. Segmentation dimensions included product format, protein source technology, target species metabolic requirements, and distribution channel economics. CAGRs were derived from fitted growth curves adjusted for regulatory authorization timelines and veterinary endorsement velocity. Forecast inputs incorporated fungal protein fermentation capacity expansion schedules and EU member state adoption differential.
Pea protein price volatility, AAFCO feline nutrient guideline revisions, and veterinary clinician sentiment shifts are the dominant revision risks to volume and value assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Nail Clippers Market
Pet Care Products
South Africa Pet Food Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
UK Pet Boarding Market
Pet Care Products
Poland Pet Food Market
Pet Care Products
Japan Pet Clothing Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
Small Breed Dog Food Market
Pet Care Products
Vegan Cat Food Market
Pet Care Products
Electric Pet Clippers Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Pet Oral Care Market
Pet Care Products
Pet Grooming Market
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
Cat Harness Market