
 South America Dog Food Market | 2026-2036
South America Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
South America Dog Food Market Insights
Urban millennial pet owners is bifurcating from price-driven rural households as the dominant buyer archetype across Brazil and Argentina. Mars Incorporated leverages its veterinary channel partnerships to sustain premium positioning in São Paulo's specialty retail corridors. Nestlé Purina PetCare anchors its regional supply chain through localized manufacturing in Brazilian industrial zones. BRF S.A. competes on protein sourcing integration, extending its poultry byproduct streams into economy-tier formulations for price-sensitive interior markets.
South America dog food encompasses formulated nutritional products meeting AAFCO canine nutrient profiles, manufactured through extrusion, canning, or freeze-drying processes designed to deliver complete diets for domestic dogs across varied life stages and breed sizes. Dry food dominates volume throughput due to shelf stability and lower logistics costs across Brazil's vast interior distribution networks, while super-premium and organic tiers capture expanding margin pools in urban coastal markets. Wet food and treats segments grow fastest through veterinary clinic and online retail channels, where subscription models and therapeutic positioning command pricing power.
ANVISA governs pet food sanitary registration and nutritional claims in Brazil, while Argentina's national food safety authority enforces equivalent labeling standards; both frameworks elevate compliance costs for imported formulations and favor locally manufactured products. Brazil's MAPA agricultural inspection protocols further shape ingredient traceability requirements, particularly for animal-derived protein sources. Stakeholders must monitor evolving Mercosur harmonization talks and shifting e-commerce tax structures to calibrate channel investments and localization strategies.
Market Dynamics
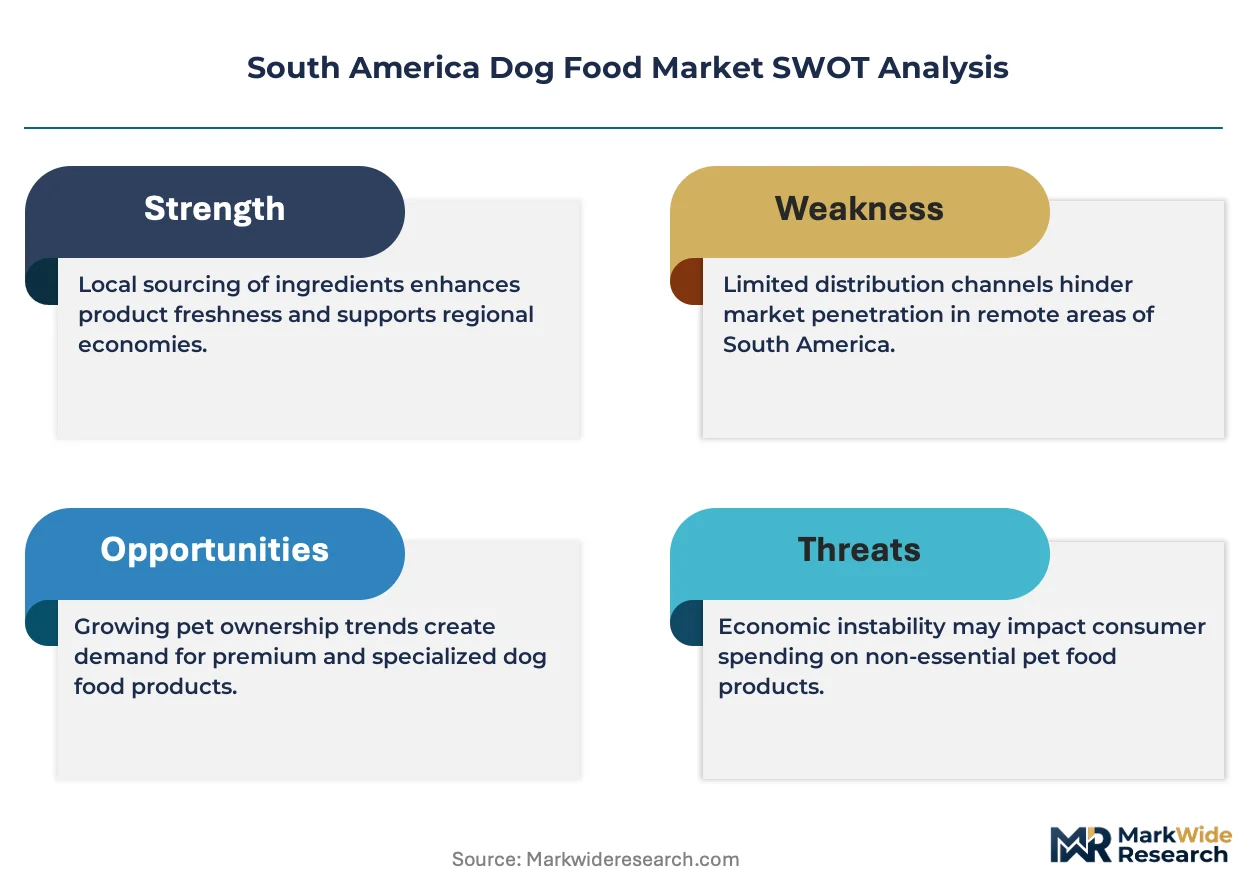
ANVISA nutritional labeling mandates are compressing formulation margins while accelerating premium tier migration among São Paulo's veterinary clinic channels, forcing manufacturers to absorb compliance costs or cede price-sensitive interior markets to local protein-integrated competitors.
Growth Catalysts
- ANVISA Nutritional Transparency Mandates:Brazil's sanitary regulator now requires detailed macronutrient disclosure on all commercial dog food packaging, elevating consumer trust in premium formulations and driving clinic-channel purchases in metropolitan corridors.
- Veterinary Clinic Channel Expansion:São Paulo and Rio de Janeiro veterinary networks are converting diagnostic appointments into therapeutic diet recommendations, capturing margin pools unavailable through supermarket retail.
- Freeze-Drying Process Adoption:Super-premium manufacturers are deploying low-temperature dehydration to preserve raw protein integrity, satisfying urban millennial demand for minimally processed nutrition formats.
Market Restraints
- Soybean Meal Price Volatility:Brazil's dependence on domestic soybean derivatives for plant-based protein concentrates exposes formulation costs to agricultural commodity swings and MAPA export quota fluctuations.
- Import Tariff Friction:Mercosur's unresolved harmonization talks perpetuate divergent e-commerce tax structures, complicating cross-border subscription fulfillment from Argentine manufacturing zones into Brazilian consumer markets.
- Wet Food Logistics Constraints:Refrigerated distribution infrastructure gaps across Brazil's interior states limit shelf-stable dry food dominance in remote municipalities, constraining therapeutic diet penetration.
Strategic Opportunities
- Subscription E-Commerce Models:São Paulo's urban density supports direct-to-consumer platforms bypassing traditional retail markups, enabling personalized portion algorithms based on breed-specific metabolic profiles.
- Argentine Pampas Protein Integration:Untapped bovine byproduct streams from Argentina's grass-fed cattle operations offer traceable novel protein sources for limited-ingredient allergy formulations targeting coastal Brazil.
- Organic Certification Tailwinds:Brazil's MAPA organic seal program is expanding eligibility criteria for pet food ingredients, opening premium positioning for producers achieving pesticide-free grain sourcing.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:São Paulo's specialty clinics face recruitment bottlenecks for professionals qualified to prescribe therapeutic diets, limiting conversion of diagnostic traffic into recurring food revenue.
- Legacy ERP Integration Friction:Established manufacturers struggle to synchronize batch traceability systems with ANVISA's digital sanitary registration portal, delaying product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Dog Food Market |
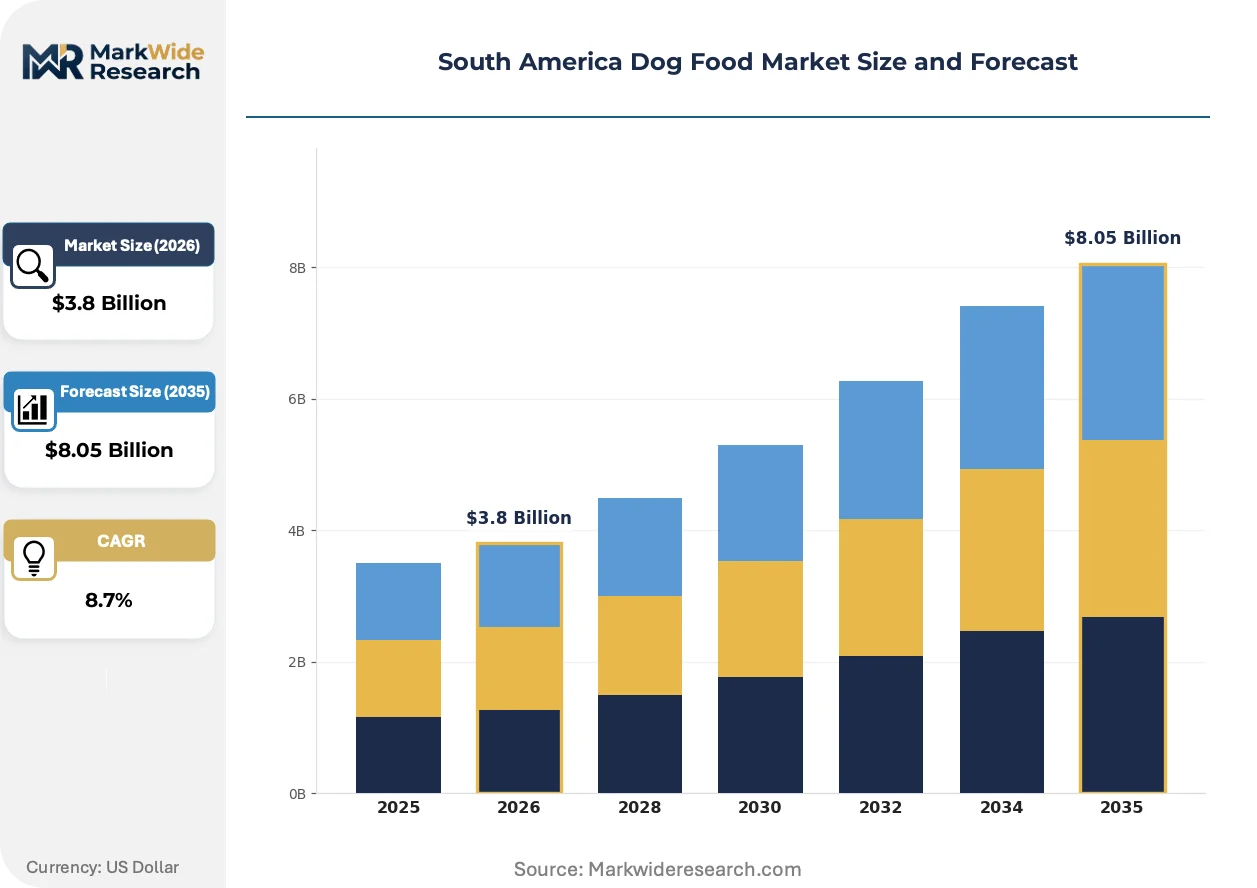
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Distribution Channel: Supermarkets, Pet Shops, Online Retail, Specialty Stores Customer Type: Pet Owners, Breeders, Shelters, Veterinary Clinics Pricing Tier: Economy, Premium, Super Premium, Organic |
| Companies Covered | Mars Incorporated, Nestlé Purina PetCare, BRF S.A., PremieRpet Holding, Empresas Carozzi S.A., Hill's Pet Nutrition, Grupo Pilar, Nutrire Indústria de Alimentos Ltda., Virbac, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Dog Food Market Trends and Innovations
Formulation science and distribution architecture are converging to reshape competitive positioning across South America's dog food landscape. Three distinct vectors are compressing traditional supply hierarchies while opening new margin pools.
Extrusion technology is miniaturizing. Small-batch thermal processing equipment now enables regional co-manufacturers to produce AAFCO-compliant kibble with capital outlays one-tenth of legacy industrial lines. Argentine mid-tier producers are adopting these compact systems to serve Brazil's interior states without national distribution infrastructure, fragmenting volume concentration previously held by São Paulo-based multinationals.
ANVISA's 2023 updated sanitary registration protocols are mandating real-time ingredient traceability through blockchain-enabled documentation. This regulatory compression is disqualifying informal protein suppliers and forcing documented chain-of-custody investments. Wet food and treat segments face the steepest compliance burden given their reliance on animal-derived inputs subject to MAPA agricultural inspection protocols.
Subscription bundling is displacing single-transaction purchasing. São Paulo's millennial pet owners are consolidating nutrition, treat, and supplement procurement into automated delivery cycles managed through veterinary clinic portals. This behavioral shift concentrates lifetime value capture with platforms achieving integration between diagnostic data and personalized feeding algorithms, marginalizing traditional supermarket shelf presence.
South America Dog Food Market Segmentation
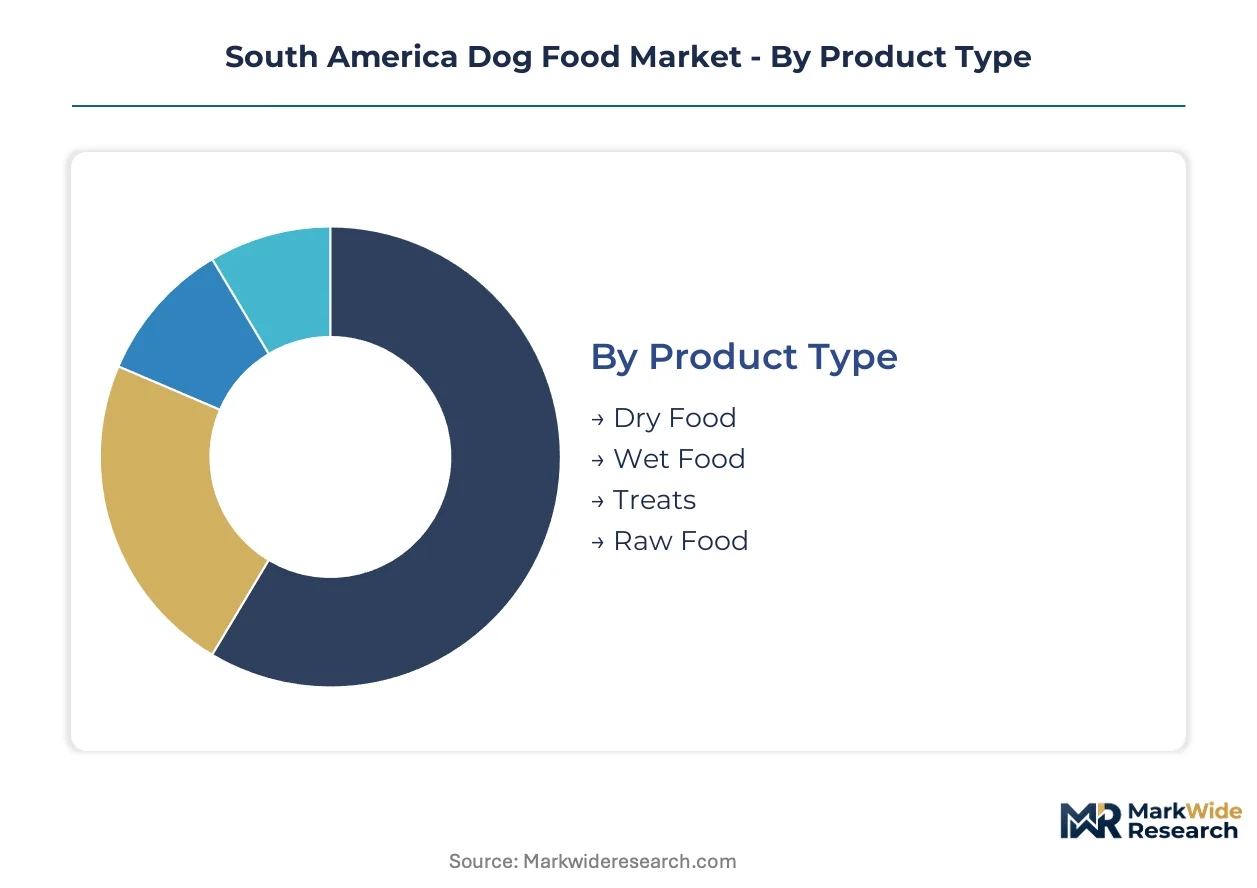
Segmentation in South America dog food reveals how formulation technology, channel infrastructure, and buyer sophistication intersect across Brazil's metropolitan corridors and Argentina's pampas regions. Each dimension exposes distinct margin pools and compliance burdens that manufacturers must navigate.
Product Type:
Dry food production concentrates in Brazilian industrial zones serving domestic mass-market demand, while wet food and raw formats draw more heavily on Argentine protein sourcing for export-adjacent coastal markets.
- Dry Food:Extruded kibble formulations achieve AAFCO nutrient density through thermal processing of grain-soy blends. São Paulo's veterinary clinic networks are converting diagnostic traffic into therapeutic dry food subscriptions, though interior logistics constraints favor shelf-stable dominance.
- Wet Food:Canned or pouched formulations with higher moisture content and animal-derived protein ratios. Refrigerated distribution gaps across Brazil's northern states limit penetration outside Rio de Janeiro and São Paulo metropolitan corridors, constraining therapeutic diet reach.
- Treats:Functional and reward formats positioned between meals.
- Raw Food:Minimally processed frozen or freeze-dried protein formats.
Dry food holds the largest share; momentum sits with wet food.
Distribution Channel:
Channel selection in this market maps directly to buyer sophistication tiers, with veterinary and online platforms capturing premium spend while supermarkets retain price-driven volume.
- Supermarkets:Mass retail shelf space dominated by economy-tier formulations with lower margins. Brazil's interior states depend on hypermarket chains for dog food access, though São Paulo's urban millennials are displacing this channel through subscription migration.
- Pet Shops:Specialty retail with trained staff and mid-tier assortment. Argentina's Buenos Aires corridor maintains independent pet shop density that Brazilian cities are losing to veterinary clinic consolidation.
- Online Retail:Direct-to-consumer platforms with algorithmic personalization.
- Specialty Stores:Premium-focused boutiques with curated super-premium assortments.
Supermarkets retain volume leadership; online retail is climbing the fastest.
Customer Type:
Buyer archetypes in South America diverge sharply between urban veterinary-integrated households and resource-constrained institutional purchasers.
- Pet Owners:Individual household purchasers driving premiumization. São Paulo's millennial demographic consolidates nutrition, treat, and supplement procurement into automated delivery cycles, capturing lifetime value through breed-specific metabolic algorithms.
- Breeders:Commercial kennel operations with volume procurement and formulation consistency requirements. Brazilian breeder associations in Rio Grande do Sul maintain direct manufacturer relationships bypassing retail markup.
- Shelters:Non-profit and municipal animal welfare operations with cost-minimization priorities.
- Veterinary Clinics:Prescription-channel gatekeepers for therapeutic diets.
Pet owners command the largest revenue pool; veterinary clinics show the steepest expansion trajectory.
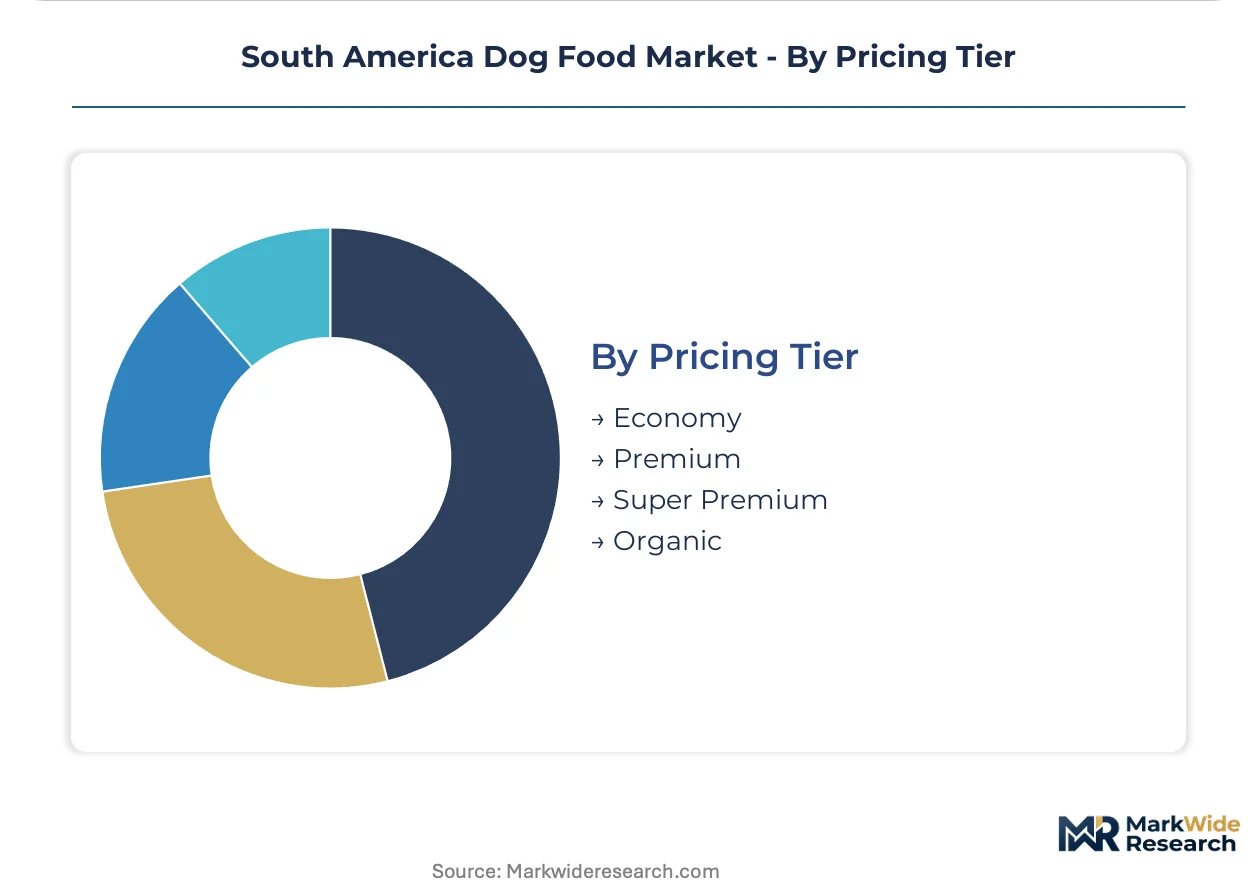
Pricing Tier:
Price stratification reflects ingredient provenance, processing intensity, and certification burden rather than simple volume scaling.
- Economy:Soybean-meal-based formulations with minimal processing. Brazil's interior municipalities and price-sensitive rural households sustain demand, though ANVISA labeling mandates are compressing margins and forcing local protein-integrated competitors to absorb compliance costs.
- Premium:Mid-tier formulations with branded ingredient sourcing and basic nutritional claims. Argentine manufacturers leverage pampas cattle byproduct streams to serve this tier with traceable novel proteins.
- Super Premium:Freeze-dried or minimally processed formats with AAFCO compliance and veterinary endorsement.
- Organic:MAPA-certified pesticide-free formulations with documented grain provenance.
Economy tier retains the largest volume base; organic certification is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's Pampas protein streams flow northward into Brazil's coastal manufacturing zones, creating a cross-border supply corridor that defines South American dog food trade architecture. This bilateral flow shapes regional competitive dynamics.
Brazil
São Paulo's veterinary clinic networks and Rio de Janeiro's subscription e-commerce platforms concentrate premium demand, while interior states depend on shelf-stable dry food through hypermarket chains. ANVISA's macronutrient disclosure mandates compress formulation margins and favor local manufacturers with integrated protein sourcing. Minas Gerais hosts expanding extrusion capacity serving economy-tier interior markets.
Argentina
Buenos Aires maintains independent pet shop density that Brazilian cities are losing to clinic consolidation, preserving mid-tier retail diversity. The national food safety authority enforces labeling standards equivalent to ANVISA, elevating compliance costs for imported formulations. Córdoba's industrial corridor processes pampas cattle byproducts into traceable novel proteins for limited-ingredient formulations.
Chile
Santiago's urban millennial demographic drives super-premium segment growth through veterinary-integrated purchasing, though market scale remains smaller than Brazil or Argentina. The country's agricultural inspection protocols align with Mercosur harmonization frameworks, facilitating cross-border ingredient flows. Valparaíso's port infrastructure supports freeze-dried raw food exports to Brazilian coastal markets.
Colombia
Bogotá's emerging middle class sustains premiumization momentum, with veterinary clinic channels expanding from diagnostic services into therapeutic diet recommendations. The national sanitary regulator enforces pet food registration requirements that favor locally manufactured products over imports. Medellín's logistics hub connects Andean interior municipalities to coastal supply chains.
Uruguay
Montevideo's small but affluent pet owner base concentrates super-premium spend through specialty retail and online subscription platforms. The country's grass-fed cattle operations offer pesticide-free protein sourcing for organic certification seekers. Mercosur membership enables duty-advantaged ingredient exports to Brazilian manufacturers.
South America Dog Food Market Competitive Landscape
Player mix skews toward multinational consumer goods conglomerates with veterinary channel integration, creating tiered competition between protein-integrated local processors and scale-driven global brands. Market structure concentrates volume among three to four entities with national distribution infrastructure, while mid-tier Argentine manufacturers fragment regional supply through compact extrusion systems. Strategic archetypes include veterinary-channel specialists, protein-backward-integrated local processors, and subscription-platform-enabled direct-to-consumer operators. Dominant competitive moves center on clinic network partnerships and localized manufacturing investments to absorb ANVISA compliance costs.
Among Brazil-based protein-integrated processors, BRF S.A. exemplifies the local backward-integration archetype, converting poultry byproduct streams into economy-tier formulations. Mars Incorporated and Nestlé Purina PetCare anchor the multinational tier, occupying positions defined by veterinary channel density and brand equity rather than manufacturing scale alone. These three entities represent the structural poles around which mid-tier competition organizes.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé Purina PetCare |
| BRF S.A. |
| PremieRpet Holding |
| Empresas Carozzi S.A. |
| Hill's Pet Nutrition |
| Grupo Pilar |
| Nutrire Indústria de Alimentos Ltda. |
| Virbac |
| Others |
Pricing and Supply Chain Analysis
ANVISA's macronutrient disclosure protocols gate both supplier qualification and price differentiation simultaneously, compressing margins for informal protein sources while elevating certified formulations to premium positioning in São Paulo's veterinary channels.
Pricing Analysis
Freeze-drying equipment depreciation divides pricing tiers sharply from legacy extrusion systems, with super-premium formats commanding subscription premiums through São Paulo's clinic networks while economy-tier soybean-meal formulations face cost compression in Brazil's interior states. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification burden and protein traceability rather than volume alone. Price differentiation hinges on MAPA organic seal attainment and veterinary endorsement density. Pricing pressure stems from ANVISA compliance cost absorption, with rural households showing highest sensitivity and urban millennial subscribers demonstrating lowest elasticity.
Supply Chain Analysis
Inventory cycles stretch longest for wet food formats dependent on refrigerated last-mile infrastructure, while freeze-dried products compress working capital needs through ambient storage. Protein sourcing concentrates in Brazil's Minas Gerais industrial corridor and Argentina's Córdoba processing zones, with Uruguayan grass-fed cattle operations feeding organic certification pipelines. Raw material flows hinge on soybean meal concentrates, poultry byproduct streams, and pampas bovine derivatives. Single-source vulnerability runs through Brazil's domestic soy derivative dependence exposed to MAPA export quota fluctuations. Distribution runs through veterinary clinic portals and subscription platforms in coastal metros, hypermarket chains in interior municipalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where ANVISA sanitary registration and MAPA traceability protocols create switching costs that marginalize unqualified suppliers.
For Market Incumbents: Consolidate veterinary clinic network density in São Paulo and Rio de Janeiro to capture therapeutic diet conversion from diagnostic traffic, while absorbing ANVISA compliance costs through backward integration into protein sourcing that informal competitors cannot replicate. Capacity addition in Minas Gerais extrusion zones defends economy-tier volume against Argentine mid-tier fragmentation.
For New Entrants and Emerging Players: Lead with freeze-dried raw formats targeting São Paulo's millennial subscription base, where algorithmic personalization and breed-specific metabolic profiling remain underdeveloped relative to incumbent scale. Argentine pampas protein integration offers traceable novel protein positioning for limited-ingredient allergy formulations in coastal Brazil's specialty retail corridors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across compact extrusion technology, enabling regional co-manufacturers to achieve AAFCO compliance without legacy industrial line investments. Long-term viability favors protein-backward-integrated processors with documented MAPA chain-of-custody over brand-dependent multinationals exposed to compliance margin compression. Watch ANVISA blockchain traceability mandate enforcement velocity as inflection signal for supplier qualification bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Clinic Network Expansion | Captures therapeutic diet conversion from São Paulo diagnostic appointments into recurring subscription revenue. |
| Protein Backward Integration | BRF S.A.'s poultry byproduct streams demonstrate margin defense against ANVISA compliance cost absorption. |
| Freeze-Drying Process Adoption | Preserves raw protein integrity for super-premium positioning in urban millennial subscription channels. |
| Blockchain Traceability Investment | ANVISA's 2023 protocols disqualify informal suppliers lacking documented ingredient chain-of-custody systems. |
| Subscription Platform Development | São Paulo's algorithmic personalization consolidates nutrition, treat, and supplement procurement into automated cycles. |
Research Methodology
The analysis maps dry food extrusion, wet food canning, freeze-dried raw formats, and treat manufacturing segments, each validated through veterinary nutritionists, clinic procurement managers, pet shop category buyers, and protein processing plant directors. Primary interviews with ANVISA registration consultants and MAPA agricultural inspectors combined with secondary validation through Brazilian customs records, ANVISA sanitary registration databases, and Mercosur trade flow disclosures. Bottom-up facility capacity assessments and top-down retail channel audits triangulate volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include product format, distribution channel, pricing tier, and metropolitan density cluster. CAGRs derive from compound growth trajectory analysis incorporating veterinary clinic expansion rates, subscription platform penetration curves, and protein input cost indices. Forecast inputs incorporate ANVISA regulatory implementation timelines and MAPA organic certification eligibility expansion.
The analysis sits within stated boundaries; outcomes outside sustained ANVISA enforcement intensity or Mercosur harmonization progress would require recalibration. Forecasts reflect documented assumptions regarding clinic network conversion rates and interior logistics infrastructure development. Commodity price volatility in soybean derivatives and pandemic-disrupted veterinary talent pipelines constitute specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Food Pulverizer Market
Pet Care Products
Dog Pen Market
Pet Care Products
Robotic Pets Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
Natural Cat Litter Products Market
Pet Care Products
China Pet Boarding Market
Pet Care Products
North America Cat Food Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Dog Pad Market
Pet Care Products
Mexico Pet Food Market
Pet Care Products
Pet Dental Health Market
Pet Care Products
Outdoor Dog Bed Market
Pet Care Products
Pet Shampoo Market