
 Physical Therapy Rehabilitation Solutions Market | 2026-2036
Physical Therapy Rehabilitation Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Physical Therapy Rehabilitation Solutions Market Outlook
Clinical-grade wearable integration is unwinding legacy equipment standards across outpatient rehabilitation. Smith+Nephew leverages its orthopedic device heritage to bundle surgical implants with post-operative therapy protocols. Hinge Health Inc anchors the employer-sponsored musculoskeletal segment with digital-first physical therapy programs. Össur competes in prosthetic rehabilitation through advanced bionic limb systems paired with gait training software.
Physical therapy rehabilitation solutions encompass equipment, software, and service modalities designed to restore musculoskeletal, neurological, and cardiopulmonary function following injury, surgery, or chronic disease progression. Exercise equipment with embedded force sensors and real-time biofeedback loops enables quantified progression tracking for post-surgical recovery protocols. Electrical stimulation devices and wearable tech represent the fastest-expanding product-technology intersection, where margin pools concentrate in subscription-linked remote monitoring platforms. Manual therapy tools remain mature with stable replacement demand, while telehealth platforms are displacing initial evaluation visits in sports injury rehabilitation workflows.
The FDA governs 510(k) clearance for electrical stimulation and ultrasound therapeutic devices, while CMS reimbursement policies directly shape provider investment in home care delivery infrastructure. HIPAA compliance requirements constrain data architecture choices for telehealth platforms and mobile apps processing patient-reported outcome measures. Stakeholders must monitor evolving state-level direct access laws that determine whether patients can self-refer to physical therapy without physician gatekeeping.
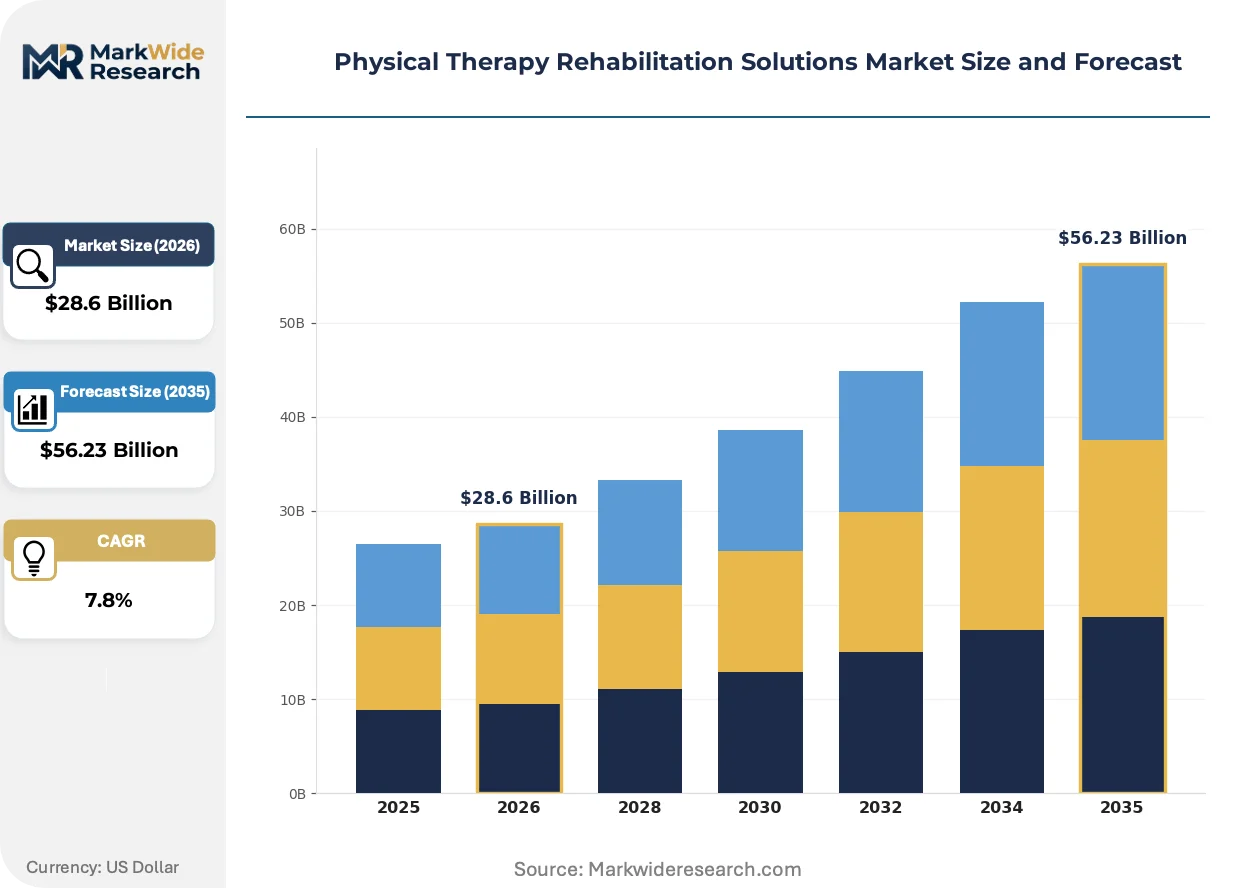
Market Dynamics
Medicare reimbursement shifts toward outpatient and home-based delivery models are restructuring provider capital allocation, forcing hospital systems to downscale inpatient rehabilitation infrastructure while accelerating procurement of connected remote monitoring platforms.
Growth Catalysts
- Remote Therapeutic Monitoring:CMS reimbursement codes for RTM services incentivize providers to deploy wearable-enabled home exercise programs, expanding addressable patient volume beyond clinic walls.
- FDA Digital Health Guidance:Streamlined 510(k) pathways for software-as-medical-device accelerate commercialization timelines for AI-driven movement assessment tools.
- Post-Surgical Protocol Bundling:Orthopedic service lines in US hospital systems now embed prescribed rehabilitation into episode-based payment models, guaranteeing equipment utilization rates.
Market Restraints
- Semiconductor Component Concentration:Force sensors and microcontrollers for wearable biofeedback devices depend on concentrated Asian foundry capacity, exposing equipment manufacturers to supply volatility.
- HIPAA Compliance Architecture:Telehealth platforms face structural cost penalties for on-premise data storage versus cloud-native alternatives, compressing SaaS margins.
- Manual Therapy Equipment Saturation:Mature product categories like treatment tables and resistance bands face replacement-only demand with minimal pricing power.
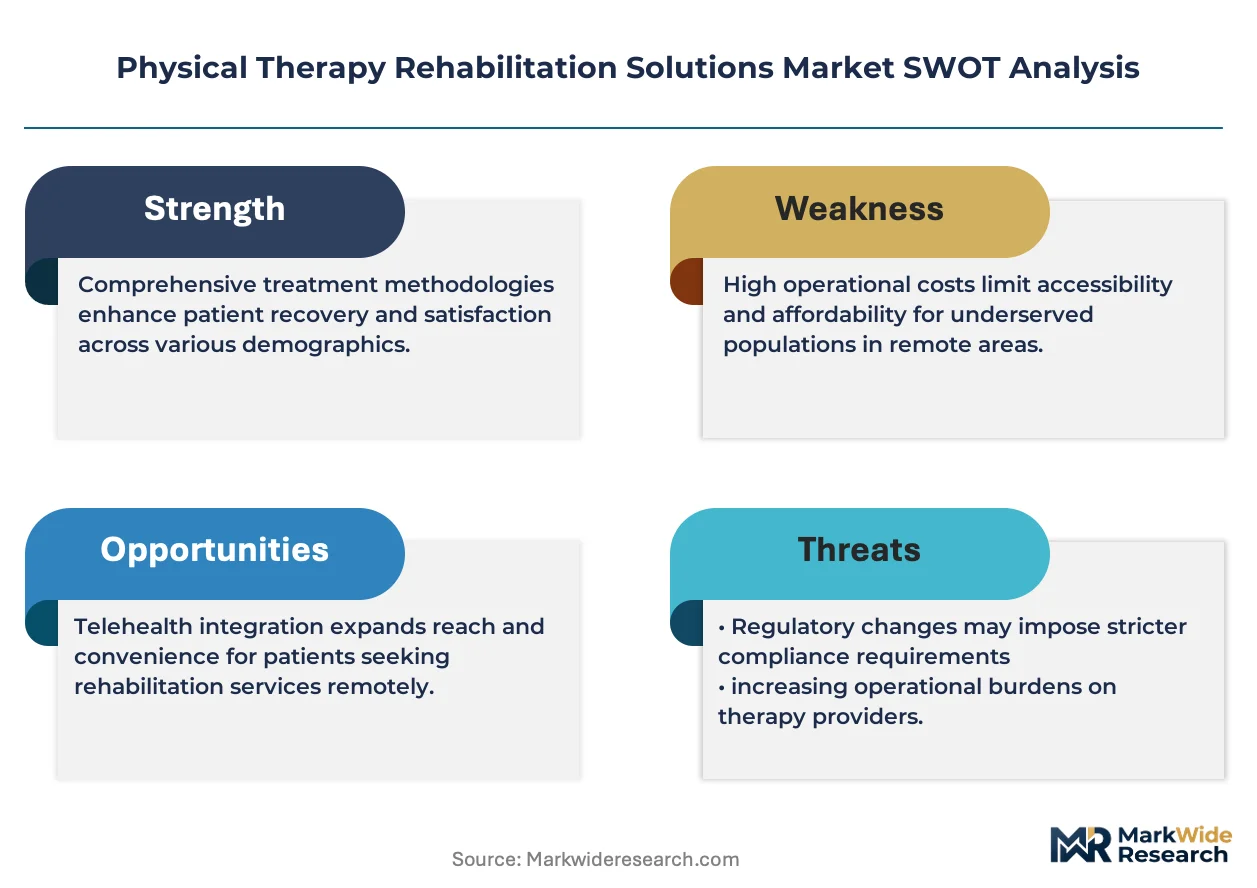
Strategic Opportunities
- Neurological Rehabilitation:Stroke and Parkinson's disease applications remain underpenetrated relative to orthopedics, offering white space for robotics-assisted gait training systems.
- Employer-Sponsored Musculoskeletal:Self-insured corporations represent a direct-pay channel bypassing traditional payer intermediaries, enabling subscription pricing for digital physical therapy.
- State Direct Access Expansion:Legislative reforms permitting patient self-referral without physician gatekeeping expand addressable demand in Texas, Florida, and Michigan.
Industry Challenges
- Interoperability Standards:Proprietary data formats from competing wearable manufacturers prevent seamless integration with hospital electronic health record systems, complicating enterprise sales cycles.
- Clinical Validation Timelines:Randomized controlled trials required for FDA breakthrough device designation extend development costs and delay commercial launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physical Therapy Rehabilitation Solutions Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $56.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exercise Equipment, Manual Therapy Tools, Electrical Stimulation Devices, Ultrasound Machines End User: Hospitals, Sports Clinics, Rehabilitation Centers, Home Care Technology: Wearable Tech, Virtual Reality, Telehealth Platforms, Mobile Apps Application: Post-Surgical Recovery, Pain Management, Sports Injury Rehabilitation, Geriatric Rehabilitation |
| Companies Covered | Smith+Nephew, Therapy Sync, ATI Physical Therapy, Athletico Physical Therapy, U.S. Physical Therapy, Inc., Select Medical, Össur, Invacare Corporation, Hinge Health Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physical Therapy Rehabilitation Solutions Market Strategic Shifts
Clinical-grade sensor miniaturization and AI-powered movement analysis are fragmenting traditional equipment categories, enabling software-defined rehabilitation protocols that decouple therapeutic content from hardware form factors.
Sensor-embedded exercise equipment is bifurcating the market between premium connected platforms with real-time biofeedback and commoditized passive devices. Outpatient orthopedic clinics in the United States are adopting force-plate-enabled resistance machines at replacement cycles of 18-24 months. This technology compression is collapsing margins for legacy equipment manufacturers while concentrating value capture in subscription-linked software layers.
The FDA's evolving enforcement discretion for AI/ML-based Software as a Medical Device is accelerating premarket notification pathways for automated movement assessment tools. Developers now navigate streamlined 510(k) reviews when algorithm modifications remain within predetermined change control plans. Physical therapy telehealth platforms targeting post-surgical recovery are the primary beneficiaries, with several US-based vendors securing clearance for remote range-of-motion quantification.
Self-insured employers are consolidating musculoskeletal benefit spending around integrated digital-first vendors, displacing traditional fee-for-service physical therapy networks. Human resources departments now contract directly with technology platforms bundling diagnosis, exercise prescription, and coaching. This channel disintermediation is most advanced among Fortune 500 manufacturers with concentrated blue-collar workforces in the Midwest and Southeast United States.
Physical Therapy Rehabilitation Solutions Market Segmentation
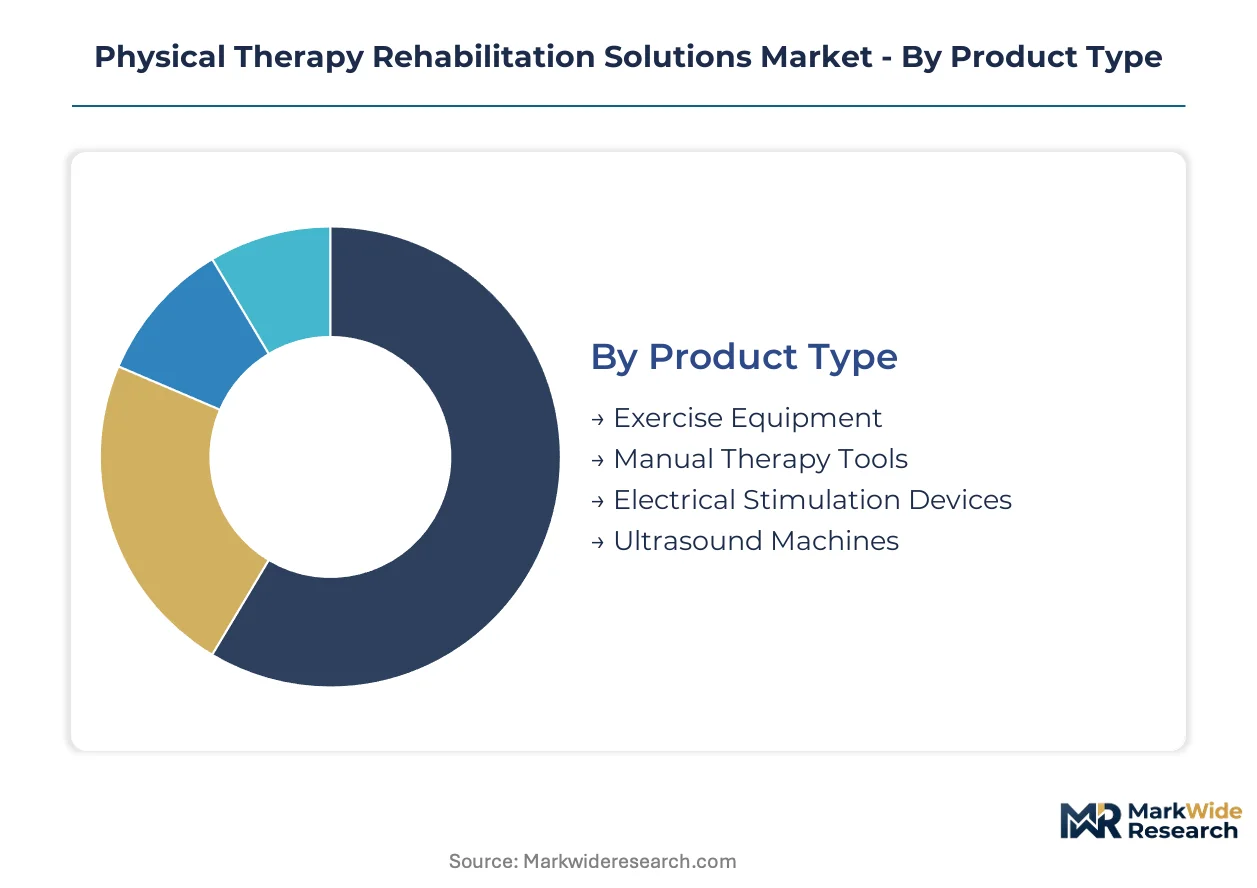
Physical therapy rehabilitation solutions fragment across four intersecting dimensions that determine procurement patterns and margin capture. Equipment manufacturers, software developers, and service providers compete within distinct technology-application pairings where reimbursement codes and clinical validation requirements create divergent competitive dynamics.
Product Type:
Margin pools concentrate in connected devices with recurring software revenue rather than capital equipment sales.
- Exercise Equipment:Force-plate-enabled resistance machines with embedded biofeedback sensors dominate orthopedic clinic procurement. Hospital systems in the United States are replacing passive equipment at 18-24 month cycles as bundled payment models mandate quantified outcome tracking.
- Electrical Stimulation Devices:Wearable neuromuscular stimulators with Bluetooth connectivity and prescription-linked mobile apps command premium pricing. CMS reimbursement codes for remote therapeutic monitoring are accelerating home-based adoption across post-surgical recovery protocols.
- Manual Therapy Tools:Treatment tables, resistance bands, and mobilization instruments face mature replacement-only demand with minimal pricing power.
- Ultrasound Machines:Portable therapeutic ultrasound units with preset treatment protocols serve outpatient clinics and athletic training facilities.
The dominant share belongs to Exercise Equipment, while Electrical Stimulation Devices is closing the gap fastest.
End User:
Procurement authority and reimbursement access determine customer lifetime value across institutional and consumer channels.
- Hospitals:Orthopedic service lines under episode-based payment models embed prescribed rehabilitation into surgical bundles. Post-surgical recovery departments are expanding capital budgets for connected platforms that guarantee utilization rates.
- Home Care:Wearable-enabled exercise programs bypass facility overhead while capturing CMS remote therapeutic monitoring reimbursement. Medicare Advantage plans in the United States are accelerating prior authorization for home-based physical therapy delivery.
- Sports Clinics:Outpatient facilities serving athletic populations prioritize rapid-return protocols and performance optimization over chronic condition management.
- Rehabilitation Centers:Dedicated inpatient and outpatient facilities maintain concentrated equipment footprints for complex neurological and cardiopulmonary cases.
Hospitals command the largest procurement volume, though Home Care is expanding most quickly as reimbursement shifts favor site-neutral payment.
Technology:
Software-defined protocols are decoupling therapeutic content from hardware form factors, collapsing traditional equipment categories.
- Wearable Tech:Clinical-grade inertial measurement units and surface electromyography sensors enable real-time movement quantification. FDA 510(k) clearances for range-of-motion assessment algorithms are accelerating enterprise adoption.
- Telehealth Platforms:Video-based evaluation and asynchronous exercise prescription tools displace initial visits in sports injury workflows. HIPAA compliance architecture costs compress SaaS margins relative to consumer health applications.
- Virtual Reality:Immersive environments for gait training and pain distraction remain concentrated in neurological rehabilitation applications.
- Mobile Apps:Patient-reported outcome capture and adherence tracking tools serve as connectivity layers across hardware categories.
Wearable Tech holds the deepest margin pools, with Telehealth Platforms gaining share fastest among outpatient providers.
Application:
Episode-based payment models and direct employer contracting create divergent pricing power across clinical indications.
- Post-Surgical Recovery:Orthopedic implant manufacturers bundle rehabilitation protocols with surgical devices, guaranteeing equipment placement. United States hospital systems under CMS bundled payment programs embed prescribed therapy into joint replacement episodes.
- Sports Injury Rehabilitation:Self-insured employers contract directly with digital-first vendors, bypassing traditional payer networks. Fortune 500 manufacturers with concentrated blue-collar workforces consolidate musculoskeletal benefit spending around integrated platforms.
- Pain Management:Non-pharmacological interventions face variable payer coverage despite opioid-reduction policy tailwinds.
- Geriatric Rehabilitation:Medicare fee-for-service constraints limit technology adoption relative to commercial populations.
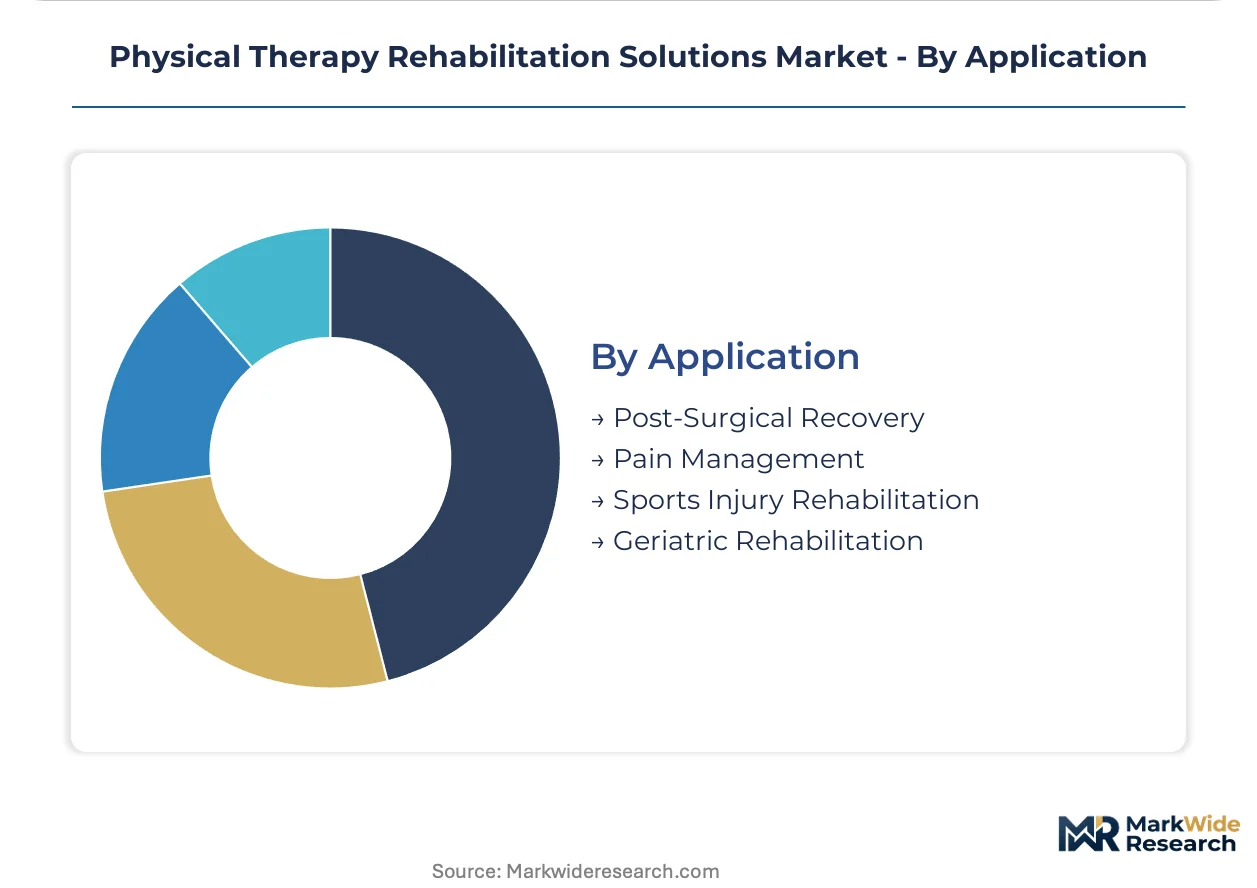
Post-Surgical Recovery generates the highest equipment utilization rates, though Sports Injury Rehabilitation shows the steepest expansion trajectory under employer direct-contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in physical therapy rehabilitation equipment, exporting connected sensor platforms to European hospital systems while importing commoditized manual therapy tools from Asian contract manufacturers. Germany and Japan maintain balanced trade positions through specialized robotics components. China's import dependency concentrates in clinical-grade force sensors and FDA-cleared software modules.
United States
Medicare Advantage plans and CMS remote therapeutic monitoring reimbursement codes drive procurement of wearable-enabled home exercise platforms. The FDA's 510(k) digital health guidance accelerates clearance timelines for AI-driven movement assessment tools. Hospital systems in Texas, Florida, and Michigan expand direct access physical therapy capacity as state-level self-referral laws loosen.
Germany
Episode-based payment models in statutory health insurance bundles embed rehabilitation into orthopedic surgical pathways. The EU Medical Device Regulation (MDR) and CE marking requirements shape product registration timelines for connected therapeutic devices. Industrial clusters in Baden-Württemberg and Bavaria concentrate manufacturing of precision sensor arrays for gait analysis systems.
Japan
Aging demographics and long-term care insurance expansion sustain demand for home-based rehabilitation robotics. METI's Society 5.0 initiative funds development of AI-powered movement quantification platforms. The Kansai region around Osaka anchors production of compact electrical stimulation devices for export to Southeast Asian markets.
China
Domestic hospital procurement of imported high-end rehabilitation robotics runs counter to NMPA localization requirements for software-as-medical-device. The country's dual carbon goals pressure manufacturers to reduce energy intensity in production of sensor-embedded exercise equipment. Yangtze River Delta medical device clusters in Jiangsu and Zhejiang provinces scale output of mid-range therapeutic ultrasound units.
United Kingdom
NHS England's musculoskeletal service redesign shifts volume toward community-based digital first-contact providers. GDPR compliance architecture costs constrain telehealth platform margins relative to US counterparts. London and Southeast England concentrate venture-backed startups developing virtual reality applications for neurological rehabilitation.
Physical Therapy Rehabilitation Solutions Market Competitive Environment
Concentration sits with diversified orthopedic device manufacturers and digital-first musculoskeletal platforms. The vendor base spans three tiers: legacy equipment manufacturers with replacement-cycle revenue, software-native entrants capturing employer-sponsored spend, and integrated hospital service operators. Strategic moves cluster around surgical protocol bundling and direct-to-employer contracting channels. M&A activity targets remote monitoring capabilities and AI-powered movement assessment assets.
Within the orthopedic-anchored tier, Smith+Nephew represents bundled surgical-rehabilitation protocol integration. Among digital-native platforms, Hinge Health Inc exemplifies employer-sponsored musculoskeletal benefit consolidation. Össur occupies a specialized position in prosthetic rehabilitation systems paired with gait training software. These three anchors illustrate divergent competitive vectors: implant bundling, direct employer contracting, and bionic device integration.
| Leading Market Players |
|---|
| Smith+Nephew |
| Therapy Sync |
| ATI Physical Therapy |
| Athletico Physical Therapy |
| U.S. Physical Therapy, Inc. |
| Select Medical |
| Össur |
| Invacare Corporation |
| Hinge Health Inc |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance pathways and CMS reimbursement code eligibility operate as simultaneous gating mechanisms for supply qualification and price tier segmentation, concentrating margin capture among vendors with established regulatory track records while compressing pricing power for uncertified entrants.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers based on FDA clearance tier and remote monitoring integration depth. Price differentiation hinges on clinical validation grade and bundled software subscription terms. Cost compression in the economy tier intensifies because Asian contract manufacturers now replicate basic sensor architectures. Self-insured employers show least price sensitivity, prioritizing outcome guarantees over per-unit costs.
Supply Chain Analysis
Strategic stockpiling of force sensors and microcontrollers dominates inventory strategy among US-based equipment manufacturers facing lead time volatility from concentrated Asian foundry capacity. Component sourcing draws from Taiwan, South Korea, and China for MEMS sensors and Bluetooth modules. Single-source vulnerability in advanced microcontroller supply creates exposure to geopolitical disruption. Distribution runs through orthopedic device distributors and direct hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through FDA digital health guidance and CMS reimbursement code capture constitutes the primary defensive moat, as switching costs for hospital systems escalate once rehabilitation protocols embed specific vendor platforms.
For Market Incumbents: Consolidate surgical protocol bundling relationships with orthopedic service lines to lock in equipment placement guarantees. Deepen backward integration into sensor manufacturing to offset semiconductor supply volatility. Prioritize CE marking investment for EU Medical Device Regulation compliance ahead of MDR transition deadlines.
For New Entrants and Emerging Players: Lead with neurological rehabilitation applications where robotics-assisted gait training remains underpenetrated relative to orthopedics. Target state direct access expansion corridors in Texas, Florida, and Michigan where patient self-referral laws loosen provider gatekeeping. Pursue employer-sponsored musculoskeletal channels with subscription pricing models that bypass traditional payer intermediaries.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified orthopedic device manufacturers seeking to monetize non-core rehabilitation software assets. Long-term viability centers on platforms with demonstrated FDA clearance velocity and established remote therapeutic monitoring reimbursement capture. Watch CMS code expansion decisions as the primary inflection signal for home-based care volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CMS Reimbursement Strategy | Remote therapeutic monitoring code capture unlocks Medicare Advantage prior authorization pathways. |
| FDA 510(k) Digital Health Pathway | Streamlined software-as-medical-device clearance accelerates AI movement assessment commercialization timelines. |
| Hospital System Partnership | Episode-based payment model integration guarantees equipment utilization rates under bundled contracts. |
| Software Companion Development | Subscription-linked mobile apps convert capital equipment sales into recurring revenue streams. |
| CE Marking Pathway | EU MDR compliance enables access to German statutory health insurance bundled rehabilitation pathways. |
Study Parameters
Initial hypotheses were tested against primary input from hospital purchasing committee members, physical therapy clinic directors, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, CMS reimbursement code databases, hospital procurement records, and orthopedic device regulatory submissions. Bottom-up equipment shipment analysis and top-down healthcare expenditure triangulation anchored market sizing across the projection horizon.
Variance decomposition across product type, end user, technology platform, and application segments structured the analytical framework, with CAGRs derived from regression analysis of historical reimbursement policy shifts and equipment replacement cycle data. Forecast inputs incorporated Medicare Advantage penetration trajectories and state-level direct access legislative tracking.
The analysis sits within stated boundaries; outcomes outside sustained CMS remote therapeutic monitoring reimbursement or FDA enforcement discretion continuity would require recalibration. Revision becomes warranted when semiconductor supply concentration or HIPAA compliance architecture costs cross thresholds that alter vendor margin structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Windsurf Masts Market
Sports & Fitness
Bowling Lane Panels Market
Sports & Fitness
Europe Sports Management Software Market
Sports & Fitness
Kung Fu Uniform Market
Sports & Fitness
US Sports Flooring Market
Sports & Fitness
North America Sports Team and Clubs Market
Sports & Fitness
Japan Fitness Ring Market
Sports & Fitness
Wetsuits Market
Sports & Fitness
Japan Sports Drink Market
Sports & Fitness
Gymnastic Bars Market
Sports & Fitness
Kiteboarding Equipment Market
Sports & Fitness
Running Gear Market
Sports & Fitness
Global Strength Members Market
Sports & Fitness
Saudi Arabia Outdoor Fitness Equipment Market
Sports & Fitness
Basketball Shooting Machine Market
Sports & Fitness
Sandbells Market