
 Global Strength Members Market | 2026-2036
Global Strength Members Market Size, Share, and Industry Trends Forecast 2026-2036
Global Strength Members Market Foresight
ISO 10966 qualification for sporting equipment reinforcement is collapsing the supplier base for high-performance strength members. DuPont leverages its aramid fiber vertical integration to dominate premium tire cord supply. ArcelorMittal sustains cost leadership in steel wire rope through captive European melt capacity. Roblon anchors Nordic market access with specialized extrusion capabilities for synthetic cordage.
Strength members are load-bearing structural elements engineered from drawn steel wire, twisted aramid filament, or braided carbon fiber composite, typically specified by tensile modulus exceeding 70 GPa and elongation at break below 4 percent, serving to reinforce flexible substrates against axial and dynamic stresses. Polyester cord occupies mature, high-volume positions in conveyor belt applications where margin pools erode on commodity pricing. Carbon fiber braided configurations represent the fastest-expanding product form segment as elevator OEMs specify lighter cable assemblies for super-tall building installations. Steel wire thread sustains dominant share in automotive tire reinforcement where heat-resistant metallurgy commands premium positioning.
FDA material contact regulations, EU REACH substance restrictions, and China's GB standards for elevator safety equipment collectively govern product formulation, chemical disclosure, and installation certification across major demand centers. REACH authorization requirements for certain phthalate plasticizers are redirecting hose assembler procurement toward aramid and polypropylene alternatives. Stakeholders must monitor evolving building code adoption of carbon fiber elevator cables versus traditional steel rope to calibrate capacity commitments and qualification investments.
Market Dynamics
EU F-Gas Regulation phase-down schedules and Japan's energy efficiency codes are compressing procurement timelines for aramid-based strength members as conveyor OEMs face 2027 compliance deadlines for fluorinated gas containment systems.
Growth Catalysts
- Automotive radial tire expansion:Production corridors in China, India, and Thailand are scaling capacity for high-performance tire reinforcement, pulling aramid and steel cord demand upward.
- REACH authorization pressure:Phthalate plasticizer restrictions are redirecting hose assemblers toward aramid and polypropylene strength member alternatives across European industrial markets.
- Super-tall building construction:Elevator OEMs in Dubai, Shanghai, and New York are specifying carbon fiber cable assemblies to reduce counterweight mass in shafts exceeding 500 meters.
Market Restraints
- Steel wire feedstock volatility:ArcelorMittal's captive European melt capacity insulates tier-one suppliers while mid-tier processors face scrap metal price swings.
- Aramid filament supply concentration:DuPont's vertical control over para-aramid polymerization limits second-source qualification for tire cord specifications.
- Carbon fiber qualification timelines:ISO 10966 sporting equipment certification cycles extend 18-24 months, freezing out non-integrated compounders from premium segments.
Strategic Opportunities
- India conveyor belt modernization:BIS standards adoption for mining equipment is creating first-mover advantage for aramid cord suppliers qualifying domestic compounders.
- Wind turbine blade root reinforcement:Hybrid carbon-glass strength member configurations are penetrating blade manufacturing as rotor diameters exceed 150 meters.
- Medical device catheter braiding:FDA material contact regulations for implantable delivery systems are opening specification windows for ultra-fine metallic and polymer strength members.
Industry Challenges
- Multi-standard certification burden:Elevator safety equipment must simultaneously satisfy EU machinery directives, China's GB standards, and Japan's METI technical regulations, multiplying testing costs.
- Polymer extrusion talent scarcity:Roblon's specialized Nordic workforce for synthetic cordage represents a non-replicable capability cluster that competitors cannot readily replicate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Strength Members Market |
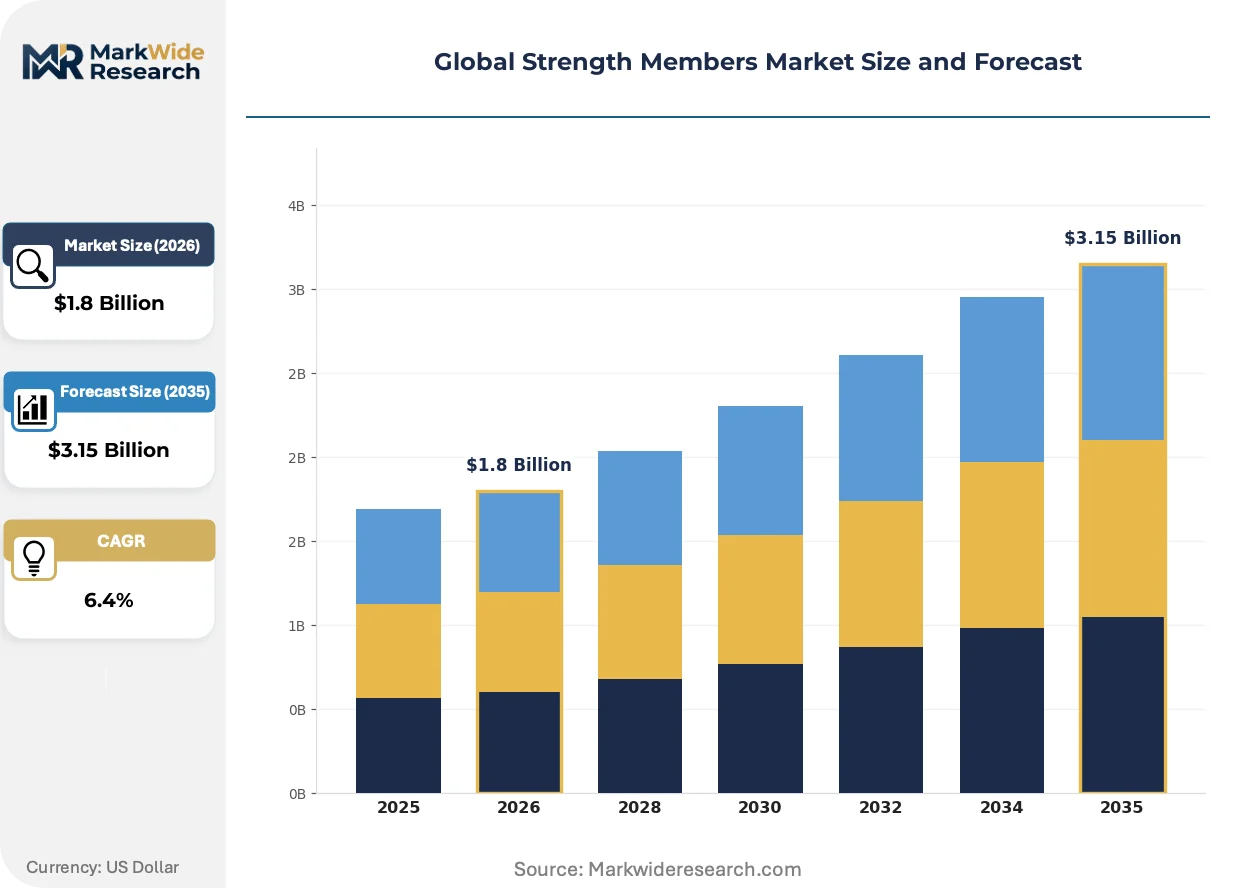
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Glass Fiber, Aramid, Carbon Fiber, Steel Wire, Polypropylene Application: Conveyor Belts, Power Transmission Belts, Automotive Tires, Hoses, Elevator Cables, Sporting Goods Product Form: Fabric, Cord, Thread, Strip, Braided, Laminated End User Industry: Tire Manufacturers, Conveyor Systems Producers, Cable Makers, Hose Assemblers, Sporting Equipment Suppliers, Textile Fabricators |
| Companies Covered | DuPont, ArcelorMittal, Tata Steel, Nucor Corporation, Roblon, Cortland, Multicom, SSAB, Phillystran, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Strength Members Market Shifts & Advancements
Material substitution patterns and regulatory compliance architectures are actively restructuring competitive positioning across tire, elevator, and industrial hose applications.
Carbon fiber braided cable assemblies are fragmenting traditional steel rope dominance in high-rise elevator installations. KONE and Otis engineering teams in Shanghai and Dubai are accelerating specification of 12-strand braided configurations for counterweight reduction. This technology is fragmenting legacy steel wire procurement pools into carbon-steel hybrid portfolios that demand new supplier qualification protocols.
EU F-Gas Regulation tightening is mandating aramid-based sealing and reinforcement in conveyor systems handling fluorinated refrigerants. German producers are reformulating belt carcasses to eliminate steel cord corrosion risks from leaked gases. Tire manufacturers in Thailand and India are observing these specifications for export compliance to European automotive OEMs.
Buyers are consolidating supplier panels around vertically integrated fiber producers who control polymerization through finished cord. Tier-one tire makers in China are reducing qualified aramid sources from twelve to four vendors. This concentration is most visible in radial truck tire segments where specification audits now prioritize in-house filament production over merchant market sourcing.
Global Strength Members Market Segmentation
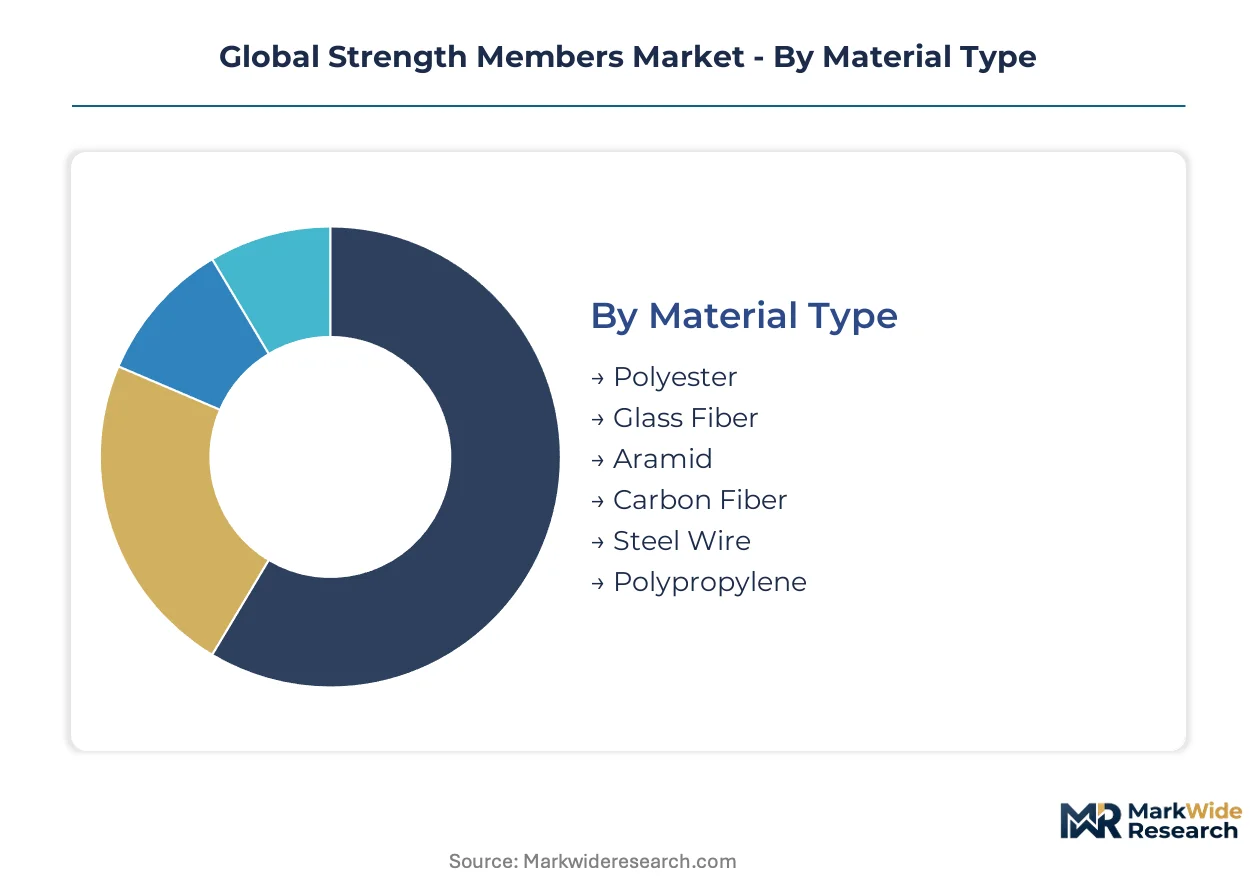
Segmentation in strength members reveals how material chemistry, product geometry, and end-use specifications fragment procurement patterns. Buyers calibrate specifications across four intersecting dimensions where technical requirements and regulatory compliance create distinct margin architectures.
Material Type:
Margin pools concentrate in high-modulus synthetic and metallic formulations where specification audits command premium positioning.
- Steel Wire:Heat-resistant drawn metallurgy with tensile modulus exceeding 200 GPa dominates automotive tire reinforcement corridors across China, India, and Thailand. Radial truck tire specifications from European OEMs mandate corrosion-resistant coatings that compress qualified supplier bases.
- Aramid:Para-aramid filament polymerization delivers strength-to-weight ratios critical for power transmission belts and conveyor systems facing EU F-Gas Regulation compliance deadlines. DuPont's captive polymerization capacity limits second-source qualification for tire cord applications.
- Carbon Fiber:PAN-based precursor tow configurations serve elevator cable assemblies in super-tall buildings exceeding 500 meters across Dubai and Shanghai.
- Polyester:Commodity PET cord occupies mature conveyor belt positions where margin erosion follows volume pricing dynamics.
- Glass Fiber:E-glass and S-glass rovings reinforce hybrid wind turbine blade root configurations as rotor diameters scale past 150 meters.
- Polypropylene:Lightweight monofilament substitutes for phthalate-plasticized alternatives in European hose assemblies facing REACH authorization restrictions.
The dominant share belongs to Steel Wire, while Carbon Fiber is expanding most quickly in premium elevator installations.
Application:
Volume concentration tracks industrial infrastructure buildout in emerging economies and regulatory-driven replacement cycles in mature markets.
- Automotive Tires:Radial tire production scaling across Thailand, India, and China pulls aramid and steel cord demand upward as export specifications tighten. BIS standards adoption in India creates first-mover positioning for qualified compounders.
- Elevator Cables:Super-tall construction in Shanghai, Dubai, and New York fragments traditional steel rope procurement into carbon-steel hybrid portfolios. KONE and Otis engineering teams accelerate 12-strand braided carbon fiber specifications for counterweight reduction.
- Conveyor Belts:German and Japanese producers reformulate belt carcasses to eliminate steel cord corrosion from fluorinated refrigerant leakage under tightening EU F-Gas schedules.
- Power Transmission Belts:Aramid tensile members replace polyester in high-torque industrial drives where energy efficiency codes compress procurement timelines.
- Hoses:REACH phthalate restrictions redirect European industrial assemblers toward aramid and polypropylene strength member alternatives.
- Sporting Goods:ISO 10966 qualification for equipment reinforcement collapses supplier bases as certification cycles extend 18-24 months.
Automotive Tires command the largest volume position, with Elevator Cables posting the steepest expansion trajectory.
Product Form:
Manufacturing complexity and qualification intensity determine margin stratification across geometric configurations.
- Braided:12-strand and 24-strand carbon fiber configurations reduce counterweight mass in high-rise elevator shafts. Braided geometries demand specialized mandrel wrapping equipment that limits supplier entry.
- Cord:Twisted aramid and steel constructions serve tire reinforcement and conveyor belt carcasses where tensile modulus specifications exceed 70 GPa. Cord extrusion talent scarcity in Nordic markets protects incumbent positioning.
- Fabric:Woven strength member layers reinforce flexible substrates in industrial belting applications.
- Thread:Fine-diameter metallic and polymer configurations enable medical device catheter braiding under FDA material contact regulations.
- Strip:Unidirectional tape formats reinforce composite laminates in wind turbine blade manufacturing.
- Laminated:Multi-layer bonded configurations serve specialized industrial hose and sealing applications.
Cord retains the dominant application share, though Braided configurations are gaining share fastest in premium building infrastructure.
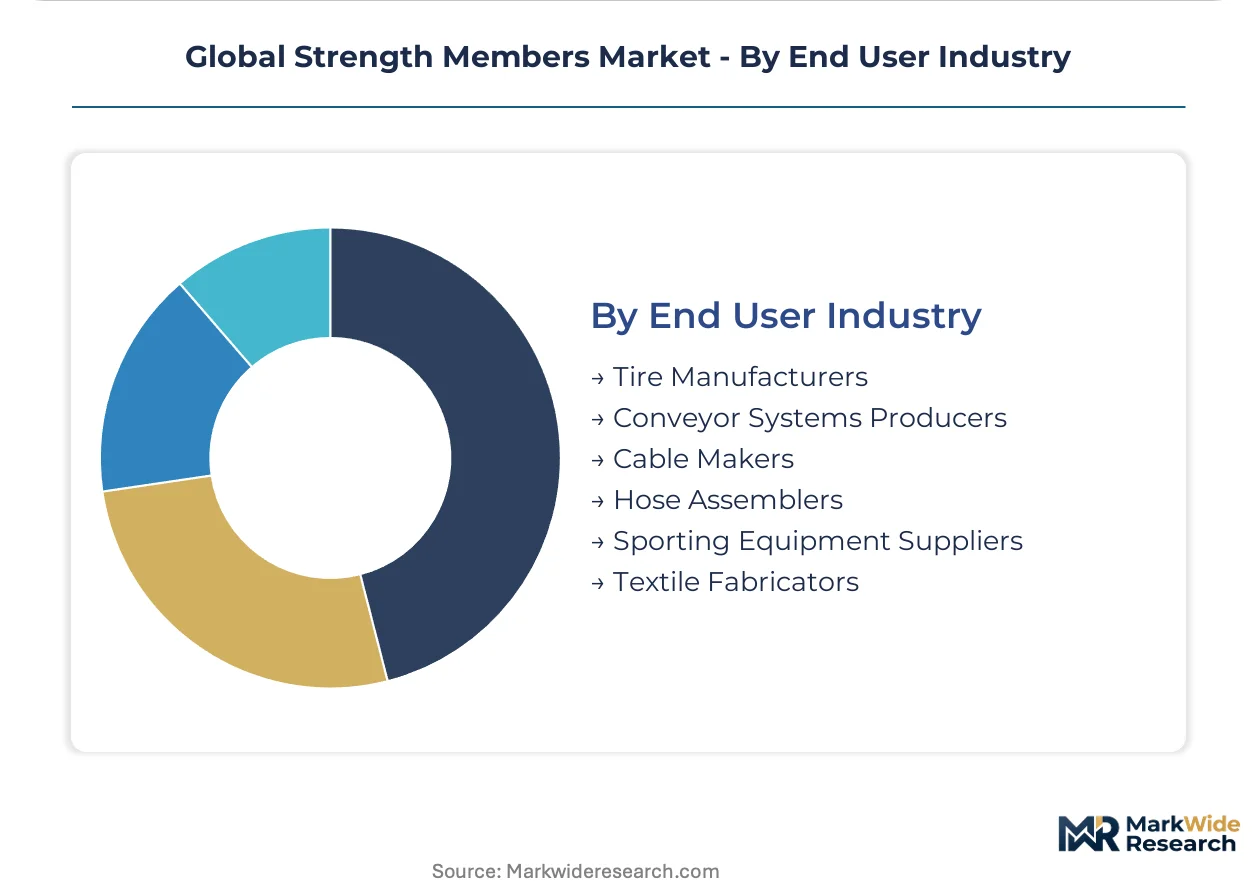
End User Industry:
Procurement sophistication varies sharply between specification-driven OEMs and price-sensitive aftermarket channels.
- Tire Manufacturers:Tier-one producers in China consolidate qualified aramid sources from twelve to four vendors, prioritizing in-house filament production over merchant sourcing. Radial truck tire audits now mandate polymerization-to-cord traceability.
- Conveyor Systems Producers:German OEMs face 2027 compliance deadlines for fluorinated gas containment, accelerating aramid-based belt procurement. Japanese producers align with national energy efficiency codes tightening material performance requirements.
- Cable Makers:Elevator OEMs in Dubai and Shanghai specify hybrid carbon-steel portfolios that demand new supplier qualification protocols.
- Hose Assemblers:European industrial channels redirect procurement toward phthalate-free strength member alternatives under REACH pressure.
- Sporting Equipment Suppliers:ISO 10966 certification requirements freeze out non-integrated compounders from premium equipment reinforcement segments.
- Textile Fabricators:Industrial belting compounders in India modernize capacity under BIS mining equipment standards adoption.
Tire Manufacturers anchor the largest demand block, while Conveyor Systems Producers are pivoting fastest toward compliance-driven material substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan Deep Water Port underwrites China's dominance in automotive tire exports, while the Rhine-Main-Danube corridor sustains German conveyor belt manufacturing. India's Dedicated Freight Corridors are pulling aramid demand into industrial belting modernization.
China
Radial tire production corridors in Shandong and Jiangsu provinces scale capacity for export to European automotive OEMs. GB standards for elevator safety equipment mandate carbon fiber cable qualification for super-tall buildings exceeding 500 meters. Shanghai engineering teams at KONE and Otis accelerate 12-strand braided specifications for counterweight reduction.
Germany
Conveyor systems producers face 2027 EU F-Gas Regulation deadlines for fluorinated gas containment systems. REACH authorization requirements redirect procurement toward phthalate-free aramid alternatives. The Ruhr industrial belt hosts reformulation of belt carcasses to eliminate steel cord corrosion risks from leaked refrigerants.
India
BIS standards adoption for mining equipment creates first-mover positioning for aramid cord suppliers qualifying domestic compounders. The Dedicated Freight Corridor network pulls demand into industrial belting modernization across Maharashtra and Gujarat. Radial tire production in Tamil Nadu and Haryana scales for domestic replacement and export markets.
United States
FDA material contact regulations govern specification windows for ultra-fine metallic strength members in medical device catheter braiding. The Port of Houston anchors carbon fiber composite demand for offshore energy applications. Elevator OEMs in New York specify hybrid carbon-steel cable assemblies for high-rise retrofits.
Japan
METI energy efficiency codes tighten material performance requirements for power transmission belts. Japanese conveyor producers align procurement timelines with 2027 compliance schedules. The Chubu industrial region around Nagoya sustains specialized aramid cordage manufacturing for automotive supply chains.
Global Strength Members Market Competitive Landscape
Listed leaders compete with private specialists across material chemistry and end-use certification intensity. The vendor base clusters around three tiers: integrated fiber producers controlling polymerization through finished cord, captive steel melt operators insulating against scrap volatility, and specialized extrusion houses protecting niche synthetic cordage positions. Strategic moves concentrate on backward integration into precursor supply and qualification protocol capture for regulated end uses.
Within the integrated fiber tier, DuPont exemplifies vertical control over para-aramid polymerization that limits second-source qualification. Among steel-based fabricators, ArcelorMittal occupies a position anchored by captive European melt capacity. At the specialized synthetic end, Roblon represents the extrusion capability scarcity that protects Nordic market access. These three anchors illustrate how competitive positioning fragments across material archetypes rather than consolidating around scale alone.
| Leading Market Players |
|---|
| DuPont |
| ArcelorMittal |
| Tata Steel |
| Nucor Corporation |
| Roblon |
| Cortland |
| Multicom |
| SSAB |
| Phillystran |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between aramid fiber producers and tire manufacturers lock in both polymerization capacity and price visibility across multi-year procurement cycles. These agreements insulate integrated suppliers from scrap metal volatility while exposing non-captive processors to feedstock cost swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified tire cord from commodity conveyor belt grades and uncertified industrial thread. Price differentiation rests on REACH compliance certification and captive polymerization capacity. Cost compression in polyester cord intensifies because Asian compounders flood mature conveyor segments with undifferentiated volume. Tier-one automotive OEMs exhibit lowest price sensitivity, while Indian mining belt assemblers face acute margin pressure.
Supply Chain Analysis
China and Germany anchor strength member fabrication, with the former commanding carbon fiber precursor production and the latter hosting specialized aramid cord extrusion. Raw material flows draw from Japanese PAN-based tow, Belgian para-aramid polymerization, and Ruhr basin steel melt capacity. Single-source vulnerability concentrates in DuPont's captive polymerization for tire-grade aramid. Distribution runs through direct mill relationships for automotive OEMs and regional belting distributors for industrial aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as tier-one tire manufacturers consolidate qualified aramid sources from twelve vendors to four, fragmenting negotiating leverage across the supplier base.
For Market Incumbents: Shield polymerization-to-cord traceability advantages by accelerating REACH certification audits before 2027 F-Gas deadlines. Deepen backward integration into PAN-based precursor supply to offset carbon fiber qualification timeline risks from emerging braid specialists. For New Entrants and Emerging Players: Differentiate on medical device catheter braiding specifications where FDA material contact regulations create specification windows for ultra-fine metallic thread. Target India's Dedicated Freight Corridor modernization as the most penetrable geography, leveraging BIS standards adoption to qualify domestic compounders ahead of established European suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward specialized extrusion houses with Nordic workforce capabilities that resist replication. Long-term viability favors compounders controlling in-house filament production over merchant market sourcing. Watch elevator OEM specification shifts toward 12-strand braided carbon fiber as the inflection signal for cable assembly margin migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive PAN-based tow production insulates carbon fiber cable assemblers from Japanese supply concentration. |
| REACH Certification Acceleration | Phthalate-free aramid qualification captures hose assembly procurement shifting under EU authorization pressure. |
| Medical Device Specification Entry | FDA material contact compliance opens catheter braiding segments for ultra-fine metallic strength members. |
| Wind Turbine Hybrid Configuration Development | Carbon-glass blade root reinforcement penetrates rotor manufacturing as diameters exceed 150 meters. |
| Indian Compounder Qualification Partnership | BIS mining equipment standards adoption creates first-mover positioning for aramid cord suppliers in Maharashtra. |
Research Methodology
Desk research of customs trade filings, SEC 10-K disclosures, and ECHA REACH authorization databases preceded structured interviews with tire manufacturer procurement directors, conveyor OEM technical engineers, elevator cable specification leads, and aramid fiber plant managers. Primary fieldwork across Shandong, Ruhr, and Tamil Nadu production corridors validated secondary volume estimates. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity assumptions.
Variance decomposition across material type, product form, application, and end-user industry dimensions shaped the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted volume trajectories and value-per-unit migration patterns. Forecast inputs incorporated EU F-Gas Regulation compliance deadlines, BIS standards adoption timelines, and super-tall building construction pipelines.
Material uncertainties — regulatory acceleration of carbon fiber elevator cable codes, scrap metal price volatility, and aramid polymerization capacity expansion — sit outside the modeled envelope. Forecasts reflect assumptions about qualification timeline stability and buyer consolidation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO