
 Basketball Shooting Machine Market | 2026-2036
Basketball Shooting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Basketball Shooting Machine Market Insights
Direct-to-consumer digital channels is fragmenting as manufacturers bypass traditional sporting goods distributors to reach individual buyers and small academies. Shoot-A-Way leverages its established brand heritage and institutional relationships to sustain dominance in the high school and collegiate segments. Dr. Dish Basketball differentiates through subscription-based software ecosystems that anchor recurring revenue beyond hardware sales. SIBOASI competes aggressively on manufacturing scale, occupying the mid-market price tier across North American and European markets.
A basketball shooting machine is an electromechanical training device equipped with motorized ball return systems, programmable trajectory adjusters, and shot counters designed to automate repetitive shooting practice for individual or team skill development. Portable units with collapsible frames and rechargeable power systems serve traveling trainers and home users lacking permanent court access. Automated machines represent the most mature revenue pool, while smart sensor-enabled models with real-time biomechanical feedback represent the fastest-growing technology segment. Wireless connectivity and mobile application integration are concentrating margin pools in software-augmented hardware platforms that command premium positioning.
FCC certification governs wireless-enabled units in the United States, while CE marking and RoHS compliance shape European market access requirements for electronic components. The Consumer Product Safety Commission and state-level athletic equipment safety boards influence liability standards and institutional purchasing protocols across American school districts. Stakeholders must monitor how evolving data privacy frameworks apply to biometric tracking features embedded in next-generation training systems.
Market Dynamics
Smart sensor integration and mobile connectivity upgrades are compressing replacement cycles as sports academies and home users demand real-time biomechanical feedback and cloud-based training analytics from their equipment investments.
Growth Catalysts
- Elite Youth Development Concentration:Texas, California, and Florida host dense clusters of competitive basketball academies that automate repetitive skill training to maximize court utilization and player throughput.
- FCC Certification Pathway:Wireless-enabled units gain institutional approval faster through established electromagnetic compliance frameworks, accelerating adoption across American school districts and collegiate programs.
- Biomechanical Feedback Integration:Real-time shot arc, velocity, and release-point analytics from embedded sensors transform standalone machines into data-rich coaching platforms that command premium positioning.
Market Restraints
- Lithium Battery Supply Concentration:Portable units depend on rechargeable power systems sourced primarily from East Asian cell manufacturers, exposing margins to raw material volatility and logistics bottlenecks.
- CE Marking Complexity:European market entry requires RoHS-compliant electronic components and multi-jurisdictional safety testing that extends product launch timelines by six to twelve months.
- Fixed Installation Substitutes:Permanent court-mounted ball return systems at well-capitalized facilities reduce replacement demand for portable electromechanical units in the institutional segment.
Strategic Opportunities
- Subscription Software Ecosystems:Recurring revenue models anchored to training analytics platforms create lifetime value multiples beyond one-time hardware transactions in the high school and collegiate segments.
- Direct-to-Consumer Channel Expansion:Manufacturers bypass traditional sporting goods distributors to capture margin and build direct relationships with individual buyers and small academy operators through digital storefronts.
- Data Privacy Framework Alignment:Early compliance with evolving biometric tracking regulations positions vendors favorably for institutional procurement protocols that prioritize liability protection.
Industry Challenges
- Embedded Systems Engineering Talent Scarcity:The convergence of electromechanical hardware, wireless connectivity, and mobile application development requires specialized firmware expertise that commands premium compensation and extends hiring cycles.
- Multi-Certification Parallel Processing:Simultaneous FCC, CE marking, and state-level athletic equipment safety board approvals demand dedicated regulatory affairs capacity that strains mid-market vendor resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Basketball Shooting Machine Market |
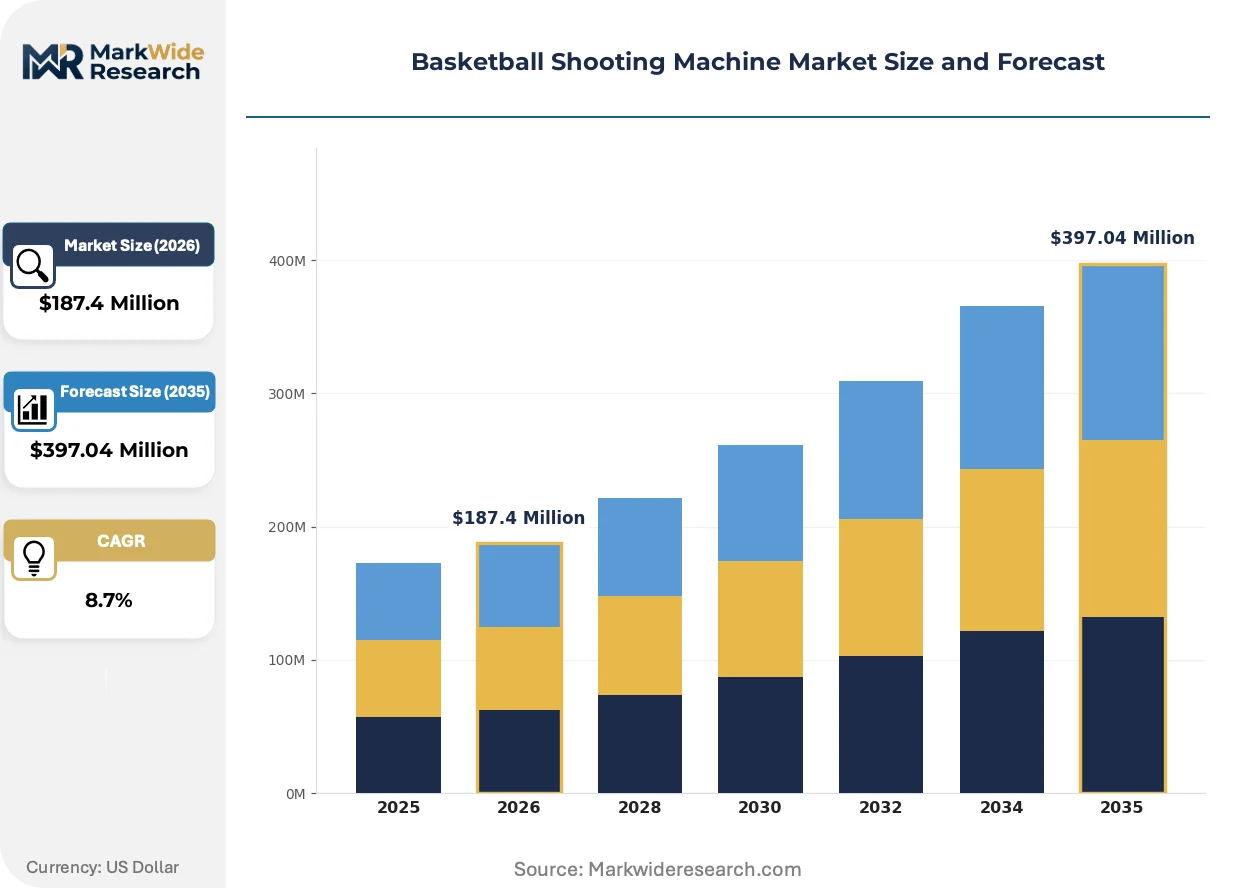
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Machines, Portable Units, Training Aids, Floor Models End User: Schools, Colleges, Sports Academies, Professional Teams Technology: Electromechanical Systems, Smart Sensors, Wireless Connectivity, Mobile Applications Distribution Channel: Online Retailers, Sports Equipment Stores, Direct Sales, Wholesalers |
| Companies Covered | Shoot-A-Way, Dr. Dish Basketball, Airborne Athletics, Franklin Sports, Lifetime, Triumph Sports, SIBOASI, GRIND Basketball, Noah Basketball, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Basketball Shooting Machine Market Trends and Innovations
Training equipment architecture is pivoting from isolated mechanical devices toward integrated software-hardware platforms that capture and monetize player performance data across distributed academy networks.
Sensor-enabled shot tracking is migrating from high-end institutional installations toward mid-market portable units as component costs decline and cloud analytics infrastructure matures. Collegiate programs and traveling trainers now expect real-time feedback without permanent court modifications. This compression of feature tiers erodes differentiation for legacy electromechanical-only manufacturers and forces accelerated R&D investment cycles.
CE marking and RoHS compliance requirements are tightening material sourcing standards for electronic subassemblies entering European markets. Vendors must document supply chain provenance for circuit boards and battery management systems to satisfy ECHA substance restrictions. German and French sports equipment distributors now prioritize pre-certified platforms to avoid customs delays and liability exposure.
Buyer preference is consolidating around bundled hardware-software service contracts that replace transactional equipment sales with annual training platform subscriptions. Small academies and individual users favor predictable operating expenditures over capital-intensive ownership. This preference shift concentrates margin pools with vendors capable of sustaining cloud infrastructure and continuous mobile application development.
Basketball Shooting Machine Market Segmentation
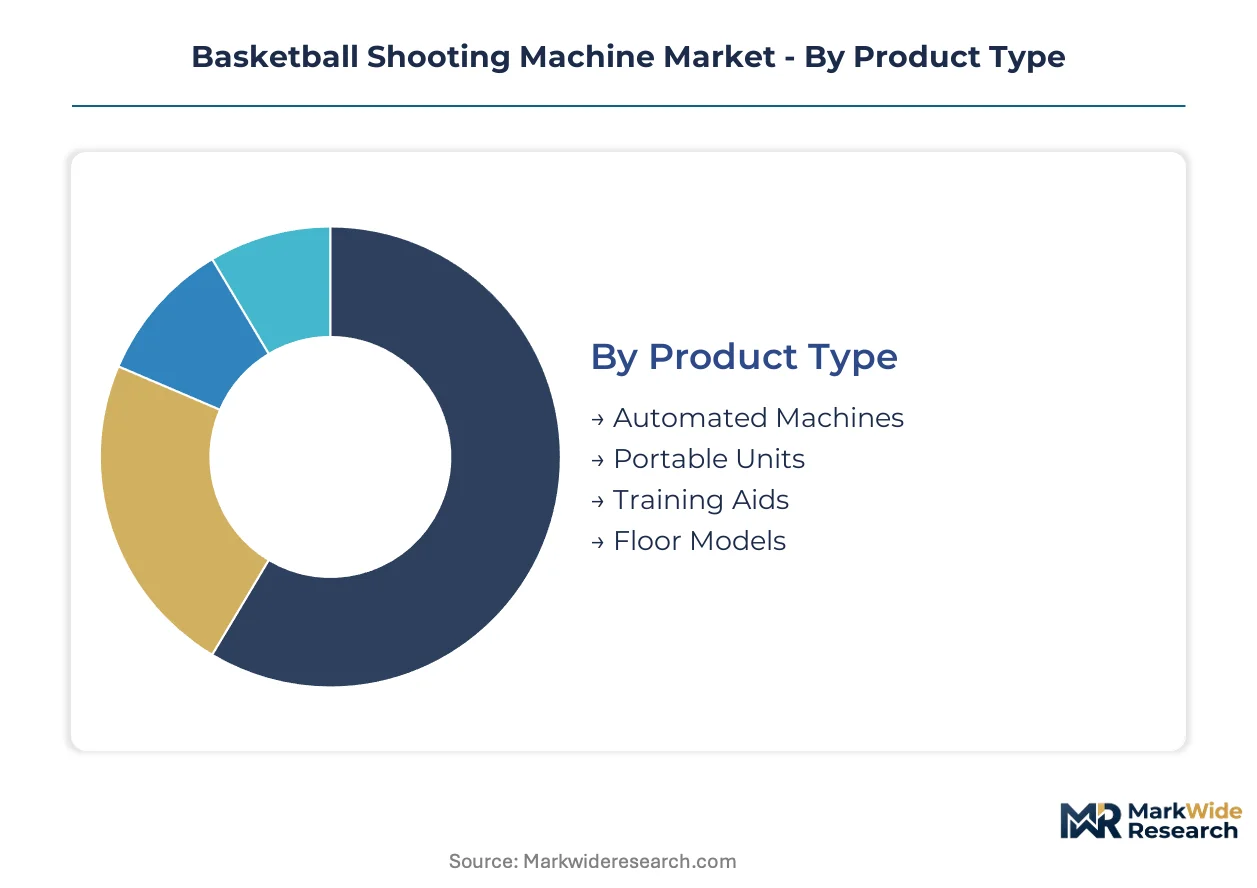
Product architecture and customer procurement patterns diverge sharply across the basketball shooting machine market. Segment-specific replacement cycles and technology refresh rates determine vendor resource allocation and pricing strategy.
Product Type:
Automated machines turn over every seven to ten years in institutional settings, while portable units face three-to-five-year refresh cycles as battery and sensor technology advances.
- Automated Machines:Permanent installations with motorized ball return systems and programmable trajectory adjusters serve high-volume training facilities. Texas and California sports academies prioritize these units for maximizing court throughput during elite youth development programs.
- Portable Units:Collapsible frames with rechargeable power systems enable deployment across multiple court locations. Traveling trainers and home users in Florida drive replacement demand as lithium battery density improves and wireless connectivity becomes standard.
- Training Aids:Supplementary equipment including shot arc guides and release-point trainers complement primary machines.
- Floor Models:Court-mounted ball return systems without full electromechanical automation occupy the entry price tier.
Automated machines dominate installed base. Portable units are where expansion concentrates.
End User:
Procurement authority and budget scale vary dramatically across customer types, with professional teams spending tenfold per installation compared to high school programs.
- Schools:Public district procurement protocols favor FCC-certified wireless units with demonstrated liability compliance. Budget constraints limit penetration to affluent suburban districts in Texas and California.
- Colleges:Athletic department capital budgets accommodate premium smart-sensor platforms with subscription analytics. Recurring software revenue potential anchors vendor sales investment here.
- Sports Academies:Private training facilities in Florida and California represent the fastest-expanding customer segment, prioritizing player throughput metrics and cloud-based progress tracking.
- Professional Teams:NBA and G-League franchises demand bespoke installations with real-time biomechanical feedback integration.
Schools dominate unit volume. Sports academies are climbing the fastest.
Technology:
Margin pools concentrate where hardware platforms capture ongoing software revenue through embedded connectivity and cloud analytics infrastructure.
- Electromechanical Systems:Motorized ball return and trajectory adjustment without digital augmentation. Legacy manufacturers defend position through institutional relationships and proven durability records.
- Smart Sensors:Embedded accelerometers and optical tracking capture shot arc, velocity, and release-point data. Collegiate programs and professional teams mandate this capability for recruiting and development decisions.
- Wireless Connectivity:FCC-compliant radio modules enable real-time data transmission to coaching tablets. Certification complexity creates barrier to entry for new market participants.
- Mobile Applications:Cloud-connected training analytics platforms transform hardware transactions into recurring subscription relationships. Small academies prefer predictable operating expenditures over capital-intensive ownership.
Electromechanical systems dominate legacy installed base. Smart sensors are gaining share fastest.
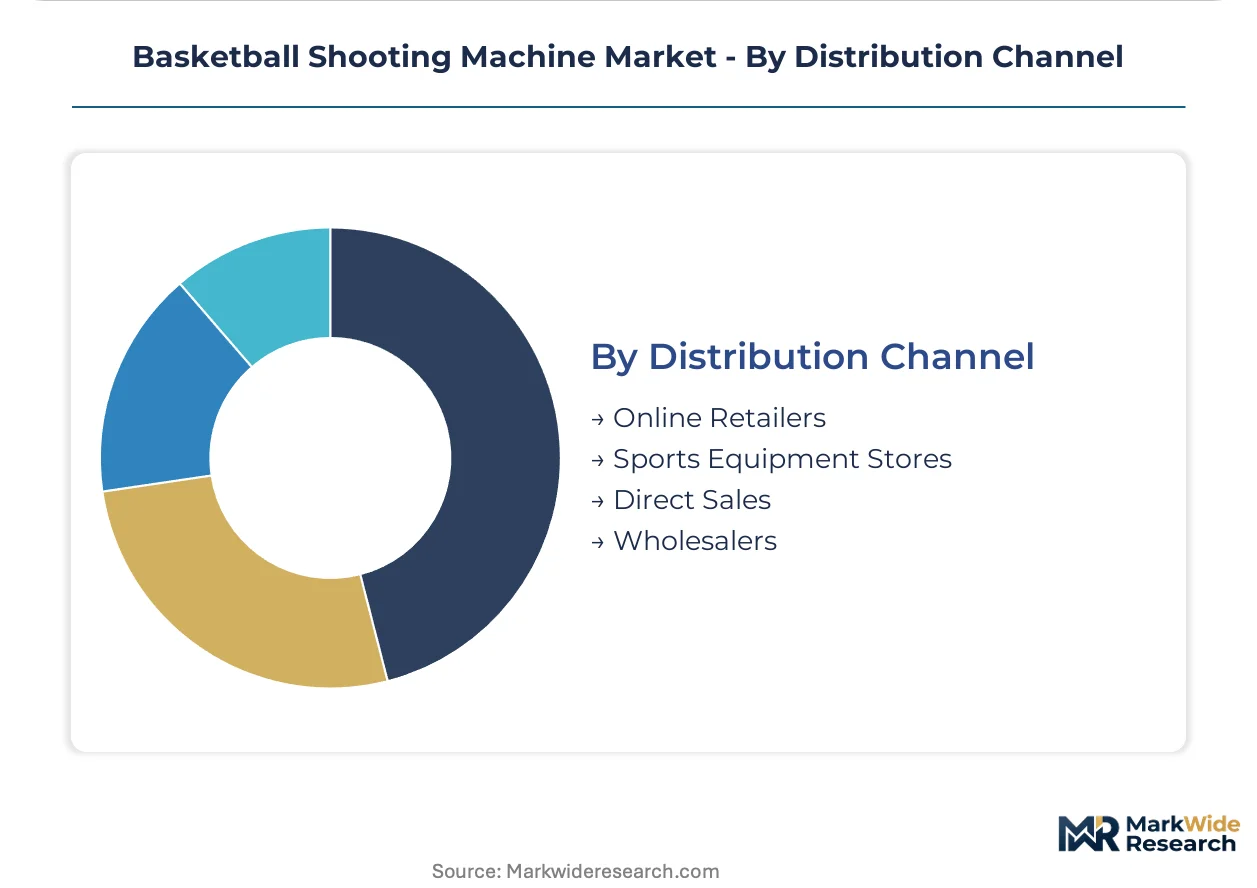
Distribution Channel:
Channel selection determines margin capture and customer relationship depth, with direct sales commanding premium positioning while online retail fragments price transparency.
- Online Retailers:Digital storefronts enable manufacturers to bypass sporting goods distributors and reach individual buyers. Direct-to-consumer expansion concentrates margin with vendors sustaining e-commerce infrastructure.
- Sports Equipment Stores:Specialty retailers provide physical demonstration and installation coordination for institutional purchasers. Regional chains in Texas and California anchor territorial coverage.
- Direct Sales:Manufacturer field teams manage complex procurement cycles for collegiate and professional accounts. Relationship investment yields multi-year service contracts and platform subscription attachment.
- Wholesalers:Distributor networks extend geographic reach to secondary markets with limited vendor sales presence.
Direct sales dominates revenue per transaction. Online retailers are where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors North American equipment flows for basketball training infrastructure, while Shenzhen's Yantian Port handles component consolidation for smart-sensor manufacturing destined for global assembly lines.
United States
Texas, California, and Florida host dense clusters of elite youth basketball academies that automate repetitive skill training to maximize court utilization. FCC certification governs wireless-enabled units, accelerating institutional approval across American school districts. Dallas-Fort Worth and Houston sports complexes drive replacement demand for portable electromechanical systems with rechargeable power.
China
Guangdong and Zhejiang provinces concentrate manufacturing capacity for motorized ball return systems and lithium battery subassemblies. MIIT standards regulate wireless radio modules for domestic and export-bound equipment. Shenzhen's electronics corridor supplies sensor components to North American and European assembly operations.
Germany
North Rhine-Westphalia and Bavaria house specialized distributors serving collegiate and professional training facilities across Central Europe. CE marking and RoHS compliance requirements shape procurement protocols for electronic subassemblies. Cologne-based sporting goods wholesalers prioritize pre-certified platforms to avoid customs delays.
Japan
Kanto region basketball academies and corporate recreational facilities drive demand for compact, precision-engineered training equipment. METI oversees industrial standards for electromechanical devices entering institutional procurement channels. Tokyo-Osaka corridor distributors emphasize durability specifications for high-frequency commercial use.
Australia
New South Wales and Victoria sports institutes integrate automated training systems into elite athlete development pathways. The country's national communications regulator manages electromagnetic compliance for wireless-enabled units. Melbourne-based academy networks favor cloud-connected platforms with subscription analytics over capital-intensive ownership models.
Basketball Shooting Machine Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: heritage manufacturers with institutional relationships, software-native entrants with subscription platforms, and scale-driven fabricators with manufacturing cost advantages. Strategic archetypes include brand-heritage defenders, ecosystem builders, and price-competitive volume players. Dominant competitive moves encompass direct-to-consumer channel expansion and recurring revenue model adoption through training analytics subscriptions.
Within the heritage-manufacturer tier, Shoot-A-Way exemplifies brand-anchored positioning sustained through decades of institutional field presence. Dr. Dish Basketball represents the ecosystem-builder archetype, occupying a position where software subscriptions transform hardware transactions into recurring revenue relationships. SIBOASI sits within the scale-driven tier, leveraging manufacturing concentration to serve mid-market price sensitivity across distributed geographic markets.
| Leading Market Players |
|---|
| Shoot-A-Way |
| Dr. Dish Basketball |
| Airborne Athletics |
| Franklin Sports |
| Lifetime |
| Triumph Sports |
| SIBOASI |
| GRIND Basketball |
| Noah Basketball |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Guangdong Province's lithium battery cell manufacturing is compressing supplier margins and enabling portable unit assemblers to negotiate favorable contract terms, while simultaneously pressuring electromechanical-only heritage manufacturers to absorb cost increases or cede share to software-augmented competitors.
Pricing Analysis
Volume-discount tiering separates institutional procurement contracts above fifty units from individual academy purchases and direct-to-consumer transactions. Premium positioning commands FCC-certified wireless platforms with embedded sensor analytics, while standard electromechanical units compete on durability specifications and economy-tier floor models serve entry-level home users. Cost compression in the mid-market portable segment intensifies as SIBOASI's manufacturing scale forces margin concessions from North American assemblers. Schools and small academies exhibit acute price sensitivity, whereas collegiate athletic departments prioritize subscription analytics attachment over upfront hardware expenditure.
Supply Chain Analysis
Contract-manufacturing concentration rests with Shenzhen-based electronics assembly specialists handling sensor integration and Guangzhou-area metal fabricators producing motorized ball return chassis. China, South Korea, and Japan anchor lithium-ion cell supply for rechargeable portable units, while German and Italian component houses supply precision drive motors for premium automated installations. Raw material exposure centers on cobalt and lithium carbonate price volatility, rare earth magnet availability for motor assemblies, and RoHS-compliant circuit board substrates. Single-source vulnerability concentrates in East Asian battery management system controllers. Distribution runs through direct sales teams for institutional accounts, online storefronts for individual buyers, and regional sporting goods distributors for secondary market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in the mid-market portable segment where subscription-native entrants can displace electromechanical heritage brands, as academy operators and traveling trainers demand cloud-connected analytics without premium-tier capital outlay.
For Market Incumbents: Entrench institutional relationships through exclusive multi-year service contracts bundling hardware refresh cycles with continuous software platform development. Accelerate backward integration into sensor component supply to offset margin pressure from East Asian contract manufacturers. Prioritize FCC pre-certification investment to accelerate district procurement timelines and defend against software-native competitors. For New Entrants and Emerging Players: Pursue white-space expansion in Florida's dense academy cluster where player throughput metrics drive equipment procurement decisions and incumbent field presence remains thinner than Texas or California. Target individual trainers and home users through direct-to-consumer digital channels with portable units featuring standard wireless connectivity and modular subscription tiers. Anchor go-to-market strategy on mobile application development capability rather than electromechanical heritage. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable smart-sensor manufacturing as component commoditization and contract-manufacturing competition reduce minimum viable scale thresholds. Long-term viability favors software-augmented hardware platforms with recurring revenue attachment over pure electromechanical fabricators facing replacement cycle compression. Acquisition target archetype: mid-market assemblers with established FCC certification and dormant subscription infrastructure requiring analytics platform integration. Monitor lithium carbonate price stabilization and MIIT export license processing velocity as inflection indicators for margin recovery and supply security.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Launch | Transforms hardware transactions into recurring revenue relationships with collegiate athletic departments. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional sporting goods distributors to capture margin from individual trainers and home users. |
| Sensor Component Backward Integration | Reduces exposure to East Asian supply concentration and accelerates product development cycles. |
| FCC Pre-Certification Investment | Accelerates institutional procurement approval across American school districts and collegiate programs. |
| Academy Network Partnership | Secures exclusive equipment placement with elite youth development programs in Texas and Florida. |
Research Methodology
Cross-validation between primary interviews with sports academy operators, collegiate athletic equipment managers, and basketball training facility directors anchors the qualitative findings, while secondary validation draws from FCC equipment authorization databases, CPSC safety incident reports, and SEC filings of publicly traded sporting goods distributors. Bottom-up triangulation aggregates unit shipment estimates by product tier and distribution channel, converging with top-down market sizing derived from capital expenditure disclosures of institutional athletic departments.
Calibration against historical replacement cycle data and sensor technology adoption curves shapes the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, end-user procurement authority, technology capability tier, and regional regulatory cluster. CAGRs derive from fitted growth curves incorporating academy network expansion rates, battery energy density improvement trajectories, and cloud analytics platform penetration assumptions.
Macroeconomic conditions sit as an overlay; deviation in lithium raw material prices, freight rate volatility, or institutional education budget allocations would shift the trajectory. Forecasts reflect documented assumptions regarding technology refresh rates and subscription attach rates. Quarterly review of FCC certification application volumes, academy network formation rates in target states, and lithium carbonate spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Mixed Martial Arts Equipment Market
Sports Equipment
Tennis Racquet Market
Sports Equipment
Balance Bike Market
Sports Equipment
Rowing Oars Market
Sports Equipment
Global Skateboard Market
Sports Equipment
Gymnastic Hoops Market
Sports Equipment
Asia-Pacific Stand-Up Paddleboard Market
Sports Equipment
Crampon Market
Sports Equipment
Global Pickleball Equipment Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Concussion Helmets Market
Sports Equipment
Air Sports Equipment Market
Sports Equipment
Kung Fu Uniform Market
Sports Equipment
Field Hockey Equipment Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Wave Windsurf Boards Market