
 Kung Fu Uniform Market | 2026-2036
Kung Fu Uniform Market Size, Share, and Industry Trends Forecast 2026-2036
Kung Fu Uniform Market Foresight
EU REACH restrictions on azo dyes and formaldehyde residues in textiles is shifting procurement criteria for European martial arts retailers. Li-Ning leverages its domestic supply chain in China to sustain cost advantages in cotton-blend traditional uniforms. Tiger Claw competes primarily through specialty distribution in North American dojos, while ProForce differentiates via reinforced stitching standards for high-intensity training gear.
A kung fu uniform is a purpose-built martial arts garment, typically constructed from breathable natural fibers or performance synthetics with a weight range of 8–12 ounces per square yard, designed to permit full range of motion during striking, kicking, and stance transitions. Traditional uniforms remain the volume anchor across institutional buyers, while modern uniforms incorporating moisture-wicking polyester blends represent the fastest-expanding material segment as competitive practitioners prioritize thermoregulation. The adult size category dominates revenue contribution, though custom sizing commands premium positioning in boutique channels serving professional demonstration teams.
China's SAMR enforces GB 18401 national textile safety standards that mandate pH and colorfastness testing for all domestically sold martial arts apparel, effectively raising compliance costs for smaller workshops. The US Consumer Product Safety Commission monitors flammability standards for children's martial arts uniforms sold through retail channels. Stakeholders must monitor evolving chemical disclosure requirements across multiple jurisdictions, as divergent textile safety protocols threaten to fragment sourcing strategies and complicate cross-border inventory management.
Market Dynamics
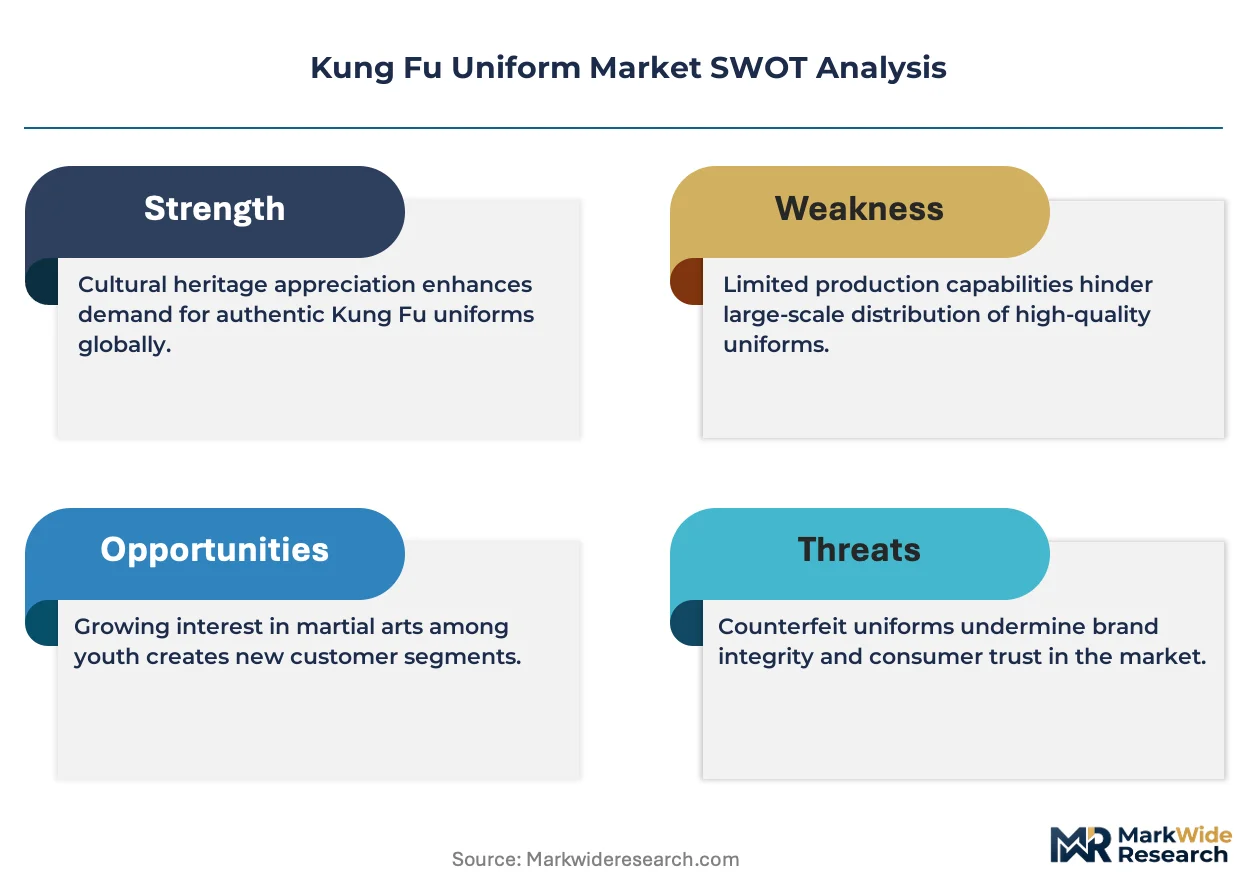
EU REACH azo dye restrictions and China's GB 18401 textile safety standards are forcing manufacturers to reformulate fabric treatments and relocate dyeing operations, compressing margins for smaller workshops while advantaging vertically integrated producers with captive testing labs.
Growth Catalysts
- Professional academy procurement:North American martial arts schools are mandating certified training apparel with documented chemical compliance, creating institutional demand for tested uniforms.
- Moisture-wicking synthetics:Polyester-cotton blends with thermoregulating properties are displacing traditional all-cotton construction in competitive practitioner segments.
- REACH compliance premium:European retailers are screening suppliers for formaldehyde-free certification, rewarding manufacturers with pre-certified inventory.
Market Restraints
- Cotton price volatility:Raw fiber costs fluctuate with commodity markets, squeezing margin on natural-fiber traditional uniforms.
- Guangdong supply concentration:Overreliance on clustered manufacturers in one province creates disruption risk from regional logistics bottlenecks.
- Flammability testing costs:US CPSC children's apparel standards require expensive third-party certification for youth uniform lines.
Strategic Opportunities
- Custom sizing boutiques:Professional demonstration teams in South Korea and Japan seek made-to-measure uniforms with premium positioning.
- E-commerce direct channels:Manufacturers are bypassing wholesale distributors to sell certified uniforms through proprietary online storefronts.
- Biodegradable synthetics:PLA-based performance fabrics align with EU Green Deal procurement criteria for sustainable sportswear.
Industry Challenges
- Multi-jurisdiction chemical disclosure:Divergent textile safety protocols between EU REACH, China GB standards, and US state-level regulations complicate cross-border inventory management.
- Dyehouse certification timelines:Third-party colorfastness and pH testing for GB 18401 compliance adds 3-6 weeks to production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kung Fu Uniform Market |
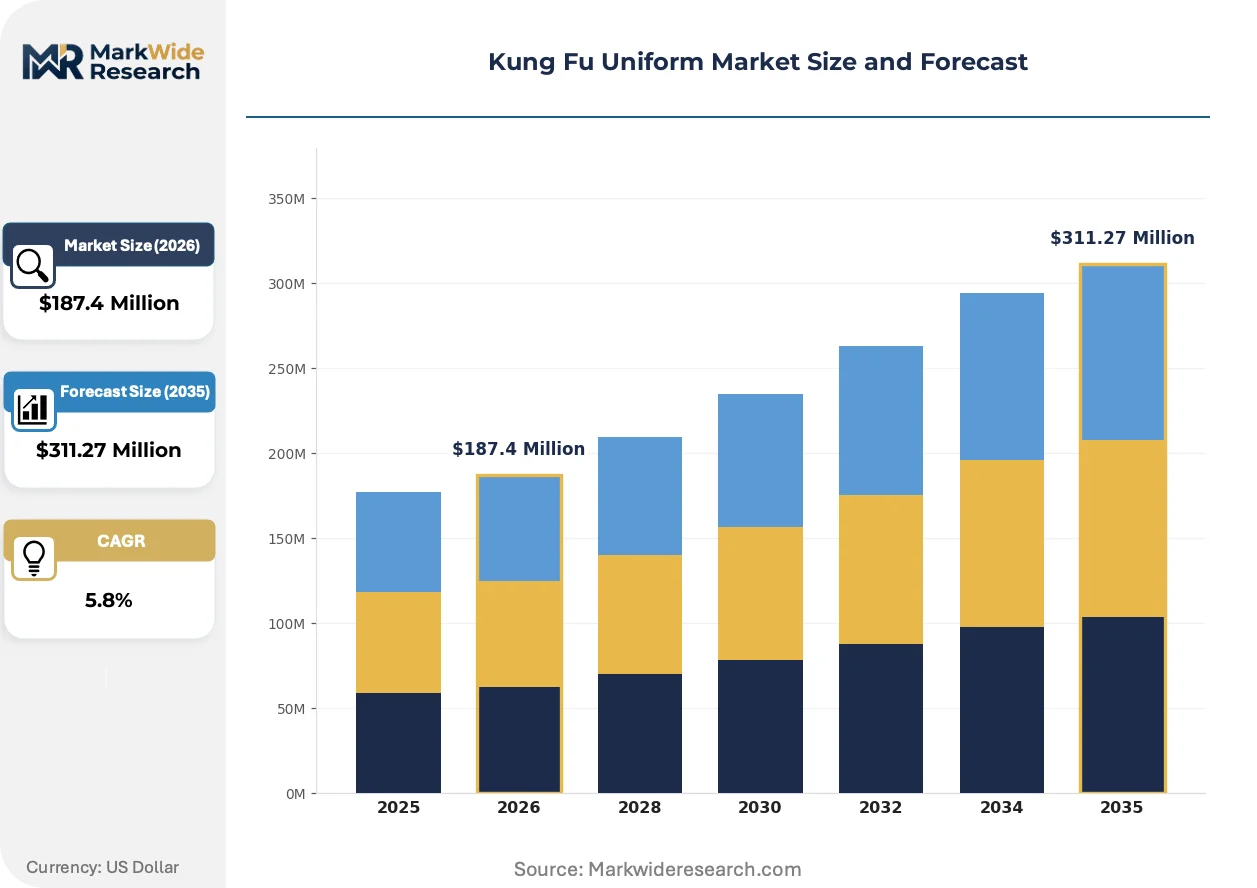
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Uniforms, Modern Uniforms, Training Gear, Competition Attire Material: Cotton, Polyester, Blends, Silk Size: Children, Adults, Plus Sizes, Custom Sizes Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Kung Fu Direct, Quality Things International, Li-Ning, SupplyLeader, Woosung, Tiger Claw, ProForce, Made-in-China Suppliers, AMAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kung Fu Uniform Market Shifts & Advancements
Material science advances and regulatory disclosure mandates are restructuring how kung fu uniforms are manufactured, tested, and sold. Three developments are compressing traditional supply arrangements while opening premium positioning for compliant producers.
Recycled polyester microfiber blends with embedded moisture channels are absorbing sweat management functions previously handled by cotton underlayers. Competitive tournament practitioners in Australia and Germany are specifying these fabrics for extended training sessions. The technology is absorbing market share from conventional cotton-poly constructions by enabling single-garment solutions that reduce laundry cycles and fabric weight.
China's SAMR is tightening enforcement of GB 18401 pH and colorfastness testing for all domestically sold martial arts apparel. Manufacturers without in-house labs must queue at certified third-party facilities, extending lead times. Smaller workshops in Fujian and Zhejiang provinces are consolidating or exiting as compliance costs rise, concentrating production among larger operators with captive testing capacity.
Academy buyers are consolidating vendor relationships around suppliers with pre-documented chemical safety certifications. North American dojo chains are shifting from spot purchasing to annual contracts with audited manufacturers. This concentration is most visible in California and Texas, where multi-location school networks are standardizing uniform sourcing to reduce administrative overhead and liability exposure.
Kung Fu Uniform Market Segmentation
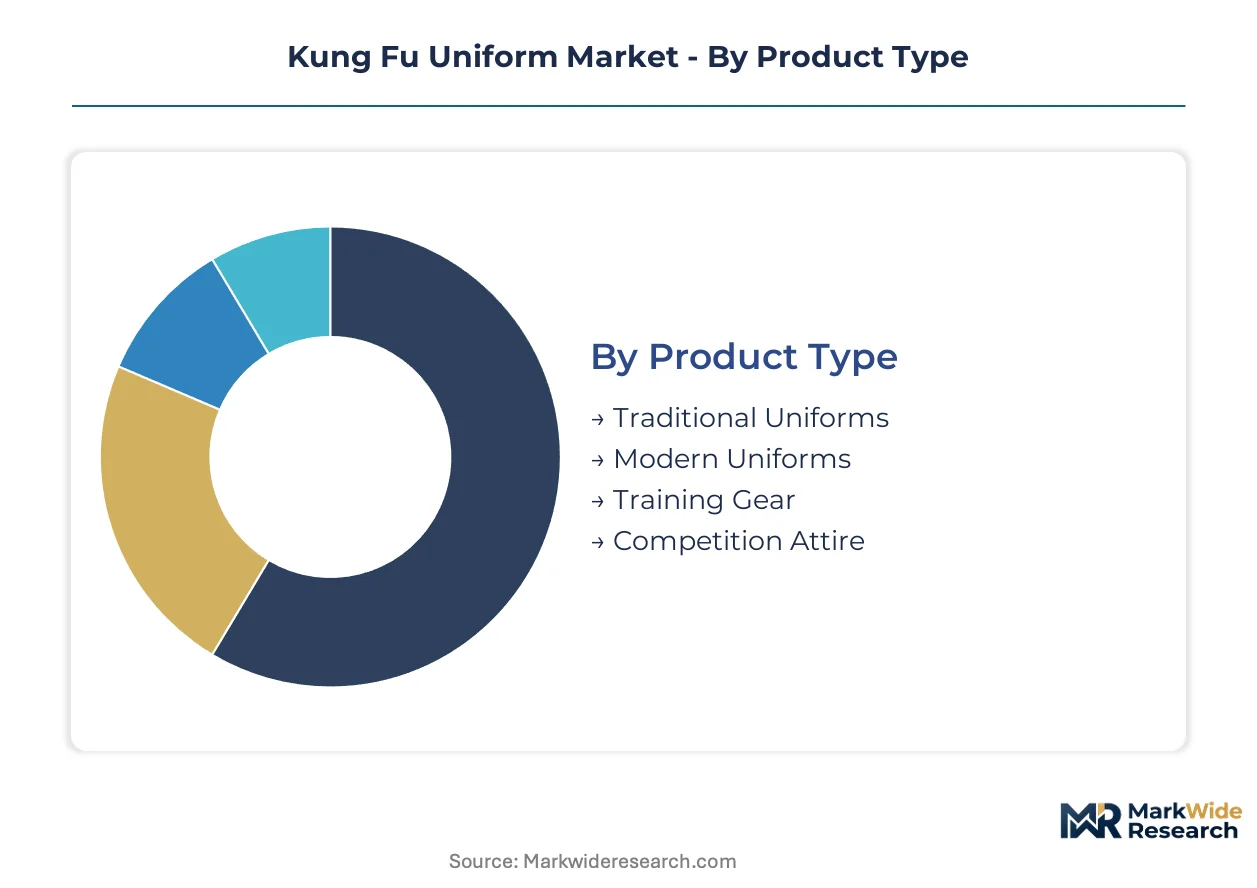
Uniform procurement patterns diverge sharply between institutional academies and individual practitioners, with material specifications and sizing flexibility determining vendor selection criteria across each buyer category.
Product Type:
Construction philosophy separates heritage designs from performance-engineered alternatives, with institutional buyers prioritizing durability certifications and competitive practitioners demanding thermoregulation features.
- Traditional Uniforms:All-cotton or cotton-heavy constructions with mandarin collars and frog-button closures dominate wushu school procurement in China. Guangdong Province workshops supply bulk orders to domestic academies seeking GB 18401-compliant natural fiber garments.
- Modern Uniforms:Polyester-cotton blends with moisture-wicking finishes are expanding most quickly among tournament competitors in Australia and Germany. These single-garment solutions reduce laundry cycles while maintaining range-of-motion performance during extended training.
- Training Gear:Reinforced stitching and heavier fabric weights serve high-intensity practitioners requiring durability under repetitive stress.
- Competition Attire:Lightweight constructions with standardized color palettes meet federation requirements for judged events.
Traditional Uniforms lead on scale; Modern Uniforms lead on momentum.
Material:
Raw fiber selection drives compliance complexity, with natural fibers facing chemical testing mandates and synthetics navigating biodegradability scrutiny under EU procurement frameworks.
- Cotton:Breathable natural fiber subject to GB 18401 pH and colorfastness testing in China. Price volatility in commodity markets squeezes margin for smaller dyehouses without captive sourcing.
- Polyester:Recycled microfiber blends with embedded moisture channels absorb sweat management functions previously requiring cotton underlayers. German and Australian competitive practitioners specify these fabrics for thermoregulation during extended sessions.
- Blends:Cotton-polyester combinations balance breathability with wrinkle resistance for multi-use practitioners.
- Silk:Premium ceremonial constructions serve demonstration teams and formal exhibitions with limited volume scale.
Cotton dominates procurement volume; recycled polyester climbs the fastest on sustainability credentials.
Size:
Demographic coverage and customization depth determine pricing architecture, with standardized sizing enabling volume production and bespoke measurements capturing premium positioning.
- Adults:Standardized size runs anchor revenue contribution across institutional and retail channels, with bulk academy orders concentrating in medium-to-large ranges.
- Children:US CPSC flammability testing requirements add certification costs for youth uniform lines, compressing margin on smaller garment constructions.
- Plus Sizes:Extended size ranges address underserved practitioner segments with modified pattern grading.
- Custom Sizes:Made-to-measure services command premium positioning for professional demonstration teams in South Korea and Japan requiring precise fit for televised performances.
Adults anchor revenue contribution; Custom Sizes capture the steepest premium multiples.
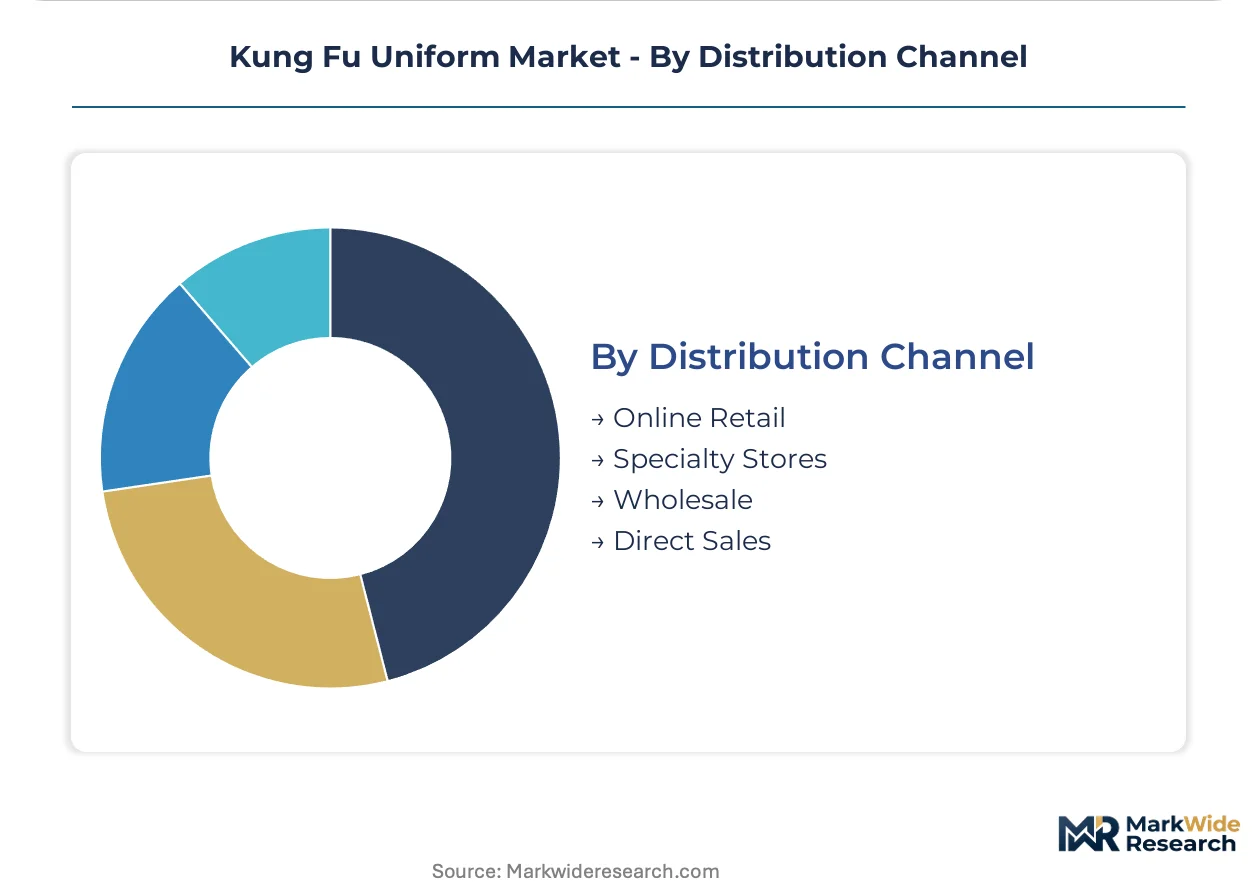
Distribution Channel:
Channel selection reflects buyer sophistication and compliance documentation requirements, with audited supply chains gaining preference among liability-conscious institutional purchasers.
- Online Retail:Direct-to-practitioner storefronts bypass wholesale markups while offering chemical certification documentation. California and Texas dojo chains are standardizing sourcing through audited e-commerce vendors to reduce administrative overhead.
- Specialty Stores:Physical dojo-adjacent locations provide fitting services and immediate availability for new enrollees requiring rapid uniform procurement.
- Wholesale:Aggregated purchasing for multi-location academy networks concentrates volume with pre-certified manufacturers.
- Direct Sales:Manufacturer-proprietary channels capture margin while controlling compliance narrative for REACH and GB standard documentation.
Wholesale dominates institutional volume; Online Retail gains share fastest on certification transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kung fu uniform production traces its industrial origins to Guangdong Province workshops that supplied domestic wushu academies before scaling into export manufacturing during the late twentieth century.
China
Domestic wushu school procurement and GB 18401 textile safety enforcement drive institutional demand. SAMR mandates pH and colorfastness testing for all domestically sold martial arts apparel. Guangdong Province manufacturers cluster in Foshan and Dongguan, supplying both domestic academies and export channels while consolidating as smaller workshops exit under rising compliance costs.
United States
Multi-location dojo chains in California and Texas standardize uniform sourcing through audited vendors. The CPSC monitors flammability standards for children's martial arts uniforms sold through retail channels. Los Angeles and Houston metropolitan areas concentrate specialty distribution networks serving academy procurement.
Germany
Competitive tournament practitioners specify recycled polyester microfiber blends for thermoregulation during extended training sessions. EU REACH restrictions on azo dyes and formaldehyde residues shift procurement criteria toward pre-certified inventory. Berlin and Munich host specialty retailers screening suppliers for chemical compliance documentation.
Australia
Tournament competitors absorb moisture-wicking synthetic uniforms for single-garment training solutions. The country's national consumer protection regulator enforces textile labeling standards for imported sportswear. Sydney and Melbourne concentrate competitive practitioner populations driving premium fabric specification.
South Korea
Professional demonstration teams seek made-to-measure uniforms with premium positioning for televised performances. The national standards body administers textile quality certification programs for performance apparel. Seoul anchors custom sizing boutiques serving choreographed martial arts productions.
Kung Fu Uniform Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent manufacturing models. Vertically integrated Chinese manufacturers with captive dyeing and testing facilities capture institutional volume from North American academy chains. Three archetypes dominate: heritage sportswear brands leveraging domestic supply chains, specialty distributors embedding in dojo-adjacent retail, and direct-to-practitioner e-commerce platforms. Competitive moves concentrate on pre-certification inventory positioning for REACH and GB standard compliance, plus backward integration into textile finishing to compress lead times.
Among China-based manufacturers, Li-Ning exemplifies heritage sportswear archetypes with domestic supply chain control. Specialty distributors include Tiger Claw, which occupies a position embedded in North American dojo procurement channels. ProForce represents the performance-engineered tier with reinforced construction standards. These three anchors illustrate how compliance documentation and material specification separate competitive positioning across institutional and practitioner segments.
| Leading Market Players |
|---|
| Kung Fu Direct |
| Quality Things International |
| Li-Ning |
| SupplyLeader |
| Woosung |
| Tiger Claw |
| ProForce |
| Made-in-China Suppliers |
| AMAS |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between REACH-compliant premium inventory and untested commodity stock separates pricing power from margin compression across Guangdong manufacturing clusters. This divergence manifests in procurement contracts where North American academy chains pay documented-chemical premiums while smaller workshops absorb testing cost spikes without pricing recourse.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors the market, with GB 18401 certification tier and volume scale as primary differentiation drivers. Price differentiation intensifies as dyehouse testing queues extend lead times for smaller producers, squeezing their margin position. Academy buyers demonstrate lowest price sensitivity for pre-certified inventory, while individual practitioners through direct channels exhibit highest elasticity.
Supply Chain Analysis
Direct-to-academy wholesale channels handle institutional volume, while proprietary e-commerce storefronts capture margin from individual practitioners. Manufacturing concentrates in China, Vietnam, and Bangladesh for cut-and-sew operations, with raw cotton drawing from US, India, and Brazilian commodity markets. Single-source vulnerability in Guangdong dyeing capacity creates disruption exposure from SAMR enforcement waves. Distribution runs through audited vendor networks for liability-conscious North American dojo chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as academy procurement shifts toward documented chemical compliance and away from spot purchasing. Premium specification demand from tournament competitors accelerates this transition.
For Market Incumbents: Anticipate consolidation pressure from vertically integrated Chinese manufacturers with captive testing labs by securing backward integration into textile finishing. Defend position by locking annual contracts with California and Texas dojo chains before compliance documentation becomes table stakes. Certification investment represents the critical lever for margin preservation. For New Entrants and Emerging Players: Direct-to-practitioner e-commerce routes offer lowest barrier entry for white-space capture. Target custom sizing boutiques serving South Korean and Japanese demonstration teams as the most penetrable premium segment. Position through biodegradable synthetic fabrics aligned with EU Green Deal procurement criteria as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where compliance cost spikes force smaller Fujian and Zhejiang workshops to exit. Long-term viability favors operators with in-house GB 18401 testing capacity and established North American academy relationships. Acquisition target archetype: mid-tier Guangdong manufacturers with dyehouse assets but underdeveloped export certification. Watch EU REACH enforcement intensity as the signal for premium inventory valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Textile Finishing | Captive dyeing capacity compresses lead times for GB 18401 compliance documentation. |
| Direct-to-Consumer E-Commerce Launch | Proprietary storefronts bypass wholesale markups while controlling REACH certification narrative. |
| Biodegradable Synthetic Fabric Introduction | PLA-based performance aligns with EU Green Deal sustainable sportswear procurement criteria. |
| Custom Sizing Boutique Partnership | Made-to-measure services capture premium multiples from South Korean demonstration teams. |
| Annual Contract Standardization | Multi-year academy agreements reduce administrative overhead for California dojo chains. |
Research Methodology
Coverage spans China, United States, Germany, Australia, and South Korea, with primary inputs from each market. The approach combines interviews with martial arts academy procurement directors, textile compliance officers at Guangdong manufacturers, specialty retail buyers, and tournament federation equipment managers, validated against secondary sources including SAMR regulatory filings, EU ECHA substance restrictions, US CPSC children's apparel standards, and customs trade data. Bottom-up academy procurement surveys triangulate with top-down manufacturing capacity estimates.
Rate-of-change decomposition separates volume growth from price realization across material type, buyer category, distribution channel, and regional regulatory cluster dimensions. CAGRs derive from segmented demand modeling incorporating practitioner enrollment trends, compliance cost pass-through elasticity, and synthetic fabric substitution curves. Forecast inputs include dyehouse certification queue dynamics and EU REACH enforcement probability.
The model assumes a particular technology adoption path for moisture-wicking polyester blends; alternative pathways for biodegradable PLA fabrics would alter the outlook. Forecasts reflect assumptions around SAMR enforcement consistency and North American academy consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Agility Ladders Market
Sports Equipment
Europe Winter Sports Equipment Market
Sports Equipment
Boxing Gloves Market
Sports Equipment
Motocross Gears Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
Shuttlecock Market
Sports Equipment
Ladderball Market
Sports Equipment
Stadium Seating Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Recreational Rowing Boats Market
Sports Equipment
Surfing Boards Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Global Golf Rangefinders Market