
 Halogen Biocides Market | 2026-2036
Halogen Biocides Market Size, Share, and Industry Trends Forecast 2026-2036
Halogen Biocides Market Analysis
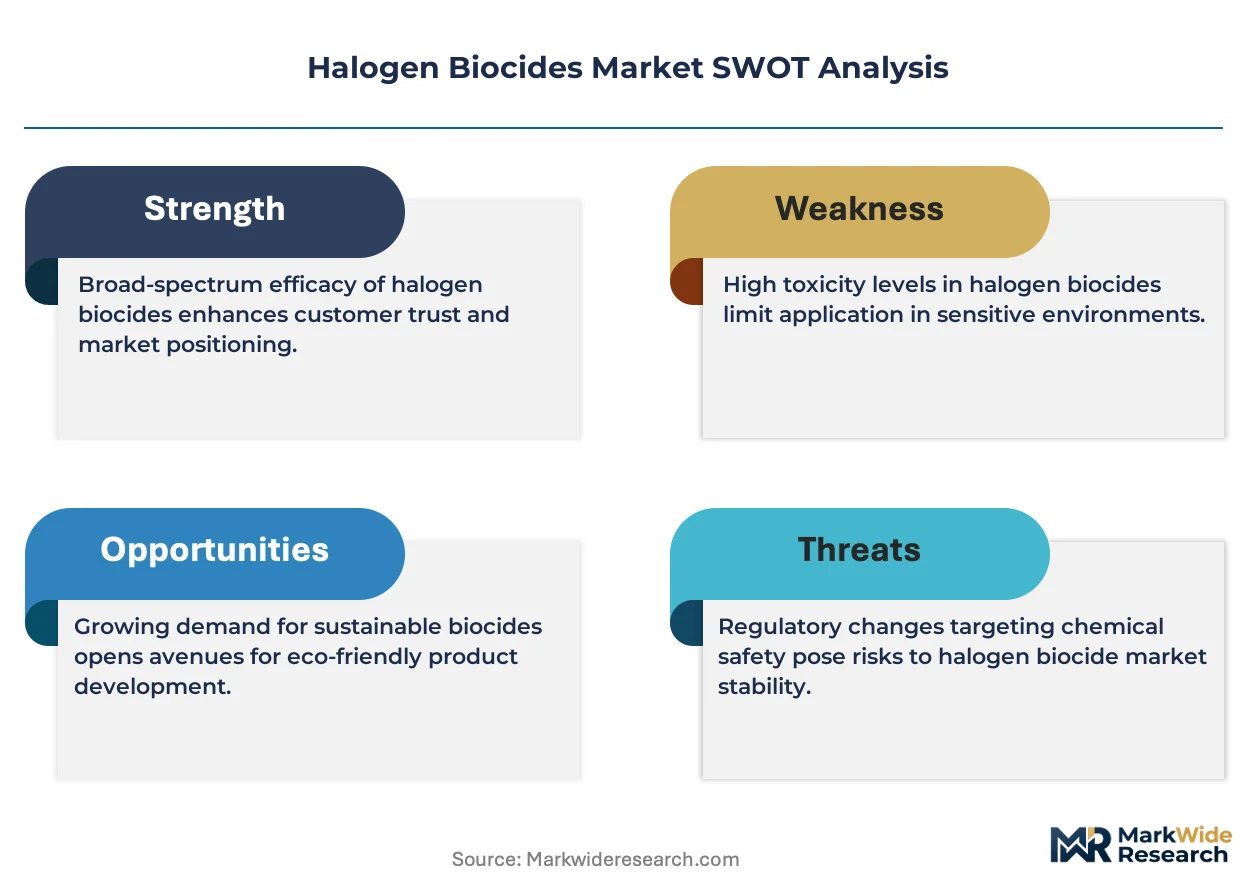
The EU F-Gas Regulation is pivoting industrial buyers toward halogen biocide formulations with lower global warming potential. Nouryon leverages its integrated bromine supply chain to sustain cost leadership across European water treatment accounts. Lonza anchors its position through specialized iodine-based sanitizers for healthcare end users. Clariant AG differentiates via advanced chlorine dioxide delivery systems for food processing plants.
Halogen biocides are chemical agents containing chlorine, bromine, iodine, or fluorine that disrupt microbial cell membranes through oxidation, typically dosed at 0.1–10 ppm depending on target organism and water chemistry. These compounds serve as primary disinfectants in municipal drinking water systems, cooling towers, and food contact surface sanitation where rapid microbial kill rates are essential. Chlorine derivatives dominate volume demand across municipal water treatment applications due to established infrastructure compatibility and low unit cost. Bromine-based formulations are expanding fastest in industrial cooling systems where pH tolerance and biofilm penetration justify premium positioning. Iodine concentrates in healthcare and personal care segments where skin compatibility and residual efficacy command higher margin pools.
EPA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act govern product efficacy claims and label restrictions in the United States, while ECHA's Biocidal Products Regulation mandates active substance approval and product authorization across EU member states. China's Ministry of Ecology and Environment enforces discharge standards that compel industrial facilities to upgrade halogen dosing systems or face operational penalties. Stakeholders must monitor evolving substitution pressures from peracetic acid and UV systems while defending halogen value propositions through formulation innovation and application-specific efficacy documentation.
Market Dynamics
REACH authorization timelines and EU F-Gas Regulation phase-down schedules are compressing formulation windows for legacy halogen biocides while redirecting R&D budgets toward lower-risk active substances.
Growth Catalysts
- Municipal water infrastructure upgrades:Germany's federal investment programs in drinking water networks are expanding chlorine derivative procurement for primary disinfection systems.
- REACH compliance frameworks:ECHA's Biocidal Products Regulation mandates are accelerating substitution toward approved active substances with favorable environmental profiles.
- Industrial cooling tower expansion:Data center buildouts across the Netherlands and Belgium are driving bromine-based biocide demand for pH-tolerant biofilm control.
Market Restraints
- Bromine supply concentration:Dead Sea extraction operations and a limited producer base create vulnerability to geopolitical disruption and input cost spikes.
- Peracetic acid substitution:Food processing facilities are migrating to peroxygen-based alternatives to avoid chlorinated byproduct formation in organic product lines.
- EPA registration timelines:Federal Insecticide, Fungicide, and Rodenticide Act review cycles extending 24-36 months delay new active substance commercialization in North American markets.
Strategic Opportunities
- Chlorine dioxide delivery innovation:Advanced two-part generation systems for food contact surfaces address residual taste concerns while maintaining sporicidal efficacy.
- Healthcare iodine concentrates:Surgical prep and wound care segments reward skin-compatible formulations with premium positioning above commodity disinfectants.
- UV-halogen hybrid systems:Convergence of ultraviolet irradiation with controlled halogen dosing reduces chemical load while ensuring regulatory-compliant kill rates.
Industry Challenges
- ECHA dossier preparation expertise:Shortage of regulatory toxicologists and environmental fate specialists extends approval timelines and raises compliance costs for SMEs.
- Legacy dosing infrastructure retrofit:Municipal utilities face capital constraints when upgrading Victorian-era chlorine contact tanks to accommodate advanced chlorine dioxide or bromine systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halogen Biocides Market |
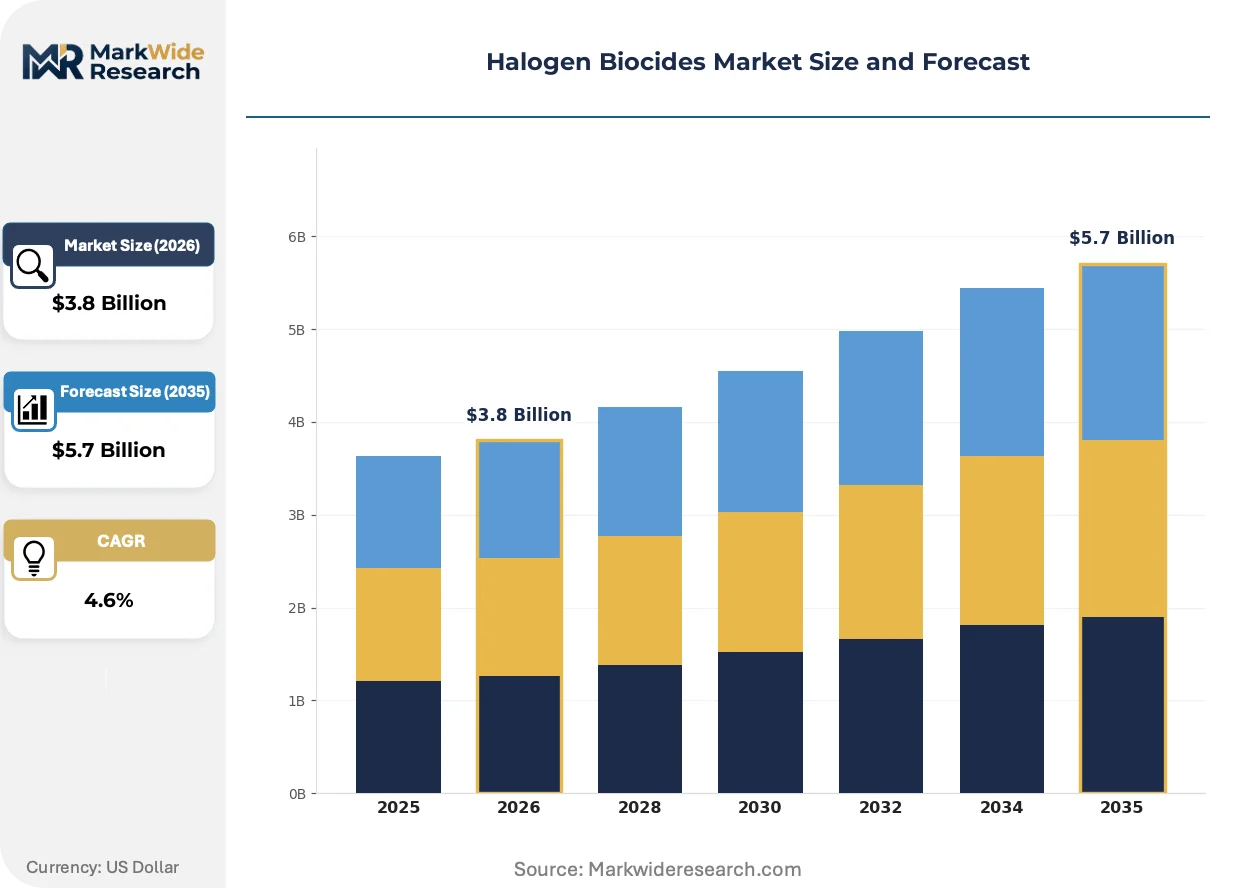
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorine, Bromine, Iodine, Fluorine Application: Water Treatment, Food Processing, Healthcare, Personal Care End User: Municipalities, Industrial Plants, Hospitals, Restaurants Distribution Channel: Direct Sales, Online Retail, Distributors, Others |
| Companies Covered | Nouryon, Lonza, Clariant AG, SUEZ, Albemarle Corporation, DuPont, BASF SE, Solvay, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halogen Biocides Market Emerging Trajectories
Real-time dosing control systems and predictive microbial monitoring are displacing fixed-concentration protocols across industrial water treatment, compressing chemical consumption while tightening effluent compliance.
Electrochemical halogen generation is automating on-site production of sodium hypochlorite and chlorine dioxide at industrial facilities, eliminating hazardous material transport and storage liabilities. Chemical processors and power plants are retrofitting cell-based systems at 15-20% annual expansion rates. This distributed manufacturing model is automating supply security while reducing working capital tied to bulk chemical inventories.
ECHA's Biocidal Products Regulation renewal assessments are forcing reformulation of legacy chloroisocyanurate products ahead of 2025-2027 approval deadlines. Industrial formulators are consolidating active substance portfolios to concentrate resources on dossier-defensible chemistries. Cooling tower operators in Germany and France are switching to stabilized bromine compounds to preempt supply discontinuity.
Water treatment utilities are unbundling chemical supply from equipment service contracts, separating procurement decisions from capital equipment vendors. Municipal buyers in the Netherlands are negotiating direct active substance supply agreements while contracting maintenance independently. This disintermediation is compressing distributor margins and rewarding producers with technical service capabilities.
Halogen Biocides Market Segmentation
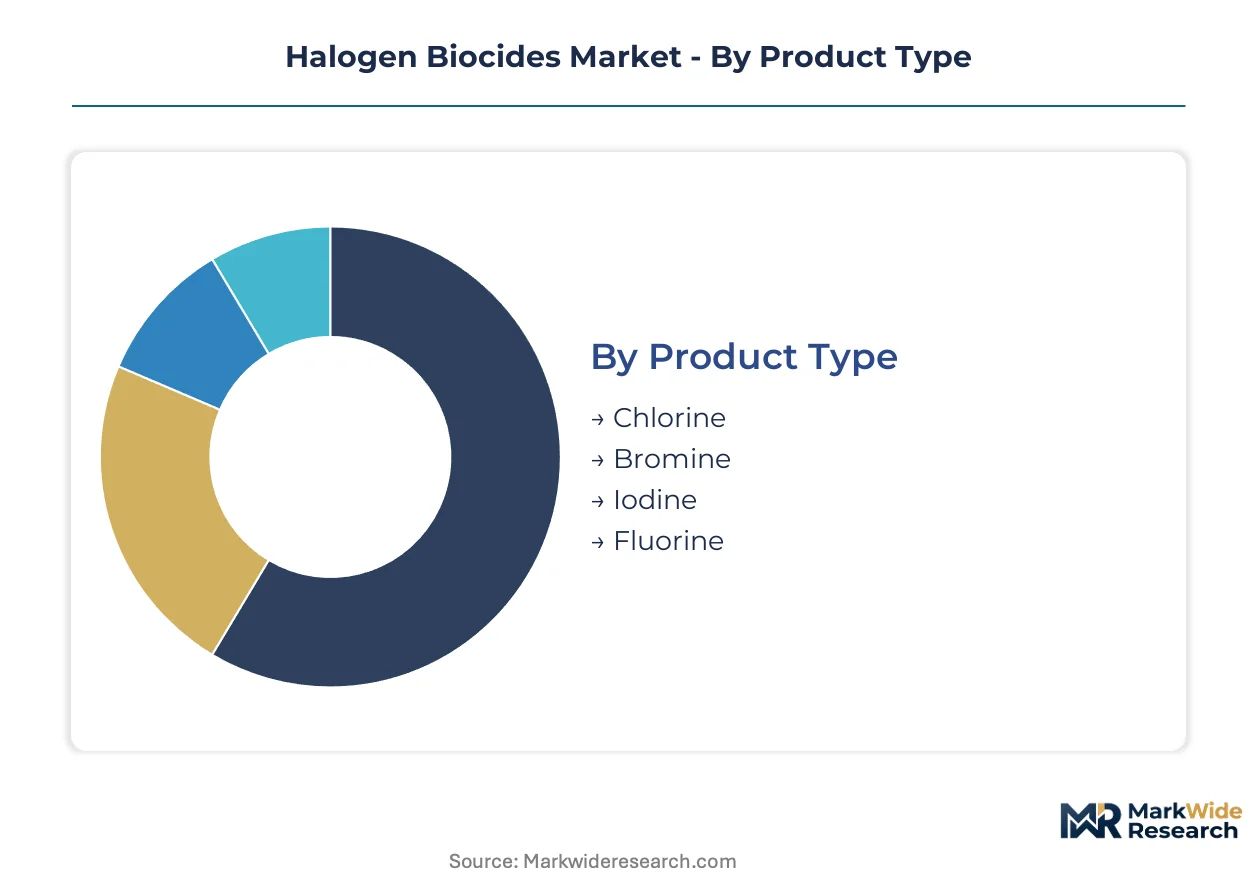
Halogen biocide procurement patterns diverge sharply across application contexts, with municipal water utilities prioritizing cost-per-kill metrics while healthcare buyers emphasize skin compatibility and residual safety profiles. Understanding these segment-specific value drivers reveals where formulation premiums command sustainable pricing power versus commodity positioning.
Product Type:
Buyers in this category sort by oxidation kinetics, pH tolerance windows, and regulatory approval status rather than raw chemistry alone.
- Chlorine:Sodium hypochlorite and chloroisocyanurate derivatives dominate municipal drinking water systems due to established infrastructure compatibility and sub-dollar-per-pound unit economics. German utilities under federal infrastructure upgrade mandates are expanding chlorine derivative procurement for primary disinfection, though ECHA renewal assessments are compressing formulation windows for legacy chloroisocyanurate products.
- Bromine:Stabilized bromine compounds penetrate biofilms more effectively than chlorine in alkaline cooling water conditions, justifying 40-60% price premiums in data center and power plant applications. Netherlands and Belgium cooling tower operators are switching to stabilized bromine compounds to preempt supply discontinuity from ECHA dossier pressures.
- Iodine:Povidone-iodine and iodophore concentrates serve surgical prep and wound care segments where skin compatibility commands premium positioning above commodity disinfectants.
- Fluorine:Perfluorinated biocidal actives remain niche due to EU F-Gas Regulation phase-down schedules and environmental persistence concerns, limiting deployment to specialized semiconductor cleaning applications.
Chlorine leads volumes today; bromine is gaining share fastest.
Application:
Volume concentration follows regulatory enforcement intensity, with effluent standard tightening accelerating procurement in water treatment relative to discretionary sanitation segments.
- Water Treatment:Municipal drinking water and industrial cooling systems represent the demand anchor, driven by China's Ministry of Ecology and Environment discharge standards and Germany's federal network investment programs. Real-time dosing control systems are displacing fixed-concentration protocols across industrial treatment, compressing chemical consumption while tightening compliance.
- Food Processing:Chlorine dioxide delivery systems for contact surface sanitation face substitution pressure from peracetic acid as organic product lines avoid chlorinated byproduct formation.
- Healthcare:Surgical prep, instrument sterilization, and wound care applications reward iodine-based formulations with premium pricing pools above commodity disinfectants.
- Personal Care:Iodine concentrates in antiseptic soaps and cosmetic preservatives where residual efficacy and skin compatibility determine formulation selection.
Water treatment commands the volume base; food processing faces the steepest substitution headwinds.
End User:
Procurement sophistication separates municipal and industrial buyers with dedicated water treatment staff from healthcare and food service operators purchasing through group purchasing organizations.
- Municipalities:Victorian-era chlorine contact tanks and capital-constrained upgrade cycles create retrofit bottlenecks when transitioning to advanced chlorine dioxide or bromine systems. Dutch municipal buyers are unbundling chemical supply from equipment service contracts, negotiating direct active substance agreements.
- Industrial Plants:Chemical processors and power plants are retrofitting electrochemical halogen generation systems at 15-20% annual expansion rates, automating on-site sodium hypochlorite production.
- Hospitals:Infection control committees prioritize sporicidal efficacy and skin compatibility in surgical prep formulations, consolidating procurement around iodine-based concentrates.
- Restaurants:Food service operators favor ready-to-use sanitizers with simplified dosing to minimize training burden and regulatory audit risk.
Municipalities anchor procurement volumes; industrial plants are automating supply fastest through on-site generation.
Distribution Channel:
Channel selection correlates with buyer scale and technical service requirements, with large accounts disintermediating distributors where in-house water chemistry expertise exists.
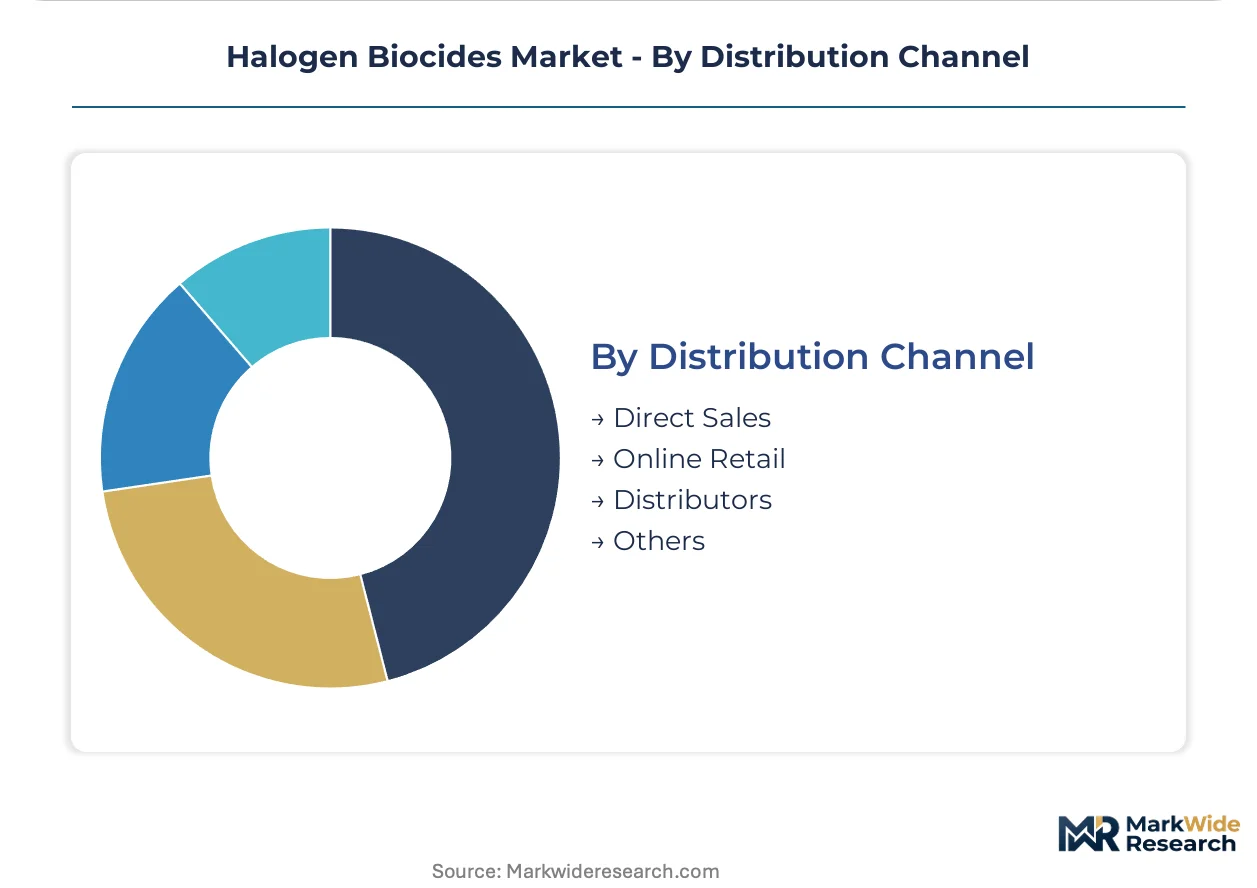
- Direct Sales:Municipal utilities and industrial accounts with dedicated water treatment engineers negotiate direct active substance supply agreements, compressing distributor margins while rewarding producers with technical service capabilities.
- Distributors:Regional chemical distributors serve mid-size industrial plants and healthcare facilities requiring localized inventory and emergency response capabilities.
- Online Retail:Small restaurants, private healthcare clinics, and maintenance departments procure ready-to-use sanitizers and test kits through B2B platforms.
- Others:Group purchasing organizations aggregate hospital and food service demand, standardizing formulary selection across member institutions.
Direct sales capture the largest account value; online retail is expanding fastest among underserviced small buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale halogen biocide production originated in German chemical complexes during the early twentieth century, with Bayer and Hoechst pioneering chlorinated disinfectant manufacturing for municipal water systems. This German foundation established technical standards and regulatory frameworks that shaped European biocide markets for decades.
Germany
Federal infrastructure investment programs are accelerating chlorine derivative procurement for drinking water network upgrades across North Rhine-Westphalia and Bavaria. ECHA's Biocidal Products Regulation mandates are compressing formulation windows for legacy chloroisocyanurate products ahead of 2025-2027 deadlines. The Rhine-Ruhr industrial corridor hosts concentrated cooling tower operations switching to stabilized bromine compounds to preempt supply discontinuity.
United States
EPA registration requirements under FIFRA govern efficacy claims and label restrictions across municipal water utilities and food processing facilities. Industrial cooling tower operators in Texas and Arizona are expanding bromine-based biocide demand for pH-tolerant biofilm control in data center buildouts. The Gulf Coast chemical processing belt is retrofitting electrochemical halogen generation systems at 15-20% annual expansion rates.
China
MEE discharge standards compel industrial facilities to upgrade halogen dosing systems or face operational penalties across the Yangtze River Delta manufacturing belt. Municipal water utilities in Shanghai and Jiangsu province are expanding chlorine derivative procurement for primary disinfection infrastructure. The Pearl River Delta electronics manufacturing cluster drives specialized demand for fluorine-based biocides in semiconductor cleaning applications.
Netherlands
Dutch municipal buyers are unbundling chemical supply from equipment service contracts, negotiating direct active substance agreements with producers. REACH compliance frameworks are redirecting R&D budgets toward lower-risk active substances with favorable environmental profiles. The Rotterdam-Antwerp port industrial complex anchors bromine-based cooling water treatment demand for petrochemical and power generation facilities.
Belgium
Data center construction across Flanders is driving bromine-based biocide procurement for industrial cooling systems requiring pH tolerance. ECHA dossier preparation requirements are extending approval timelines and raising compliance costs for SME formulators. The Port of Antwerp chemical cluster represents a concentrated demand node for stabilized bromine compounds in process water treatment applications.
Halogen Biocides Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory dossier defensibility. The vendor base organizes into three tiers: integrated bromine producers with captive raw material access, specialized iodine formulators serving healthcare verticals, and commodity chlorine derivative suppliers competing on unit economics. Dominant competitive moves include backward integration into bromine extraction assets and portfolio consolidation around REACH-defensible active substances.
Among integrated chemical producers, Nouryon and Solvay represent the bromine-integrated archetype with upstream control over Dead Sea extraction operations. Lonza occupies a position exemplifying the healthcare-specialist tier through iodine-based concentrate formulations. Clariant AG anchors the advanced delivery systems segment with differentiated chlorine dioxide generation technologies for food processing applications.
| Leading Market Players |
|---|
| Nouryon |
| Lonza |
| Clariant AG |
| SUEZ |
| Albemarle Corporation |
| DuPont |
| BASF SE |
| Solvay |
| Dow Inc. |
| Others |
Supply Flow & Price Mechanics
Electrochemical halogen generation systems are compressing delivered cost economics while redistributing supply chain power toward industrial end users with captive production capabilities. This distributed manufacturing transition simultaneously erodes bulk chemical distributor margins and concentrates raw material leverage among bromine-integrated producers with Dead Sea extraction access.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by formulation complexity and regulatory dossier defensibility. Premium iodine concentrates for healthcare applications command significant markups over commodity chlorine derivatives due to skin compatibility certification requirements and surgical prep efficacy documentation. Pricing pressure stems from peracetic acid substitution in food processing segments seeking to eliminate chlorinated byproduct liabilities. Municipal water utilities exhibit the highest price sensitivity due to fixed-rate tariff structures and capital-constrained upgrade cycles, while healthcare procurement committees prioritize efficacy documentation over unit cost.
Supply Chain Analysis
Freight cost differentials between bulk liquid chlorine derivatives and stabilized bromine compounds influence regional procurement patterns across European industrial corridors. Supply concentrates in Israel, Jordan, and the United States for bromine extraction, while chlorine derivative production clusters in Germany, China, and the Gulf Coast chemical processing belt. Raw material dependencies include Dead Sea bromine brine, chlorine gas feedstock, and iodine-rich brine solutions from caliche ore deposits. Single-source vulnerability around Dead Sea extraction operations creates geopolitical risk exposure. Distribution runs through direct sales agreements for large municipal and industrial accounts, with regional chemical distributors serving mid-size facilities requiring localized inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage potential between ECHA-regulated European markets with compressed formulation windows and Asian industrial corridors with expanding discharge standard enforcement. Producers can capture margin premiums by locating advanced bromine formulation capacity proximate to German cooling tower demand while sourcing raw materials from lower-cost extraction jurisdictions.
For Market Incumbents: Cement dossier-defensible positions around REACH-approved active substances ahead of 2025-2027 renewal deadlines. Prioritize backward integration into bromine extraction assets to insulate margin structures from Dead Sea supply concentration risks. Defend against peracetic acid substitution by documenting halogen efficacy advantages in biofilm penetration applications. For New Entrants and Emerging Players: EU F-Gas Regulation phase-down schedules in Europe open a window for lower-risk biocidal formulations with favorable environmental fate profiles. Target healthcare iodine concentrates where skin compatibility certification creates formulation stickiness and premium pricing pools. Pursue electrochemical generation equipment partnerships to bypass bulk chemical distribution infrastructure entirely. For Investors and Strategic Acquirers: Valuations sit cheapest among commodity chlorine derivative suppliers facing ECHA renewal pressure and peracetic acid displacement. Long-term viability favors integrated bromine producers with upstream extraction control and specialized iodine formulators serving defensible healthcare verticals. Monitor ECHA approval timeline announcements as the critical inflection signal for portfolio reallocation toward dossier-defensible chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine Extraction | Captive supply from Dead Sea operations insulates margin structures from input cost volatility. |
| REACH Dossier Consolidation | Concentrating resources on approved active substances reduces regulatory discontinuity risk ahead of renewal deadlines. |
| Electrochemical Generation Deployment | On-site sodium hypochlorite production eliminates hazardous material transport liabilities for industrial facilities. |
| Healthcare Iodine Concentrate Development | Surgical prep formulations command premium positioning above commodity disinfectants through skin compatibility certification. |
| UV-Halogen Hybrid System Partnerships | Convergence technologies reduce chemical load while ensuring regulatory-compliant microbial kill rates for municipal utilities. |
Methodological Framework
Coverage spans Germany, the United States, China, the Netherlands, and Belgium, with primary inputs from each jurisdiction triangulated against secondary validation. Primary research incorporated interviews with water treatment plant managers, industrial procurement leads at chemical processing facilities, ECHA regulatory affairs specialists, and healthcare infection control officers. Secondary sources included ECHA Biocidal Products Regulation approval databases, EPA FIFRA registration filings, MEE discharge standard documentation, customs trade flow data, and industry association technical reports. Bottom-up segment sizing and top-down macro validation ensured cross-check integrity across the analysis window.
Rate-of-change decomposition across the modeling period separated volume growth from price-mix effects and segment-shift dynamics. Segmentation dimensions incorporated product type, application context, end-user procurement sophistication, and distribution channel structure. CAGRs were derived from regression-based trending of disclosed industrial procurement volumes and regulatory enforcement intensity indicators. Forecast inputs included ECHA approval timeline trajectories, municipal infrastructure investment program announcements, and data center cooling capacity buildout pipelines.
Revisions become necessary when ECHA accelerates or delays active substance approval timelines, when Dead Sea extraction operations face geopolitical disruption, or when peracetic acid substitution rates exceed modeled trajectories in food processing segments. Forecasts reflect documented assumptions about regulatory enforcement continuity and raw material supply stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Cosmetic Grade Preservative Market
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
Deltamethrin Market
Disinfectants and Preservatives
Global Fusidic Acid Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
Global Mold Inhibitors Market
Disinfectants and Preservatives
Nisin Market
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
Sodium Bisulphite Market
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Sterilants Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
Sterilization Markers Market
Disinfectants and Preservatives
Continuously Sterilized Product Market