
 Shaving Care Market | 2026-2036
Shaving Care Market Size, Share, and Industry Trends Forecast 2026-2036
Shaving Care Market Analytics
E-commerce platforms are rewriting distribution economics for shaving care, collapsing traditional wholesale markups and enabling direct-to-consumer subscription models. The Procter & Gamble Company leverages its Gillette brand infrastructure to sustain dominant shelf presence across mass retail channels. Edgewell Personal Care anchors its competitiveness through specialized manufacturing scale in blade systems and disposable razors. Koninklijke Philips N.V. differentiates via electric grooming technology leadership, competing against cartridge-based incumbents with rechargeable precision instruments.
Shaving care encompasses the full range of products and devices designed for hair removal from facial and body surfaces, including multi-blade cartridge systems with titanium-coated edges, lubricating strips containing aloe and vitamin E, and thermally responsive gels that soften keratin structures prior to blade contact. The primary commercial purpose centers on reducing skin irritation, minimizing nicks, and extending the comfortable interval between shaving sessions through lubrication and post-treatment skin conditioning. Razors and replacement cartridges command the largest revenue pool within product type segmentation, while aftershaves and balms capture disproportionate margin contribution through premium fragrance positioning and dermatological certification. The men's end-user segment remains structurally mature in developed economies, whereas women's specialized shaving products represent the fastest-growing demand vector as gender-specific formulation marketing intensifies.
FDA oversight of cosmetic safety claims in the United States, REACH chemical registration requirements administered by ECHA in Europe, and BIS packaging standards in India collectively shape product labeling, ingredient transparency obligations, and market access conditions for shaving care manufacturers. These regulatory frameworks elevate compliance costs for new entrants while rewarding incumbents with established toxicology dossiers and reformulation capabilities. Stakeholders must monitor evolving microplastic restrictions in rinse-off cosmetics, as pending filament bans in synthetic shaving brushes and exfoliating scrubs threaten supply chain continuity for several established product lines.
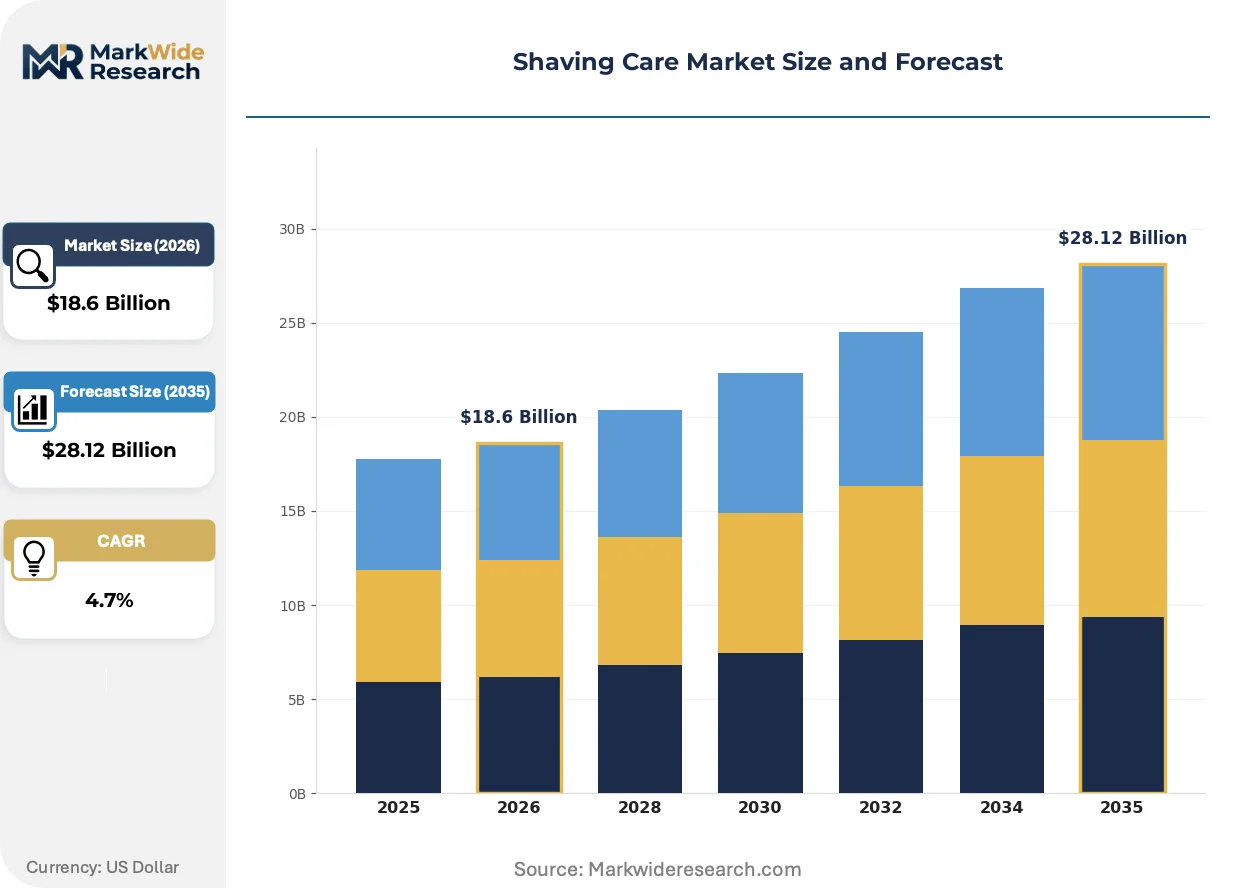
Market Dynamics
The EU Green Deal's chemical safety mandates are forcing systemic reformulation across European shaving care portfolios, while e-commerce subscription models compress traditional wholesale economics and redistribute margin capture toward direct-to-consumer platforms.
Growth Catalysts
- REACH Registration Requirements:ECHA's chemical dossier standards in Europe reward incumbents with established toxicology data, creating compliance moats that deter new entrants and consolidate shelf presence among legacy manufacturers.
- Barbershop Culture Concentration:Germany's premium grooming salon density sustains specialized per-capita consumption of professional-grade shaving preparations, anchoring above-average demand for pre-shave oils and hot-towel formulations.
- Titanium-Coated Blade Metallurgy:Advanced edge-coating processes extend cartridge longevity and reduce skin irritation, driving replacement cycle compression and premium pricing acceptance among male facial-grooming users.
Market Restraints
- Stainless Steel Input Volatility:Razor blade substrate costs fluctuate with global steel pricing, squeezing margin structures for cartridge manufacturers who lack captive metallurgy operations or long-term supply agreements.
- Synthetic Filament Supply Disruption:Pending microplastic restrictions on rinse-off cosmetics threaten continuity for shaving brushes and exfoliating scrubs, forcing rapid material transitions ahead of confirmed ban timelines.
- Electric Grooming Substitution:Philips and other rechargeable precision instruments capture users seeking reduced irritation and lower lifetime cost, pressuring cartridge-based volume in developed European markets.
Strategic Opportunities
- Women's Specialized Formulations:Gender-specific marketing intensifies demand for body-area shaving products with distinct fragrance profiles and skin-conditioning chemistries, opening white space beyond mature male facial segments.
- Dermatological Certification Positioning:Efficacy claims validated by skin-health authorities command premium shelf placement and reimbursement-adjacent positioning in pharmacy channels across France and Germany.
- Direct-to-Consumer Subscription Infrastructure:Automated replenishment platforms collapse traditional retail markups and capture recurring revenue streams, with logistics networks now enabling personalized blade-schedule algorithms.
Industry Challenges
- Reformulation Timeline Compression:EU Green Deal ingredient blacklists require rapid toxicology reassessment and supply chain requalification, straining R&D bandwidth while maintaining existing product registrations.
- Legacy System Integration Friction:Traditional manufacturers embedding e-commerce capabilities encounter data-architecture mismatches between ERP systems and direct-to-consumer analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shaving Care Market |
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $28.12 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Razors, Shaving Gels, Aftershaves, Creams End User: Men, Women, Barbers, Grooming Salons Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies Packaging Type: Tubes, Bottles, Jars, Dispensers |
| Companies Covered | The Procter & Gamble Company, Edgewell Personal Care, Koninklijke Philips N.V., Panasonic Holdings Corporation, Beiersdorf AG, BIC Group, Church & Dwight Co., Inc., Unilever PLC, Wahl Clipper Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shaving Care Market Evolving Landscape
Thermally responsive gel chemistry and precision electric instrumentation are bifurcating the shaving care landscape, while regulatory chemical mandates and channel disintermediation simultaneously reshape formulation priorities and margin distribution.
Heated shaving gel systems incorporate phase-change materials that activate upon skin contact, softening keratin structures prior to blade engagement. Professional barbershop chains in Germany and the United Kingdom are standardizing these preparations to reduce client irritation incidents. Single-use thermal sachets are rendering obsolete bulk-pump dispensers in premium service environments where hygiene theater commands pricing power.
ECHA's pending restrictions on per- and polyfluoroalkyl substances (PFAS) in cosmetic applications are eliminating water-repellency additives from lubricating strips and post-shave balms. Manufacturers with early PFAS-free formulation pipelines secure uninterrupted market access while competitors face stock-recall exposure. The regulatory pressure concentrates most acutely on mass-market cartridge lines dependent on legacy chemistries for glide performance.
Subscription-based blade replenishment has displaced pharmacy and supermarket impulse purchases among urban male demographics. Automated scheduling algorithms tied to usage-pattern data now determine delivery cadence, compressing the traditional retail intermediary layer. This behavioral shift manifests most visibly in Scandinavian markets where digital payment penetration and logistics density support frictionless recurring commerce.
Shaving Care Market Segmentation
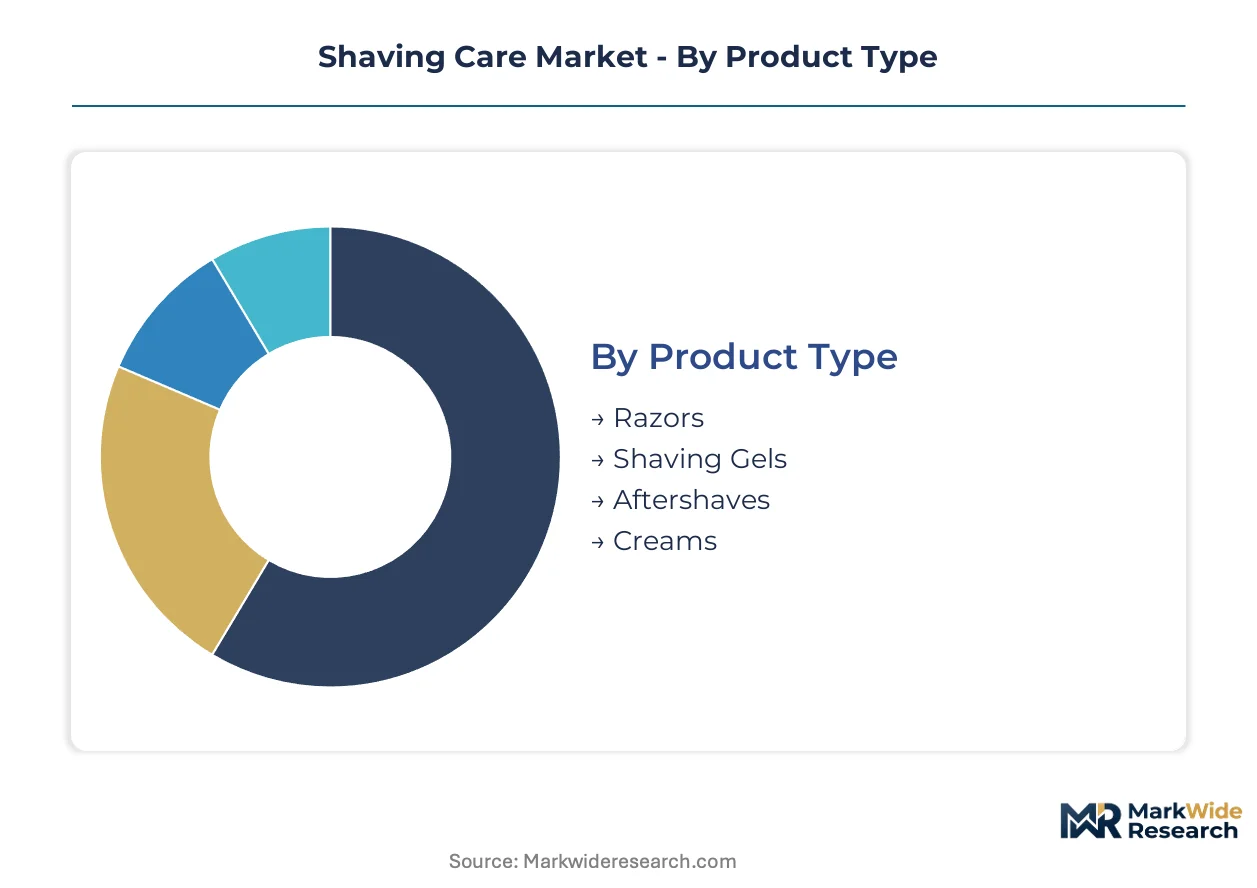
Shaving care segmentation reveals divergent margin profiles and replenishment cadences across product categories. After-sales intensity varies dramatically between disposable consumables and durable hardware, reshaping customer lifetime value calculations for manufacturers.
Product Type:
After-sales service intensity peaks with cartridge systems requiring continuous replenishment, while gel and cream formats demand less ongoing manufacturer engagement beyond initial purchase.
- Razors:Multi-blade cartridge systems with titanium-coated edges and lubricating strips dominate hardware revenue. Germany's barbershop culture sustains professional-grade handle and cartridge demand through institutional procurement contracts.
- Shaving Gels:Thermally responsive formulations containing phase-change materials soften keratin prior to blade contact. Heated gel sachets are displacing bulk dispensers in premium UK and German service environments where hygiene protocols command pricing premiums.
- Aftershaves:Fragrance-positioned skin conditioning products with dermatological certification capture disproportionate margin in French and German pharmacy channels.
- Creams:Traditional lather preparations maintain volume in mass retail through price-accessible positioning and established brand recognition.
By volume, Razors lead. By growth pace, Shaving Gels are climbing the fastest.
End User:
Customer acquisition costs and retention mechanics diverge sharply between individual consumers and institutional service providers.
- Men:Structurally mature facial-grooming segment with established cartridge replacement habits. Subscription algorithms now automate replenishment among urban demographics in Scandinavian markets.
- Women:Specialized body-area formulations with distinct fragrance chemistries are expanding most quickly as gender-specific marketing intensifies beyond legacy unisex positioning.
- Barbers:Professional-grade hardware and preparation procurement follows equipment lifecycle patterns and service menu standardization.
- Grooming Salons:Institutional buyers prioritize bulk formats and dermatological certifications for liability management in client-facing treatments.
By installed base, Men dominate. By expansion trajectory, Women are gaining share fastest.
Distribution Channel:
Channel economics determine margin capture and data access, with direct platforms collapsing traditional wholesale layers.
- Online Retail:Subscription infrastructure with automated replenishment algorithms compresses retail markups. Logistics density in Nordic markets enables frictionless recurring commerce.
- Supermarkets:Impulse-driven mass-market volume with high SKU velocity and promotional pricing sensitivity.
- Specialty Stores:Curated premium positioning with trained staff consultation and gift-set merchandising.
- Pharmacies:Dermatological certification requirements and reimbursement-adjacent positioning in France and Germany elevate price acceptance.
By transaction volume, Supermarkets lead. By margin expansion, Online Retail shows the steepest trajectory.
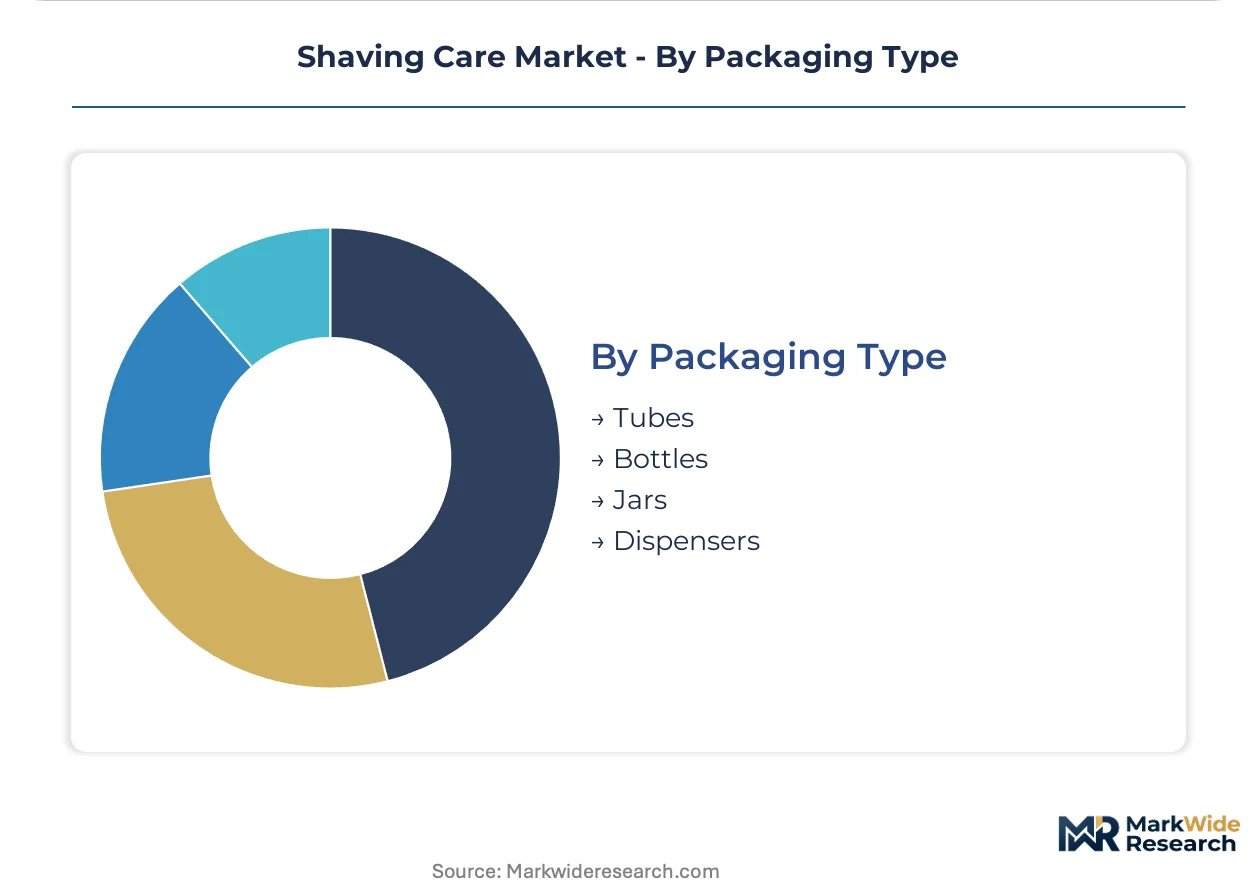
Packaging Type:
Packaging format selection intersects with regulatory compliance timelines and sustainability positioning.
- Tubes:Flexible barrier formats for gel and cream products with controlled dispensing and shelf stability.
- Bottles:Rigid containers for liquid aftershaves with fragrance preservation and premium aesthetic requirements.
- Jars:Wide-mouth formats for balm and conditioning products enabling finger-application in professional settings.
- Dispensers:Pump and aerosol systems facing reformulation pressure under ECHA microplastic and PFAS restriction timelines.
By unit shipments, Tubes lead. By regulatory exposure, Dispensers face the most compressed transition timeline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites German distribution dominance for European shaving care imports, while Rotterdam's chemical handling infrastructure anchors REACH-compliant formulation supply chains across the continent.
Germany
Premium barbershop density in Berlin and Munich sustains professional-grade cartridge and preparation demand through institutional procurement contracts. ECHA's REACH registration requirements reward incumbents with established toxicology dossiers, consolidating shelf presence among legacy manufacturers. The Rhine-Ruhr industrial corridor hosts specialized metallurgy operations supplying titanium-coated blade substrates to cartridge producers.
United States
FDA oversight of cosmetic safety claims elevates compliance costs for new entrants while rewarding established players with reformulation capabilities and toxicology databases. Direct-to-consumer subscription platforms collapse traditional wholesale markups, redistributing margin capture toward automated replenishment algorithms. The Chicago-Milwaukee corridor maintains concentrated manufacturing scale for multi-blade cartridge systems serving mass retail channels.
United Kingdom
Heated gel sachets displace bulk-pump dispensers in London and Manchester premium service environments where hygiene protocols command pricing premiums. ECHA's pending PFAS restrictions eliminate water-repellency additives from lubricating strips, forcing rapid material transitions ahead of confirmed ban timelines. The Southeast England logistics cluster enables frictionless e-commerce fulfillment for subscription-based blade replenishment.
India
BIS packaging standards and expanding male grooming consciousness drive formalization of previously unorganized shaving preparation markets. The country's national pharmaceutical regulator maintains vigilance over dermatological certification claims in pharmacy-positioned aftershave and balm segments. Maharashtra's Mumbai-Pune industrial belt concentrates contract manufacturing operations for both domestic brands and multinational licensees.
Japan
Electric grooming technology adoption accelerates as rechargeable precision instruments capture users seeking reduced irritation and lower lifetime cost versus cartridge alternatives. METI's product safety standards shape labeling requirements and ingredient transparency obligations for imported formulations. The Kanto region surrounding Tokyo anchors premium retail positioning for fragrance-positioned skin conditioning products with dermatological certification.
Shaving Care Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability clusters: metallurgy-integrated cartridge manufacturers, electric grooming technology specialists, and formulation-driven personal care conglomerates. Strategic archetypes include scale-driven mass-market incumbents, precision-engineering electric device fabricators, and dermatology-certified premium positioning players. Dominant competitive moves encompass direct-to-consumer channel disintermediation and rapid reformulation pipelines responding to ECHA chemical restriction timelines.
Among diversified personal care conglomerates, The Procter & Gamble Company and Unilever PLC exemplify scale-driven archetypes with established toxicology dossiers and mass retail shelf presence. Edgewell Personal Care occupies a position within the specialized manufacturing tier, while Koninklijke Philips N.V. anchors the electric grooming technology vector competing against cartridge-based incumbents. Panasonic Holdings Corporation and Wahl Clipper Corporation represent additional precision-instrument specialists, with Beiersdorf AG and Church & Dwight Co., Inc. exemplifying dermatology-adjacent formulation positioning. BIC Group occupies the disposable razor value-tier segment.
| Leading Market Players |
|---|
| The Procter & Gamble Company |
| Edgewell Personal Care |
| Koninklijke Philips N.V. |
| Panasonic Holdings Corporation |
| Beiersdorf AG |
| BIC Group |
| Church & Dwight Co., Inc. |
| Unilever PLC |
| Wahl Clipper Corporation |
| Others |
Value Network & Pricing Analysis
The Port of Hamburg's container throughput cost dynamics compress margin structures for titanium-coated blade substrate imports while amplifying price differentiation between mass-market cartridge systems and professional-grade barbershop equipment. Supply concentration in Germany's Rhine-Ruhr metallurgy corridor feeds downstream pricing power that subscription-based direct-to-consumer platforms partially erode through collapsed wholesale layers.
Pricing Analysis
Volume-discount tiering separates dermatology-certified pharmacy-positioned aftershaves from mass-retail disposable razors and economy-tier bulk creams. Price differentiation rests on certification grade and after-sales service bundling, with cartridge replacement subscriptions commanding premium positioning over transactional hardware purchases. Cost compression in stainless steel-dependent cartridge manufacturing intensifies pricing pressure from electric grooming substitution. Barbershop procurement contracts demonstrate lowest price sensitivity while supermarket impulse buyers exhibit highest elasticity.
Supply Chain Analysis
Stainless steel feedstock draws from Germany's specialized metallurgy operations, China's commodity steel production, and Japan's precision substrate fabrication. Titanium coating chemistries and thermally responsive gel phase-change materials constitute critical component dependencies alongside lubricating strip polymers. Single-source vulnerability concentrates in REACH-registered toxicology dossiers held by legacy European manufacturers. Distribution runs through e-commerce subscription platforms, mass retail chains, and pharmacy networks with divergent margin capture profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
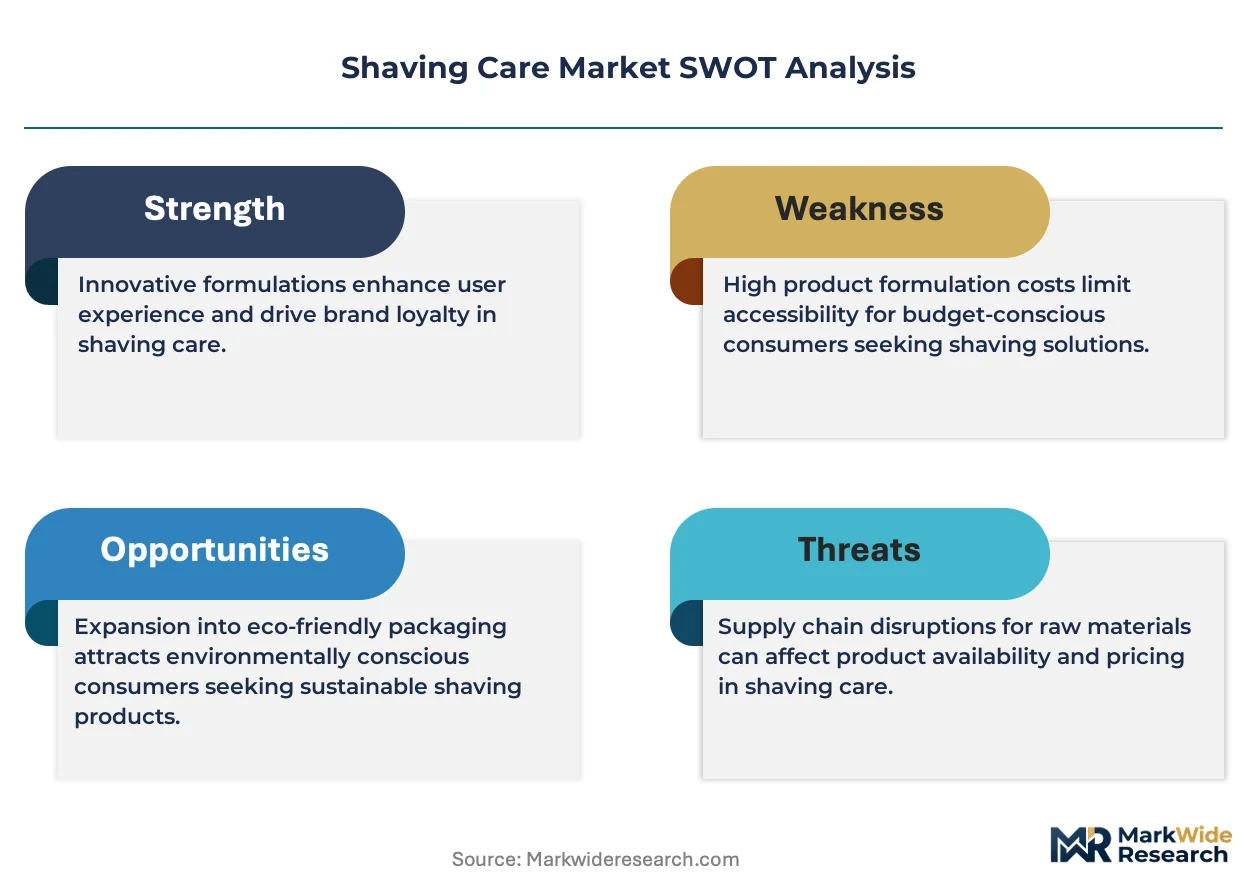
Shaving care functions as a service-attach opportunity where automated blade replenishment and professional preparation subscriptions expand faster than durable hardware sales, rewarding manufacturers who embed recurring revenue architecture ahead of pure product transactions.
For Market Incumbents: Pre-empt electric grooming substitution by accelerating dermatological certification pipelines for pharmacy-channel aftershaves and securing titanium-coating capacity in Germany's Rhine-Ruhr corridor. Channel control through direct-to-consumer subscription infrastructure defends margin position against disintermediation. R&D prioritization should target PFAS-free lubricating strip reformulation ahead of ECHA restriction timelines. For New Entrants and Emerging Players: Women's specialized body-area formulations with distinct fragrance chemistries represent the most penetrable entry point, exploiting white space beyond mature male facial segments where gender-specific marketing intensifies. German barbershop institutional procurement contracts offer a secondary avenue through professional-grade hardware and heated gel sachet supply. Go-to-market execution should leverage Nordic logistics density for frictionless subscription platform deployment. For Investors and Strategic Acquirers: Formulation-driven personal care specialists with established REACH toxicology dossiers and rapid reformulation pipelines constitute the priority acquisition archetype for long-term viability across the next decade. Dermatological certification capabilities and direct-to-consumer subscription infrastructure signal durable competitive positioning. Monitor ECHA chemical restriction announcements as the critical inflection indicator for portfolio exposure reassessment.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Reformulation Pipeline | ECHA restriction compliance secures uninterrupted market access for lubricating strip and balm portfolios. |
| Direct-to-Consumer Subscription Launch | Automated replenishment algorithms collapse retail markups and capture recurring revenue in Scandinavian markets. |
| Dermatological Certification Investment | Pharmacy-channel positioning in France and Germany commands premium shelf placement and price acceptance. |
| Titanium-Coating Capacity Expansion | Rhine-Ruhr metallurgy integration reduces stainless steel input volatility exposure for cartridge manufacturers. |
| Women's Formulation Line Extension | Gender-specific body-area products with distinct fragrance chemistries exploit fastest-growing demand vector. |
Research Methodology
A spread of perspectives from brand managers at personal care conglomerates, category buyers at mass retail chains, procurement leads at German barbershop chains, and supply planners at metallurgy operations converged on the working assumptions shaping this analysis. Primary interview insights combined with secondary validation from customs records, Nielsen retail audit data, ECHA chemical registration databases, and SEC 10-K filings. Bottom-up product-level volume aggregation and top-down macroeconomic alignment provided triangulation discipline.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeling spanning product type, end user, distribution channel, and packaging format dimensions. CAGRs derived from trend extrapolation adjusted for regulatory intervention timelines and channel shift velocity. Industry-specific forecast inputs incorporated ECHA chemical restriction phase-in schedules and e-commerce penetration curves by Nordic logistics density.
Practitioners should monitor ECHA blacklist announcements, stainless steel commodity price volatility, and electric grooming technology adoption rates for early signals necessitating forecast revision. Cross-checking against customs import data for titanium-coated blade substrates through the Port of Hamburg is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Underarm Sweat Pads Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Wet Shave Market
Personal Grooming Products
North America Mosquito Repellent Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
India Sexual Wellness Market
Personal Grooming Products
Global Massage Guns Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Smart Water Bottle Market
Personal Grooming Products
Shaving Pen Market
Personal Grooming Products
Global Beard Balm Market
Personal Grooming Products
Nose & Ear Hair Trimmers Market
Personal Grooming Products
Infant Mosquito Repellent Market
Personal Grooming Products
Electric Toothbrush Market